• Skip to main content
  • Skip to primary sidebar

Nexa Collections

  • Home
  • Serving
    • Medical
    • Dental
    • Small Business
    • Large Business
    • Commercial Collections
    • Government
    • Utilities
    • Fitness Clubs
    • Schools
    • Senior Care Facility
  • Contact Us
    • About us
    • Cost

Debt Recovery

Dental Collection Agency | HIPAA-Compliant Recovery for Dentists & DSOs

You spent years building their trust; don’t let a $200 co-pay burn that bridge. We aren’t just collectors, we are the ‘Relationship Guard‘ that secures your revenue while keeping the door open for their next cleaning. Our high Google ratings are a testament to our patient-friendly approach. We offer a reputation-safe, HIPAA-compliant recovery process designed for modern dental practices.
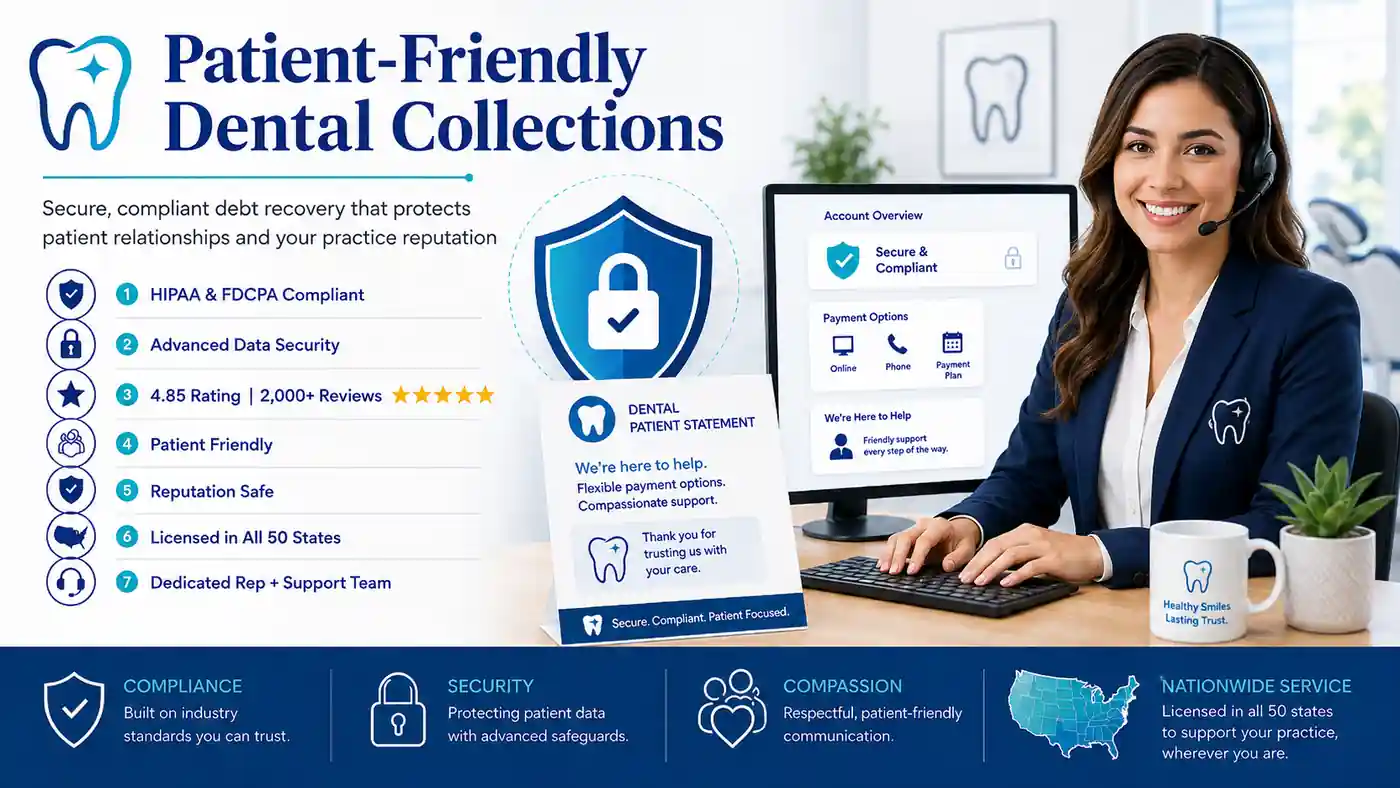
A Modern Approach to Dental Patient Collections

Quick answer: Dental debt collection recovers past-due copays, deductibles, and defaulted treatment-plan balances through HIPAA-compliant, patient-friendly outreach that coordinates with your practice management software. The credit bureaus voluntarily exclude paid debt and balances under $500 as their own policy, not a binding federal rule, so effective recovery leans on diplomatic communication and flexible payment plans rather than the threat of credit damage.


The New Rules of Dental Billing: Compliance First

Before any account can be collected, your practice must be compliant. Recent laws have changed how patient billing works, and using a partner who understands this landscape is critical.

  • HIPAA & Business Associate Agreements (BAA): As your partner, we are a “Business Associate” under HIPAA. We can sign a BAA with your practice, binding us to protect your patients’ Protected Health Information (PHI). We only use the “minimum necessary” information (like name, balance, and dates of service) to perform our job.
  • The “No Surprises Act” (NSA): This federal law is crucial. It requires you to provide “Good Faith Estimates” (GFEs) to your uninsured or self-pay patients before a service. An attempt to collect a bill that is significantly higher than your GFE can lead to disputes and legal challenges. We help you navigate collections for accounts that are fully compliant.

The ‘Velvet Hammer’ Approach
We treat your patients like patients, not criminals. Our fixed fee Step 1 service looks exactly like a gentle reminder from your front desk, preserving the relationship so they return for their next cleaning.

Ready to start collections? Contact Us

Services & Pricing

Your hygienists went to school to save smiles, not to perform financial interrogations. When you turn your front desk into a collection department, you don’t just lose revenue, you lose morale. Let them keep the drills; we’ll handle the bills. See our full pricing breakdown for how these fees compare across account types.

Collection agency cost

  1. Step 1 — First-Party Courtesy Reminders (Fixed-Fee)
    We act as your extension with five soft reminders for fresher balances (0–60 days), sent as if these reminders are coming from you.

    • Typical Fee: $15 per account.
  2. Step 2 — Third-Party Written Demands (Fixed-Fee)
    Five professional letters on our letterhead that prompt action while preserving goodwill.

    • Typical Fee: $15 per account.
  3. Step 3 — Full Third-Party Collections (Contingency)
    Persistent, polite phone and digital outreach from our HIPAA-trained specialists. We negotiate payment plans and settlements to get you paid.

    • Typical Fee: 40% of amounts recovered. No Recovery, No Fee.
  4. Step 4 — Legal Collections (Contingency, Client-Approved)
    For large, unresponsive accounts, we escalate to an attorney after an in-depth review, and only with your explicit approval.

    • Typical Fee: Up to 50% of amounts recovered. No Recovery, No Fee.

Recent Successes in Dental Debt Recovery

Case 1: Multi-Location DSO (12 Practices)

  • Initial Challenge: $142,000 in aged (>120 days) patient balances and unpaid PPO copays stuck across multiple Dentrix ledgers. High administrative burden and fear of negative Google reviews across locations.

  • Nexa Strategy: Automated ledger batching, guarantor account consolidation, and soft-touch digital outreach with flexible, interest-free payment portal options.

  • Result: 84% total recovery ($119,280) within 60 days with zero negative reviews or patient complaints across all 12 practice locations.

Case 2: Cosmetic & Implant Dental Practice (Solo Office)

  • Initial Challenge: $38,500 in defaulted high-ticket dental implant treatment plans where patients abandoned care mid-treatment or defaulted on internal financing.

  • Nexa Strategy: Audit of completed clinical steps against unearned fee adjustments, followed by diplomatic financial counseling and budget-matched installment structuring.

  • Result: $31,200 recovered (81% recovery rate) while preserving ongoing patient relationships for routine hygiene and preventative care.

⚠️ Dental Billing Compliance Watch

  • Good Faith Estimates: The “No Surprises Act” requires strict estimates for self-pay patients. We ensure your collections match these rules to avoid fines.
  • Credit Reporting Is a Patchwork, Not a Rule: The credit bureaus voluntarily stopped reporting paid debt and balances under $500 as their own 2022–2023 policy. A federal rule that would have gone further and banned medical/dental debt reporting nationally was vacated by a court in July 2025, and that ruling also cast legal doubt on the roughly 15 state laws restricting this reporting too. Old-school credit “threats” were never reliable and are even less so now. You need diplomatic, persistent outreach strategies instead.

Key Benefits of Our Service:

  • For Steps 1-2, payments go directly to you.
  • We can collect in all 50 states and Puerto Rico.
  • Free Services: We provide free bankruptcy screening, litigious debtor checks, and free address verification on all accounts.
  • Practice Software Integration: We support streamlined ledger exports compatible with major dental PMS platforms, including Dentrix, Eaglesoft, Open Dental, Curve Dental, and PracticeWorks, so your front desk isn’t stuck manually re-entering account data. At most, you will download data in an excel sheet from your PMS platform and directly upload in our portal.

The Dental Practice Ledger Dispute Matrix

Not every unpaid balance has the same root cause, and the right recovery approach depends on knowing which one you’re dealing with.

Dental Account Type Root Cause of Delay Recovery Strategy
PPO Patient Copays Patient assumed insurance covered 100% of treatment EOB verification, patient financial education, soft digital payment plans
Family Ledger Accounts Combined household balances or divorce/custody disputes over who’s responsible Guarantor-level consolidation, diplomatic outreach, clear itemized family statements
Mid-Treatment Defaults Patient discontinues multi-stage care (implants, ortho) partway through Audit unearned-fee adjustments, bill only completed procedure steps, offer flexible financing
In-House Membership Plans Failed card on file for a recurring membership payment Soft automated retries, courteous update notices, balance reconciliation

Best Practices for Your In-Office Team

The best collection is one that never has to be sent. We find that practices with the highest success rates follow these steps:

  1. Have a Clear Financial Policy: Patients should sign a clear, simple policy stating they are responsible for all charges not covered by insurance.
  2. Verify Insurance Before Treatment: Always check eligibility and benefits before the appointment to give the most accurate co-pay estimate.
  3. Collect Co-pays at Time of Service: This is the easiest way to reduce post-treatment billing.
  4. Send Statements Immediately: Send the final patient-responsible bill as soon as the EOB (Explanation of Benefits) is received.

When Is It Time to Send an Account to Us?

It’s time to let your staff focus on patient care when you see these red flags:

  • The patient has ignored two or more statements.
  • The patient has made a broken promise to pay.
  • The patient is no longer communicating (“ghosting”).
  • Your staff is spending more time chasing payments than serving patients.
  • An invoice is 90-120 days past due. The older an account gets, the harder it is to collect.

Why Dental Practices Switch to Us

  • We Protect Your Reputation: We will not harass your patients. Our goal is to find a solution, not create a conflict. We save you from negative Google and Yelp reviews.
  • We Are HIPAA Experts: We are not just “HIPAA compliant”; we are experts who understand the law and can sign a BAA with your practice, the same expertise we apply on our medical debt recovery side of the business.
  • Better ROI: Our blend of low-cost fixed-fee options (Steps 1-2) and a professional contingency service (Step 3) means you recover more, more efficiently.
  • Get Your Front Desk Back to Scheduling, Not Chasing: Your front desk team are healthcare professionals, not collectors. Let them focus on patient care and growing your practice.

Frequently Asked Questions for Dental Practices

What if the patient is disputing an insurance claim?

We are not an insurance billing company. We only pursue the patient-responsible balance after insurance has paid or denied the claim. We will direct patients with insurance questions back to your office.

Will you sue my patients?

We are not a law firm and will never sue a patient without your explicit, written permission. Our process (Steps 1-3) is designed to resolve accounts before legal action is ever considered.

What about credit reporting?

It’s more limited and less predictable than most practices assume. The credit bureaus voluntarily stopped reporting paid debt and balances under $500 as their own policy, not a binding federal law, and a broader federal rule that would have banned medical/dental debt reporting entirely was struck down by a court in 2025. We believe protecting your patient relationship is far more valuable than chasing credit-report leverage anyway, and we focus on professional, diplomatic communication to get results.

How do we get started?

It’s simple. You Contact us, we sign a Business Associate Agreement (BAA), and you can securely place accounts through our online portal.

How do you handle a family account when the guarantor and the patient who received treatment aren’t the same person?

Dependent balances get consolidated under the primary guarantor, the person who signed the financial responsibility agreement, rather than pursued piecemeal across multiple family members. If a divorce or custody dispute is part of the picture, we work from what your intake paperwork actually says about who’s financially responsible, not a private agreement between the parents that your practice was never a party to.

Can we refuse to schedule a patient’s future appointments if they have an unpaid balance? Is that patient abandonment?

Declining new, elective appointments for a patient with a significant unpaid balance is generally permissible, the same way any business can decline future service to a customer who hasn’t paid. Where it gets legally and ethically risky is discontinuing care mid-treatment, an active infection, a procedure left incomplete, since that can cross into patient abandonment regardless of the balance owed. The distinction is whether the patient relationship is being ended cleanly between treatment plans, or cut off in the middle of one.

A patient stopped a multi-stage treatment plan (implants, ortho) partway through. Can we bill for the full plan, or only the work actually completed?

Only the completed and documented clinical steps, not the full plan as originally quoted. Billing for unearned future stages of a treatment plan the patient never received is difficult to defend if challenged, and doing so is one of the faster ways to turn a routine balance dispute into a state dental board complaint. We audit the account against what was clinically completed before pursuing it, and adjust the balance to match.

Ready to Improve Your Practice’s Cash Flow?

Stop letting aged receivables hurt your bottom line. Contact us for a no-obligation, fully compliant quote.

Need a Dental Collection Agency? Contact Us

Serving hundreds of dentists nationwide – HIPAA compliant.

Best recovery rates in the industry


Information about Dental Malpractice Insurance: Types, Cost and Lawsuit Reasons
Additional Information:  Suggested Dental Collection Strategy


Filed Under: Debt Recovery

Medical Debt Collection Agency: Patient-Friendly, HIPAA-Compliant Recovery

A patient who ignored three billing statements often responds to the fourth one, if it comes from someone whose entire job is getting it resolved without burning the relationship. That’s the gap Nexa fills: revenue recovered, HIPAA compliance maintained, and the patient still comfortable walking back through your door next year. With over 50% of our clients coming from the medical and dental fields, we are true specialists in the healthcare industry.

Quick answer: Nexa Collections recovers unpaid patient balances through HIPAA-compliant, patient-friendly outreach, starting at a $15 fixed fee per account, with 40% contingency for older debts. Recovery is built around 501(r) charity-care screening for hospitals and No Surprises Act compliance for emergency billing, not around threatening credit damage, since medical debt’s presence on credit reports is shifting and increasingly state-dependent.

Medical billing specialist consulting empathetically with a patient about flexible payment plan options.

Why Choose Nexa?

  • Transparent Pricing: Fixed fees starting at $15/account.
  • No Recovery, No Fee: 40% contingency for older debts.
  • Compliance First: 501(r) & No Surprises Act ready.

Respectful Treatment: It’s Our Policy, Not Just a Promise

Your patients deserve respect, even in collections. We understand that avoiding harsh tactics is your top priority. That’s why we record and randomly review our calls, to ensure our collectors always maintain our minimal patient stress policy and protect your practice’s reputation.


Services and Fee Structure

Let your team keep the stethoscopes; we’ll handle your AR spreadsheets.

Nexa Collections medical collection agency fee structure — $15 fixed fee per account for demand letters, 40% contingency for phone collections

Step Service Type What We Do Fee Structure
Step 1 First-Party Demands Five polite payment reminders sent to the debtor in your name. Fixed-Fee: $15 per account
Step 2 Third-Party Written Demands Five collection letters sent by our agency. Fixed-Fee: $15 per account
Step 3 Third-Party Collections Persistent, professional phone outreach and resolution. Contingency: 40% of amount collected
Step 4 Legal Collections (client-approved) Attorney-led action where appropriate. Contingency: 50% of amount collected

See the full pricing breakdown for how these tiers compare across account types.


Healthcare Providers We Serve

We recover patient balances across every healthcare specialty and setting, with compliant workflows tailored to each provider type:

  • Hospitals & Health Systems: 501(r)-compliant intake, FAP screening, ECA documentation, and high-volume account processing.
  • Physician Groups & Multi-Specialty Clinics: Clean claim verification, EOB reconciliation, and payment plan enrollment before escalation.
  • Urgent Care Centers: High-volume, lower-balance accounts processed efficiently with fixed-fee letter campaigns.
  • Dental Practices: HIPAA-compliant dental debt recovery with patient-first communication that preserves recall rates and referral relationships.
  • Behavioral Health & Addiction Treatment: Sensitivity-trained collectors who understand the unique stigma, privacy concerns, and the stricter federal consent rules that govern this billing category specifically (see the FAQ below).
  • Ambulatory Surgery Centers (ASCs): Higher-balance accounts with complex insurance coordination, resolved via structured payment plans and portal enrollment.
  • Home Health & Hospice: Balance billing recovery from families and patients in sensitive circumstances, handled with appropriate care and compliance.
  • Physical Therapy & Chiropractic: High-frequency, moderate-balance accounts suited to our fixed-fee first-party demand service.
  • Federally Qualified Health Centers (FQHCs): Sliding-scale and self-pay recovery with financial assistance awareness built into every outreach.

Medical office staff are frustrated with being forced into part-time debt collectors, as it distracts them from their primary responsibilities.

Quick start: Send 10–20 test accounts or a CSV export. We’ll review in 1 business day and recommend the lowest-friction path.

Need a Medical Collection Agency? Contact Us

Serving Thousands of Medical Professionals Nationwide

Easy to use • Fully Compliant with HIPAA, Federal and State Laws • USA Citizens-Only Team • 24×7 Secure Portal • High Recovery Rates • Expert Medical Collectors • Free Credit Bureau reporting • Low fee 


Recent Results

• Multi-Specialty Clinic – $380–$1,400 balances – 72–118 days
Up-front estimate + two-way texting + 4-month plans → 82% resolved without ECAs in 30 days.

• Nonprofit Hospital Outpatient – $650 average – 95 days
FAP screening + plain-language bills + text-to-pay → 68% pay/plan within 21 days; remainder documented for charity review.

• Ambulatory Surgery Center – $1,200 average – 132 days
Portal enrollment + hardship tiers + autopay → 74% enrolled in plans, with <3% cancellations over 90 days.


Why Medical Debt Collection Requires Dual Compliance: FDCPA + HIPAA

Most general collection agencies are only trained on the Fair Debt Collection Practices Act (FDCPA), the federal law governing how debts can be collected from consumers. Medical debt collection adds a second, equally strict layer: HIPAA (the Health Insurance Portability and Accountability Act). See our general overview of collection laws for how these federal and state rules interact more broadly.

Requirement FDCPA (all collection agencies) HIPAA (medical only)
What it governs How, when, and how often collectors can contact patients How patient health information (PHI) is accessed, stored, and shared
Key obligation No harassment, false statements, or unfair practices Minimum necessary PHI only; signed BAA required with all vendors
Violation risk Lawsuit by patient; FTC enforcement; $1,000/violation OCR investigation; $100–$50,000/violation; potential criminal charges
Who is liable The collection agency The healthcare provider AND the agency (shared liability)

The key risk for providers: If your collection agency mishandles PHI, even accidentally, your practice shares liability under HIPAA. A signed Business Associate Agreement (BAA) is not enough on its own; the agency must also have documented HIPAA training, secure data transfer protocols, and audit trails. Nexa Collections is fully SOC 2 Type II certified and HIPAA-compliant, with BAAs in place before any account is processed.


What Changed Recently (Why This Matters to Your Revenue)

  • Credit reporting is now a patchwork, not a lever. The major credit bureaus voluntarily stopped reporting paid medical debt and balances under $500 (with roughly a one-year grace period) as their own 2022–2023 policy. Separately, a federal rule that would have banned medical debt reporting nationwide was vacated by a court in July 2025, and that same ruling cast real legal doubt on the roughly 15 state laws that restrict it too. The practical upshot: credit-report pressure is no longer a reliable lever anywhere, and it’s a shifting, state-by-state question where it applies at all. That’s exactly why our outreach leans on communication and payment structure, not the threat of a credit ding.
  • No Surprises Act: Out-of-network emergency and post-stabilization charges have strong federal protections; our outreach aligns with those rules.
  • Hospitals (501(r)): Nonprofit hospitals must screen for financial assistance before any extraordinary collection actions (ECAs). We document those “reasonable efforts” so you stay audit-ready.
  • Policy watch: Regulations continue to evolve, especially around credit reporting. We keep scripts, notices, and workflows current so your team stays compliant.

HIPAA, Privacy & Dignity

  • We share only the minimum necessary PHI for payment/operations.
  • Business Associate Agreements with all third-party vendors we engage.
  • Scripts avoid clinical specifics; focus stays on balance, options, and empathy.

What We Need to Start

Invoices/statement • EOB (if available) • Patient contact info • Registration notes • Prior outreach logs • Financial-assistance status (if hospital)


Medical Collections FAQs

Can unpaid medical bills still appear on credit reports?

It depends more on the state than on any single federal rule right now. The three major credit bureaus voluntarily stopped reporting paid medical debt and balances under $500, with a roughly one-year grace period, as their own 2022–2023 policy, not a legal mandate. Separately, a federal rule that would have banned medical debt reporting nationwide was vacated by a court in July 2025, and that ruling also found federal law may preempt the roughly 15 state laws that restrict this reporting too, so even those state protections are on uncertain footing. We build outreach around getting paid regardless of what credit reporting can or can’t do, since that landscape keeps shifting.

When should we place accounts?

After two unsuccessful internal attempts and by 60–120 days past due. Earlier placement means better patient recall and faster resolution.

What counts as an “extraordinary collection action” (ECA) for hospitals?

Examples include liens, wage garnishment, adverse credit reporting, and non-emergent care denial due to past bills, and they’re considered only after documented FAP screening.

Is sending a medical account to outside collections a HIPAA violation?

No, if you share the minimum necessary information for payment/operations and have a BAA in place.

Do you handle surprise-bill disputes?

Yes, we explain protections under the No Surprises Act and help resolve misunderstandings about out-of-network emergency and post-stabilization charges.

Behavioral health and addiction treatment are listed as specialties. Does substance use disorder billing require anything beyond standard HIPAA compliance?

Yes, and it’s a meaningfully higher bar. Substance use disorder treatment records are protected by 42 CFR Part 2, a federal regulation stricter than HIPAA that generally requires specific, SUD-tailored patient consent before that information, including billing details tied to the treatment, can be disclosed to a collection agency at all. A standard HIPAA Business Associate Agreement isn’t automatically sufficient on its own; the consent language needs to specifically cover SUD records. We handle these accounts under that stricter standard rather than treating them like an ordinary medical balance.


Ready to Lower Bad Debt (Without Damaging Trust)?

Start with 10–20 test accounts or a payer-mix subset. We’ll map the shortest path: TOS optimization, payment plans, charity screening, or—only when necessary—post-screen escalation.

Need a Collection Agency? Contact us

Filed Under: Debt Recovery

Debt Recovery for Community Banks & Credit Unions: Reputation Safe Approach

Your members see you at the grocery store. A national bank’s collections department doesn’t have that problem, and neither does its collections vendor. Yours does, and it means every past-due account your institution places carries a risk a large bank never has to think about: the member you’re collecting from is also your neighbor’s coworker, your board member’s cousin, or the person who’s going to mention how it went at the next community event.

This section isn’t for national or money-center banks, it’s built specifically for the community and regional institutions whose reputation is their loan book. Serving both B2B and B2C accounts.

collection agency for regional banks and credit unions


Quick answer: Community banks and credit unions need a recovery partner built around reputation protection first and recovery second, because the two are the same problem here. Nexa leads every account with a low-cost fixed-fee service, roughly $15 for a structured sequence of professional contacts, and moves only selected accounts to traditional contingency-based collection when the fixed-fee stage genuinely hasn’t worked. GLBA, FDCPA, and full federal and state compliance are built into every step, with a dedicated rep and simple batch Excel upload for placing accounts.

Nexa provides  reputation-safe, equipped with all 50-state collections license, offering free credit reporting, free litigious debtor check, free bankruptcy scrub, and zero onboarding fees. Secure – SOC 2 Type II & GLBA compliant. Over 2,000 online reviews rate us 4.85 out of 5. 

Need a Collection Agency? Contact us


Why Reputation Comes First Here, Not Second

A large bank’s brand survives a bad collections call because most of its customers will never hear about it directly. A community bank or credit union doesn’t have that insulation. Your members bank with you because you’re local, because a person answers the phone, because the relationship feels different than a national chain. A single harsh, poorly-handled collections call doesn’t just risk that one account, it risks the referral network your institution actually grows on.

That’s the entire reason our default posture is diplomatic, low-pressure, fixed-fee outreach, not because it’s the cheaper option, but because it’s the one least likely to turn a delinquent member into a lost member and a bad review. We will not sacrifice your institution’s reputation to collect a few extra dollars. That’s not a slogan here, it’s the actual sequencing decision behind every account we place.

“Nexa helped us recover over 38% of our delinquent loan balances without generating any member complaints to our board. Their fixed-fee approach protected our local reputation exactly as promised.”

— VP of Lending, Regional Credit Union ($450M Assets)


Why Our Rating Is High Because of How We Collect, Not Despite It

Our own review rating isn’t separate from this philosophy, it’s the direct result of it. A collections process built to avoid confrontation generates fewer complaints, fewer disputes, and fewer reasons for a frustrated debtor to leave a public review naming your institution. Our reputation and yours are tied together on every account we handle, which is exactly why the same restraint that protects your Google rating also protects ours. We have references from other financial institution clients, banks and credit unions we currently serve, available on request if you’d like to hear directly from them before making a decision.


The Fixed-Fee-First Model: Why Sequencing Is the Point

Nexa Collections fixed-fee and contingency pricing structure

Step 1 & 2: Fixed-Fee Recovery, roughly $15 per account. A structured sequence of professional, respectful contacts, letters and calls that read as a serious institutional follow-up, not a threat. Your institution keeps 100% of what’s recovered at this stage. This is where the large majority of accounts should resolve, and it’s the stage least likely to generate a complaint or a review.

Step 3: Contingency Collection, selectively, around 40%. Reserved specifically for accounts that genuinely didn’t respond to the fixed-fee stage, not run in parallel with it. Moving an account here is a deliberate decision based on how it actually behaved in Step 1 and 2, not a default escalation path applied to everything at once.

Step 4: Legal Referral, only with your approval. For the small subset of accounts where balance and circumstances justify it.

Most recovery vendors treat contingency as the default and fixed-fee as a discount tier. We treat it the other way around, because for a community institution, the reputational cost of an aggressive contingency call on a fresh account is almost always higher than the marginal dollars it might recover.


Timing Matters More Than Most Institutions Realize

An account placed around 90 days past due gives the best realistic combination of recovery odds and reputation-safe handling, the member still remembers the loan clearly, contact information is usually still current, and a professional fixed-fee letter genuinely has room to work before the relationship has soured. Recovery probability declines steadily the longer an account sits, waiting doesn’t protect the member relationship, it just narrows the window where a diplomatic approach can still succeed. Institutions that wait past 120–150 days are often left choosing between an aggressive contingency push or writing the balance off entirely, exactly the choice a 90-day placement was built to avoid.

Need a Collection Agency for Your Institution? Contact us

Banks using our 90-day recovery strategy see a 20% higher recovery rate than those who wait until 150 days


Compliance Built for What Your Examiners Actually Ask About

  • GLBA. The Gramm-Leach-Bliley Act’s Safeguards Rule applies to “financial institutions,” and the FTC’s own definition explicitly includes debt collectors. That means Nexa carries the same category of federal data-security obligation your institution does, not a separate, looser standard.
  • FDCPA and applicable state law, governing every consumer contact, disclosure, and timing rule.
  • SOC 2 Type II certified data security with documented, auditable controls.
  • 256-bit encryption and role-restricted access on every account.
  • Clean documentation for OCC, FDIC, and NCUA vendor-management reviews, so your third-party risk file has something real behind it, not a marketing claim.

Built to Be Easy on Your Team, Not Just Your Members

  • Dedicated account representative, backed by a specialized support team, not a rotating call queue or a ticket number.
  • Batch account upload via Excel. Place ten accounts or a thousand the same way, no manual re-entry, no proprietary file format to learn.
  • Responsive support that treats a placed account as an ongoing relationship, not a one-time transaction.
  • Simple, transparent reporting your team can actually use for board updates, without translating vendor jargon first.

Serving Regional Banks and CUs Nationwide

Need a Financial Collection Agency? Contact Us

High data security and privacy standards


Where This Applies Across Your Portfolio

  • Auto loan deficiencies after repossession, where fixed-fee outreach frequently resolves a balance the member simply hasn’t gotten around to addressing.
  • Charged-off credit card and personal loan balances, re-approached with a diplomatic tone rather than treated as a lost cause.
  • Overdrawn share and DDA accounts, exactly the small, high-volume, reputation-sensitive category where a $15 letter outperforms a percentage-based call every time.
  • Small business and SBA-adjacent loans, where guarantors increasingly warrant the same careful, documented handling as individual consumers.

See the full pricing breakdown for how the fixed-fee and contingency tiers compare across account types, and credit union-specific recovery details for member-account handling beyond what’s covered here.


Frequently Asked Questions

Is this collection service actually built for small and regional banks, or just relabeled for them?

It’s built specifically for community and regional institutions, not a large-bank service with different branding. The core philosophy, fixed-fee-first outreach with only selective escalation to contingency, exists because a local institution’s reputation is directly tied to individual member relationships in a way a national bank’s isn’t, and the collection strategy reflects that difference rather than treating every institution the same.

Why is a fixed-fee collection letter more reputation-safe than a traditional contingency call?

A fixed-fee letter is a written, professional notice that reads as a serious follow-up rather than a confrontation, and it removes the incentive structure that can push a contingency-paid caller toward pressure tactics on a percentage-based account. Most complaints and negative reviews trace back to an aggressive phone interaction, not a formal written demand, which is exactly why the fixed-fee stage is the default rather than a discount option.

When should our institution move an account from fixed-fee to contingency collection?

Only after the fixed-fee sequence has genuinely run its course without response, not as a parallel or automatic next step. An account that responds, disputes, or begins a payment plan during Step 1 or 2 generally stays there; only accounts that show no engagement at all are selectively moved to contingency, which keeps the more assertive collection approach reserved for accounts that have actually earned it.

How does GLBA compliance actually apply to a collection agency working with our institution?

The Gramm-Leach-Bliley Act’s Safeguards Rule applies to financial institutions, and the FTC’s definition of that term explicitly includes debt collectors, so a properly compliant agency carries the same category of federal data-security obligation your institution does. This means documented safeguards, access controls, and incident response procedures aren’t optional extras, they’re a direct legal requirement on the vendor, not just a vague alignment claim.

What’s the ideal time to place a past-due account with a collection agency?

Generally around 90 days past due. At that point the member typically still remembers the loan clearly and current contact information is more likely to be accurate, and a diplomatic fixed-fee letter has genuine room to resolve the account before the relationship has deteriorated. Recovery probability declines the longer an account ages, so waiting significantly past 90 days usually means choosing later between a more aggressive approach or writing the balance off.

Can we upload a batch of delinquent accounts instead of submitting them one at a time?

Yes. Accounts can be placed through a simple Excel batch upload, whether it’s ten accounts or several hundred, without manual re-entry or a proprietary file format to learn first. This is built specifically for institutions that need to move a portfolio segment at once rather than submitting individual accounts as they age.

Do we get a dedicated point of contact, or do we work with a general support queue?

A dedicated account representative, backed by a specialized support team, handles your institution’s accounts specifically, rather than routing through a rotating call center or ticket system. That consistency matters for a community institution that needs its recovery partner to actually understand its member base and tone, not just process files.

Can you provide references from other banks or credit unions you currently serve?

Yes. We work with other financial institution clients, including banks and credit unions, and can provide references on request before you commit to a placement. Speaking directly with an existing client is a reasonable step for any institution vetting a vendor that will be interacting with its members on its behalf.


blank


Talk to Us About Your Institution’s Portfolio

Filed Under: Debt Recovery

Auto Collection Agency: Expert Car Loan Debt Recovery

blank

Accelerating Cash Flow: The Dealership’s Guide to Professional Debt Recovery

Stop letting delinquent car notes stall your dealership’s growth. Whether you’re a high-volume franchise or a local independent lot, every day a payment is missed, your margins tighten. We turn “past due” into “paid” so you can keep your focus on the showroom floor, not the collections desk.

Nexa provides a reputation-safe approach, equipped with all 50-state collections license, offering free credit reporting, free litigious debtor check, free bankruptcy scrub, and zero onboarding fees. Secure – SOC 2 Type II & FDCPA compliant. Over 2,000 online reviews rate us 4.85 out of 5. 

Need a Collection Agency? Contact us

Two Lanes to Restore Your Cash Flow

  • Fixed-fee $15: Ideal for small balances like membership dues or service no-shows. You keep 100% of the money we recover.

  • Contingency (20%–40%): No recovery, no fee. Best for larger medical spa balances or older accounts that require intensive skip tracing.

blank


The Velvet Hammer: Why Diplomacy Outperforms Aggression

In the current automotive market, a car is often a person’s most vital asset. When a customer stops paying, it’s rarely because they don’t want the car—it’s because they’ve hit a hurdle. As a professional collection agency, we employ the Velvet Hammer approach. This means we are firm enough to secure your payment but empathetic enough to protect your 5-star online reputation.

We prioritize being the first bill the debtor wants to pay. By working with them rather than against them, we lower the “defensive wall” that typically leads to ignored calls. Before our collection agency even initiates contact, we perform a litigation scrub. This identifies high-risk individuals who may have a history of filing predatory lawsuits, protecting your dealership from unnecessary legal exposure. This proactive strategy is why our recovery rates are significantly higher than the industry average.


🚩 Red Flag Box: 3 Dealership Collection Pitfalls

  1. The “Friendship” Delay: Waiting to send an account to a collection agency because the customer “promised” to pay next week usually leads to a total loss once they disappear.

  2. Using Sales Staff for Collections: Your top sellers should be closing deals, not wasting hours on high-stress collection calls they aren’t trained for.

  3. Ignoring Bilingual Needs: In many local markets, failing to offer Spanish-speaking outreach means you are effectively ignoring 20% or more of your past-due accounts.


Recent Success Stories: Real-World Automotive Recovery

Scenario 1: The Vanishing CPO Buyer

A customer with a Certified Pre-Owned sedan stopped communicating after three months of consistent payments.

  • Step 1: We utilized current skip-tracing tools and USPS address checks to locate the debtor who had moved two towns over.

  • Step 2: Our Spanish-speaking collectors reached out via SMS and phone to establish a rapport and understand the financial block.

  • Step 3: We negotiated a “catch-up” settlement that recovered 100% of the principal within 60 days.

Scenario 2: The Defaulted Truck Note

An independent dealer had a $15,000 balance on a heavy-duty truck with a debtor who was “ghosting” all internal attempts.

  • Step 1: Our collection agency performed a bankruptcy and litigation scrub to ensure the debtor was eligible for collection.

  • Step 2: We sent a series of firm, professional notices via USPS demand letter and text, prompting an immediate response from the debtor’s spouse.

  • Step 3: The debtor chose to settle the full balance to avoid a negative impact on their credit report, which we updated upon payment.


A Note from the Reconciliation Team

We view ourselves as your “Account Reconciliation Team.” Our goal is to resolve the financial friction between you and your customer with total transparency. Every interaction we have is a reflection of your dealership’s values, and we take that responsibility seriously.


High-Efficiency Recovery Pricing

We offer flexible pricing models that align with your dealership’s specific recovery needs:

  • Fixed-Fee Model ($15): A flat fee per account for early-stage outreach. You keep 100% of the recovered funds.

  • Contingency Model (40%): Our “No Recovery, No Fee” option. We only get paid when we successfully bring money back to your office.

  • Returned Car Incentive (25%): We understand that a returned car has depreciated and requires labor to re-sell. Therefore, if the vehicle is returned rather than the cash being paid, our contingency fee drops to 25% to recognize the equipment’s lower value relative to a new asset.

Please Note: As a collection agency, we do not perform physical repossessions. To reclaim a vehicle, you must engage a licensed lawyer or a local sheriff if you have already obtained a court judgment.


Advanced Tools and Federal Compliance

Speed and accuracy are the engines of successful recovery. By involving a professional collection agency early, you significantly improve your recovery rates. We use the most amicable strategies to ensure your employees can do the core work they were hired for.

  • Digital Speed: We utilize email and text messaging to speed up response times when appropriate.

  • Integrity Checks: All calls are recorded and randomly reviewed to prevent “rogue collectors” and protect you from review-bombing risks.

  • Data Accuracy: We perform skip tracing, bankrupty checks, and credit reporting (where permitted and requested) to ensure every lead is actionable.

  • Bilingual Outreach: Our team includes dedicated Spanish collectors to bridge communication gaps.


Frequently Asked Questions

1. How soon should I send an account to your collection agency?

The earlier, the better. Statistically, accounts assigned within the first 60 days of delinquency have a recovery rate nearly 3x higher than those left for six months.

2. Can you help with customers who live across state lines?

Yes. Our skip-tracing and address verification tools are national, allowing us to track debtors regardless of where they move within the current business environment.

3. Does your $15 flat fee include skip tracing?

Our flat-fee service is a high-velocity outreach tool. For deeper investigative work like skip tracing on “skips” (debtors who have vanished), our contingency model is often the more effective choice.

4. Will using a collection agency hurt my local reputation?

Not with our “Velvet Hammer” approach. We focus on firm, professional reconciliation that often results in the debtor thanking us for helping them clear their record, protecting your local standing.

Recovering Debts Nationwide

Need a Collection Agency for Unpaid Auto Loans? Contact Us


Filed Under: Debt Recovery

CPA & Accounting Firm Debt Collection: Protect Relationships & Recover Past-Due Fees

You finished the return. You finished the audit. The client isn’t paying, and the fee sitting in accounts receivable outweighs almost any client relationship, but the way you go after it matters more in this profession than in almost any other, because a badly handled fee dispute doesn’t just cost you money, it can cost you a malpractice complaint you didn’t actually do anything to deserve.

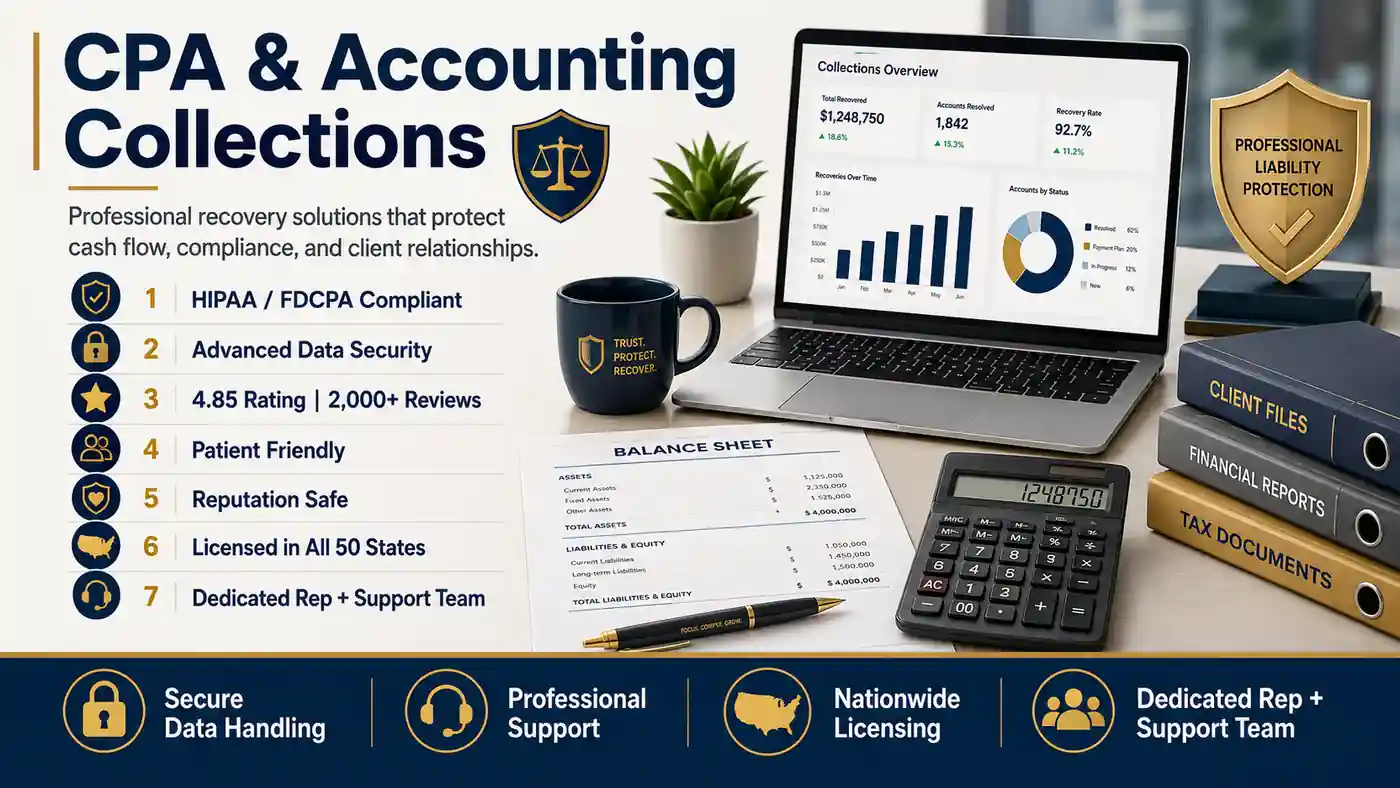
CPA and accounting collections dashboard showing secure financial recovery, balance-sheet management, data protection, nationwide licensing, dedicated support, and a 4.85 rating from 2,000+ reviews.

Quick Answer: Recovering Past-Due Accounting & Tax Fees
CPA firms should recover unpaid fees through diplomatic, AICPA-conscious outreach rather than aggressive demands or a lawsuit filed directly by the firm, since suing a client for fees is one of the most common triggers for a retaliatory malpractice counterclaim. A neutral third party sending a low-cost, professional demand letter, starting around $15 per account, resolves most balances without ever creating that opening.

Need a collection agency? Contact us


The Real Reason CPAs Hesitate to Collect: The Malpractice Counter-Claim

Every accounting firm has felt this hesitation, and it’s not paranoia. Suing a client directly for unpaid fees is one of the most reliable ways to provoke a retaliatory malpractice allegation, whether or not the underlying work had any real problem. Once a firm becomes the plaintiff in a fee dispute, the client has every incentive to reframe the relationship as a grievance instead of an unpaid bill, and even a meritless counterclaim can trigger a malpractice insurance notification, discovery costs, and months of distraction.

A neutral third party changes that dynamic entirely. When a collection agency, not the firm itself, sends the first formal demand, there’s no direct legal confrontation between accountant and client to escalate into a counterclaim. Nexa’s $15 fixed-fee demand letter functions as exactly that firewall: professional enough to get results, distant enough that it doesn’t read as the CPA personally coming after the client.

Where Accounting Fees Actually Go Unpaid

Four situations account for most delinquent accounting receivables, and each needs a slightly different approach:

Tax return delivered, fee unpaid. 
The most common scenario. The return is finished and the client wants it, but hasn’t paid. This is also the one governed by the most specific ethics rules (see below), get it wrong and you risk more than the fee.

Scope creep on audit or advisory work. 
What started as a defined engagement grows, more questions, more meetings, more analysis, without a formal amendment to the engagement letter. When the final invoice reflects that growth, clients often push back precisely because nothing was signed acknowledging the expanded scope.

Retainer depletion. 
A client burns through a retainer faster than expected, work continues because stopping mid-engagement feels worse than the risk of nonpayment, and the gap between retainer and actual hours becomes a receivable no one formally agreed to.

Monthly bookkeeping defaults. 
Recurring engagements are especially vulnerable to quiet nonpayment: a client stops paying the monthly invoice but still expects the books kept current, and by the time a firm notices, several months have accumulated.

Serving Accounting Firms Nationwide

Need an Accounting Collection Agency, or for your clients? Contact Us

What AICPA Rules Actually Say About Withholding Records

This is worth getting exactly right, because the wrong move here can turn a simple fee dispute into an ethics complaint.

Under AICPA Interpretation 501-1, client records fall into categories with different rules:

  • Records the client originally provided to you cannot be withheld under any circumstance, including an active fee dispute. This isn’t optional.
  • Your own completed work product, a finished tax return, financial statement, or similar deliverable, can generally be withheld if the client hasn’t paid the specific fee tied to preparing it. This is a real, recognized “practitioner’s lien.”

For tax engagements specifically, there’s an additional federal layer: IRS Circular 230, Section 10.28(a) generally requires practitioners to promptly return any records the client needs to meet their own federal tax filing obligations, even during an active fee dispute, unless the applicable state specifically permits a retaining lien, in which case only what must be physically attached to the return needs to go back.

The practical takeaway: you can often hold the finished return itself as leverage, but you can’t hold hostage whatever the client’s own filing deadline actually requires. Getting this distinction wrong is exactly the kind of misstep that turns a billing dispute into a state board complaint.

Litigation vs. Traditional Agency vs. Nexa’s $15 Demand

Factor Firm Files Suit Directly Traditional Collection Agency Nexa’s Step 1 ($15 Fixed-Fee Demand)
Malpractice counterclaim risk High, direct legal confrontation invites a retaliatory response Lower, but generic scripts can still feel adversarial Best, positioned as a professional, neutral nudge
Upfront cost Filing fees + attorney time Often none (contingency) $15 per account, flat
Client retention Very low, the relationship is effectively over Low to moderate Higher, many clients pay and quietly return
Speed Months Weeks Days to a few weeks
Confidentiality handling Court filings are public record Varies by agency SOC 2 Type II secure, no client data exposure beyond what’s necessary

Transparent, CPA-Friendly Pricing

Accounting receivables don’t all look the same, so the fee model shouldn’t either.

Fixed-Fee Recovery ($15/account)

Best suited to early-stage receivables — invoices where the debtor relationship is still fresh and a firm, professional nudge is likely enough. Debtors pay 100% directly to you. There are no commissions taken from what’s recovered. Can be claimed as a business expense so this service can essentially be 100% free for you.

Contingency Service (20%–40%)

Built for older, disputed, or “ghosted” accounts that need sustained investigation, skip tracing, and negotiation. No Recovery, No Fee — Nexa is paid only when the account is successfully collected.

Nexa Collections fixed-fee and contingency pricing structure for restoration company debt recovery

Recent Recovery Results

1. Mid-Sized Tax & Advisory Firm (Texas)

  • The Challenge: The firm faced $48,500 in aged past-due balances across 22 client accounts following tax season. The primary drivers were clients who received completed returns/filings but ghosted final invoice reminders, alongside scope-creep billing for unbudgeted IRS audit defense work. The managing partner was hesitant to pursue legal action due to malpractice countersuit risks. Accounts were about 60 days past due.

  • The Strategy: Deployed Nexa’s Fixed-Fee Service ($15/account). Diplomatic, soft-demand letters framed the balances as unapplied administrative oversights and offered structured monthly payment plan engineering.

  • The Result:

    • 72% ($34,920) recovered within 30 days.

    • $0 paid in contingency fees (firm retained 100% of recovered funds).

    • 14 out of 22 client relationships were successfully preserved for the following tax year without a single state board or malpractice complaint filed.

2. Regional CPA & Bookkeeping Practice (Florida)

  • The Challenge: A multi-partner CPA firm held $92,000 in severe delinquency (120+ days past due) from 8 corporate clients who defaulted on monthly retainer agreements and year-end audit fees. Internal AR staff had spent over 60 hours chasing payment with zero response.

  • The Strategy: Escalated accounts to Nexa’s Step 3 Contingency Recovery, utilizing batch skip tracing, corporate asset searches, and direct officer-level mediation while maintaining strict adherence to AICPA Rule 1.700 confidentiality guidelines.

  • The Result:

    • 61% total recovery across 6 of the 8 accounts.

    • Negotiated 3 full-balance lump-sum payouts and 3 structured 90-day settlement arrangements.

    • Total time-to-recovery averaged 82 days from placement, eliminating internal staff administrative overhead.


Frequently Asked Questions

Can a CPA send a client to collections without violating client confidentiality?

Yes, as long as only the information necessary to collect the debt is shared, name, amount owed, and basic contact details, not the underlying financial or tax information from the engagement itself. This is consistent with AICPA confidentiality standards, which govern disclosure of client information but don’t prevent a firm from pursuing payment for services already rendered.

How do I collect unpaid tax preparation fees without getting sued for malpractice?

The single biggest risk factor is the firm itself filing suit or sending aggressive demands directly, since that’s what most often provokes a retaliatory counterclaim. Routing the demand through a neutral third party, rather than the CPA personally, removes that direct confrontation and resolves most balances without ever creating the opening for a countersuit.

Is a $15 fixed-fee collection letter effective for accounting firms?

Often, yes, particularly for fresher balances. A professional, third-party demand letter frequently resolves the account without escalation, and because it’s flat-fee rather than contingency, the firm keeps 100% of whatever is recovered. It’s typically the right first move before considering contingency collection or legal escalation.

Should a CPA firm withhold tax returns for unpaid billing fees?

It depends on which records are involved. A firm can generally withhold its own completed work product, like a finished return, if the client hasn’t paid the fee tied to preparing it, but cannot withhold records the client originally provided, under any circumstance. For tax engagements specifically, IRS Circular 230 requires promptly returning whatever the client needs to meet their own federal filing deadline, even mid-dispute, unless state law specifically allows a retaining lien, in which case only what must be attached to the return has to go back.


If you are looking for a good collection agency for accountants or CPA’s,  or for their clients, we can help you.

Filed Under: Debt Recovery

Contractor Debt Recovery: Stop Funding Your Customers’ Projects

Plumber

Your Customers Aren’t “Late”—They’re Using You as a Zero-Interest Bank!

In the trades—whether you’re clearing drains, installing HVAC systems, or framing additions—every unpaid invoice is a direct hit to your personal pocket. You already paid for the copper. You already paid your crew’s Friday payroll. You already paid for the gas in the truck.

When a customer ghosts your calls or “forgets” to send the check, you are literally funding their lifestyle with your hard-earned cash. Chasing money isn’t just annoying; it’s a second, unpaid job that keeps you away from your next billable project. It’s time to stop being the neighborhood’s free credit line and start getting paid like a professional.

Nexa is the recovery partner for plumbers, electricians, and general contractors. We offer a $15 fixed-fee demand service that gets you paid without ruining the referral-heavy reputation you’ve built.

Stop Funding Your Clients. Start Collecting Today


The Tradesman’s “Aha!” Strategy: 3 Moves to Secure Your Cash

1. The “Final Walkthrough” is Your Insurance Policy

The #1 reason residential customers withhold payment is “minor dissatisfaction”—often a $50 fix used to hold up a $5,000 invoice.

  • The Move: Never leave a site without a signed Certificate of Completion.

  • The “Aha!” Factor: When a debtor tries to claim the work was “substandard” to a collector later, that signed document is your “Get Out of Jail Free” card. It turns a subjective argument into an objective debt.

2. Watch the 90-Day “Lien Cliff”

Most contractors wait far too long to get serious. In many states, your legal right to file a Mechanic’s Lien expires exactly 90 days after your last day on the job.

  • The Move: If the check isn’t in your hand by day 45, the account is officially at risk.

  • The “Aha!” Factor: Nexa’s $15 Fixed-Fee Service triggers a formal agency demand on day 46. It sends a signal that you aren’t just “some guy in a truck”—you’re a business with a legal team.

3. Conditional Lien Waivers: The Safe Middle Ground

Customers often refuse to pay because they fear you’ll file a lien after they pay.

  • The Move: Offer a Conditional Lien Waiver.

  • The “Aha!” Factor: This document says: “My right to file a lien is gone as soon as this check clears.” It removes the customer’s last excuse for withholding the funds.


Cost-Effective Recovery (No Onboarding Fees)

blank

  • Fixed-Fee Recovery ($15/account): We send professional, firm demands under our agency name. The customer pays 100% directly to you. You keep every dollar recovered.

  • Contingency Fee (20%–40%): For the accounts that require “diplomatic” phone calls and deeper skip-tracing. No Recovery = No Fee.


Industries We Serve

  • Plumbing & Rooter: Rapid recovery for high-volume residential calls.

  • HVAC & Mechanical: Managing high-value equipment invoices and maintenance contracts.

  • Electrical & Solar: Navigating complex commercial progress payments.

  • Restoration & Remediation: Expertise in handling “Insurance-Check” withholding disputes.

  • General Contracting & Sub-Trades: Securing the payment chain between the GC and the homeowner.


Recent Trade Success Stories

  • The “Punch List” Blockade:
    A kitchen remodeler was owed $12,000. The customer refused to pay because of a loose cabinet handle. Nexa used Amicable Mediation to secure the $11,800 undisputed portion in 10 days, allowing the contractor to fix the handle and move on.

  • The Ghosting Homeowner:
    An electrician completed a full panel upgrade ($4,500) and was blocked on the customer’s phone. Nexa’s Fixed-Fee Demand reached the customer’s spouse; the full payment was mailed within 48 hours.


Frequently Asked Questions (FAQ)

1. “I don’t have a written contract. Can I still collect?”
Yes. While a written contract is best, a series of text messages, emails, or even a signed work order can serve as evidence of an “agreement to pay.” We specialize in building cases out of unconventional documentation.

2. “What if the customer claims my work was bad?”
This is the most common “defensive” tactic. We act as a third-party mediator. By asking the customer for specific documentation of the “bad work,” we often expose the claim as a stall tactic, allowing us to pivot back to the payment demand.

3. “I’m afraid of a bad Google/Yelp review if I send them to collections.
“
Our “Amicable First” strategy is designed to preserve your reputation. We don’t use “strong-arm” tactics; we use professional business mediation. Most customers respect a firm business approach and will settle the debt once a third party is involved.

4. “How do I know when it’s time to stop calling them myself?”
If you have called three times and been promised a check that never arrived, you are being “managed.” Stop wasting your billable hours. Hand the account to Nexa so you can get back to the job site.

Serving Plumbers Nationwide

Need a Collection Agency for Plumbers? Contact Us


Filed Under: Debt Recovery

  • « Go to Previous Page
  • Page 1
  • Interim pages omitted …
  • Page 50
  • Page 51
  • Page 52
  • Page 53
  • Page 54
  • Page 55
  • Go to Next Page »

Primary Sidebar


accounts receivable

Need a Collection Agency?
Kindly fill this form.
We’ll get in touch with you

    Please prove you are human by selecting the car.

    Compliance & Security

    • SOC 2 Type II Certified: Third-party audited data security and strict privacy controls.

    • HIPAA Compliant: Secure, legal processing of medical and municipal EMS accounts.

    • PCI-DSS Level 1: Highest tier of data encryption for secure payment processing.

    • FDCPA & FCRA Aligned: Full legal adherence to federal consumer protection laws.

    Recent Posts

    • Nationwide Debt Collection Agency Serving U.S. Cities
    • Chula Vista Collection Agency for Medical, B2B, Schools & Business Debt
    • Corpus Christi Collection Agency: Itemized Bill Rules for Practices
    • Riverside Collection Agency | For Logistics, Medical, Schools & Business Recovery
    • Collection Agency for Large Balances: High-Value B2B Debt Recovery
    • Baltimore Collection Agency | Medical, Commercial, Schools & More
    • Commercial and B2B Collection Agency in Detroit
    • Boston Medical Collection Agency | Serving Hospitals, Physicians & Dentists

    Featured Posts

    • Get New Dental Patients: Modern Marketing to Outwit Competitors
    • How to Find New Clients for a Medical Accounting Firm
    • Top 14 Issues Faced by EMS / Ambulance Operators

    Copyright © 2026 NEXACOLLECT.COM | This content is provided for general informational purposes only and should not be considered legal advice. Collection laws and requirements may vary by state, account type, documentation, debtor status, and specific facts. Please consult qualified legal counsel for guidance regarding your particular situation. Nexa and its authorized collection partners service accounts in accordance with applicable federal and state collection requirements. Visit our home page to know more about us.

    X
    Need a Collection Agency?
    Contact Us