• Skip to main content
  • Skip to primary sidebar

Nexa Collections

  • Home
  • Serving
    • Medical
    • Dental
    • Small Business
    • Large Business
    • Commercial Collections
    • Government
    • Utilities
    • Fitness Clubs
    • Schools
    • Senior Care Facility
  • Contact Us
    • About us
    • Cost

Debt Recovery

Utility Collection Agency for Electric, Gas, Water & Sewer Providers

A utility collection agency recovers unpaid bills for electric, gas, water, sewer, and waste service providers — with a specialization in final-bill and move-out recovery that standard collection agencies are not equipped to handle.

Utility debt collection operates under a unique compliance environment: in addition to FDCPA and TCPA, collectors must navigate state Public Utility Commission (PUC) rules, seasonal disconnection moratoriums, landlord/tenant liability disputes, and GLBA data-security requirements.

The most effective utility collection agencies combine forensic skip-tracing for moved-out customers, regulatory-compliant multi-channel outreach, and automated moratorium controls that protect your utility brand from regulatory complaints.
Utility collection agency recovering unpaid electric and gas bills for power providers — FDCPA and PUC compliant with forensic skip-tracing for final-bill accounts

Electric, gas, water, sewer, and waste providers keep communities running. But high account volumes, tight margins, seasonality, and strict public-utility rules make past-due recovery uniquely challenging—especially final bills after a move-out. You need a specialist who protects your brand while improving net recoveries.

Why In-House Efforts Plateau

  • Hidden cost of collections: staff time, training, QA, and turnover dilute results.

  • Compliance exposure: FDCPA, TCPA consent/dialer rules, FCRA (if reporting), GLBA data safeguards, plus state PUC shut-off/moratorium rules. A single misstep risks fines and reputational damage.

  • Operational gaps: large “long tail” of small balances, skip-trace needs on move-outs, landlord/tenant responsibility disputes, and seasonal spikes.

What Makes Us Different

  • Utility-specific approach: respectful, “customer-first” collections that align with community expectations and board/council oversight.

  • Compliance by design: FDCPA, TCPA (express consent management, DNC scrubs), FCRA/Metro-2 (optional, by client policy), GLBA; PCI-compliant payments and SOC 2–aligned processes.

  • Omnichannel with consent: letter, phone, email, SMS, self-serve portal/IVR, and multilingual (incl. Spanish).

  • Data-driven results: segmentation, propensity-to-pay modeling, right-time outreach, and real-time dashboards.


Serving Utility Companies Nationwide !

Need a collection agency: Contact us

Solutions Mapped to Your AR Stages

Our 4-Stage Utility Recovery Framework

Utility debt recovery is not a single process — it is a sequenced framework calibrated to the account’s age, balance, debtor status, and regulatory environment. Here is how we approach every utility portfolio:

Stage 1 — Immediate Data Scrubbing & Account Triage

The moment accounts are placed, we cross-reference every disconnected account against national change-of-address (NCOA) databases, utility industry databases, and credit header data to locate the debtor’s current address before a single letter is sent. Accounts are simultaneously screened for bankruptcy, military (SCRA) status, deceased indicators, and active PUC moratorium holds — removing ineligible accounts from the collection queue before any outreach begins. This eliminates wasted spend and compliance exposure from day one.

Stage 2 — Soft-Touch, PUC-Compliant Multi-Channel Outreach

For accounts cleared by Stage 1 screening, we initiate regulatory-compliant, multi-channel communications — letters, SMS (with verified TCPA consent), email, and self-serve IVR — calibrated to your Public Utility Commission’s standards and your brand voice. Outreach is sequenced by propensity-to-pay score: higher-probability accounts receive earlier phone escalation; lower-probability accounts are resolved through cost-efficient digital channels first. All messaging is available in English and Spanish as standard, with additional languages on request for service territories with diverse customer populations.

Stage 3 — Advanced Forensic Skip-Tracing

For high-balance gas and electric final-bill accounts where the customer left no forwarding information — or where Stage 2 outreach confirmed the provided address is stale — we deploy deep-tier forensic skip-tracing. This goes beyond NCOA: we cross-reference employer records, phone carrier data, property transfer records, utility connection records at new addresses, social profile signals, and court filings to build a current contact profile. Forensic skip-tracing is the single highest-ROI activity for utility final-bill portfolios, where the moved-out customer is often traceable but simply unreachable through standard channels.

Stage 4 — Credit Reporting & Final Resolution

For accounts that remain unresolved after Stages 1–3, we report eligible inactive accounts to the major consumer credit bureaus — Equifax, Experian, and TransUnion — using Metro-2 compliant formatting (client-controlled; you decide which accounts are reported and when). Credit reporting is one of the most effective final-resolution tools for utility debt because the impact on a customer’s credit profile creates urgency to resolve — particularly for former customers who are now applying for new utility service, a mortgage, or a car loan. Legal escalation via affiliated attorneys is available for high-balance accounts with verified assets, with your explicit written approval.

Where We Excel for Utilities

  • Final Bills & Move-Outs: advanced skip-trace, new-address linking, employer/phone/email enrichment.

  • Landlord/Tenant Responsibility: documented occupancy windows, lease linkage, and property-manager workflows.

  • Dispute Resolution: meter read/date disputes, estimated bill corrections, and payment-plan conversion.

  • Energy Theft/Tampering Fees: specialized scripts and evidence handling.

  • Deposits, Fees & Returned Checks: deposit application/recovery, NSF, reconnection/field fees.

  • Deceased & Probate Handling: compassionate outreach, estate claims, and timeline tracking.

  • Bankruptcy & Military (SCRA) Protocols: automatic scrubs and compliant treatment paths.

  • Medical/Critical-Care Flags & Moratoria: respectful handling; no shut-off pressure messaging, weather/winter rules honored.

  • Small-Balance at Scale: automated micro-AR cleanups without burdening your team.

Utility Types We Serve

Our recovery process is calibrated to the regulatory, billing, and customer-relationship differences across utility commodity types:

Electric utilities — investor-owned, municipal, and rural co-ops

Electric utility collections involve the highest average final-bill balances and the strictest state PUC oversight. Investor-owned utilities (IOUs) face public rate-case scrutiny that makes complaint rates especially sensitive. Municipal electric utilities operate under city council oversight with additional political accountability. Rural electric cooperatives (RECs) serve member-owners — meaning every collection interaction affects a co-op membership relationship, not just a customer account. We tailor scripts, escalation thresholds, and reporting formats to your governance structure.

Natural gas providers

Gas accounts carry the highest seasonal volatility: winter heating bills spike final-bill balances significantly, and winter moratorium rules in most states restrict disconnection and collection activity between November and April. Our compliance engine automatically applies state-specific heating moratorium rules, suppresses collection activity during protected periods, and queues accounts for immediate outreach when the moratorium window closes — capturing the recovery opportunity before the next heating season begins.

Water & sewer authorities

Water account collections often involve municipal or special-district governance with formal public meeting reporting requirements. Balance sizes tend to be lower than electric or gas, making fixed-fee letter campaigns the most cost-effective recovery path. Landlord/tenant disputes are especially common in water collections because water service is frequently maintained in the landlord’s name even during tenancy — creating complex liability questions that our documented occupancy-window process resolves before outreach begins.

Telecom, cable & internet providers

Telecom final bills involve equipment return disputes, early termination fee collections, and a high volume of disputed balances. Our dispute-handling workflow verifies equipment return status and ETF calculation before pursuing any contested balance — preventing the frivolous-dispute volume that inflates collection costs for telecom AR teams. We also handle returned-equipment charge recovery separately from service-balance recovery, since these have different documentation requirements.

Waste, refuse & recycling services

Waste collection accounts typically have the lowest individual balances but the highest account volumes — making automated, low-cost fixed-fee resolution the right approach. Our small-balance automation handles bulk refuse portfolios efficiently without manual collector involvement, recovering aggregate revenue that would otherwise be written off as too small to pursue individually.

Multi-commodity & energy retailers

Energy retailers operating in deregulated markets often manage both electric and gas accounts under a single customer relationship — with different state PUC regulations governing each commodity. Our collectors are trained on the specific regulatory frameworks of all deregulated energy markets (Texas ERCOT, Illinois, Ohio, New York, Pennsylvania, etc.) and apply the correct rules per commodity, per account, per state.

Seasonal Moratoriums & State PUC Collection Rules

Every state has its own Public Utility Commission (PUC) rules governing when and how utilities can pursue debt collection. Getting this wrong — even with the right intent — can result in regulatory fines, consumer complaints filed with the PUC, and reputational damage that outweighs the recovered revenue. Here is how we manage the most common regulatory constraints:

Winter heating shutoff moratoriums

Most states with significant cold-weather seasons have winter heating moratorium rules that restrict or prohibit disconnection of natural gas and electric heating accounts between specific dates (commonly November 1 through April 15, though exact dates vary by state). Many states also restrict collection agency contact on these accounts during the moratorium period. Our compliance engine is state-mapped: accounts in moratorium states are automatically flagged, collection activity is suspended for the protected period, and accounts are queued for immediate outreach when the moratorium window closes — capturing the spring recovery window before accounts age further.

Medical necessity and critical-care holds

Customers with documented medical conditions requiring continuous electric or gas service can apply for medical necessity holds that restrict disconnection and, in some states, third-party collection activity. We process medical hold flags at account intake and apply compliant treatment paths — never using shutoff-pressure messaging on medically protected accounts, and routing these to payment-plan outreach only.

Low-income customer protections

Many states require utilities to offer low-income customers arrearage management programs (AMPs), budget billing, or LIHEAP referrals before pursuing collection. Our collectors identify LIHEAP, LIHWAP, and state-specific assistance program eligibility markers at intake and refer qualifying customers to assistance programs — reducing write-offs while avoiding the regulatory liability of pursuing someone who qualifies for protected status.

State-specific PUC interest rate caps and fee limitations

Some state PUC tariffs cap the interest rates and late fees that utilities can charge on overdue accounts — and by extension, limit what can be included in a collection demand. Our compliance engine is updated dynamically to mirror individual state tariff limitations, ensuring that demand letters never include uncollectable fee amounts that could trigger a dispute or a PUC complaint.

Landlord & Tenant Utility Debt: Determining Responsibility

One of the most common complications in utility final-bill recovery is the landlord/tenant liability dispute — where the property owner and former tenant both claim the other is responsible for the unpaid balance. Here is how we navigate this:

How we document the service period

Before any outreach, we establish the billing window — the dates during which service was provided and consumed. We cross-reference your billing system’s service dates against lease commencement and termination records (where available), property transfer records, and NCOA data. This creates a documented occupancy timeline that establishes who was in residence during the period the charges accrued.

Tenant liability vs. landlord liability

In most states, the person who applied for and received service is the primarily liable party — regardless of who actually consumed it. If a tenant applied for service in their name, they are the primary debtor. If the account was in the landlord’s name throughout the tenancy, the landlord retains liability for any balance, with a separate right of action against the tenant under the lease agreement. We pursue the documented account holder first, not the property address.

Property manager workflows

For utility companies servicing large rental portfolios managed by property management companies, we offer a dedicated property manager contact protocol — reaching out to the management company’s AR contact rather than the individual property owner for multi-unit residential landlord accounts. This consolidates communication, reduces duplicate contacts, and respects the professional relationship between your utility and large property management clients.

When both parties dispute

When both the landlord and tenant deny responsibility, we conduct a documented dispute resolution process: requesting lease agreements, move-in/move-out inspection records, and utility transfer confirmation, then assigning liability based on the weight of documentation. Unresolved disputes are escalated to our legal team for assessment of which party has a viable collection path — rather than pursuing both simultaneously and creating regulatory exposure.

Integration, Reporting, and Our Security

  • Fast, secure onboarding: SFTP/API or portal upload; account-level consent flags, service status, and move-out dates captured.

  • 24/7 portal: placements, notes, disputes, recoveries, and dashboard KPIs (recovery %, liquidation by DPD, right-party contact rate, average days-to-pay, complaint rate).

  • Controls: call recording, QA scorecards, model governance, and monthly performance reviews.

  • Key Strength: We address critical utility industry pain points directly—such as final-bill aging, high move-out delinquency rates, budget-billing reconciliation, and preserving customer goodwill in regulated markets.

Utility Collection Results

Case Study: Regional Electric Co-op — $890,000 in Final-Bill Recovery

The situation: A rural electric cooperative with 41,000 member-accounts had accumulated $890,000 across 3,200 final-bill accounts from moved-out members. Average balance: $278. The co-op’s internal billing team had sent one statement per account but had no skip-tracing capability — approximately 40% of accounts had no valid forwarding address in the system.

Our approach: We ran the full portfolio through Stage 1 NCOA and utility-database scrubbing within 48 hours of placement, locating new addresses for 1,840 of the 3,200 accounts (57.5%). We deployed Stage 2 branded letter campaigns for located accounts and Stage 3 forensic skip-tracing for the remaining 1,360. All outreach was calibrated to the co-op’s member-relationship tone — emphasising account resolution over pressure tactics.

The outcome: 68% of located accounts resolved within 90 days. Total recovered: $604,000. An additional $87,000 recovered via credit reporting trigger payments in months 4–6. Zero PUC complaints filed. The co-op’s board reported the program at the annual member meeting as a model for responsible revenue recovery. (Nexa internal data, 2025)

Case Study: Municipal Water Authority — High-Volume Small-Balance Cleanup

The situation: A city water authority had 8,400 final accounts under $200 — totalling $1.1M — that had been written off internally due to the perceived cost of pursuing small balances individually. Staff estimated that manual outreach on these accounts would require 1.5 FTE for six months.

Our approach: We processed the full portfolio through our small-balance automation track: Stage 1 scrubbing, then a five-letter fixed-fee demand series at $15 per account. Total placement cost to the authority: $126,000. No phone outreach was required — the letter series alone resolved 52% of accounts.

The outcome: $571,200 recovered. Net return after placement cost: $445,200 — with zero additional staff hours from the authority’s team. Accounts over $200 were escalated to Stage 3 contingency phone outreach, recovering a further $143,000. Total net recovery: $588,200 on a $126,000 investment. (Nexa internal data, 2024)

Results You Can Expect

  • 10–25% lift in final-bill recoveries vs. in-house only

  • 20–40% reduction in cost-to-collect on early-stage AR

  • Measurably lower complaint rates with community-sensitive scripting

Stop letting past-due accounts leak revenue. Choose a partner engineered for utility AR—and built to protect public trust.

Frequently Asked Questions: Utility Debt Collection

Can you collect on active utility accounts, or only inactive/closed ones?

We primarily specialise in final-bill and inactive utility accounts — past tenants, moved property owners, and closed service accounts. This protects your ongoing customer relationships while aggressively recovering lost revenue from dormant accounts. Active-account early-stage reminders (Step 1 first-party program) can be deployed for newly past-due balances as a brand-safe pre-collection service, but our core utility expertise is in final-bill and move-out recovery where skip-tracing and forensic location work is required.

How do you ensure compliance with state Public Utility Commission (PUC) rules?

Our compliance engine is dynamically updated to mirror individual state laws, maximum interest rate caps, and seasonal disconnection/collection moratoriums — ensuring zero regulatory risk to your utility brand. When a state implements a new moratorium rule or updates its tariff-based fee limitations, our system flags affected accounts and adjusts outreach protocols automatically. We provide monthly compliance attestation reports you can submit to your regulatory affairs team or use in PUC proceedings.

How long before a utility bill goes to collections?

Most utility providers place final-bill accounts with a collection agency between 60 and 90 days after the final bill is issued, following at least one internal statement attempt. For active accounts, the threshold is typically 90–120 days past due after internal escalation has been exhausted. Waiting beyond 120 days on final bills significantly reduces recovery rates — a moved-out customer’s contact information degrades rapidly, and forensic skip-tracing becomes more expensive and less successful the longer the account ages.

Does an unpaid utility bill affect credit scores?

It can — but the landscape has changed. Unpaid utility balances under $500 are no longer included on consumer credit reports under major bureau policy changes effective 2023–2024. For balances over $500 placed with a collection agency, the agency can report to Equifax, Experian, and TransUnion using Metro-2 formatting — which typically remains on the consumer’s credit report for up to 7 years from the date of first delinquency. Credit reporting is a client-controlled option at Nexa: you decide which accounts are reported and when, based on your utility’s customer relationship policy.

How do you handle SCRA military account protections?

The Servicemembers Civil Relief Act (SCRA) provides significant protections for active-duty military members — including interest rate caps, restrictions on certain legal actions, and in some cases protections against utility disconnection. We run SCRA scrubs on all accounts at intake using the Department of Defense’s Manpower Data Center (DMDC) database. Active SCRA accounts are flagged and removed from standard collection workflows; they receive a compliant treatment path that respects military protections and maintains your relationship with active-duty customers and their families.

What is forensic skip-tracing and how is it different from standard skip-tracing?

Standard skip-tracing uses NCOA (National Change of Address) and credit header data to find a new address — it resolves the majority of “soft skip” accounts where the customer simply moved and forgot to update their address. Forensic skip-tracing goes deeper: we cross-reference employer records, property transfer databases, utility connection records at new addresses (showing where they turned on service next), phone carrier data, and social profile signals. For high-balance electric and gas final-bill accounts where the customer deliberately left no forwarding trail, forensic skip-tracing often recovers accounts that standard methods cannot.

Who is responsible for an unpaid utility bill — the tenant or the landlord?

In most cases, the person who applied for and received service is the primarily liable party — regardless of who consumed it. If a tenant applied for service in their name, they are the primary debtor. If the account was in the landlord’s name, the landlord retains liability. When both parties dispute responsibility, we conduct a documented occupancy-window analysis using lease dates, NCOA data, and property transfer records to establish who was in residence during the billing period — then pursue the party with documented liability.

Can you collect from a former tenant who has moved to another state?

Yes. Nexa is licensed to collect in all 50 states. When a former tenant moves out of your service territory, the debt moves with them — subject to the originating state’s statute of limitations on utility debt (typically 3–6 years depending on the state and the nature of the obligation). We apply the debtor’s current state’s contact rules while pursuing a debt originated in your state. Interstate utility final-bill recovery is a core competency — it’s where forensic skip-tracing most frequently proves its value.

How does the fixed-fee letter service work for small utility balances?

For accounts under approximately $300–$500 where the contingency economics don’t justify phone outreach, our fixed-fee letter series (Step 2, $15 per account) sends five escalating written demands with dispute-handling workflows built in. You pay $15 per account regardless of outcome on accounts that resolve — and keep 100% of every dollar recovered. The letter series resolves 40–60% of cleanly documented final-bill accounts without requiring any phone outreach, making it the most cost-effective utility collection tool for high-volume small-balance portfolios.

Do you integrate with utility billing and CIS platforms?

Yes. We accept account placements via SFTP file transfer or REST API integration, with account-level consent flags, service status, move-out dates, and last-known address captured at intake. Tested platforms include Oracle CC&B (Customer Care & Billing), SAP ISU, Cayenta, Datastream, and major AMI/MDM systems. Payment confirmations and account status updates are pushed back to your system on a scheduled basis. Our 24/7 secure portal provides real-time account-level visibility for your billing and AR teams without requiring system integration.

What happens to accounts during a PUC-mandated winter moratorium?

Accounts in states with active winter heating moratoriums are automatically suppressed in our outreach queue for the protected period — no letters, no calls, no collection activity. The account remains in our system and is queued for immediate outreach when the moratorium window closes. This ensures you capture the spring recovery window — typically March through May — when customer incomes stabilise after winter and before the next heating season begins. We provide a moratorium status report showing all suppressed accounts and their scheduled reactivation dates.

How do you handle deceased utility account holders?

Deceased accounts require compassionate outreach directed to the estate executor or next of kin — never to the deceased individual. We run deceased-indicator scrubs at intake, flag identified accounts for estate-claim processing, and direct outreach to the estate with a notice of claim that is legally appropriate in the relevant state. For small-balance deceased accounts where estate proceedings are unlikely, we apply a documented write-off workflow that satisfies your audit requirements without incurring collection costs on unrecoverable balances.

What is your complaint rate for utility collections?

We maintain utility-specific complaint rate tracking separate from our overall portfolio — because the political sensitivity of government-regulated utility collections demands a higher standard. Our utility complaint rate targets are: zero PUC-filed complaints and fewer than 0.5 FDCPA complaints per 1,000 accounts contacted. We report complaint rates monthly in your performance dashboard and treat any PUC-filed complaint as a critical incident requiring same-day review and response. We maintain a 4.85/5 aggregate rating across 2,000+ online reviews — a reflection of our community-sensitive outreach standards.
 

Filed Under: Debt Recovery

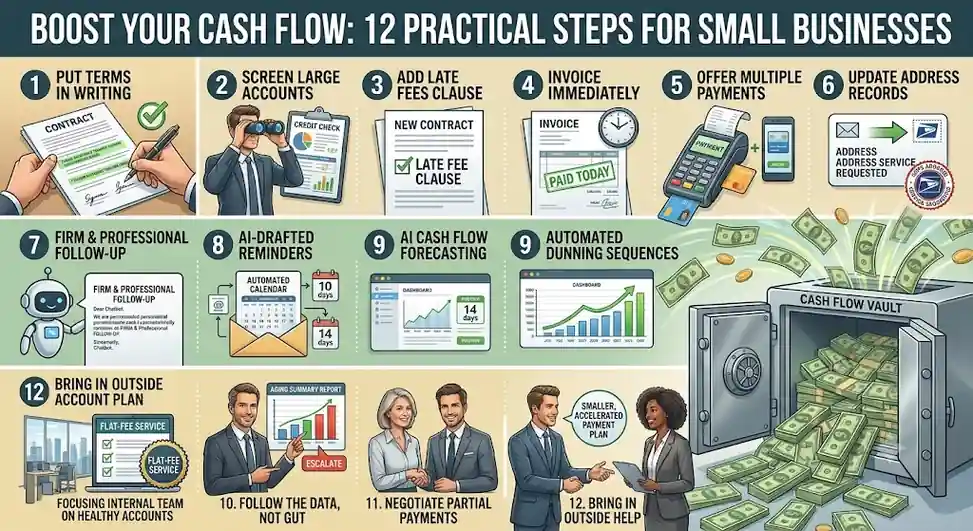
How to Improve Cash Flow: 12 Practical Steps for Small Businesses

Most small businesses that fail don’t run out of customers — they run out of cash, usually because of slow-paying accounts. Improving cash flow starts with clear payment terms and prompt invoicing, gets reinforced by consistent follow-up and modern tools like AI-drafted reminders, and ends with knowing when to bring in outside help on accounts that have gone quiet for 60 to 90 days.

steps to follow to improve cash flow for your small business

Why Cash Flow Problems Sneak Up on Good Businesses

An often-cited stat puts the number at around 80% of small business failures tracing back to cash flow, not a lack of customers or a bad product. The pattern is usually the same: work gets done, invoices go out, and then nothing happens for weeks because no one followed up. None of the fixes below are complicated — most just require deciding in advance what your process is, instead of reacting account by account.

Set the Terms Before You Need Them

Put payment terms in writing

If customers don’t know exactly when payment is due, plenty will assume “whenever” is close enough. State your terms clearly on every invoice and contract, not just in a conversation that’s easy to forget.

Screen larger accounts before extending credit

A quick bank reference or trade credit check before a large sale on credit is a small cost against a real risk. For mid-sized deals, even a basic credit check pays for itself the first time it flags a problem account.

Add a late fee clause up front

A late fee is easiest to introduce when you’re signing a new agreement — nobody expects to pay late on day one, so there’s no friction. Down the line, it gives slow payers a reason to prioritize your invoice over others, and covers some of the cost of chasing it.

Make It Easy to Pay You Fast

Invoice immediately, then follow up on a schedule

Delayed invoicing is a surprisingly common reason payments are late — the customer simply hasn’t been billed yet. Once an account is overdue, contact every 10 to 14 days rather than waiting a full month between reminders.

Offer more than one way to pay

A customer who has to mail a check or read a card number over the phone is a customer who’ll put it off. Online payment, ACH, and card options remove that friction.

Keep your address records current

Bad addresses are a quiet source of missed payments. USPS’s “Address Service Requested” service (printed just below your return address) automatically returns updated forwarding information when mail goes to an old address — most modern billing platforms now run this check automatically as part of sending statements.

Modern Tools Worth Adding to the Basics

None of this replaces good process, but a few tools have become genuinely useful additions:

  • AI-drafted reminders: Tools like ChatGPT can turn “please pay us” into a firm, professional, personalized follow-up in seconds — useful for a business without a dedicated collections writer.
  • Automated dunning sequences: Many invoicing platforms now schedule and send reminder sequences automatically, timed around when a given customer segment historically responds.
  • AI-assisted cash flow forecasting: Modern accounting software can flag which open invoices are statistically likely to go late based on that customer’s payment history, before the due date passes.
  • Basic chatbots for payment status: A simple bot that answers “what do I owe and how do I pay it” frees staff for the calls that actually need a person.

Follow the Data, Not Your Gut

Use your aging report to decide when to escalate

It’s tempting to give a familiar customer more slack because it “feels” like they’ll pay eventually. An aging summary report will tell you faster and more accurately who’s actually paying and who isn’t.

Treat a partial-payment call as a good sign

A customer who calls to say they can’t pay in full is still engaging. Negotiate what they can pay now and when the rest is due — a smaller, aging balance is easier to resolve than a large one that’s gone quiet.

Handle People Well, Fix Your Own Mistakes Fast

Staff dealing with overdue accounts should be trained to stay firm without being adversarial — the goal is getting current while keeping the relationship. If a customer is disputing a charge because of a genuine error on your end, own it and fix it quickly; denying an obvious mistake just adds resentment on top of an unpaid bill. And know the law: businesses collecting their own debts are often bound by many of the same rules that govern third-party collection agencies, including restrictions on when and how you can contact someone.

Know When to Bring in Outside Help

Statistics commonly cited in the collections industry suggest in-house follow-up loses most of its effectiveness after 90 days — by that point, a customer has usually had four to six requests for payment already. That’s the point where a flat-fee reminder service or a collection agency partner tends to accomplish more than another internal phone call, simply because the request is coming from somewhere other than you. Not every account will be collected no matter what you do — the businesses that manage cash flow best are the ones that identify those accounts early and stop spending time on them.

Need help with an account that’s stopped responding? Contact us and we’ll help you find the right fit.

Frequently Asked Questions

What’s the biggest cause of small business cash flow problems?

Slow-paying or non-paying customers, most commonly. Around 80% of small business failures are linked back to cash flow issues rather than a lack of demand for the product or service itself.

How often should I follow up on an overdue invoice?

Every 10 to 14 days once an account is past due. Waiting a full month between reminders lets the balance drift further from the customer’s mind.

Should I charge a late fee?

It’s worth considering, especially if it’s written into the agreement from the start. A late fee gives customers a reason to prioritize your invoice and offsets some of the cost of following up.

Can AI tools actually help with collections?

Yes, at a basic level. AI can draft personalized reminder emails, and modern accounting software can flag which invoices are statistically likely to go late before the due date even passes.

When should I stop chasing an overdue account myself?

Most in-house follow-up loses effectiveness after 90 days. If an account has gone quiet after four to six contact attempts, that’s typically the point to consider outside help rather than continuing to absorb the time cost yourself.

Is it legal to call customers about a past due balance?

Generally yes, but many states hold businesses collecting their own debts to rules similar to those governing collection agencies — restrictions on contact hours and disclosing the debt to third parties, for example. Check your state’s requirements if you’re unsure.

Filed Under: Debt Recovery

Collection Agency: Body Shop and Auto Repair Garage

Car Workshop

Automotive repair and body shop garages regularly face issues related to accounts receivable. Whether it is because a customer did not fulfill his obligation to pay or a delay/rejection of the claim by an insurance company. Past-due accounts can quickly erode the profits of an automotive workshop and even interrupt the smooth running of the facility.

If an Automotive workshop on a 20% profit margin, say 5% of their customers do not pay, then effectively 25% of their net profit is gone. Collecting money from existing customers is more important than getting new customers. Sounds unreal, but it’s correct.

Need a collections agency: Contact us

Besides the time required to generate new business, an automotive workshop faces many challenges. These include increased competition, certification requirements, integrated vehicle technologies, a limited number of skilled workers, paperwork, and higher expectations for speedy repairs despite a slower reimbursement process by insurance companies.

If a repair is being paid through an insurance claim, the garage must often navigate a complex process to get paid. This can lead to delays and increased administrative burden.

Relying on in-house staff, which are not adequately trained to collect the debt can be ineffective, time-consuming and costly. Transferring an account to a professional collection agency will reduce the staff burden and even result in higher recovery rates. Debt collectors are experts in collecting debt; after all that is what they do every workday. They ensure that the debt collection rules and regulations specified by the Federal and State governments are followed, minimizing the chances of a counter-lawsuit.

A collection agency will also do advance Skip Tracing, which helps to locate a debtor in case he has shifted from this residence. Services offered by collection agencies are usually diplomatic but can be slightly intensive if required. The two-step collection process offered by collection agencies is perfect for starting the diplomatic process initially and then using debt collectors or filing a legal suit to put more pressure to settle the account. Collection agencies can also report the debt to Credit Bureaus if you request them to do so. They drastically reduce the stress of debt collection for the owner and the staff.

Collection Letters Service
  • Upfront cost for 5 Collection Letters is about $15 per account.
  • Debtors pay directly to you, no other fees. Low cost option.
  • Good for accounts less than 120 days past due.
Collection Calls Service
  • Contingency fee only. No upfront or other fees.
  • Agency gets paid a portion of money they recover.  No recovery-No fees.
  • Best for accounts over 120 days. A debt collector calls debtor many times.
  • If everything fails, a possible Legal Suit if recommended by the attorney.


Filed Under: Debt Recovery

Telecom & ISP Debt Recovery | Equipment & Revenue Solutions

blank

Reclaiming the Signal: High-Velocity Revenue Recovery for Telecom & ISP Leaders

In an industry defined by 5G expansion and aggressive subscriber churn, your “bad debt” is often a mix of ghost accounts and unreturned hardware. For telecom giants and regional ISPs, an unpaid invoice isn’t just a loss of service revenue—it’s the loss of physical assets and the high cost of subscriber acquisition. As churn rates in the mobile sector hover between 20% and 50% annually, waiting 90 days to act is no longer an option. Nexa provides a sophisticated, tech-enabled recovery strategy that protects your brand’s reputation while securing the cash flow required to maintain your infrastructure.

The Telecom Economy: By the Numbers

The “cost of churn” is staggering. For a provider with 1 million subscribers at a $50 ARPU, a 20% churn rate translates to $120 million in lost revenue annually. Furthermore, the industry is currently navigating a period of high debt due to 5G infrastructure capex. Nexa helps offset these pressures by turning “uncollectible” accounts into liquid assets, specifically focusing on the high-value equipment often left behind when a subscriber switches carriers.

Industries We Serve (Telecom & Tech)

  • MVNOs (Mobile Virtual Network Operators): specialized recovery for light-infrastructure carriers where high churn is a constant threat to margins.

  • ISPs & Fiber Providers: focused on recovering balances and unreturned hardware (routers, modems, ONT units) from residential and commercial installs.

  • VOIP & Cloud Communications: 100% HIPAA-compliant recovery for business communication systems, ensuring service fee disputes don’t linger.

  • Satellite & Broadband: Managing high-value equipment recovery and multi-service “bundled” account balances.

  • Construction & Infrastructure: Revenue recovery for subcontractors and crews handling fiber-to-the-home (FTTH) rollouts.

  • B2B Commercial Tech: specialized recovery for restoration and waste management firms serving the telecom industry.


Telecom Compliance: 2026 Legal Framework

Telecom debt is uniquely regulated. Nexa remains ahead of the curve, ensuring your center is protected from TCPA litigation.

Feature 2026 Regulation / Update
TCPA Revocation As of April 11, 2026, new FCC rules require callers to apply a “one-type” opt-out to all communication channels. Nexa’s systems are fully integrated to meet this deadline.
RCS Messaging The FCC and carriers now prioritize verified RCS messages over standard SMS to reduce “robotext” spam.
Equipment Liens While consumer billing is protected, commercial equipment recovery allows for aggressive asset-location strategies.
Statute of Limitations Generally 4 years for written contracts, though federal “Truth in Billing” rules apply to certain disputes.

Recent Recovery Results

  • B2B Fiber Infrastructure: A regional ISP was owed $14,500 for a commercial fiber installation where the client disputed the hardware cost. Nexa initiated a professional mediation phase, resulting in a 100% principal recovery within 32 days.

  • Medical Group VOIP Recovery: A multi-site medical practice had an outstanding balance of $11,200 for cloud communication services. Using our HIPAA-compliant recovery protocol, we secured a full settlement in 18 days.

Transparent & Cost-Effective Pricing

blank

  • Fixed Fee Service ($15): The gold standard for early-stage delinquency. The subscriber pays you directly; you keep 100% of the money.

  • Contingency Fee (20% – 40%): Our “No Recovery, No Fee” model. We take the risk, and you get the results.


Frequently Asked Questions (FAQ)

1. How do you handle unreturned equipment like routers or modems?

We use a specialized “Hardware Reconciliation” track. We don’t just ask for payment; we provide clear paths for equipment return or full-value reimbursement, which often triggers a response where standard billing notices fail.

2. Is your process compliant with the 2026 TCPA “Stop-All” rules?

Yes. Our platform uses centralized consent management. If a subscriber opts out of a text, our system immediately updates their voice and email profile across our entire network to ensure 100% compliance.

3. Do you handle B2B telecom disputes?

Absolutely. We specialize in high-value contract disputes for wholesale bandwidth, tower leasing, and commercial managed services.


Ready to Reclaim Your Revenue?

Don’t let unpaid gear and ghost accounts stall your network expansion. Partner with a recovery team that speaks the language of telecom.

Contact Nexa Today

Filed Under: Debt Recovery

Lawn Care & Landscaping Debt Recovery

blank

Stop Financing Your Customers’ Backyards. It’s Time to Mow Down Your Bad Debt.

The “Sweat Equity” Trap.
You are in a labor-intensive industry. You pay for fuel, equipment, mulch, and payroll upfront. When a customer doesn’t pay, you haven’t just lost profit—you have physically paid for the privilege of working on their property.

In the Green Industry, there is a massive divide between “Mow & Blow” maintenance and “Hardscape Design/Build.” Each requires a different recovery strategy.

  • Residential clients often treat the final invoices of the season (October/November) as “optional,” ghosting you until Spring.

  • Commercial clients (HOAs and Property Managers) use you as a bank, stretching Net-30 terms into Net-90.

You need a collection partner who understands that a lien works for a $20,000 patio, but a polite nudge works better for a $50 lawn cut.


The 3 “Weeds” Choking Your Cash Flow (And How to Pull Them)

1. The “End-of-Season” Ghost
This is the most common metric killer in lawn care. Customers pay diligently from April to August. Then, as the grass goes dormant, so does their communication. They skip the final two invoices and the leaf cleanup bill.

  • The Nexa Fix: We use a Step 1 (Fixed-Fee) campaign timed for the “Winter Gap.” We send diplomatic reminders in your name during the off-season. It signals that you are professional and paying attention, ensuring they clear the balance before they dare call you for Spring cleanup.

2. The HOA & Property Management “Shuffle”
Commercial contracts are lucrative but dangerous. Property Managers change, boards vote on budgets, and your invoice gets lost in the shuffle.

  • The Nexa Fix: We bypass the “help desk.” Our B2B commercial collectors know how to navigate the corporate hierarchy of management companies to find the person who actually cuts the check (the Treasurer or Controller).

3. The Hardscape “Workmanship” Dispute
You built a $15,000 paver patio. The client pays the deposit, but refuses the final $5,000 draw because “one stone looks slightly different.”

  • The Nexa Fix: This isn’t just debt; it’s a contract dispute. We document the signed completion certificate and photos of the finished work. We effectively strip away their excuse, forcing them to pay or face a hit to their credit that could jeopardize their home equity.

Serving Lawn Care Companies Nationwide: Contact us


Q&A: Protecting Your Turf

Q: Will sending a residential client to collections ruin my reputation in the neighborhood?

A: Not if you use the “Soft Touch” method. Neighborhood word-of-mouth is your lifeblood. That is why we recommend Step 1 (Fixed Fee) for residential accounts under $500. It utilizes polite letters and emails that look like a billing office escalation, not a scary debt collector. You recover the funds without becoming the villain on the neighborhood Nextdoor page.

Q: Can’t I just file a Mechanic’s Lien?

A: For hardscaping (construction), yes—but deadlines are tight (often 60-90 days from last work). For maintenance (mowing), most states do not allow liens. If you miss the lien window, or if the debt is for maintenance, you need a collection agency to enforce the contract personally against the homeowner.

Q: How do we stop “Route Density” loss?

A: When you fire a non-paying customer, you lose route density. By recovering the funds diplomatically using a third party, you often save the customer. They pay the debt to save face, and you can keep them on the route (on a pre-pay basis only).


Pricing & Services: The “Seasonal” Waterfall

We structure our fees so you don’t lose your margin on small residential accounts.
blank

Step 1: The “Off-Season” Nudge (Fixed Fee)

  • Cost: ~$15 per account.

  • Best For: Residential balances $50–$400; End-of-season ghosts.

  • Strategy: Five contacts (Email/Mail/SMS) sent in your name. It looks like your office manager is just being thorough.

  • Benefit: You keep 100% of the recovery. Perfect for cleaning up the ledger in January.

Step 2: The “Service Suspension” Demand (Fixed Fee)

  • Cost: ~$15 per account.

  • Best For: Clients 90+ days past due who are ignoring calls.

  • Strategy: Formal demand sent in the Agency Name.

  • Benefit: Signals that their credit score is now at risk.

Step 3: Contingency Collections (Commercial & Construction)

  • Cost: ~33% – 40% (No Recovery = No Fee).

  • Best For: HOA defaults, Commercial Property Managers, High-dollar Hardscape disputes.

  • Strategy: Skip-tracing owners, locating assets, and intensive negotiation.

Step 4: Legal Action

  • Cost: ~40% – 50% Contingency.

  • Best For: Large commercial contracts or hardscape projects >$2,500 where a lien failed or wasn’t filed.


Recent Results: Green Industry Recovery

  • Landscape Design Firm (Colorado) – The “Change Order” War

    • The Scenario: A homeowner approved $12,000 in “verbal” change orders on a retaining wall project, then refused to pay the final bill, citing “budget overruns.”

    • The Solution: We placed the account in Step 3. Our team collected the text message history and site logs proving the homeowner authorized the changes.

    • The Result: Faced with the documented proof and imminent credit reporting, the homeowner settled for $10,500 (87% of the claim) within 20 days.

  • Lawn Maintenance Franchise (Florida) – The HOA Lag

    • The Scenario: A Property Management company fell 120 days behind on 15 different HOA accounts, totaling $38,000 in unpaid maintenance fees.

    • The Solution: We bypassed the property manager and sent formal demands to the Board of Directors of each HOA via Step 2 (Agency Demand).

    • The Result: The HOA Boards, unaware bills weren’t being paid, pressured the management company. Full payment of $38,000 was released within 2 weeks.

  • Independent Mower (Ohio) – Winter Cleanup

    • The Scenario: 45 residential customers owed small balances ($40–$150) from the end of the season. The total was only $4,500, but it was pure profit.

    • The Solution: A bulk Step 1 campaign in February.

    • The Result: Recovered $3,100 directly to the owner. The cost was roughly $675 in flat fees. He recovered his winter cash flow without making a single phone call.


Ready to Prune Your Ledger?

Stop letting unpaid invoices eat your profits. Whether it’s a $50 mow or a $50,000 commercial contract, NexaCollect helps you get paid for the work you’ve already done.

Need a Collection Agency? Contact us

Let your office manager focus on routing and scheduling, not chasing checks.

Filed Under: Debt Recovery

Debt Collection for Pest Control Companies: Turn Late Payers into Cash Flow

Pest control is a $25B+ industry with thin margins and heavy AR. Learn why pest control invoices go past 60–90 days, what it costs your business, and how a pest-control–savvy collection agency can recover more while protecting your brand.

Pest Control

Pest control is a serious business: recurring service routes, emergency call-outs, seasonal spikes, and tight margins. On paper, revenue often looks great. In reality, too much of that money is stuck in Accounts Receivable.

If your aging report keeps growing, if “we’ll pay next month” has become a familiar phrase, and if staff dread payment calls, you’ve got a collections problem—not a service problem.

This page walks through real AR issues pest control companies face and how a focused collections strategy can turn old invoices into actual cash flow.

Contact us if you are looking for a collection agency with experience in your industry.


The AR headaches pest control owners know too well

Pest control receivables have their own personality. Common pain points:

  • Recurring plans with broken auto-pay
    Clients sign up for monthly or quarterly plans on a card, then the card expires or is declined. Nobody notices for a few cycles, and by the time you catch it, the balance is big and awkward to chase.

  • “Emergency” one-time jobs that never get paid
    Wasp nests, rodents, bed bugs, termites… you rush out same day. The customer promises they’ll “sort the payment later.” Later never comes.

  • Property managers and HOAs that pay on their own schedule
    You service multiple units or common areas. The decision-maker isn’t on-site, and invoices sit in someone’s inbox for 60–90+ days.

  • Seasonal overload
    Spring and summer crush your team. Trucks are full, phones are ringing, and AR follow-up falls to the bottom of the to-do list.

  • Callbacks and goodwill visits
    Techs do extra work “to keep the customer happy,” but it’s not documented or billed clearly. When you try to collect, the customer claims they already paid enough.

  • Chargebacks and “I didn’t approve that” complaints
    Even when you charge up front, customers sometimes dispute the charge weeks later—especially if they forgot about a recurring plan.

Every one of these situations turns into slow pay, partial pay, or no pay at all unless you have a clear AR and collections process.


Why in-house collections usually stall

Your office staff are great at scheduling routes, calming upset customers, and supporting technicians. Expecting them to also act as trained collectors is asking too much.

Typical in-house roadblocks:

  • They feel uncomfortable being firm.
    It’s hard to push for payment and then book the same person’s next service with a smile.

  • They don’t have a structured follow-up ladder.
    Calls and emails happen randomly: when someone remembers, not on a system.

  • They get swamped in busy season.
    When the phones are crazy, no one has time to sit quietly and work a 60–90 day aging list.

  • They don’t know the legal limits.
    Without proper training, staff may say the wrong thing on a call or send a letter that doesn’t meet state or federal requirements.

Result: accounts age, the “past due” column grows, and you quietly accept write-offs that shouldn’t have been lost.


Why pest control debt is actually recoverable (if you act early)

The good news: compared to many other industries, pest control debt is reasonably collectible when it’s handled correctly and early.

Reasons recovery can be strong:

  • Service is tied to health, comfort, and safety—people don’t want to lose it.

  • You often have signed agreements or at least clear work orders.

  • Balances are usually in a range where a payment plan is realistic, not impossible.

The catch: every month an invoice sits unpaid, the odds of recovery drop. By the time a bill is 6–12 months old, most owners quietly assume it’s gone.

That’s why many successful pest control companies move accounts to collections around 60–90 days past due, instead of waiting until everyone has forgotten what the job was.


How a pest-control–savvy collection agency approaches your accounts

A collection agency that understands pest control doesn’t treat you like a random utility bill. They know the stories and objections your customers will raise.

They typically:

  • Segment your accounts

    • Residential vs commercial vs property management

    • Recurring plan customers vs one-time jobs

    • High-risk patterns (serial late payers, chronic complainers)

  • Start with a diplomatic but firm tone

    • Reference the agreement, visits completed, and past communication

    • Explain what’s owed in simple terms

    • Offer realistic payment options when appropriate

  • Use professional tools and compliance know-how

    • Call strategies that respect call-time limits and disclosure rules

    • Proper letter language and timelines based on federal and state laws

    • Systematic tracking of contact attempts and responses

  • Escalate only when needed

    • Some accounts respond to a couple of well-crafted letters

    • Others require multiple contacts, possible payment plans, and—in rare cases—stronger measures such as negative credit reporting or legal escalation (based on your preferences and current regulations)

The goal is to recover money while protecting your brand in the neighborhoods you serve.


Simple placement rules that work well for pest control

You don’t need a complicated policy. The key is to stop deciding one account at a time and let clear rules guide what goes to collections.

Here’s a starter framework you can adapt:

1. Residential customers

  • Balance $150 or higher

  • No payment in 60–75 days

  • At least 2–3 reminders sent (statement, text, email or call)

→ Eligible to send to collections.

2. Commercial / property management

  • Balance $500 or higher

  • Invoice 60–90+ days past due

  • One broken promise or repeated “we’ll pay next month”

→ Management review, then placement with a collection agency if still unpaid.

3. Small, old balances

  • Balance $50–150

  • Age 120 days or more

→ Decide to batch them once or twice a year to collections or write them off and clean your books. Stop letting them clutter your aging report forever.

Write these rules down. Share them with your office manager and bookkeeper. Once everyone knows the rules, decisions stop being emotional and start being automatic.


Tips to tighten your AR before accounts ever reach collections

Collections should be the final step, not the only step. A few front-end tweaks can dramatically reduce how many accounts go bad:

  • Get something up front.
    Ask for a card or partial payment before you roll a truck—especially for one-time emergency jobs.

  • Put recurring terms in writing.
    Spell out visit frequency, minimum term, and cancellation policy for maintenance plans.

  • Use reminders before each visit.
    Texts or emails reduce no-shows and keep your brand fresh in the customer’s mind when the bill arrives.

  • Train techs to note exceptions.
    If extra work was done, the customer was unhappy, or there was a special promise, make sure that lands in your job notes so AR and collections teams aren’t blindsided later.

The tighter your front end, the stronger your back-end collections will be.


How we help pest control companies get their money in the door

Our focus is simple: we help pest control companies turn old invoices into collected cash without wrecking relationships.

Typically, this looks like:

  • Reviewing your current aging report and AR process

  • Identifying where invoices are getting stuck (residential, commercial, HOAs, seasonal surges)

  • Helping you set clear placement rules (who gets sent, when, and at what balance)

  • Connecting you with experienced collection services that already know pest control accounts and how to handle them professionally

You keep doing what you do best—keeping homes and businesses pest-free.

With a better AR and collection strategy behind you, your cash flow can finally start reflecting all the work your technicians already did.

Image Source:
Senior Airman Austin Harvill -commons.wikimedia.org/wiki/File:
Pestering_pests,_Entomology_sprays_down_threats_150323-F-XD389-010.jpg

Filed Under: Debt Recovery

  • « Go to Previous Page
  • Page 1
  • Interim pages omitted …
  • Page 48
  • Page 49
  • Page 50
  • Page 51
  • Page 52
  • Interim pages omitted …
  • Page 55
  • Go to Next Page »

Primary Sidebar


accounts receivable

Need a Collection Agency?
Kindly fill this form.
We’ll get in touch with you

    Please prove you are human by selecting the car.

    Compliance & Security

    • SOC 2 Type II Certified: Third-party audited data security and strict privacy controls.

    • HIPAA Compliant: Secure, legal processing of medical and municipal EMS accounts.

    • PCI-DSS Level 1: Highest tier of data encryption for secure payment processing.

    • FDCPA & FCRA Aligned: Full legal adherence to federal consumer protection laws.

    Recent Posts

    • Why Dental Patients Dispute Bills: The Nexa Collections Dental Account Dispute Index
    • 2027 Commercial Collections Benchmark: U.S. Late Payments, AR Risk and B2B Collection Trends
    • Bulk Account Placement: What a Collection Agency Actually Needs From You
    • Nationwide Debt Collection Agency Serving U.S. Cities
    • Chula Vista Collection Agency for Medical, B2B, Schools & Business Debt
    • Corpus Christi Collection Agency: Itemized Bill Rules for Practices
    • Riverside Collection Agency | For Logistics, Medical, Schools & Business Recovery
    • Collection Agency for Large Balances: High-Value B2B Debt Recovery

    Featured Posts

    • Achieving Maximum Benefit from a Sales Presentation
    • Empathetic Medical Debt Collection Agency Services
    • Can I Hire Multiple Collection Agencies at One Time?

    Copyright © 2026 NEXACOLLECT.COM | This content is provided for general informational purposes only and should not be considered legal advice. Collection laws and requirements may vary by state, account type, documentation, debtor status, and specific facts. Please consult qualified legal counsel for guidance regarding your particular situation. Nexa and its authorized collection partners service accounts in accordance with applicable federal and state collection requirements. Visit our home page to know more about us.

    X
    Need a Collection Agency?
    Contact Us