• Skip to main content
  • Skip to primary sidebar

Nexa Collections

  • Home
  • Serving
    • Medical
    • Dental
    • Small Business
    • Large Business
    • Commercial Collections
    • Government
    • Utilities
    • Fitness Clubs
    • Schools
    • Senior Care Facility
  • Contact Us
    • About us
    • Cost

Debt Recovery

2027 Commercial Collections Benchmark: U.S. Late Payments, AR Risk and B2B Collection Trends

The 2027 Commercial Collections Benchmark is Nexa Collections’ annual reference report tracking U.S. B2B payment behavior, overdue receivables, payment terms, accounts-receivable risk and commercial collection trends using the latest available industry datasets.

Quick answer: U.S. businesses head into 2027 with a quieter problem than “customers pay late.” Customers are increasingly paying on longer terms, often terms nobody formally agreed to. Fifty-nine percent of small businesses now carry invoices 30+ days overdue (up from 47% a year earlier), small businesses wait an average of 29.3 days to get paid, and credit managers report net-30 customers drifting to 45 days. The businesses best positioned for 2027 will watch payment behavior, not just invoice age, and set written rules for when follow-up becomes escalation.
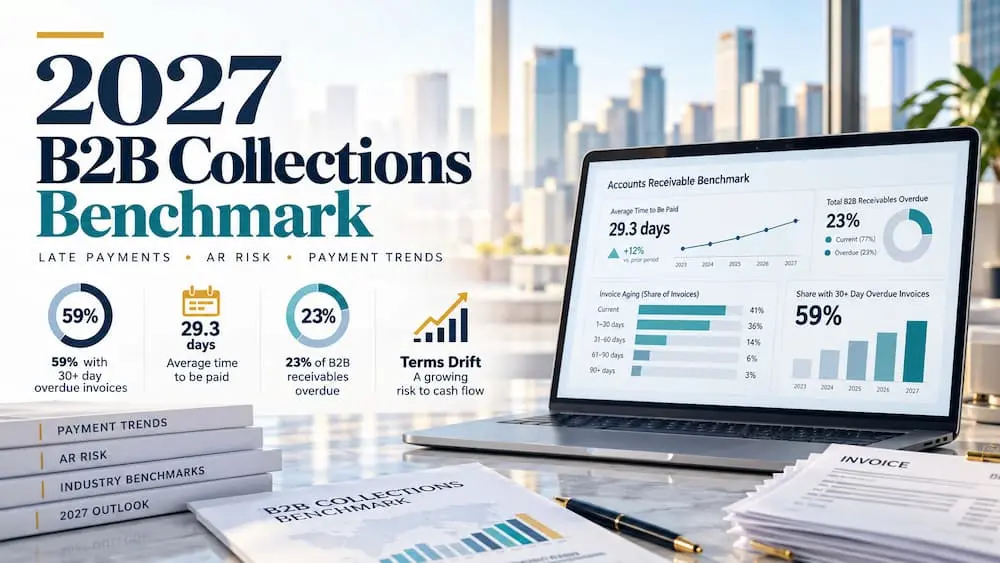
2027 B2B collections benchmark covering U.S. late payments, payment terms, overdue receivables, AR risk, cash-flow trends and collection strategies.

Here is the oddest pair of numbers in this year’s payment data.

In the June quarter of 2026, U.S. small businesses got paid less late: an average of 8.5 days past due, down half a day. Yet they waited longer for their money: 29.3 days from invoice to payment, up from 28.6.

Both can be true because the due dates moved. Xero, whose transaction data produced those figures, reads the gap as businesses extending their invoice terms. Credit managers describe the same thing from the other side of the desk: customers who used to pay in 30 days now taking 45, sometimes without asking.

That is the story of this benchmark. Late payment in 2026 isn’t only showing up as delinquency. It’s showing up as drift, and drift doesn’t set off alarms on a standard aging report.

Delinquency Window Average National Collectability Rate Asset Depreciation Velocity Recommended Resolution Track
Current to 30 Days Past Due 93% – 95% Baseline (Normal credit cycle) In-house accounts receivable / polite automated reminders
60 to 90 Days Past Due 70% – 73% ~10% loss in value per 30 days Step 1 Diplomatic Resolution ($15 Fixed Fee per account)
90 to 180 Days Past Due 50% – 55% Rapid decline; debtor solvency risks surge Step 2 Final Fixed Notice ($15) >> Contingency (30%–40%)
180 to 365 Days Past Due 25% – 30% Severe risk; corporate asset dissipation likely Contingency Placement (40%–50%) with asset investigation
365+ Days (1+ Year Past Due) Under 10% Critical write-off threshold Legal review / judgment enforcement / bad debt write-off

This edition brings four independent datasets (Intuit QuickBooks, Xero, Atradius and the National Association of Credit Management) into one practical view of the receivables risk U.S. businesses are carrying into 2027. Because 2027 hasn’t started yet, it uses the newest 2026 data as the baseline. Nexa Collections will update it as 2027 data arrives.


The 2027 Benchmark at a Glance

Indicator Latest figure Population Source
Small businesses with invoices 30+ days overdue 59% (47% a year earlier) U.S. small businesses QuickBooks, 2026
Average owed to businesses waiting on unpaid invoices $17,700 (about $17,500 a year earlier) U.S. small businesses QuickBooks, 2026
Businesses with 20%+ of invoices 30+ days overdue 22% U.S. small businesses QuickBooks, 2026
Overdue invoices: net-30 vs. immediate-payment businesses 55% vs. 26% U.S. small businesses QuickBooks, 2026
Owners who say one late payment made payroll or bills harder to cover 39% U.S. small businesses QuickBooks, 2026
Average time to be paid, June quarter 2026 29.3 days (28.6 prior quarter) U.S. small businesses (transaction data) Xero, 2026
Average days paid late, June quarter 2026 8.5 days (down 0.5) U.S. small businesses (transaction data) Xero, 2026
Share of B2B sales made on credit 45% U.S. businesses Atradius, 2026
Firms experiencing late B2B payments About 7 in 10 North America (U.S., Canada, Mexico) Atradius, 2026
Share of B2B receivables overdue 23% North America Atradius, 2026
Overdue B2B invoices paid within 30 days of due date 71% North America Atradius, 2026
NACM Credit Managers’ Index, August 2026 54.6 (down 1.8) U.S. credit professionals NACM, 2026

These studies measure different populations with different methods. Read them side by side, not added together. There is no single “national late-payment rate,” and this table doesn’t try to create one.

Finding 1: “Late” Is Quietly Being Rewritten as “Terms”

Three independent sources point in the same direction.

Transaction data (Xero). Days paid late improved every month of the June quarter (8.7 in April, 8.5 in May, 8.3 in June), while total time to be paid rose to 29.3 days, above the dataset’s historical average of 28.9. Xero’s own reading: small businesses, on average, extended their invoice payment terms.

Survey data (Atradius). Most North American suppliers kept payment terms unchanged in recent months. Where terms did change, they got longer more often than shorter, particularly among trade companies and businesses in the United States and Mexico.

Credit-desk reports (NACM). NACM’s September 2026 reporting describes customers asking for extended terms to hold on to cash, and some simply moving themselves from 30-day to 45-day payment without asking. NACM economist Amy Crews Cutts described these customers as “deciding to unilaterally rewrite the contract.”
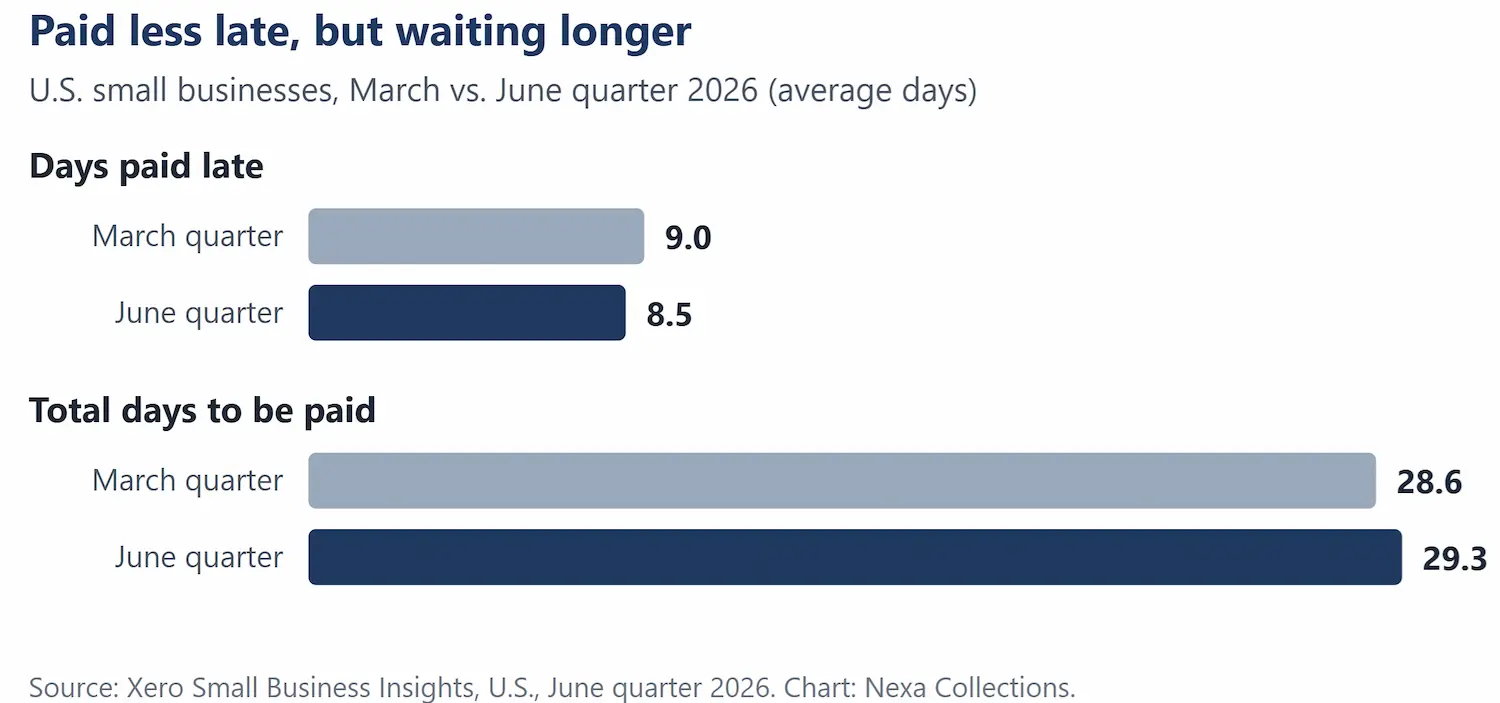
Paid less late, but waiting longer

Why this matters for collections: most aging reports measure lateness against the due date. If the effective due date slides from day 30 to day 45, an account can look “current” while your cash conversion cycle gets two weeks longer. That’s why this benchmark adds a metric many AR teams don’t track: terms drift, the average days from invoice to payment compared with the terms in the contract. (See the metrics table below.)

Finding 2: More Businesses Are Waiting, Not for Bigger Balances

QuickBooks’ 2026 Small Business Late Payments Report found that 59% of small businesses have at least some invoices 30 or more days overdue, up from 47% a year earlier. That’s a 12-point jump in twelve months.

The average amount owed barely moved: $17,700, versus about $17,500 the year before.

Read together, those numbers say the problem got wider, not deeper. Far more businesses are waiting on money than a year ago, even though the typical balance is about the same.

For a meaningful minority it got deeper too. 22% of businesses say at least one in five of their invoices is 30+ days overdue. At that level you’re not dealing with a few stragglers anymore. You’re dealing with a credit policy, a customer mix or a follow-up process that isn’t working.

One clarification worth making: 59% doesn’t mean 59% of invoices are late. It means 59% of businesses have at least one invoice that has crossed the 30-day overdue mark.

Finding 3: It Doesn’t Take a Big Miss to Break a Month

  • 39% of owners say a single late payment made it harder to cover payroll or bills in the past year.
  • 27% say a missed payment under $5,000 was enough to cause that strain.
  • 12% say a payment under $1,000 was enough.

Then the problem travels. 42% of businesses say outside pressures delayed payments they owed to their own contractors, suppliers or vendors over the last quarter. That rises to 53% among businesses with overdue invoices, versus 26% among those without. And among businesses with invoices 30+ days overdue, nearly one in four (24%) point specifically to delayed revenue as the reason they couldn’t pay their own vendors on time.

Businesses with overdue invoices are also leaning harder on credit cards: 38% say they’ve become more reliant on them over the past year, compared with 21% of businesses without overdue invoices.

That’s the payment chain in plain terms. A late customer becomes a late vendor payment, which becomes someone else’s late customer, often financed at credit-card rates along the way. A $2,000 invoice may be immaterial to your customer and critical to you, so collection priority should reflect your exposure, not just the invoice size.

Finding 4: Payment Terms Are the Biggest Lever You Already Control

QuickBooks’ data draws a clear line between terms and trouble.

Businesses on net-30 terms Businesses requiring immediate payment
Report overdue invoices 55% 26%

Looked at from the other direction, 64% of businesses with no overdue invoices require immediate payment, compared with 34% of businesses that do have overdue invoices. QuickBooks itself cautions that terms don’t explain every late invoice, and some industries and client relationships genuinely require credit.

This isn’t an argument for putting every customer on prepay. Trade credit wins deals, supports larger orders and builds long relationships. It’s an argument for treating credit as a decision rather than a default:

  • New customers: start with shorter terms or a lower limit, and extend as payment history earns it.
  • Large or unusual orders: consider a deposit, partial prepayment or progress billing.
  • Existing customers who start slipping: review limits before shipping more. Credit managers quoted by NACM describe approving new terms only with conditions attached, such as partial prepayment, cash in advance or a standby letter of credit.
  • Contract terms: state due dates plainly and, where your agreements and applicable law allow, spell out late fees up front rather than improvising them later.

Collection risk starts the day credit is extended, not the day an invoice turns 90.

Finding 5: B2B Late Payment Is Common. The Real Risk Is the Tail.

Atradius’ 2026 Payment Practices Barometer for North America, a survey of 662 businesses in the U.S., Canada and Mexico, shows how routine late payment has become in B2B trade:

  • U.S. businesses conduct about 45% of their B2B sales on credit.
  • Across the region, about seven in ten firms experience late B2B payments.
  • Overdue invoices make up an average of 23% of B2B receivables.

But look at when those overdue invoices actually get paid.
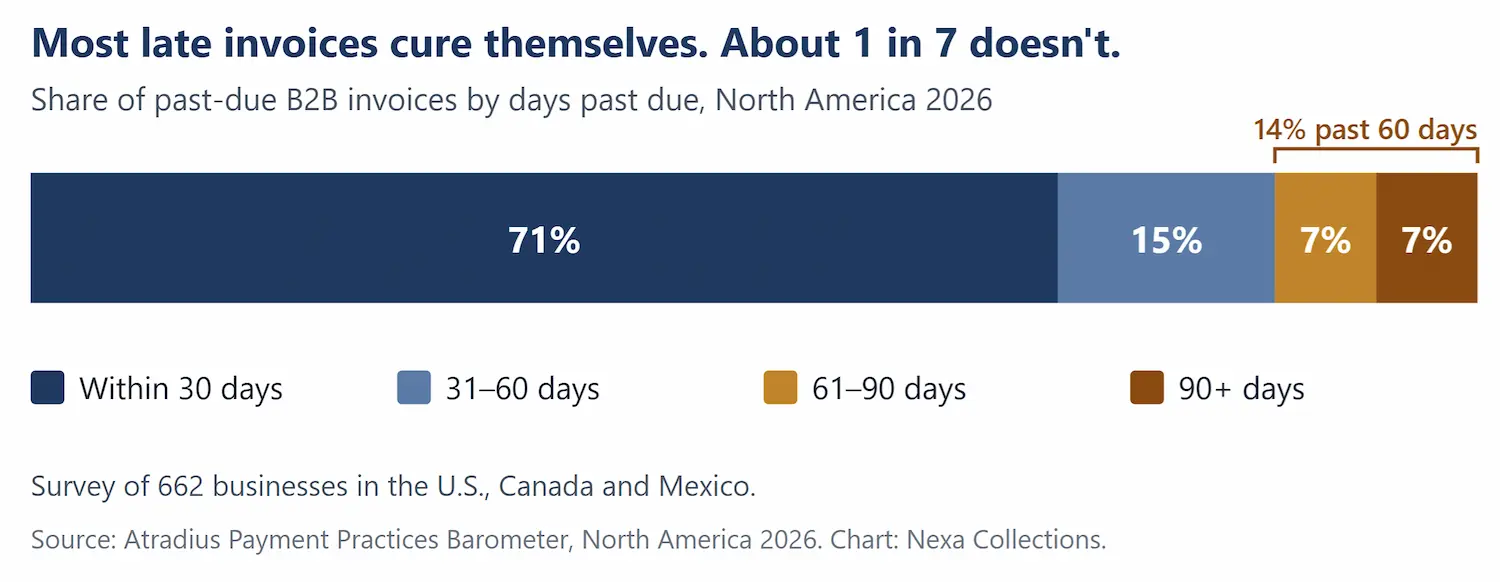
Share of past-due B2B invoices by days past due

71% of past-due invoices are settled within 30 days of the due date. Another 15% land at 31 to 60 days. The remaining 14% stretch past 60 days, and half of those go beyond 90.

That’s the core insight for collection strategy: most late invoices cure themselves. The job isn’t to escalate every slow payer. It’s to spot the roughly one in seven that won’t cure, early, while contact details are current and the customer is still operating.

Why do customers pay late? Customer cash flow leads by a wide margin (49% of respondents), followed by banking delays (36%), complex payment processes (17%) and internal approval delays (16%). Atradius attributes delays mainly to liquidity rather than disputes or administrative errors.

Bad debt remains broadly contained. Nearly half of North American suppliers report bad debt below 1% of receivables, and fewer than one in four report levels above 2%. Notably, Atradius links bad debt more often to customers becoming inactive or unreachable than to long-running nonpayment of large invoices, which is a strong argument for acting while a customer still picks up the phone.

What 1% can cost (illustrative): on $10 million in annual credit sales, 1% bad debt is $100,000. At a 10% net margin, replacing that profit takes roughly $1 million in new revenue.

Finding 6: Stable Headlines, Fragile Underneath

On the surface, the outlook looks calm. Most North American businesses in the Atradius survey expect customer payment behavior to hold steady, two in five expect faster payments, and nearly half expect margins to improve.

Underneath the surface:

  • 62% expect insolvency risk to stay elevated, and 27% expect it to rise further.
  • Around one-third of suppliers already report reduced cash availability.
  • Economic slowdown tops the list of expected risks to payment behavior, followed by inflation and cost pressures, then interest rates.

Atradius’ own analyst framed it this way: payment performance and financial confidence are moving in different directions, and many companies are managing through pressure rather than coming out of it.

NACM’s Credit Managers’ Index tells a similar two-sided story. The combined index fell 1.8 points to 54.6 in August 2026. That’s still above the 50 line that separates expansion from contraction, but the drop was driven by a sharp swing in dollar sales that NACM ties to customer cash-flow strain.

Meanwhile, Xero recorded 4.0% year-over-year sales growth for U.S. small businesses in the June quarter. Sales are up. Cash is slower. Revenue growth and cash-flow improvement are not the same thing.


Why the Aging Report Doesn’t Tell the Whole Story

Two invoices. Both 75 days past due.

Invoice A: The customer responded right away. A missing PO number held up approval, the paperwork was corrected, and accounts payable confirmed a payment date.

Invoice B: The customer has promised payment four times. Every date has passed. Calls now go to voicemail. There’s no dispute.

Your aging report shows them identically. Their risk is nothing alike.

A credit manager quoted by NACM draws the key distinction: first work out whether you’re looking at a cash problem or a cash-management problem. A cash-management problem (an invoice routed to the wrong inbox, turnover in accounts payable, a missing PO) is usually fixed with better paperwork. A genuine cash problem calls for faster, more protective action.

What you see Likely cause Right first move
No acknowledgment, no response to billing Wrong contact, lost invoice, AP turnover Re-verify the contact; resend with PO and supporting documents
Customer raises a specific objection Genuine dispute Investigate, document, and resolve or credit quickly
Customer acknowledges the balance and asks for time Temporary cash pressure Written payment arrangement; hold on new credit until it’s current
Broken promises, fading contact, no dispute Serious financial distress Escalate now, using a documented plan for a client who won’t pay, rather than waiting for the next aging bucket

8 Early-Warning Signals to Watch in 2027

  • Promise dates keep moving. “Friday” becomes “next week” becomes “end of the month.” (Here’s how to handle the most common debtor excuses.)
  • A reliable payer starts stretching. A customer who always paid in 20 days and now pays in 45 deserves more attention than one who has always paid at 45.
  • Requests for longer terms, or longer terms simply taken without asking.
  • Unplanned partial payments from a customer who used to pay in full.
  • Several invoices aging at once from the same account.
  • New orders keep arriving while old balances sit unpaid, quietly growing your exposure.
  • Accounts-payable contacts go quiet: unanswered emails, staff turnover, disconnected numbers.
  • “We’ll pay when we get paid.” Credit managers report hearing this more often, even when the contract says net-30. It can signal that your customer’s receivables problem is becoming yours.

The 30-60-90-120 Commercial Escalation Framework

There’s no single day when every commercial account should go to collections. Contracts, balances, industries and relationships differ. What every business does need is written escalation points, so accounts move on purpose instead of aging by default.

Days past due Objective What to do Decision at the end of this stage
1–30 Remove friction Confirm the invoice was received, the PO and billing details are correct, documentation is complete and the right AP contact has it; get a committed payment date Is this administrative or financial?
31–60 Diagnose behavior Log every contact, promise date, partial payment, extension request and dispute Is the customer engaging or drifting?
61–90 Formal risk review Review contract terms, payment history, other open invoices, business status and, where appropriate, bankruptcy filings; decide whether to hold new credit Is internal effort still producing progress?
91–120 Decide and escalate Options include intensified internal follow-up, a written payment arrangement, settlement discussions, third-party commercial collections placement, or attorney review of suitable accounts through the legal collection process Which path fits the facts of this account?
120+ No drifting Give every account a documented status: payment plan, disputed, third-party collection, legal review, bankruptcy or write-off Does every old balance have an owner and a status?

“Still in AR” is not a status. If you’re weighing whether to keep chasing internally or hand accounts off, our comparison of in-house collections vs. an agency walks through the trade-offs.

Why the clock matters: widely cited Commercial Law League of America figures put the collectability of commercial debt at roughly 73% at 90 days, about 50% at 180 days and about 25% at one year. Treat those as a rule of thumb rather than a promise, since documentation, debtor solvency and whether the business is still operating all matter, but the direction is consistent: time rarely helps. Legal time limits can also eventually apply; see our guide to statutes of limitations on debt.


7 Accounts Receivable Metrics Worth Tracking in 2027

Metric What it tells you Warning sign
Past-due % by aging bucket Where risk is accumulating A growing share in the 60+ and 90+ buckets
Days Sales Outstanding (DSO) How quickly sales turn into cash Rising DSO not explained by seasonality or a change in customer mix
Terms drift Average days from invoice to payment vs. contract terms Customers paying “on time” to a due date that keeps moving
Promise-to-pay kept rate Share of payment promises actually honored A falling rate, often visible before write-offs rise
Broken promises before escalation How many “next week”s your team accepts before acting Nobody knows the answer, so measure it
Time to escalation Days from due date to a real escalation decision Old accounts with no decision attached
Bad debt % of credit sales, plus recovery by age at placement What ultimately becomes uncollectible, and when referral works best for your accounts Bad debt creeping up, or recoveries falling on late placements

Why There’s No Honest “Average Commercial Recovery Rate”

“What percentage will you recover?” is the question businesses ask collection agencies most often. There’s no credible universal answer. Results depend on account age, balance, documentation quality, whether the debtor is solvent and still operating, contactability, dispute status, prior collection attempts, bankruptcy, industry and jurisdiction.

A portfolio of 45-day-old invoices from active companies can’t fairly be compared with two-year-old accounts from businesses that may have closed. Whenever you see a recovery rate quoted, ask what kinds of accounts produced it. For how pricing typically works, see our breakdown of collection agency fees.


Nexa’s 2027 Watchlist

The trends we think credit and AR teams should watch most closely next year, and the ones we plan to revisit in future editions:

  • Terms drift. Are customers taking longer before invoices are even “due”?
  • “Pay when paid.” Is your payment being tied to your customer’s own collections?
  • Good customers going slow. Are historically reliable accounts starting to stretch?
  • The tail. Is the share of overdue receivables past 60 and 90 days growing?
  • Unreachable customers. Are once-active accounts going silent, the pattern most linked to bad debt?
  • Time to escalation. Are you deciding sooner, or letting old balances pile up?

Methodology and Limitations

The 2027 Nexa Collections Commercial Collections Benchmark is published ahead of calendar year 2027 and uses the latest available 2026 data as its baseline.

  • Intuit QuickBooks, 2026 Small Business Late Payments Report. Draws on QuickBooks Small Business Insights, an ongoing quarterly survey of roughly 5,000 small-business owners and decision-makers, and an online survey of 1,305 U.S. business owners (0 to 250 employees) conducted in December 2025.
  • Xero Small Business Insights, U.S., June quarter 2026. Aggregated, anonymized transaction data from Xero small-business subscribers. Time to be paid runs from invoice to payment; late payment compares the payment date with the invoice due date.
  • Atradius Payment Practices Barometer, North America 2026. Online survey of 662 businesses across the U.S., Canada and Mexico, conducted between late Q2 and mid-Q3 2026. Most figures are regional (North America), not U.S.-only; the 45% credit-sales share is U.S.-specific. Atradius updated its survey panel for this edition and notes that direct comparisons with prior years aren’t possible.
  • NACM Credit Managers’ Index, August 2026. Monthly survey of U.S. credit and collection professionals rating favorable and unfavorable business factors; readings above 50 indicate expansion.

Because these sources use different populations, definitions and methods, their percentages shouldn’t be added together or treated as one sample. This benchmark is an industry reference and risk-management resource. It isn’t a prediction about any individual customer or portfolio, and it isn’t legal advice.


Commercial Credit & Collection: Plain-English Legal Reference Rules

  • CLLA Depreciation Principle (Commercial Law League of America): Commercial accounts receivable depreciate exponentially after the 90-day mark. Delaying third-party intervention past 120 days cuts recovery likelihood in half, as corporate debtors prioritize vendors applying active collection pressure over silent creditors.

  • Uniform Commercial Code § 2-725 (Sale of Goods): A 4-year statute of limitations generally governs commercial contracts for goods. Waiting for informal promises to pay can cause claims to approach expiration under state-specific commercial code deadlines.

  • Account Stated Doctrine: Sending regular monthly statements with clear dispute deadlines creates an enforceable “account stated” under common law. If the business debtor retains invoices without written objection, courts presume the accuracy of the debt, defeating late-stage balance disputes.

  • Preference Claim Safeguards (11 U.S.C. § 547): When collecting from financially distressed businesses, third-party recovery strategies must structure settlements to fit within standard business terms or contemporaneous exchanges, protecting funds from bankruptcy trustee 90-day clawbacks.


Frequently Asked Questions

What percentage of U.S. small businesses have overdue invoices?

According to Intuit QuickBooks’ 2026 Small Business Late Payments Report, 59% of small businesses have at least some invoices 30 or more days overdue, up from 47% a year earlier. Businesses waiting on unpaid invoices are owed about $17,700 on average, similar to roughly $17,500 the year before.

How long do U.S. small businesses wait to get paid?

Xero Small Business Insights data shows U.S. small businesses waited an average of 29.3 days to be paid in the June quarter of 2026, up from 28.6 days in the March quarter. Late payments actually improved to an average of 8.5 days past due, which Xero interprets as businesses extending their invoice payment terms.

How common are late B2B payments in North America?

Atradius’ 2026 Payment Practices Barometer for North America found that about seven in ten firms across the U.S., Canada and Mexico experience late B2B payments, and overdue invoices make up an average of 23% of B2B receivables. U.S. businesses conduct about 45% of their B2B sales on credit. Most overdue invoices, 71%, are paid within 30 days of the due date.

Why are B2B customers paying invoices late in 2026?

Customer cash flow is the leading reason, cited by 49% of North American suppliers in Atradius’ 2026 survey, followed by banking delays and complex payment or approval processes. Credit managers surveyed by NACM also report more customers requesting extended terms or saying they will pay only after they themselves are paid.

When should an unpaid B2B invoice be sent to collections?

There’s no single age that fits every commercial account. Consider the balance, payment terms, customer history, dispute status, documentation, responsiveness and whether internal follow-up is still producing progress. Many businesses set a formal review point between 60 and 90 days past due. What matters most is having a written escalation policy so accounts don’t age without a decision.

Does commercial debt become harder to collect as it gets older?

Generally, yes. Businesses close, contacts leave, records get harder to find and legal time limits can eventually apply. Widely cited Commercial Law League of America figures put collectability at roughly 73% at 90 days, 50% at 180 days and 25% at one year, though documentation, debtor solvency, disputes and contactability can matter as much as age.


The Bottom Line: Treat Your Aging Report as a Risk Report

No single statistic defines commercial collections going into 2027. What stands out is how consistently the evidence points the same way: more businesses waiting, customers stretching terms, small misses hitting payroll, and calm headlines sitting on top of real liquidity strain.

The strongest credit teams in 2027 won’t necessarily be the ones making the most calls. They’ll be the ones who notice behavior changes first, fix legitimate invoice problems fastest, document every promise, limit new exposure to slipping accounts, and know exactly when routine follow-up becomes formal escalation.

When an invoice goes seriously past due, “How much do they owe us?” stops being the most useful question. The better one is: Why haven’t they paid, what has changed, how much risk are we carrying, and what are we doing next?


About the Nexa Collections Commercial Collections Benchmark

The Nexa Collections Commercial Collections Benchmark is an ongoing research series on U.S. B2B payment behavior, accounts receivable management and commercial debt recovery. This baseline edition uses the latest public 2026 research. Future editions will add new industry data and, where enough anonymized data is available, Nexa portfolio statistics such as recovery by account age, balance size, industry and time to first payment.

Carrying B2B accounts that have stopped moving? Talk to the Nexa Collections commercial team at support@nexacollect.com or +1-844-639-2123.

Sources

  • Intuit QuickBooks, 2026 Small Business Late Payments Report (July 2026)
  • Xero, United States Small Business Insights, June quarter 2026 (July 2026)
  • Atradius, B2B Payment Practices Trends in North America 2026 (September 2026)
  • NACM, Payment delays rise as customers hold tight to cash (September 2026)
  • NACM, Growth cools as customers continue to hold onto cash (September 2026)

Published September 2026 | Baseline edition for 2027 | Built on the latest available 2026 data
Filed Under: Debt Recovery

Bulk Account Placement: What a Collection Agency Actually Needs From You

Submitting 5,000 accounts to collections is not simply the same as submitting five accounts a thousand times.

At scale, data quality, compliance screening, documentation, account validation, and reconciliation become essential parts of the collection process. If these areas are not handled properly, a large placement can quickly lead to duplicate accounts, manual cleanup, unnecessary delays, and increased compliance risk.

A good collection agency should make the entire bulk-placement process smooth and simple for you. Few agencies can also provide API integration directly with your billing or accounting software, allowing accounts and updates to flow automatically between systems.

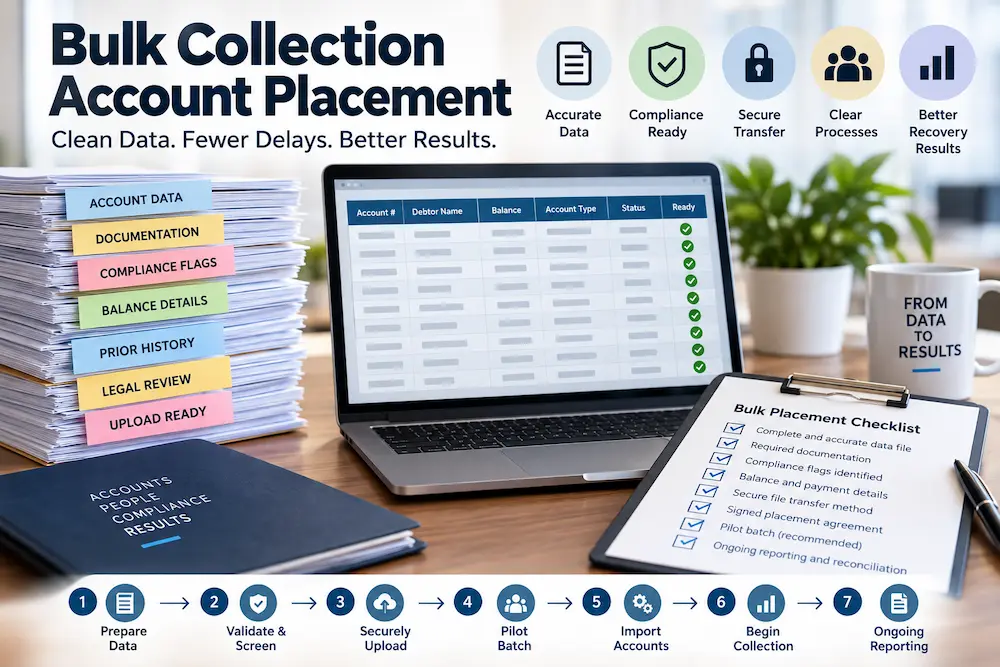
Quick answer: A collection agency handling a large-volume placement needs standardized, machine-readable account data (or a standard excel spreadsheet format), clear consumer-vs-commercial classification, upfront legal and compliance flags (disputes, bankruptcy, attorney representation, statute-of-limitations concerns), available documentation identified in advance, a secure transfer method, a signed placement agreement covering fees and business terms, and a process for reconciling payments the client receives directly. For a new relationship or a new portfolio type, a smaller pilot batch before full-volume placement is the cheapest way to catch problems before they multiply across thousands of accounts.

Ready to place a large portfolio (500 or 5000 accounts?): Contact us

blank

Nexa provides a reputation-safe approach, backed by a comprehensive 50-state collections licensing infrastructure, offering free credit reporting,  free litigation/bankruptcy scrubs, and zero onboarding fees. A 4.85 of Google rating from  2,000+ reviews. Secure – SOC 2 Type II & HIPAA compliant. 

Need a Collection Agency? Contact us


Automated Regulatory Safeguards:

  • Regulation F 7-in-7 Tracking (12 CFR § 1006.14): Automated frequency caps prevent more than 7 telephone calls within 7 rolling days, maintaining lawful tracking even across multiple accounts for the same debtor.

  • Automated Bankruptcy & SCRA Scrubbing: Every batch is screened immediately against federal PACER records and the DoD DMDC database to suppress active bankruptcies and protect active-duty military personnel before contact starts.

  • FCRA Metro 2 Reporting Standards: Standardized batch data furnishing and automated dispute workflows comply fully with federal accuracy mandates and statutory dispute resolution timelines.


Data File Quality and Format

A standardized template or a standard spreadsheet format. Every account needs a unique client or account reference number to prevent duplicate placements and simplify reconciliation later. Core fields should generally include debtor or customer name, business name where applicable, last known address, phone and email, the client’s own reference number, original and current creditor, original and current balance, relevant transaction or invoice dates, date of default, date of last payment, and charge-off date where applicable.

For consumer accounts, provide the itemization behind the current balance, principal, interest, fees, payments, and credits, so the agency isn’t left reconstructing how a number was reached. Sensitive identifiers like date of birth should be included only when legitimately held and actually necessary, not automatically attached to every record. Data should be machine-readable and consistently formatted across every batch; scanned spreadsheets, PDFs used as account lists, and merged cells create exactly the kind of manual cleanup that erases the efficiency bulk placement is supposed to create.


Consumer vs. Commercial Classification

Every account should clearly identify what kind of debt it is: consumer, commercial/B2B, medical, rental or lease, education-related, government or municipal, judgment debt, or another specialized category. This distinction matters more than it might seem, since the applicable notice requirements, communication rules, credit-reporting treatment, and documentation standards can differ substantially between categories. Commercial and consumer accounts in particular follow genuinely different rules, and misclassifying even a portion of a large batch can create compliance exposure across every misclassified account.


Account Documentation and Balance Basis

The agency should know before placement what supporting documentation actually exists, a signed contract, credit application, invoices, purchase orders, delivery confirmation, payment history, a personal guaranty, or a prior settlement agreement, depending on the account type. For large placements, flagging which documents are available directly in the data file is far more efficient than requiring manual inspection of every account.

The client should also identify the principal balance, accrued interest, the contractual interest rate if one applies, late fees or other charges, and the contractual or statutory basis for anything being requested beyond the principal. The agency shouldn’t have to guess how a balance was calculated, and at volume, that guesswork compounds into real errors across the portfolio.


Legal and Compliance Flags

Accounts requiring special handling need to be flagged clearly before placement, not discovered mid-collection. This includes bankruptcy (filed or previously filed), consumer disputes, identity-theft or fraud claims, cease-communication requests, attorney representation, deceased or minor debtors, active litigation, existing judgments, prior settlements, accounts previously placed with another agency, known statute-of-limitations concerns, and any known regulatory complaint. Flagging an account isn’t necessarily a reason to reject it, it’s what allows the agency to route it through the appropriate compliance review before any collection activity begins.

Statute-of-limitations screening shouldn’t rely on the charge-off date alone. Provide the date the obligation arose, the invoice or transaction date, the contract date, the date of default, the date of last payment, the charge-off date, and, where relevant, the governing-law provision in the contract and the state associated with the debtor. Large batches should be systematically screened for potentially time-barred accounts before collection or litigation decisions are made, not assessed account-by-account only when a dispute arises.


Prior Collection Activity and Communication History

The agency should know what’s already happened on an account: a previous collection agency, dates placed and recalled, prior disputes, broken payment arrangements, attorney involvement, previous lawsuits or judgments, and whether the account has previously been furnished to a credit bureau. This prevents duplicated or contradictory collection activity landing on the same debtor from two directions at once.

For consumer portfolios, it also helps to note the source of a phone number or email address, whether the consumer supplied it directly, known preferred language, communication restrictions, and any prior opt-outs from specific electronic channels. This becomes genuinely important once thousands of contact records are transferred at once rather than a handful.


Chain of Title, Industry Requirements, and Data Security

If accounts were sold, purchased, or assigned, chain-of-title documentation should exist before placement, not get reconstructed after a dispute. This includes the purchase and sale agreement, bill of sale, portfolio schedules, and account-level records tying each specific account to the broader portfolio.

Industry-specific pre-collection steps need to be confirmed as already completed, particularly for healthcare, dental, property management, education, utilities, and government accounts. For healthcare accounts specifically, confirm applicable billing and patient-notice requirements were met before placement, and if protected health information is involved, the appropriate Business Associate Agreement and HIPAA safeguards need to already be in place.

Large placements should never move through ordinary email attachments. Use a secure client portal, encrypted SFTP, or an approved API integration instead, with clear access controls, data-retention periods, and breach-notification procedures agreed upon by both sides. Only information actually required for collection should be transferred at all.


Placement Agreement and Business Terms

Before a large batch is submitted, the written agreement should address the fee structure (including different rates by account age or balance, if applicable), minimum balance and maximum account age thresholds, the remittance schedule, how direct payments received by the client are reported and reconciled, account recall procedures, settlement and payment-plan authority, credit-reporting responsibilities, and litigation authorization. See the full fee structure breakdown for how this typically applies across different account types and ages.

Direct-payment reconciliation deserves its own process, not an afterthought. If debtors pay the client directly after placement, that needs to be reported quickly, ideally electronically, matched through the unique account reference number, with periodic reconciliation between agency and client. Without this, an agency can end up continuing to pursue a balance that’s already been paid, a genuinely avoidable and reputation-damaging mistake at volume.


Duplicate Screening, Pilot Batches, and Ongoing Cadence

Automated screening should happen before a large file enters the normal workflow, checking for duplicate accounts, previously placed accounts, zero-balance or already-paid accounts, bankruptcy accounts, deceased consumers, and accounts already in litigation or outside the agency’s acceptance criteria.

For a new client or a new portfolio type, a pilot batch beats loading the full portfolio immediately. Testing file formatting, documentation quality, duplicate detection, compliance flagging, and reporting on a smaller representative sample identifies problems while they’re still cheap to fix, before they’re multiplied across an entire portfolio. Once that pilot runs cleanly, the same process scales to the full batch.

If placements will happen regularly, establishing a predictable cadence, weekly, twice monthly, or monthly, is generally easier to manage than irregular large file dumps, along with a clear cutoff rule for when an account moves from internal accounts receivable into collections.


Reporting and Designated Contacts

Agree in advance on what reporting the client actually wants: accounts and dollars placed, amounts collected, recovery rate, payment arrangements, disputes, recalls, and legal recommendations. For large portfolios, this is best delivered through a dashboard, scheduled report, or API rather than manually prepared each time.

Both sides should also appoint specific contacts for day-to-day placement questions, data issues, disputes, compliance questions, payment reconciliation, and management escalation. Without designated contacts, small questions become real bottlenecks once thousands of accounts are involved.


The Bulk Placement Process, Start to Finish

→ Execute agreement and compliance documents
→ Agree on standardized file format
→ Securely transfer a pilot batch
→ Validate data and documentation
→ Run duplicate, bankruptcy, and compliance screening
→ Resolve exceptions
→ Approve full portfolio
→ Import accounts
→ Begin collection activity
→ Reconcile payments and account changes regularly
→ Provide scheduled performance reporting

At volume, data quality, automated screening, documentation, secure transfer, and reconciliation aren’t separate from the collection process, they are the collection process. A clean pilot batch before full implementation remains the simplest, least expensive way to catch problems before they’re multiplied across an entire portfolio.


Frequently Asked Questions

What’s the biggest mistake businesses make when placing a large volume of accounts?

Treating thousands of accounts as though they were simply one account repeated thousands of times. Without standardized data, upfront compliance flags, and automated duplicate and eligibility screening, an agency ends up doing manual cleanup that erases most of the efficiency bulk placement is supposed to create.

Do we need to flag every account with a potential compliance issue, or only the ones we’re sure about?

Flag anything with a genuine question mark, disputes, bankruptcy, attorney representation, cease-communication requests, or statute-of-limitations concerns. Flagging isn’t the same as rejecting the account, it’s what allows the agency to route it through the right compliance review before any collection activity starts, rather than discovering the issue mid-collection.

Why does a pilot batch matter if we’re confident in our data?

Because a pilot batch tests the entire process, file formatting, documentation quality, duplicate detection, and reporting, on a small, manageable sample before the same process runs across an entire portfolio. Problems that are cheap to fix in a pilot of a few hundred accounts can be expensive and disruptive once they’re already multiplied across ten thousand.

What happens if a debtor pays us directly after we’ve placed the account for collection?

That payment needs to be reported to the agency quickly and matched to the account through its unique reference number, ideally electronically rather than through ad hoc updates. Without a reliable reconciliation process, the agency can continue pursuing a balance that’s already been paid or reduced, which is avoidable and can damage the debtor relationship unnecessarily.

Does the statute of limitations review depend only on the charge-off date?

No, and relying on charge-off date alone is a common mistake. A proper review also considers the date the obligation arose, the original transaction or contract date, the date of default, the date of last payment, and the governing-law provision or debtor’s state, since these can point to a different limitations period than the charge-off date alone would suggest.

How is a commercial (B2B) portfolio different from a consumer portfolio for placement purposes?

The applicable notice requirements, communication rules, and documentation standards can differ substantially between consumer and commercial debt, so every account should be clearly classified by type before placement. Misclassifying accounts, even a small portion of a large batch, can create compliance exposure across every account affected.


Talk to Us About Placing a Large Portfolio

Filed Under: Debt Recovery

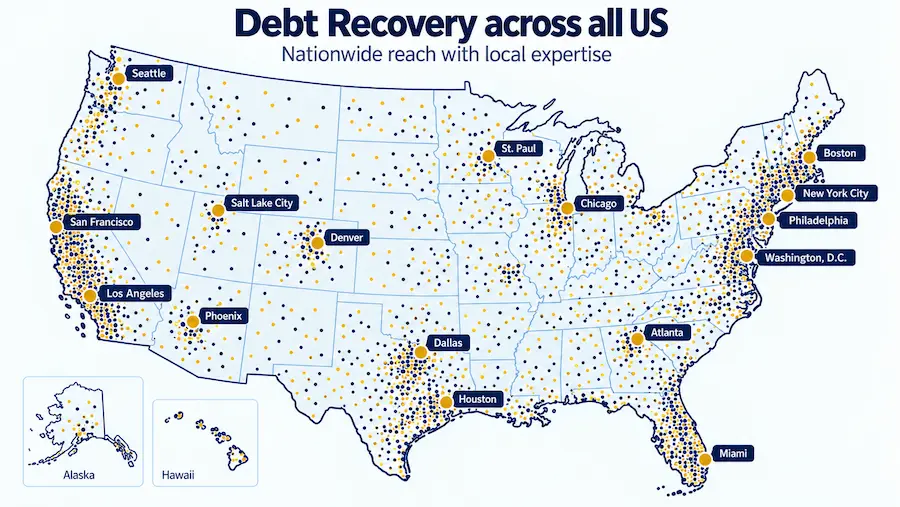
Nationwide Debt Collection Agency Serving U.S. Cities

A medical balance in Miami, a commercial invoice in Chicago, and an unpaid school account in Los Angeles can involve very different customers, industries, regulations, and recovery challenges. That is why Nexa combines nationwide debt collection capabilities with city- and state-aware recovery strategies designed to get businesses paid while protecting the relationships and reputations they have worked hard to build.

Whether you are a healthcare provider, school, contractor, CPA firm, utility, government organization, small business, or B2B company, find your city below to see how Nexa approaches debt recovery in your market.

Need a Collection Agency? Contact us

The Nexa Advantage

  • Nationwide Coverage – Serving businesses and organizations across all 50 states.
  • Local Market Expertise – Recovery strategies adapted to state, city, industry, and account type.
  • Reputation-Safe Collections – Professional communication designed to protect your customer relationships and brand.
  • SOC 2 Type II & HIPAA Compliant – Strong standards for security, privacy, and sensitive account information.
  • Flexible Pricing – Fixed-fee options starting at $15 per account, plus contingency-based collections for older or more difficult accounts.
  • Broad Industry Experience – Medical, dental, hospitals, schools, small businesses, CPAs, B2B, contractors, utilities, government, gyms, restoration, security alarm companies, and more.
  • Highly Rated Service – 4.85 rating with 2,000+ reviews.
  • Scalable for Small and Large Businesses – Suitable for a handful of overdue accounts or ongoing high-volume placements.
  • Multiple Recovery Strategies – Early-stage recovery, contingency collections, and structured follow-up based on account age and complexity.
  • Simple Nationwide Partner – One collection partner for accounts spread across multiple cities and states.

Nexa is a nationwide debt collection agency serving businesses and organizations across cities throughout the United States, combining national reach with local expertise.


Collection Agency in Alabama

Birmingham | Jasper | Huntsville | Mobile | Montgomery

Collection Agency in Alaska

Anchorage | Juneau | Ketchikan

Collection Agency in Arizona

Tucson | Flagstaff | Goodyear | Phoenix | Mesa | Glendale | Scottsdale | Tempe | Chandler | Surprise

Collection Agency in Arkansas

Lowell | White Hall | Fort Smith | Jonesboro | Little Rock | North Little Rock | Pine Bluff | Searcy

Collection Agency in California

Burbank | Petaluma | San Diego | Santa Clarita | San Luis Obispo | Irvine | Carmichael | Bakersfield | Fresno | Escondido | Anaheim | Beverly Hills | Rancho Cucamonga | Calabasas | Woodland Hills | Carlsbad | Chatsworth | Chico | Hanford | Fountain Valley | Cypress | Glendale | Agoura Hills | Grover Beach | Hayward | Huntington Beach | Oceanside | La Mesa | Lodi | Long Beach | Los Alamitos | West Covina | Los Angeles | Campbell | Vacaville | Modesto | Sacramento | Monrovia | Newport Beach | North Hollywood | Novato | Oakland | Oakley | Orange | Palm Springs | Indio | Pasadena | Pleasant Hill | Rancho Cordova | Redding | Salinas | San Jose | San Francisco | San Leandro | Gardena | Santa Barbara | Visalia | Santa Rosa | Camarillo | Simi Valley | South Pasadena | Stockton | Tarzana | Murrieta | Thousand Oaks | Van Nuys | La Mirada | Vista | Folsom | Sherman Oaks | Fairfield | Oxnard | Elk Grove | Garden Grove | Lancaster | Palmdale | Corona | Roseville | Fontana | Moreno Valley | Sunnyvale | Pomona | Victorville | Fullerton | Torrance | Santa Clara | Clovis | Riverside | Santa Ana | Chula Vista

Collection Agency in Colorado

Greenwood Village | Colorado Springs | Centennial | Longmont | Denver | Durango | Aurora | Fort Collins | Lakewood | Thornton

Collection Agency in Connecticut

Trumbull | Sandy Hook | West Hartford | Waterbury | Danbury | Bridgeport | Stamford | New Haven

Collection Agency in Delaware

Harrington | Dover | Lewes | Newark | New Castle | Wilmington

Collection Agency in Florida

Pembroke Pines | Tampa | Hudson | Orlando | Jacksonville | Sarasota | Boca Raton | Pompano Beach | Bradenton | Brooksville | Clearwater | Dunedin | Miami | Coral Springs | Boynton Beach | Fort Lauderdale | Fort Myers | Fort Walton Beach | Lake Worth | North Miami Beach | Coconut Grove | Miami Lakes | Miramar Beach | Ocala | Hollywood | Pensacola | Plantation | Vero Beach | West Palm Beach | Bonita Springs | Maitland | St. Petersburg | Port St. Lucie | Hialeah | Cape Coral | Tallahassee | Gainesville | Palm Bay

Collection Agency in Georgia

Atlanta | Norcross | Alpharetta | Marietta | Albany | Athens | Woodstock | Augusta | Brunswick | Columbus | Covington | Conyers | Duluth | Macon | Ellijay | Peachtree Corners | Rincon | Tucker | Savannah

Collection Agency in Idaho

Nampa | Idaho Falls | Boise | Lewiston | Meridian | Twin Falls

Collection Agency in Illinois

Lake Forest | Warrenville | Rolling Meadows | Des Plaines | Decatur | Oak Brook | Bloomington | Chicago | Palatine | Saint Charles | Taylorville | Park Ridge | Arlington Heights | Normal | Bourbonnais | Carbondale | Champaign | Elgin | Northbrook | Tinley Park | Lombard | Oakbrook Terrace | Naperville | Wheeling | Streator | Peoria | Hillside | Rockford | Itasca | Springfield | Sterling | Gurnee | Zion | Aurora

Collection Agency in Indiana

Indianapolis | Columbus | Fort Wayne | Greensburg | Terre Haute | Yorktown | Richmond

Collection Agency in Iowa

Cedar Falls | Sioux City | Des Moines | Cedar Rapids

Collection Agency in Kansas

Hutchinson | Wichita | Kansas City | Lawrence | Lenexa | Mission | Salina | Topeka | Olathe

Collection Agency in Kentucky

Paducah | Louisville | Bowling Green | Elizabethtown | Hopkinsville | Lexington | La Grange

Collection Agency in Louisiana

Kenner | Lake Charles | Alexandria | Metairie | Baton Rouge | Gonzales | Lafayette | Mandeville | Monroe | Shreveport | Covington | New Orleans

Collection Agency in Maine

Bangor | Auburn

Collection Agency in Maryland

Hunt Valley | Columbia | Bethesda | Towson | Rockville | Annapolis | Pikesville | Hyattsville | Beltsville | Crofton | Gaithersburg | Hollywood | Lanham | Pasadena | Salisbury | Silver Spring | West Friendship | Baltimore

Collection Agency in Massachusetts

Woburn | North Andover | Norwell | Chelsea | Lawrence | Wilmington | Framingham | Westborough | Lowell | Middleboro | Milford | Pembroke | Wilbraham | Mansfield | Worcester | Boston (Medical)

Collection Agency in Michigan

Flint | Troy | Clawson | Niles | Farmington Hills | St Johns | Ann Arbor | Jackson | Cadillac | Escanaba | Hancock | Midland | Manistee | Saginaw | Muskegon | Petoskey | Port Huron | Shelby Charter Township | Traverse City | Portage | Wyandotte | Sparta | Warren | Sterling Heights

Collection Agency in Minnesota

Ham Lake | Coon Rapids | St. Paul | Eden Prairie | Minneapolis | Montrose | Anoka | Cambridge | Plymouth | Champlin | Albert Lea | Alexandria

Collection Agency in Mississippi

Jackson | Flowood | Hattiesburg | Corinth | Moss Point | Natchez | Tupelo

Collection Agency in Missouri

St. Charles | Hazelwood | Chesterfield | Fenton | North Kansas City | St. Joseph | St Louis | Washington | Springfield | Columbia

Collection Agency in Montana

Missoula | Helena | Great Falls | Havre | Kalispell | Miles City

Collection Agency in Nebraska

Omaha | Kearney | Fremont | Beatrice | Denton | Lincoln

Collection Agency in Nevada

Las Vegas | Reno | Henderson

Collection Agency in New Hampshire

Salem | Rochester

Collection Agency in New Jersey

Piscataway | Pompton Plains | Fairfield | Fair Lawn | Voorhees Township | Whippany | Cherry Hill | East Brunswick | Waldwick | Gibbsboro | Hackettstown | Haddonfield | Hi-Nella | Mount Laurel | North Brunswick Township | Montvale | Old Bridge | Howell | Princeton | Red Bank | Branchburg | Upper Saddle River | Vineland | Wayne | Berlin | Hamilton Square | Newark | Paterson | Jersey City | Lakewood | Elizabeth

Collection Agency in New Mexico

Farmington | Albuquerque | Las Cruces

Collection Agency in New York

New York City | Bohemia | Poughkeepsie | Mount Sinai | Geneseo | Westbury | Commack | Arcade | Syosset | Buffalo | Valhalla | Babylon | Thornwood | Amherst | Bellmore | Staten Island | Baldwin | Bath | Tonawanda | Cheektowaga | Coram | East Northport | Elmsford | Fairport | Farmingdale | Flushing | Plainview | Hewlett | Hicksville | Hornell | Inwood | Lindenhurst | Nesconset | Newburgh | Patchogue | Syracuse | Tarrytown | Garden City | Melville | White Plains

Collection Agency in North Carolina

Durham | Winterville | Charlotte | Edenton | Greenville | Winston-Salem | Asheville | Greensboro | Salisbury | Concord | Gastonia | Hudson | Morrisville | Rocky Mount | Wilmington | Raleigh | Fayetteville | Cary

Collection Agency in North Dakota

Bismarck | Grafton | Fargo

Collection Agency in Ohio

Columbus | Defiance | Gahanna | Hamilton | New Albany | Mason | Berea | Hudson | Rocky River | Cleveland | Toledo | Dayton

Collection Agency in Oklahoma

Tulsa | Oklahoma City | Norman

Collection Agency in Oregon

Medford | Astoria | The Dalles | Roseburg | Portland | Keizer | Albany | La Grande | Bend | Eugene | Coos Bay | Hermiston | Klamath Falls | McMinnville | Salem

Collection Agency in Pennsylvania

Mechanicsburg | Pittsburgh | Ambler | Harrisburg | Trevose | Dickson City | Reading | Bethlehem | Glen Mills | Broomall | Blue Bell | Wayne | Eynon | Bangor | Camp Hill | Cheswick | Drums | Kingston | Halifax | West Reading | Lancaster | Lititz | Middletown | New Kensington | Hatboro | Sunbury | West Chester | York | Philadelphia

Collection Agency in Rhode Island

East Providence

Collection Agency in South Carolina

Rock Hill | Greenville | Travelers Rest | Columbia | Charleston

Collection Agency in South Dakota

Aberdeen | Sioux Falls

Collection Agency in Tennessee

Memphis | Nashville | Knoxville | Chattanooga | Clarksville | Murfreesboro

Collection Agency in Texas

Amarillo | Arlington | Austin | Brownsville | Carrollton | Dallas | Denton | Fort Worth | Garland | Grand Prairie | Houston | Irving | Killeen | Laredo | Lubbock | McKinney | Plano | Richardson | Royse City | San Antonio | Spring | Tyler | Mesquite | Pasadena | McAllen | Waco | Midland | Lewisville | Round Rock | Pearland | College Station

Collection Agency in Utah

South Ogden | Salt Lake City | Ogden | American Fork | West Valley City

Collection Agency in Virginia

Norfolk | Virginia Beach | Lynchburg | Springfield | Roanoke | Alexandria | Richmond | Emporia | Danville | Newport News | Woodbridge | Chesapeake

Collection Agency in Washington

Bothell | Redmond | Bellevue | Everett | Spokane Valley | Vancouver | Spokane | Walla Walla | East Wenatchee | Lynnwood | Centralia | Chehalis | Ellensburg | Federal Way | Kennewick | Kent | Moses Lake | Mount Vernon | Oak Harbor | Pasco | Port Angeles | Poulsbo | Seattle | Tacoma | Tumwater | Yakima | Union Gap

Collection Agency in West Virginia

Morgantown

Collection Agency in Wisconsin

Madison | Manitowoc | Green Bay | Janesville | Elkhorn | Beloit | La Crosse | Portage | Kenosha | Eau Claire | Fond du Lac | Germantown | Pewaukee | Hartland | Hudson | Marshfield | Brookfield | Milwaukee | Beaver Dam | Oshkosh | Racine | Wausau

Collection Agency in Wyoming

Sheridan | Casper | Laramie | Evanston

Collection Agency in Washington DC

Washington, D.C.

Puerto Rico

Puerto Rico

Filed Under: Debt Recovery

Chula Vista Collection Agency for Medical, B2B, Schools & Business Debt

Chula Vista is built on South Bay relationships and cross-border commerce. Your collection strategy has to protect both.

From healthcare and schools to Bayfront hospitality, contractors, professional firms, and businesses connected to the San Diego–Tijuana trade corridor, overdue accounts can become complicated quickly.

Nexa provides reputation-safe debt collection in Chula Vista, CA, combining HIPAA-compliant healthcare recovery, commercial B2B expertise, $15 fixed-fee options for fresher accounts, contingency collections for tougher balances, secure workflows, bilingual (English & Spanish collectors), and nationwide collection capability. The goal is simple: recover more of what you’re owed without putting your brand, customer relationships, or hard-earned reputation at unnecessary risk.

Chula Vista California Bayfront and marina representing reputation-safe medical, B2B and small business debt collection

Nexa provides a reputation-safe approach, equipped with all 50-state collections license, offering free credit reporting, free litigious debtor check, free bankruptcy scrub, and zero onboarding fees. Secure – SOC 2 Type II & HIPAA compliant. Over 2,000 online reviews rate us 4.85 out of 5. 

Need a Chula Vista Collection Agency? Contact us


Our 4-Step Process: Control & Flexibility

blank

You decide how far to go.

  • Step 1: First-Party Outreach ($15): We act as your internal team, sending professional reminders under your brand.

  • Step 2: Third-Party Demands ($15): We escalate respectfully as a third party, applying more pressure.

  • Step 3: Contingency (40%): If Steps 1 & 2 don’t work, we move to a traditional model. We only get paid if you do.

  • Step 4: Legal Forwarding (50%): For the most difficult accounts, we can manage the legal process.

Most of our clients use a powerful combination: Step 2 (Third-Party Demands) followed by Step 3 (Contingency). This hybrid approach gets results without the immediate high cost.


Recent Recoveries

Dental Practice — Fixed-Fee | 91% Recovered

A South Bay dental practice placed $7,800 in relatively fresh patient balances. Patient-friendly fixed-fee outreach recovered $7,098 — 91% while preserving the practice’s relationship-focused approach.

Dental Collection Services

Import & Distribution Company — B2B Contingency | 83% Recovered

A Chula Vista-area distributor assigned $34,600 in overdue commercial invoices involving receiving and freight disputes. Documentation-led negotiation recovered $28,718 — 83%.

Commercial B2B Collections

Restoration Contractor — Contingency | 69% Recovered

A South County restoration company placed $22,400 in older completed-job balances involving disputed extras and delayed approvals. Professional recovery efforts produced $15,456 — 69%.

Contractor Collection Services


Industries We Serve in Chula Vista

Nexa provides specialized, reputation-safe debt collection tailored to the unique economic landscape of Chula Vista and the South Bay—from the Otay Mesa freight corridor to master-planned communities across Eastlake and Otay Ranch.

  • Cross-Border Logistics, Freight & Warehousing:

    Positioned along the I-805, SR-125, and Otay Mesa ports of entry, Chula Vista is a vital artery for third-party logistics (3PL), drayage carriers, and freight forwarders. We recover unpaid commercial freight invoices, detention and demurrage charges, and warehouse storage fees while navigating complex multi-party B2B shipping contracts.

  • Hospitals, Healthcare Systems & Dental Practices:

    From regional hospital networks like Sharp Chula Vista Medical Center and Scripps outpatient facilities to private clinics and dental practices along Eastlake and Third Avenue. We recover overdue patient-responsibility balances with strict adherence to HIPAA, California’s SB 1061 (prohibiting medical debt credit bureau reporting), and state balance-billing protections.

  • Restoration Companies (Water, Fire & Mold):

    Disaster recovery and emergency restoration contractors face complex insurer payout timelines and property owner disputes. We collect unpaid self-pay deductibles, insurance shortfalls, work authorization balances, and emergency mitigation charges using signed assignments of benefits (AOB) and Xactimate-backed documentation.

  • Commercial & Residential Contractors (Trades & Subcontractors):

    Serving framing, electrical, plumbing, HVAC, and general contractors operating across the Chula Vista Bayfront, Otay Ranch, and Millenia. We pursue unpaid milestone billing, change orders, and retainage balances while ensuring your collection efforts stay aligned with California mechanics’ lien timelines (Cal. Civ. Code § 8416).

  • Private Schools, Daycares & Vocational Academies:

    Tuition default and mid-year student withdrawals strain private academy cash flow. We collect past-due tuition, enrollment agreement obligations, activity fees, and childcare balances through sensitive, brand-protective outreach that preserves family and community goodwill.

  • Home Security & Commercial Alarm Systems:

    Recurring subscription models and early termination fee (ETF) disputes require specialized contract verification. We recover delinquent monitoring fees, unreturned hardware costs, and valid termination charges under California contract requirements, confirming all customer agreements meet residential consumer protection standards.

  • Aerospace, Manufacturing & B2B Technology:

    Supporting South Bay precision machine shops, naval defense suppliers, and IT service providers (MSPs). We recover high-value B2B receivables, purchase order balances, and milestone delivery defaults with firm, auditable communication.


Chula Vista Debt Collection FAQs

Do California’s Rosenthal debt-collection rules now apply to some Chula Vista small-business debts?

Yes. California expanded the Rosenthal Fair Debt Collection Practices Act to certain covered commercial debts entered into, renewed, sold, or assigned on or after July 1, 2025.

The expansion is not a blanket rule covering every B2B invoice. It generally addresses qualifying commercial credit of $500,000 or less involving a natural-person debtor or guarantor and applies specific protections against unfair or deceptive collection practices.

For Chula Vista lenders, financing providers, and businesses working with personally guaranteed commercial obligations, the account type and underlying documentation should therefore be identified before collection begins.

Commercial B2B Collection Services

Can a Chula Vista medical practice report an unpaid patient balance to the credit bureaus?

For medical debt covered by California law, medical debt generally cannot appear on a consumer credit report. California’s SB 1061 took effect January 1, 2025, and the California Attorney General reaffirmed that prohibition in late 2025.

Hospital-originated consumer debt has additional collection requirements. California law requires specified information in the collector’s first written communication and generally requires at least 180 days from the patient’s initial hospital billing before a lawsuit is filed over that debt.

That makes insurance resolution, financial assistance, accurate patient responsibility, and account classification especially important before placement.

Medical Collection Services

What should a Chula Vista importer, distributor, or supplier send when a cross-border B2B invoice is disputed?

An invoice alone may not be enough.

For businesses involved in South Bay or international trade, a stronger collection file can include the purchase order, contract, commercial invoice, bill of lading, proof of delivery, receiving confirmation, customs or shipping documentation, approved surcharges, change orders, payment history, and emails explaining the dispute.

The objective is to determine whether the real problem is damaged or rejected goods, quantity discrepancies, freight charges, procurement delays, an AP bottleneck, or simply nonpayment.

This question fits Chula Vista particularly well because the city identifies its proximity to the U.S.–Mexico border and international import/export activity as a distinct economic advantage.

Commercial Debt Collection

Can a Chula Vista contractor keep negotiating payment and still preserve a California mechanics lien?

Negotiating payment does not automatically preserve lien rights.

Without a qualifying Notice of Completion or Cessation, California mechanics liens generally must be recorded within 90 days of completion. When a qualifying Notice of Completion is recorded, the deadline can shorten to 60 days for a direct contractor and 30 days for subcontractors and material suppliers. Preliminary-notice requirements can also affect lien rights.

That means contractors should not spend months pursuing informal payment while assuming a collection placement stops the lien clock.

Nexa can pursue documented unpaid invoices while the contractor separately evaluates any California lien rights and deadlines.

Contractor Collection Services

Can a Chula Vista public school send unpaid cafeteria balances to a collection agency?

California treats school-meal debt differently from many other school receivables.

For public school districts, county offices of education, and charter schools covered by California Education Code rules, collection efforts involving unpaid meal debt must be directed toward the parent or guardian rather than the student, and California guidance specifically says those efforts may not use a debt collector. Students also cannot be denied, delayed, or shamed over a nutritionally adequate meal because of unpaid meal debt.

California’s Universal Meals Program also requires public schools to make breakfast and lunch available at no charge to students requesting them.

That does not mean every school receivable is treated the same way. Private-school tuition, damaged devices, enrollment obligations, extended-care fees, and other documented contractual balances can involve different recovery rules.

School Collection Services

How can a Chula Vista business verify that a debt collector is properly licensed in California?

California requires debt collectors and debt buyers operating in the state and covered by the Debt Collection Licensing Act to obtain a license through the California Department of Financial Protection and Innovation (DFPI).

Businesses can verify licensed collectors through NMLS Consumer Access. California also requires applicable collection communications to display the collector’s California license number.

For a medical practice, school, contractor, CPA firm, or small business, licensing should be one part of due diligence. Security controls, industry knowledge, complaint history, reporting, and the agency’s approach to protecting customer relationships also matter.


Get Started Today

Stop losing money to bad processes. Let’s improve your Reno cash flow.
Contact Nexa Today

Filed Under: Debt Recovery

Corpus Christi Collection Agency: Itemized Bill Rules for Practices

A Texas medical practice cannot pursue collection on a patient balance until it sends a written itemized bill. Since September 1, 2023, Texas law has made this a required step, and the bill must generally be sent within 30 days after final insurer payment. Miss it, and collection can be delayed until the requirement is satisfied.

Corpus Christi also has a uniquely industrial economy, anchored by Port Corpus Christi, energy, petrochemicals, logistics, and healthcare. Nexa helps recover local accounts starting at a $15 fixed fee per account, with contingency options for older balances—combining compliant recovery with reputation-safe, licensed, and easy-to-use service.

Corpus Christi, TX collection agency services by Nexa Collections offering compliant, reputation-safe debt recovery, low-cost collection options, and nationwide support.

Nexa provides a reputation-safe approach, equipped with all 50-state collections license, offering free credit reporting, free litigious debtor check, free bankruptcy scrub, and zero onboarding fees. Secure – SOC 2 Type II & HIPAA compliant. Over 2,000 online reviews rate us 4.85 out of 5. Easy to use and a good client support team.

Need an Corpus Christi Collection Agency? Contact us


What Makes Corpus Christi Genuinely Different

Medical debt collection here has a hard prerequisite most providers don’t know exists. 
Under Tex. Health & Safety Code § 185.002, a health care provider requesting payment from a patient must submit a written, itemized bill describing each distinct service or supply provided, and the statute states directly that a provider “may not pursue debt collection against a patient… unless the provider has complied with this section.” The itemized bill must go out no later than 30 days after the provider receives final payment from a third party like an insurer. For Corpus Christi’s major medical hub, home to CHRISTUS Spohn, Corpus Christi Medical Center, and Driscoll Children’s Hospital, confirming this step happened, and happened on time, is worth checking before any account is placed for collection.

Port Corpus Christi anchors a genuinely massive, distinctive commercial economy. 
As the largest U.S. crude-oil export gateway and the second-largest U.S. gateway for LNG exports, the port drives a regional petrochemical and industrial-service sector that purchases more than $1.5 billion in local goods and services annually and supports roughly 50,000 direct and indirect jobs. B2B accounts tied to this sector, freight, terminal services, oilfield services, fabrication, and industrial maintenance, are often documentation-heavy, turning on master service agreements, field tickets, and change orders rather than a simple invoice.

Texas’s broad wage garnishment prohibition still applies here, the same as statewide. 
Texas generally does not allow wage garnishment for most consumer debts, and the Texas Finance Code Chapter 392 reaches original creditors collecting their own debts, not just third-party agencies, consistent with the framework already established across other Texas cities in this project.


The Texas Legal Landscape

Statute of Limitations (most consumer debt) 4 years — Tex. Civ. Prac. & Rem. Code § 16.004
Medical Debt Pre-Collection Requirement Written itemized bill required before collection — Tex. Health & Safety Code § 185.002
Itemized Bill Deadline Within 30 days of receiving final third-party payment
Wage Garnishment Not allowed for most consumer debts (exceptions: child support, taxes, certain federal student loans)
Governing Consumer Law Texas Finance Code Chapter 392, reaches original creditors
Third-Party Collector Bonding $10,000 surety bond with the Texas Secretary of State
Nonresidential Mechanics Lien 15th day of the 4th month after completion, termination, or abandonment
Residential Mechanics Lien 15th day of the 3rd month after completion
Nueces County Justice Court Limit $20,000 (excluding statutory interest/costs, including attorney fees)

What This Costs

Step 1 & 2: Fixed-Fee Recovery (~$15/account). Professional demand sequences for accounts under roughly 60-90 days, with itemized-bill compliance screening built in for medical accounts. Payments go directly to you. See the full pricing breakdown.

Step 3: Contingency Collection (~40%). For older or unresponsive accounts, no recovery, no fee.

Step 4: Legal Referral (client-approved, ~50%). With mechanics lien deadline coordination for eligible construction accounts, filing fees reimbursed from the first recovery.

Nexa Collections fixed-fee and contingency pricing structure


Who We Collect For Across Corpus Christi

  • Agriculture & Manufacturing: B2B and commercial receivables for the oilfield-service companies, fabricators, and industrial suppliers tied to the Coastal Bend’s refining and petrochemical sector.
  • Hospitals, Dental & Medical: HIPAA and Chapter 185-compliant patient balance recovery for the region’s major medical systems and independent practices.
  • Colleges & Universities: Tuition and fee recovery for the region’s higher education institutions.
  • K-12 Private & Charter Schools: Tuition and activity fee recovery handled diplomatically, alongside meal and fee recovery for public districts.
  • Accountants & CPA Firms: Commercial receivables for the professional services firms supporting the energy and port-driven economy.
  • Banks & Credit Unions: Recovery for the region’s financial institutions and lending partners.
  • Construction & Trades: B2B recovery with Texas’s mechanics lien deadlines flagged at intake for industrial contractors, marine contractors, and trades serving the port and energy sector.
  • B2B Commercial, Restoration & Waste Management: Commercial receivables for freight companies, terminal operators, hotels, event venues, restoration contractors, and waste management providers.

Recent recovery Results in Corpus

$38,400 Recovered (66% Recovery Rate) — B2B Industrial Marine & Port Services
An equipment rental and marine repair contractor near the Port of Corpus Christi held $58,200 in past-due invoices from an out-of-region maritime logistics operator disputing fuel surcharges and mobilization fees. Nexa conducted an audit of signed master service agreements (MSAs), daily work tickets, and port gate logs, securing a $38,400 wire settlement in 40 days without formal litigation.

$16,200 Collected (71% Recovery Rate) — Outpatient Medical & Imaging Center
A multi-specialty healthcare and diagnostic imaging clinic near the SPID / Staples commercial corridor accumulated $22,800 across 18 delinquent self-pay and high-deductible patient balances (90–150 days past due). Operating under Texas Finance Code Chapter 392 and HIPAA guidelines, Nexa deployed Step 2 diplomatic demand notices with embedded digital payment links, recovering $16,200 directly to the clinic’s account.


Frequently Asked Questions

Can a Corpus Christi collection agency recover unpaid freight, terminal, and logistics invoices?

Yes. Port Corpus Christi is one of the country’s largest energy and cargo gateways, with connections by deep-water ship channel, rail, interstate highway, terminals, warehouses, and industrial facilities. The Port describes itself as the largest U.S. crude-oil export gateway and the second-largest U.S. gateway for LNG exports. For Corpus Christi freight companies, terminal operators, trucking firms, warehouses, equipment providers, and industrial suppliers, collectible balances may include transportation charges, storage, demurrage-related invoices, equipment rentals, terminal services, project cargo, and other B2B receivables. Keep contracts, rate agreements, bills of lading, delivery records, gate or terminal records, invoices, and emails concerning shortages, delays, storage, or disputed charges. Port-related disputes are often documentation-heavy, so the invoice alone may not tell the full story.

How should Corpus Christi oil, gas, refinery, and petrochemical companies handle unpaid B2B invoices?

Early. The Coastal Bend has one of the country’s largest concentrations of refining, petrochemical, LNG, midstream, fabrication, and industrial-service activity. Corpus Christi reports that the regional petrochemical sector purchases more than $1.5 billion in local goods and services annually and supports roughly 50,000 direct and indirect jobs. That creates significant receivables for oilfield-service companies, industrial contractors, fabricators, maintenance firms, equipment rental companies, engineering businesses, chemical suppliers, transportation companies, and parts vendors. Before collection begins, preserve master service agreements, purchase orders, field tickets, delivery documents, time sheets, change orders, inspection records, invoices, and approval emails. Industrial accounts often involve disputes over scope, downtime, change orders, or who actually authorized the work.

Can Corpus Christi hospitals and medical practices send patient balances to collections under Texas law?

Yes, but Texas healthcare providers need to complete the required billing steps first. Under Texas Health and Safety Code Chapter 185, a covered healthcare provider requesting payment from a patient must provide a written itemized bill showing the services or supplies provided, applicable billing information, and the amount claimed from the patient. Importantly, the law says a provider may not pursue debt collection until it has complied with the itemized-billing requirement. That is particularly relevant in Corpus Christi, which serves as a major South Texas medical hub with systems such as CHRISTUS Spohn, Corpus Christi Medical Center, and Driscoll Children’s Hospital. Medical offices, dentists, hospitals, surgery centers, urgent care providers, imaging centers, and specialists should verify the patient-responsibility balance and required billing documentation before referring an account for professional collection.

How quickly should a Corpus Christi contractor act when a commercial or residential project goes unpaid?

Before the Texas lien deadline starts getting uncomfortable. For an original contractor on a nonresidential project, a lien affidavit generally must be filed by the 15th day of the fourth month after the month the work was completed, terminated, or abandoned. On a residential project, the deadline is generally the 15th day of the third month. Different notice requirements and deadlines can apply to subcontractors, suppliers, and retainage claims. That matters for Corpus Christi industrial contractors, restoration companies, roofers, HVAC firms, electricians, plumbers, marine contractors, subcontractors, and material suppliers. Do not let months of friendly reminders consume potential lien rights. Collection activity can begin while a qualified Texas construction attorney evaluates any statutory notices or lien filings.

Can Corpus Christi hotels and event businesses collect unpaid group bookings or convention invoices?

Yes. Tourism and group business are major parts of the local economy. Visit Corpus Christi reported in 2026 that the city attracts about 5.1 million visitors annually and roughly $1.2 billion in visitor spending, while meetings and events alone generated an estimated $22.2 million in economic impact in 2024. Hotels, resorts, caterers, fishing and charter operators, event venues, AV companies, transportation providers, restaurants, and convention vendors may have unpaid balances involving room blocks, corporate events, catering, cancellation charges, equipment rentals, deposits, or additional services. For stronger collection files, keep the signed event agreement, room-block terms, cancellation or attrition provisions, banquet orders, approved extras, invoices, and correspondence showing who authorized the charges.

Can a Corpus Christi business use Nueces County Justice Court for an unpaid invoice?

Yes, depending on the type and amount of the claim. Nueces County Justice Courts can hear Small Claims cases of up to $20,000, excluding statutory interest and court costs but including attorney fees, if any. Texas also has a separate Debt Claim procedure for certain lawsuits brought by an assignee, debt collector or collection agency, financial institution, or certain lenders. Those cases also generally have a $20,000 Justice Court limit. For a straightforward Corpus Christi invoice with good documentation, Justice Court may be one option after collection efforts fail. However, obtaining a judgment does not automatically mean the money is recovered; enforcement is a separate stage, and larger or more complicated commercial matters may warrant a Texas debt-collection attorney.


Talk to Us About Your Corpus Christi Receivables

Filed Under: Debt Recovery

Riverside Collection Agency | For Logistics, Medical, Schools & Business Recovery

Riverside keeps Southern California moving, through logistics, manufacturing, healthcare, construction, and thousands of local businesses. But when customers stop paying, cash flow can slow down fast.

From warehouses and distributors along the Inland Empire logistics corridor to medical and dental practices, manufacturers, contractors, property managers, schools, and professional firms across Riverside, Nexa helps turn overdue accounts back into working revenue. We combine persistent follow-up with a reputation-first approach, firm enough to get attention, professional enough to protect the customer and business relationships you still value.

Quick answer: Riverside’s economy is genuinely anchored by the Inland Empire’s logistics and goods-movement corridor, alongside aerospace, clean-tech, and food-and-beverage manufacturing, all operating under California’s standard legal framework: a 4-year statute of limitations for written contracts, medical debt barred from credit reports since January 2025, and mechanics-lien deadlines running on a strict 90-day clock separate from ordinary collection timelines. Nexa recovers Riverside accounts starting at a $15 fixed fee per account, with contingency options for older balances.

Riverside, California collection agency services by Nexa Collections, featuring compliant, reputation-safe debt recovery, low-cost options, strong reviews, and nationwide licensing.

Nexa provides a reputation-safe approach, equipped with all 50-state collections license, offering free credit reporting, free litigious debtor check, free bankruptcy scrub, and zero onboarding fees. Secure – SOC 2 Type II & HIPAA compliant. Over 2,000 online reviews rate us 4.85 out of 5. Easy to use and a good client support team.

Need a Riverside Collection Agency? Contact us


Four Recent Recovery Results

Urgent Care Clinic — $24,600 Recovered at 58%. 
A Riverside urgent care practice carrying $42,400 in self-pay balances across 76 accounts placed them on a Step 1/Step 2 fixed-fee sequence. 48 accounts resolved within 50 days, with the remainder moving to contingency, bringing total recovery to $24,600 (58%) within 85 days.

Private School — $19,300 Recovered at 61%. 
A Riverside-area private school carrying $31,600 in unpaid tuition and activity fee balances across 34 families used a diplomatic, relationship-first collection sequence. 22 accounts resolved within 60 days, recovering $19,300 (61%) while retaining several families for the following enrollment year.

Logistics & Warehousing Company — $38,900 Recovered at 68%. 
A distribution company along the Inland Empire corridor carried $57,200 across 11 accounts tied to storage, detention, and freight charges. With rate confirmations and proof-of-delivery documentation reviewed at intake, 9 of 11 accounts resolved within 70 days, recovering $38,900 (68%) without litigation.

Commercial Supplier — $31,700 Recovered at 72%. 
A Riverside industrial supplier carrying $44,000 across 8 aged B2B accounts placed them on contingency after internal collection stalled. 7 of 8 accounts resolved within 65 days, recovering $31,700 (72%) through direct negotiation.


What Makes Riverside’s Economy Genuinely Different

The logistics corridor creates a distinct commercial account category. 
Riverside sits within Southern California’s major goods-movement corridor, with strong logistics, transportation, and distribution activity. Accounts here often involve freight charges, trucking invoices, warehousing fees, and detention or storage disputes rather than a simple product invoice, and documentation like rate confirmations, bills of lading, and proof of delivery matters more here than in a typical commercial market.

Manufacturing here spans aerospace, clean-tech, and food and beverage. 
Riverside’s substantial manufacturing base, and the city’s active efforts to attract green transportation and next-generation manufacturing companies, means industrial B2B accounts frequently turn on whether goods or work met agreed specifications, making purchase orders, inspection records, and change orders genuinely important documentation.

Mechanics lien deadlines run on a separate, strict clock. 
A qualifying mechanics lien generally must be recorded within 90 days of completion, and subcontractors or material suppliers may need a 20-day Preliminary Notice to preserve lien rights for earlier work. A recorded Notice of Completion can shorten the filing window further, to 60 days for a direct contractor or 30 days for subcontractors, so collection efforts should begin well before any of these deadlines are at risk.


The California Legal Landscape

Statute of Limitations (written contracts) 4 years — Cal. Code Civ. Proc. § 337
Statute of Limitations (oral agreements) 2 years — Cal. Code Civ. Proc. § 339
Medical Debt Credit Reporting Barred since January 1, 2025
Mechanics Lien Filing 90 days from completion (60/30 days with recorded Notice of Completion)
Preliminary Notice (subcontractors/suppliers) Generally required within 20 days
Security Deposit Accounting 21 calendar days, plus 2025 photo-documentation requirements
Small Claims (Riverside County) $12,500 individual/sole proprietor; $6,250 for business entities

What This Costs

Step 1 & 2: Fixed-Fee Recovery (~$15/account). Professional demand sequences for accounts under roughly 60-90 days. Payments go directly to you. See the full pricing breakdown.

Step 3: Contingency Collection (~40%). For older or unresponsive accounts, no recovery, no fee.

Step 4: Legal Referral (client-approved, ~50%). With mechanics lien deadline coordination on eligible construction accounts, filing fees reimbursed from the first recovery.

Nexa Collections fixed-fee and contingency pricing structure


Who We Collect For Across Riverside

  • Agriculture & Manufacturing: B2B and commercial receivables for aerospace component makers, food and beverage producers, and clean-tech manufacturers across the metro.
  • Hospitals, Dental & Medical: HIPAA-compliant patient balance recovery for physicians, dentists, hospitals, urgent care centers, and senior living providers.
  • Colleges & Universities: Tuition and fee recovery for the region’s higher education institutions.
  • K-12 Private & Charter Schools: Tuition and activity fee recovery handled diplomatically, alongside meal and fee recovery for public districts.
  • Accountants & CPA Firms: Commercial receivables for the professional services firms supporting Riverside’s logistics and manufacturing base.
  • Banks & Credit Unions: Recovery for the region’s financial institutions and lending partners.
  • Construction & Trades: B2B recovery with California’s mechanics lien deadlines flagged at intake for contractors, roofers, HVAC companies, and restoration firms.
  • B2B Commercial, Restoration & Waste Management: Commercial receivables for the logistics, warehousing, and distribution companies along the Inland Empire corridor, plus restoration contractors and waste management providers.

Frequently Asked Questions

Can a Riverside collection agency recover unpaid freight, logistics, and warehousing invoices?

Yes. Riverside is part of Southern California’s major goods-movement corridor and has strong logistics, transportation, manufacturing, and distribution activity. The city itself highlights logistics and advanced manufacturing as important parts of its economic base. Nexa can pursue documented B2B receivables involving freight charges, trucking invoices, warehousing fees, storage, distribution services, equipment rentals, transportation services, and commercial supply accounts. For disputed logistics accounts, businesses should preserve contracts, rate confirmations, bills of lading, proof of delivery, warehouse records, invoices, and correspondence involving shortages, damages, detention, storage, or other disputed charges.

Can Riverside manufacturers and industrial suppliers use a collection agency for unpaid B2B invoices?

Yes. Riverside has a substantial manufacturing base that includes aerospace components, food and beverage, transportation products, clean technology, and advanced manufacturing. The city is also actively attracting companies in green transportation, aerospace, and next-generation manufacturing. Nexa can pursue legitimate receivables for manufacturers, machine shops, component suppliers, equipment companies, engineering firms, industrial contractors, and distributors. For manufacturing disputes, keep purchase orders, contracts, invoices, delivery records, inspection or acceptance documents, change orders, warranty records, credit memos, and customer communications. These accounts often turn on whether the goods or work met the agreed specifications.

Can Riverside medical and dental practices still send unpaid patient balances to collections in California?

Yes. California still allows valid patient-responsibility balances to be collected, but the rules surrounding medical debt have changed significantly. Since January 1, 2025, California generally prohibits medical debt from appearing on consumer credit reports. HHS also confirms that healthcare providers may use collection agencies as part of their payment activities through an appropriate business-associate arrangement, subject to HIPAA requirements. For Riverside physicians, dentists, hospitals, urgent care centers, surgery centers, ophthalmologists, imaging centers, and senior living providers, collection should focus on accurate patient balances, secure data handling, respectful communication, and realistic payment resolution rather than credit-reporting pressure.

How quickly should a Riverside contractor act on an unpaid construction invoice?

Quickly. California mechanics-lien deadlines can expire while contractors are still sending routine reminders. A qualifying mechanics lien generally must be recorded within 90 days of completion or another qualifying completion event. Subcontractors and material suppliers may also need to provide a 20-day Preliminary Notice to preserve lien rights for earlier work or materials. For Riverside general contractors, roofers, HVAC companies, restoration firms, electricians, plumbers, subcontractors, and material suppliers, collection efforts should begin well before potential lien rights expire. A California construction attorney should handle lien filing or enforcement when legal action becomes necessary.

Can Riverside property managers collect move-out charges that exceed the tenant’s security deposit?

Potentially, yes, if the remaining charges are legitimate and properly documented. California generally requires landlords to provide an itemized security-deposit accounting within 21 calendar days after the tenant vacates. Beginning in 2025, California also added photographic documentation requirements for deductions involving certain cleaning and repairs. For Riverside landlords and property managers, a strong collection file should include the lease, payment ledger, move-in and move-out photographs, inspection records, repair invoices, cleaning charges, security-deposit accounting, and tenant communications. If lawful unpaid rent, damages, or other permitted charges exceed the deposit, the documented remaining balance may still be collectible.

Can a Riverside business use Riverside County Small Claims Court for an unpaid invoice?

Yes. Riverside County Small Claims Court can handle qualifying money disputes relatively quickly and inexpensively. An individual or sole proprietor can generally sue for up to $12,500, while a corporation or other business entity can generally seek up to $6,250 in Small Claims Court. Riverside County also requires the plaintiff to ask the defendant to pay before filing, and the court provides local Small Claims assistance and mediation resources. For straightforward, well-documented unpaid invoices, Small Claims Court may be useful. However, winning a judgment does not automatically produce payment; the creditor remains responsible for collection and enforcement afterward.


Talk to Us About Your Riverside Receivables

Filed Under: Debt Recovery

  • Page 1
  • Page 2
  • Page 3
  • Interim pages omitted …
  • Page 55
  • Go to Next Page »

Primary Sidebar


accounts receivable

Need a Collection Agency?
Kindly fill this form.
We’ll get in touch with you

    Please prove you are human by selecting the cup.

    Compliance & Security

    • SOC 2 Type II Certified: Third-party audited data security and strict privacy controls.

    • HIPAA Compliant: Secure, legal processing of medical and municipal EMS accounts.

    • PCI-DSS Level 1: Highest tier of data encryption for secure payment processing.

    • FDCPA & FCRA Aligned: Full legal adherence to federal consumer protection laws.

    Recent Posts

    • Why Dental Patients Dispute Bills: The Nexa Collections Dental Account Dispute Index
    • 2027 Commercial Collections Benchmark: U.S. Late Payments, AR Risk and B2B Collection Trends
    • Bulk Account Placement: What a Collection Agency Actually Needs From You
    • Nationwide Debt Collection Agency Serving U.S. Cities
    • Chula Vista Collection Agency for Medical, B2B, Schools & Business Debt
    • Corpus Christi Collection Agency: Itemized Bill Rules for Practices
    • Riverside Collection Agency | For Logistics, Medical, Schools & Business Recovery
    • Collection Agency for Large Balances: High-Value B2B Debt Recovery

    Featured Posts

    • The Silent Bankruptcy Trigger: Why Medical Debt Is Breaking U.S. Households
    • The “Aggressive” Agency Trap: Is Fast Cash Worth Losing Your Business?
    • Laundry and Dry Cleaning Service: Debt Collections Agency

    Copyright © 2026 NEXACOLLECT.COM | This content is provided for general informational purposes only and should not be considered legal advice. Collection laws and requirements may vary by state, account type, documentation, debtor status, and specific facts. Please consult qualified legal counsel for guidance regarding your particular situation. Nexa and its authorized collection partners service accounts in accordance with applicable federal and state collection requirements. Visit our home page to know more about us.

    X
    Need a Collection Agency?
    Contact Us