• Skip to main content
  • Skip to primary sidebar

Nexa Collections

  • Home
  • Serving
    • Medical
    • Dental
    • Small Business
    • Large Business
    • Commercial Collections
    • Government
    • Utilities
    • Fitness Clubs
    • Schools
    • Senior Care Facility
  • Contact Us
    • About us
    • Cost

Debt Recovery

Pros and Cons of Hiring a Debt Collection Agency

The challenges that businesses face are numerous, but few are as aggravating as customers that don’t pay their bills. This violates the basic quid pro quo that commerce is founded on. You provide a product or service, and in return, your customers agree to pay for it.

When they don’t, business owners must decide whether to pursue the debts themselves or pass the job off to a third-party collection agency. Both options have their positives and negatives. This article will focus on the pros and cons of hiring a debt collector instead of doing the difficult work of collecting yourself.
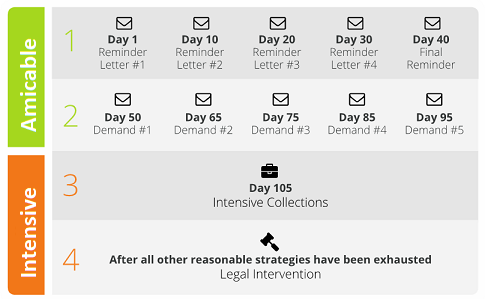
Collection Agency

Pros in Favor of Collection Agencies

Convincing delinquent accounts to settle their balances can take quite a lot of time and effort. These are the reasons why businesses should let collection agencies take the wheel.

Collection Agency is the “Bad Guy”, you are not

By involving a professional debt collector, you are not directly involved in the collections activity. You can just maintain that it is the company policy to forward accounts for collections, now things are out of your hands. They should contact the agency directly for settling the balance.  

Collection laws

Welcome to the United States, there are complex and countless laws involved in attempting to collect your own money. Collection agencies are well versed with federal and state debt collection laws therefore they minimize the risk of getting sued back by the debtor.

Debtors are far more likely to pay when a Collection Agency is involved

Debt Collectors are experts in collecting debt, after all that is what they do all day long. They have access to several tools and services to effectively and legally recover your money. Debtors understand that giving false excuses or simply relocating to a new address is ineffective with a collection agency. It is nearly impossible to match the cost and recovery rates of a collection agency.

Businesses Have Better Things to Do

You have a business to run. Time spent drafting and sending collection letters, making phone calls, and keeping track of account statuses pulls personnel away from their normal duties. Depending on the volume of potentially bad debt you’re carrying, the amount of time your business can lose is significant.

It’s certainly worth attempting to collect funds owed before they become considerably past due. But once a customer has demonstrated a reticence to pay, further efforts on your part are likely to be unsuccessful.

Moving these delinquent accounts to a collection agency allows you to focus on finding new customers and on generating new income while the agency attempts to recover funds you likely can’t.

Collection Agencies Are Better Equipped for the Job

Collection agencies have a number of tools available to them that you don’t. Plus they have the benefit of single-minded focus. They don’t have to run your business while trying to collect debts.  Collecting debt is all they do, so they’re able to dedicate themselves to the task.

If you sell widgets online, your skills lie in widget sales and online commerce. Debt collection isn’t likely something you’re trained in or something that you know how to do well. But that is the primary focus for collection agencies, and so they have a significant advantage over you when attempting to recover the delinquent debt.

You just addressed the Collection Problems that every business faces

Most companies do not have dedicated people to handle overdue accounts receivable. Your existing employees are neither effective nor organized to handle the debt collection. Hiring a collection agency will help you to address even those accounts with low balances. Regardless you have high volume of unpaid invoices or just a few accounts, a collection agency will continue to work for you. You will be better advised on accounts with severe delinquencies, litigious customers, or when the debtors are difficult to locate. Hiring a collection agency will leave your employees less frustrated since internal staff hates doing debt collection.

Collection Services Only Cost You Money If They’re Successful

Most reputable collection agencies charge using performance-based contracts. They take a percentage of any monies recovered, which means you’re not risking anything by seeking their services. If they collect nothing from your delinquent accounts, you pay them nothing.

On the other hand, if they’re successful, you’ll pay a set percentage of the total funds recovered. But these are funds you likely would not have recovered on your own, and a percentage is better than recovering nothing at all.

Although most collection agencies offer low-cost & fixed fees based Collection Letters service as well which are extremely effective and recommended for accounts less than 120 days.

Other important benefits

Collection agencies can collect debt across all 50 states, in both Spanish and English. They also have a national network of attorneys who can assist if there is a need to take the debtor to the court. They will offer several payment options to the debtor and can even place the account to be paid off in installments. 

Cons Against Collection Agencies

Like any business, collection agencies aren’t right for every customer. Here are a few things to keep in mind when considering whether to hire a debt collector.

They Aren’t Cheap

Collection agencies charge a fairly high percentage for their services, often between 25% and 50% of the funds recovered, depending on the type of debt. But this is to be expected.

Delinquent debtors are typically transferred to a Collection Agency after 90 days of non-payment and the possibility of recovering anything from these accounts through the efforts of in-house employees is nearly zero. Money collected through collection agencies is cash you may have not got otherwise. 

Even with their expertise, a large amount of debt remains unrecoverable without invoking severe, and expensive legal actions. So collection agencies must support their businesses with the funds they are able to recover. It’s important to remember that without the help of a collection agency nearly all delinquent debt remains unrecoverable. Paying 50% on recovered funds is better than the alternative.

Federal laws restrict what a Collection Agency can do 

There are many debt collection laws applicable when Collection Agencies are trying to recover money from a debtor. A simple example is  “30-day” dispute period during which a debtor can tell a collection agency to prove he indeed owes the debt, or stop contacting him. The dispute period does not apply to the original creditor. Many states put original creditor and collection agency in the same bucket, which means the collection laws apply to either one trying to recover money from the debtor.

Slightly Higher Possibility of Sour Customer Relationships

Some customers just get agitated due to the mere fact that the account has been transferred to a collection agency when they themself have failed to fulfill the payment obligation despite your repeated efforts and reminders from your in-house accounting/receivables department. Do you even bother so much anyway to maintain a good relationship with these customers?

If you choose a collection agency that’s overly aggressive or one that employs unsavory methods for collecting on your accounts, those customers affected will likely think ill of you by the end of the process.

This is less than ideal because many customer accounts become delinquent due to circumstances out of your customer’s control. They often want to pay, but can’t. When their financial situations improve they could revert to being good, paying customers. But this is less likely to happen if a bad collection agency ruins the relationship.

Hire a Trustworthy, Well-Reviewed Agency

The negatives associated with collection agencies can be avoided by checking references and reviews for the agencies you’re considering to find one that employs industry best-practices, works to maintain healthy customer relationships, and take a fair percentage in exchange for their services.

The unfortunate reality is that attempting to collect delinquent accounts on your own is likely to net you nothing but heartache and wasted time. Trusting these accounts to an esteemed collection agency significantly improves your chances of recovering funds, and something is always better than nothing.

If you need a cost-effective collection agency that utilizes an amicable, diplomatic yet firm approach to recover your money then Contact us.
Filed Under: Debt Recovery

Can You Collect Debt After Writing It Off? (Recovery Guide)

If your business has been writing off bad debts without involving a Collection Agency, you might be leaving significant revenue on the table.

Many business owners believe that once a debt is “written off” for tax purposes, it is gone forever. This is a myth. A “write-off” is usually just an accounting entry to clear your books. Unless you have legally “forgiven” the debt in writing to the customer, they still owe you money, and you still have the right to collect it.

Here are the 8 most common reasons small businesses prematurely write off debt—and why you should reconsider.

1. “We’ve never used an agency before.”

The Fear: You are unsure what a Collection Agency actually does or if it’s worth the effort.

The Fact: You need to hire a professional to see the difference. A collection agency acts as an extension of your back office, immediately improving your cash flow by applying professional, consistent pressure that internal staff simply cannot replicate.

2. “It seems like too much hassle.”

The Fear: You think onboarding an agency involves complex paperwork and software integration.

The Fact: Modern collection agencies take the stress off your plate. We accept accounts via simple online portals or spreadsheets. Once you hand it over, we do the work. Your in-house employees cannot match the efficiency and recovery rates of a dedicated team equipped with skip-tracing tools and legal expertise.

3. “We’ll just make up the loss with new sales.”

The Fear: You accept the loss and try to offset it by getting new orders.

The Fact: This is dangerous math. If you have a 10% profit margin and write off a $1,000 debt, you don’t need $1,000 in new sales to break even—you need $10,000 in new sales just to recover that one loss. Recovering the cash you already earned is far more profitable than chasing new clients.

4. “Management won’t approve it.”

The Fear: Accounting and Receivables departments often struggle to convince Owners or CFOs to change company policy and assign accounts over 90 days past due.

The Fact: Cash flow is the lifeblood of a business. Management needs to understand that holding onto old debt doesn’t save money; it costs money in inflation and administrative time. (See our guide: Is Management Ready to Hire a Collections Agency?)

5. “We don’t know who to trust.”

The Fear: Choosing the wrong partner feels risky.

The Fact: Nexa Collections specializes in ethical, effective recovery. We are transparent about our methods and results. You don’t need to search endlessly; we are ready to help you today.

Need a Collection Agency? Contact us

6. “The commission fees are too high.”

The Fear: Since agencies charge contingency fees (a percentage of what is collected), owners are reluctant to “share” the money.

The Fact: Ask yourself: Would you rather have 100% of nothing, or 60% of something? Many businesses sit on these accounts until they become legally uncollectible (Statute of Limitations), resulting in a 100% loss. No agency recovers every dollar, but we will recover significantly more than zero, which is what you get if you do nothing.

7. “We don’t know when to send the account.”

The Fear: Waiting too long or acting too fast.

The Fact: The earlier you transfer, the better.

  • Best Practice: Transfer accounts after 60–90 days of non-payment.

  • Acceptable: Accounts under 1 year old are still very collectible.

  • Too Late: Accounts older than 3 years generally result in low recovery rates.

8. “It will ruin our reputation.”

The Fear: A Collection Agency will spoil the business relationship with customers. The Fact: This is the biggest myth of all. Professional agencies pursue a diplomatic, amicable, yet firm approach. We cannot threaten or harass; it is against federal FDCPA laws. We work with the debtor to find a solution (like a payment plan) rather than working against them. Our goal is to recover your money while preserving the relationship for future business.

The Bottom Line: It’s Not Too Late

To attempt the recovery of bad debts previously written off, they should be assigned to a collection agency without further delay. As long as the debt is within the Statute of Limitations for your state, there is still hope.

Don’t let your hard-earned revenue vanish.

Filed Under: Debt Recovery

Financial Collection Agency | Secure Bank & Credit Union Recovery

Financial institutions of all sizes frequently struggle with accounts receivable, often losing significant resources chasing the 2%–3% of accounts that refuse to pay. When internal follow-ups fail, a professional financial collection agency is essential to recovering unpaid bills without draining your internal team’s productivity.

Nexa provides a reputation-safe approach, equipped with all 50-state collections license, offering free credit reporting, free litigious debtor check, free bankruptcy scrub, and zero onboarding fees. Secure – SOC 2 Type II & GLBA compliant. Over 2,000 online reviews rate us 4.85 out of 5. 

Need a Collection Agency? Contact us

The Cost of Inaction

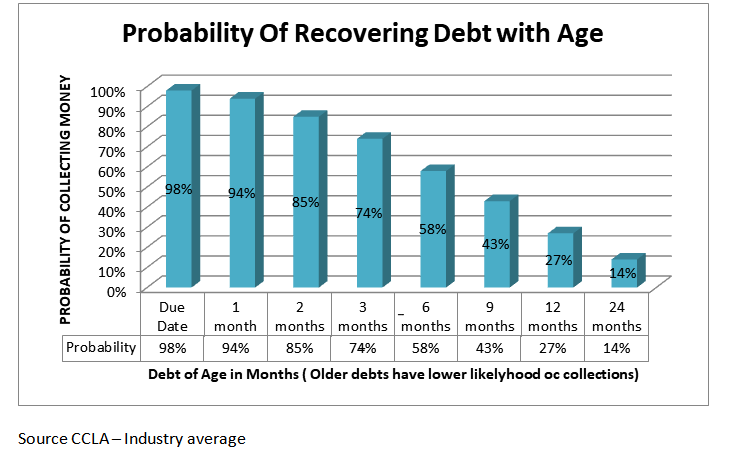
Writing off delinquent loans, mortgages, or overdraft fees directly impacts your profit margin and can lead to severe cash flow issues. Data shows that accounts not resolved within the first 90 days rarely get settled. In fact, the likelihood of recovery drops by approximately 10% for every month that passes.

Banks, credit unions, and fintech firms require a partner that understands the delicate balance between firm recovery and brand protection.

Debt Recovery Chances

Summary of Financial Collection Services

Service Tier Best For Strategy & Cost
Phase 1: Specialized Letters Accounts < 120 days past due. Low Cost: Approx. $15 per account. Debtors pay you directly; no percentages taken.
Phase 2: Professional Calls Accounts > 120 days past due. Contingency-Based: No Recovery, No Fee. Includes intensive skip-tracing and direct negotiation.
Phase 3: Legal Escalation High-balance, unresponsive accounts. Recommended by attorneys if all other professional attempts are exhausted.

Why Financial Institutions Choose Nexa

1. Strict Regulatory Compliance

We operate with a “compliance-first” mindset. Our team is rigorously trained in FDCPA, FCRA, and CFPB regulations to ensure your institution is never exposed to unnecessary legal risk.

2. Enterprise-Grade Security

We handle sensitive financial data with the highest level of protection. Nexa is SOC 2 Type II and HIPAA compliant, utilizing advanced encryption and secure portals to maintain data integrity.

3. Reputation-Safe Recovery

We understand that your customers are your greatest asset. Our “diplomatic yet firm” approach ensures debts are recovered while keeping your brand’s reputation intact. We provide a 50-state licensed solution that scales with your business.

4. Advanced Technology

From bankruptcy scrubs to automated credit reporting, we use high-tech tools to identify the most “collectible” accounts, ensuring your recovery efforts are targeted and efficient.

blank


Frequently Asked Questions

When should we move an account from internal collections to Nexa?

Most financial institutions see the best ROI when transferring accounts between 60 and 90 days past due. Waiting longer significantly decreases the probability of full recovery.

Are there any setup or onboarding fees?

No. Nexa offers zero onboarding fees, allowing you to start recovering funds immediately without upfront capital investment.

How do we track the progress of our accounts?

Clients receive access to a secure, real-time portal to monitor recovery status, view reports, and manage documentation.

Need a cost-effective partner for your financial receivables? Contact Us Today

Filed Under: Debt Recovery

Will a Collection Agency Ruin My Business Relationship?

It isn’t uncommon for people to have unpaid debt wind up at a Collection Agency. Sometimes they forget that they have an outstanding balance and other times, they simply don’t have the money to pay the lump sum.

If you are a business owner, you may have been forced to make the difficult decision to send your delinquent customer or a business partner to a debt collector.

Most B2C debt is transferred to a collection agency after 60-90 days of non-payment. Most B2B partners try to postpone making this move, but if they are dodging your requests for payments, you may have not have had any other choice. The question is, will this move ruin your business relationship?

Debt collectors are often met with a negative connotation. Your delinquent customer or a business partner probably won’t be happy to learn that you sent their balance to a collector. The good news is, debt collectors use a diplomatic approach specifically so that your business relationship remains in good standing. They understand the importance of business relationships and work hard to preserve it. They will work with the debtor in order to consolidate or get rid of their debt entirely.

To get a full grasp of this concept, let’s look at how a collection agency works in order to determine how it affects your business relationship.

Understanding How Debt Collectors Work

If you decide to send someone’s unpaid balance to a collection agency, they will be immediately notified; usually via phone call or a collection letter. These contacts are often met with apprehension because being sent to collections can possibly effect the debtor’s credit score if the creditor has requested the collection agency to report the debt to the credit bureaus. And, naturally, this can ruin their chances of getting a car, a house, or a business loan.

When Debt Is Sent To Collections

It’s difficult to know when it is time to write off the unpaid debt as a loss. If you have been working with your business partner for some time, you may wait for months or even years before you decide to send their debt to collections. However the chances of recovering the past due amount go down by about 10% each month. The longer you wait, higher the chances are that you will never recover your money.

There is no set dollar amount or time frame that depicts when it’s time to write off unpaid balances. If you get the impression that your partner isn’t going to pay off their capital or they haven’t made an effort to set up payments, you should absolutely cut your losses.

Debt can be sent to a collection agency 31 days past the due date, though many wait until after three to six months of nonpayment. It is recommended to use Debt Collection Letters after 60 days past due date. If the debt is over 120 days or more past due then go for the Collection Calls service.

How It Affects The Debtor’s Credit Score

Not everyone’s credit score is affected unless the original creditor instructs the collection agency to report the debt to the credit bureaus. Generally speaking, those with higher credit scores are often penalized more points than those who have a lower credit score. The amount owed will also determine how many points will be shaved off their credit score.

How A Collection Agency Will Approach Your Delinquent Customer or Business Partner

If someone owes you money, knowing how collection agencies approach debtors can help you rest easy about your decision. In the past, the tact of a debt collector was to make relentless phone calls demanding payment. And if you’re looking to maintain your business relationship, having put your partner in this situation is obviously going to cause some tension.

However, now with the Fair Debt Collection Practices Act (FDCPA), agencies use a more subdued approach when contacting your partner or associate.

Talk To Your Associate First

As the original creditor, you can only send someone to collections 31 days after the payment is past due. The best practice to maintain your business relationship is to talk with your associate first. Have a system in place to send out reminders that payment is due. This includes regular emails, phone calls, and other points of contact.

Approaching your associate about their late payment first can help preserve your relationship. This is recommended instead of sending them straight to collections without warning or notice of this action.

 The Fair Debt Collection Practices Act

This act was created once it had been made clear that, “Abusive debt collection practices contribute to the number of personal bankruptcies, to marital instability, to the loss of jobs, and to invasions of individual privacy.” Along with other reasoning established in this act, debt collectors may not be abusive or vexatious when approaching debtors.

Instead, collection agencies will approach your partner in an amicable way. They may even give guidance on setting up payments to their debt. With these practices, you can rest assured that sending someone’s debt to an agency should not ruin your business relationship. We only recommend notifying your business associate first and educate them on your impending decision to write off their debt. Once you’ve made your decision, the debt agency will take the reins to help settle the outstanding balance.

Conclusion

No Collection Agency can guarantee that your business relationship with the debtor will remain intact during the collection process. However, this article simply conveys you that all good collection agencies use diplomatic and an amicable way to collect a debt, rather than the common notion that debt collectors are intensive, abusive or threatening. This drastically ups the chances to retain your business relationship. If any agency uses threat tactics, it just violated the debt collection laws.

Filed Under: Debt Recovery

Amicable Debt Collection: Don’t Lose Customers

crm small business
It’s an unfortunate reality in business that not everyone pays their bills. No matter how careful you are about setting proper payment terms and sending reminder letters, there will always be some portion of your receivables that are difficult to collect.

Classically, the process for recovering a portion of the debt owed has been to either outsource the uncollectable debt to a “Collection Agency”. A Collection Agency will attempt to collect the delinquent debt and charge a percentage of any funds recovered.

Historically the methodology of collecting debt was not amicable at all till the US government intervened and introduced debt collection laws like the FDCPA and TCPA. FDCPA is a consumer protection amendment, establishing legal protection from abusive debt collection practices.

Earlier the Debt collectors regularly badgered delinquent accounts, threatening legal action when necessary. These fear tactics could be effective, but they also soured any future relationship between the debtor and the original company.

And this was a problem because many people that fall behind on payments don’t do so out of malice, or a desire to steal from the companies they do business with. They have a legitimate reason when their bills go unpaid. They even have a strong desire to pay off their bills as soon as their financial condition improves.

They may have lost a job, encountered large, unexpected expenses, or suffered some other financial setback that prevented them from settling their debts. These are people that want to pay, but can’t for reasons outside of their control.

Given time, they would likely return to being customers in good standing, once their circumstances improved. But the likelihood of this happening is drastically reduced when standard, confrontational debt collection techniques are employed.

There’s a Better Way

Confrontational debt collection assumes that your delinquent customers are terrible people, actively trying to rip you off, and it treats them that way. Since this frequently isn’t the case, it’s far better to try and come to an amicable solution that respects your customer’s situation and works to establish repayment terms they can afford.

Consider someone that’s missed a few paychecks and doesn’t have the savings to pay what they owe. Calling repeatedly and threatening lawsuits if they don’t immediately settle their balance isn’t going to change their situation. If they can’t pay, they can’t pay.

A structured payment plan, on the other hand, would reduce the amount they need to pay right now, allowing them to pay off the remainder in affordable increments. Brokered negotiations allow both parties to come to a solution that works for them, allowing the creditor to recover some portion of the money owed them while providing the debtor payments that don’t further damage their financial stability.

Amicable recovery is a fundamentally different way of approaching debt collection because it assumes the best about people instead of the worst. It’s less confrontational and more cooperative. As a result, it’s generally more effective, and it’s certainly less expansive than the legal proceedings that might be necessary without it.

If you’re facing uncollectable receivables, it’s worth considering amicable recovery solutions before resorting to less friendly methods. Your customers likely want to pay you, and if you work with them, they can. And when they do, it’s likely that they’ll be grateful, loyal customers for life.

Looking for a collection agency that employs an amicable approach to collect debt: Contact us

Filed Under: Debt Recovery

Contingency Collection Service: No Collection-No Fees

Contingency Collection
Contingency Collections, also called Traditional Collections, is the most popular debt collection service to recover your money from defaulters.

The concept of “Contingency debt collection” is really simple – Once the Creditor has tried enough to recover his money from the Debtor without success, he finally hires a Professional Collection Agency to collect money from the Debtor. The Creditor does not pay anything for the Collection Agency’s recovery efforts till they actually recover money from the Debtor. The Agency deducts the contingency fees per the contract and returns the remaining money to the Creditor. No other costs or hidden fees.

For example:
If a Creditor assigns an account to a Collection Agency with an outstanding amount due of $1000, and a collection agency charges a 40% contingency fee thenScenario 1: If the Collection Agency recovers the full amount, then the Creditor gets $600 and the Agency keeps $400
Scenario 2: If the Collection Agency recovers only half the amount ($500) then the Creditor gets $300 and the Agency keeps $200
Scenario 3: If the Agency recovers nothing, they get nothing.

No Collection – No Fees

Benefits of Contingency Collections:

1. If a collection agency does not recover any amount, it results in a net loss for them. (Why?) A collection agency invests resources, manpower and uses expensive softwares to collect money from the debtor, regardless a recovery is made or not. Therefore, the Collection Agency puts its best effort and resources into recovering your money.

2. The Creditor has nothing to lose. In fact, most of this past-due debt would have been written off as a loss, all recoveries translate into a nice profit.

3. By involving a Collection Agency, you have just given a powerful message to the debtor. He is more likely to pay now than ever before.

4. Collection Agencies are up to date with the latest debt collection laws, which lowers the chances of a counter lawsuit versus when your own under-trained employees were attempting to make a recovery.

5. Most agencies can do contingency debt collections in both English and Spanish, even attempting to locate a missing debtor using advanced skip tracing.

6. Biggest advantage is off-loading the hard work of debt collection to a 3rd party. Who wants to follow up with a customer/patient again and again? By outsourcing those hard-to-collect accounts, you have also outsourced all the stress and stopped wasting too much time on accounts that have a very low chance of ever paying anyway.

7. Many collection agencies offer customizable strategies and plans to meet the specific needs of businesses, increasing the likelihood of successful debt recovery.

8. Collection agencies keep records of the debts they attempt to collect and the process they follow. This documentation can be useful if a business decides to write off the debt as a tax deduction or if it ends up in litigation.

Are you looking for a cost-effective collection agency with low contingency rates? Contact us

Note: Contingency collections / Collection Calls are best suited for accounts over 120 days past due. For accounts less than that one should consider the flat-fee-based Collection Letters service.

Filed Under: Debt Recovery

  • « Go to Previous Page
  • Page 1
  • Interim pages omitted …
  • Page 38
  • Page 39
  • Page 40
  • Page 41
  • Page 42
  • Interim pages omitted …
  • Page 55
  • Go to Next Page »

Primary Sidebar


accounts receivable

Need a Collection Agency?
Kindly fill this form.
We’ll get in touch with you

    Please prove you are human by selecting the star.

    Compliance & Security

    • SOC 2 Type II Certified: Third-party audited data security and strict privacy controls.

    • HIPAA Compliant: Secure, legal processing of medical and municipal EMS accounts.

    • PCI-DSS Level 1: Highest tier of data encryption for secure payment processing.

    • FDCPA & FCRA Aligned: Full legal adherence to federal consumer protection laws.

    Recent Posts

    • Why Dental Patients Dispute Bills: The Nexa Collections Dental Account Dispute Index
    • 2027 Commercial Collections Benchmark: U.S. Late Payments, AR Risk and B2B Collection Trends
    • Bulk Account Placement: What a Collection Agency Actually Needs From You
    • Nationwide Debt Collection Agency Serving U.S. Cities
    • Chula Vista Collection Agency for Medical, B2B, Schools & Business Debt
    • Corpus Christi Collection Agency: Itemized Bill Rules for Practices
    • Riverside Collection Agency | For Logistics, Medical, Schools & Business Recovery
    • Collection Agency for Large Balances: High-Value B2B Debt Recovery

    Featured Posts

    • Propane & Heating Oil Debt Collection: Recover Unpaid Fuel Balances & Protect Dealer Reputation
    • Enterprise Collection Agency for Large Business: B2B & B2C Recovery
    • Nationwide Debt Collection Agency Serving U.S. Cities

    Copyright © 2026 NEXACOLLECT.COM | This content is provided for general informational purposes only and should not be considered legal advice. Collection laws and requirements may vary by state, account type, documentation, debtor status, and specific facts. Please consult qualified legal counsel for guidance regarding your particular situation. Nexa and its authorized collection partners service accounts in accordance with applicable federal and state collection requirements. Visit our home page to know more about us.

    X
    Need a Collection Agency?
    Contact Us