• Skip to main content
  • Skip to primary sidebar

Nexa Collections

  • Home
  • Serving
    • Medical
    • Dental
    • Small Business
    • Large Business
    • Commercial Collections
    • Government
    • Utilities
    • Fitness Clubs
    • Schools
    • Senior Care Facility
  • Contact Us
    • About us
    • Cost

Debt Recovery

Hospital Revenue Cycle Management | Early-Out & Bad Debt Recovery

Delivering exceptional collection results while engaging in compassionate patient interactions to maintain hospitals’ reputation are the core principles of our medical debt collections. We emphasize patient satisfaction and have a proven track record of successful late-stage debt collections.
Collection agency for hospital bills

Nearly all hospitals in America face a significant burden of unpaid medical bills. Emergency room visits, uninsured patients, those with limited insurance coverage, and the rising cost of healthcare contribute to an increasing portion of out-of-pocket expenses for patients. We can help you collect your claims from insurance companies too.

Need a Collection Agency? Contact Us

Using Epic Systems? Collection Utility is available too!

Proudly Serving Hospitals Nationwide, References Available.

In addition to unpaid patient bills, hospitals often have outstanding receivables with insurance companies, which may delay or dispute claims for various reasons. An experienced hospital collection agency can manage these unpaid patient bills and even handle collections from insurance companies when necessary.

A medical collection agency should have a deep understanding of the patient-doctor relationship, insurance laws, HIPAA privacy laws, and several debt collection laws that vary by state. Hospitals also require a multilingual collection agency to recover money from Spanish-speaking patients.

Unpaid medical bills remain a persistent challenge for healthcare providers, impacting both financial stability and patient well-being. Here’s a closer look at the issue and contemporary strategies for tackling it effectively:

The Scale of the Issue

Unpaid medical bills constitute a significant financial strain on hospitals and healthcare facilities. According to the latest figures from the American Hospital Association, uncompensated care—which includes charity care and bad debts—totaled approximately $41 billion annually. These numbers can fluctuate due to changing economic conditions, evolving insurance landscapes, and healthcare policy modifications.

Why Do Medical Bills Go Unpaid?

Several factors contribute to patients failing to pay medical bills:

  • High Deductibles: Rising popularity of high-deductible health plans leaves many patients facing large out-of-pocket costs.
  • Insurance Issues: Lack of insurance or inadequate coverage leads patients to shoulder significant expenses.
  • Complex Billing: Patients often find medical bills confusing and challenging to understand, causing delays or non-payment.
  • Financial Priorities: Patients might prioritize other immediate expenses, such as housing and utilities, over medical bills.

Impact on Healthcare Providers

The financial strain from unpaid bills forces healthcare facilities into difficult decisions:

  • Reduced Resources: Hospitals may cut budgets, reduce staffing levels, or eliminate less profitable services.
  • Debt Sales: Many hospitals resort to selling unpaid debts to collection agencies at significant discounts, incurring considerable losses.

Consequences for Patients

Patients also face substantial repercussions from unpaid medical bills:

  • Credit Damage: Unpaid debts sent to collections can severely damage credit scores, limiting patients’ future financial opportunities.
  • Stress and Anxiety: Debt collection actions increase stress, exacerbating health problems and negatively affecting overall well-being.

Available Assistance Programs

Recognizing these challenges, healthcare providers and governments offer various assistance programs:

  • Charity Care Programs: Many hospitals provide financial assistance or sliding-scale payments based on income and financial need. If a patient qualifies for Financial Assistance (501r compliance), we encourage them to apply for it instead of harassing them. This protects your non-profit status.
  • Government Assistance: Medicaid Disproportionate Share Hospital (DSH) payments help partially offset hospitals’ costs for treating low-income, uninsured patients, though gaps often remain.

Modern Solutions to Tackle Unpaid Medical Bills

Hospitals and policymakers are increasingly adopting innovative solutions:

  • Transparent Pricing: Clear, upfront pricing helps patients understand expected costs, reducing surprises and disputes.
  • Improved Financial Counseling: Enhanced counseling services guide patients through available payment plans and assistance options.
  • Technological Innovations: Leveraging technology to simplify billing processes, enabling easy-to-understand digital bills and online payments.
  • Insurance Reform: Policies advocating for broader insurance coverage and lower deductibles can significantly reduce unpaid medical debt.
  • Collaborative Debt Resolution: Hospitals collaborating proactively with patients through structured payment plans or settlements, preventing debts from escalating to collections.

By adopting comprehensive, patient-focused financial practices and policies, hospitals can significantly reduce the impact of unpaid medical bills, improving financial stability for providers and patients alike.

Healthcare finance can change over time. It’s a good idea to check the latest statistics and policies for the most up-to-date information on this topic.

Frequently Asked Questions

What’s the difference between “early-out” and “bad debt” recovery?

Early-out outreach happens before an account is formally charged off, typically presented as an extension of the hospital’s own business office. Bad debt recovery applies once an account has been written off internally and placed with a collection partner. The tone, timing, and urgency of each phase are different, and treating them the same tends to hurt both.

Can a collection partner recover from insurance companies as well as patients?

Yes. Not every outstanding balance is the patient’s responsibility — claims that an insurer has delayed, underpaid, or disputed are a separate category of receivable, and pursuing those directly with the payer is a normal part of hospital AR recovery, not something limited to patient-owed balances.

Do you screen patients for financial assistance eligibility before pursuing collection?

Yes. For nonprofit hospitals subject to IRC § 501(r), screening for charity care or financial assistance eligibility before collection isn’t just good practice — it’s a federal tax-exemption requirement. Accounts are checked accordingly before collection activity proceeds.

Do you integrate with hospital billing systems like Epic?

Yes, integration options are available for hospitals using systems like Epic, so placed accounts and payment updates can move between systems without manual re-entry.

Can you collect from Spanish-speaking or other non-English-speaking patients?

Yes, multilingual outreach is available. A meaningful share of patient balances involve a first language other than English, and language barriers shouldn’t be the reason a resolvable account goes unpaid.

How does uncompensated care affect a hospital’s collection strategy?

Uncompensated care (charity care plus bad debt) is tracked separately from a hospital’s collection efforts, but the two are related — screening for financial-assistance eligibility before collection generally reduces how much otherwise-collectible debt gets miscategorized as bad debt in the first place.

Is patient billing data handled under HIPAA during the collection process?

Yes. Patient billing records carry protected health information regardless of where an account sits in the early-out or bad debt process, and are handled under HIPAA-aligned procedures throughout, with a Business Associate Agreement executed where required.

Need a Collection Agency? Contact us
Filed Under: Debt Recovery

10 Signs Your Invoice May Not Get Paid on Time

late invoice
When you’re running your small business it can be difficult to stay on top of everything. In the middle of incessant daily workload, one aspect that may get overlooked is that an invoice may not get paid on time.

Whether you’re a doctor, a lawyer, or a dentist, the chances of a client’s invoice (or several invoices) going awry the inevitable. If you want to decrease the number of unpaid client invoices, your best bet is to stay on top of your practices and look for loopholes in your payment process.

So, here are 10 signs your invoice may not get paid on time.

1. Your Client’s Contact Information is Wrong

The most common way that a client invoice will not be paid on time is if their contact information is wrong. This is usually done in error, but if the client’s email, phone number, and address all are wrong, then it’s safe to assume this was done intentionally. These are the people who never planned on paying for your services in the first place.

The best way to catch these scammers is to test their contact information before delivering your service. If they don’t reply or answer to phone calls, emails, or other forms of communication, then you may want to consider handing them an invoice ahead of time or request a prepayment.

2. Your Client Pays with a Check

In today’s tech-savvy world, it seems safe to assume that your clients will want to pay by credit card, cash, or a mobile payment service like Venmo or Paypal. However, there are those select few who still hold fast to their written checks and try to use them as a payment method.

One of the reasons that payment in checks have fallen by the wayside is because they take longer to process, they can bounce, and they are ultimately less convenient. If your client tries to pay with a check, make sure to routinely follow up with the payment processor else your invoice may not get paid on time.

3. They Aren’t Organized

A client who is disorganized is instantly going to cause you problems. While being scatter-brained isn’t a deal-breaker, it should serve as a red flag about how the payment is going to be. These clients may be picky about what they want or they may change their mind multiple times during your agreement with them.

Either way, this sort of mentality should be a clear indicator that this client may have trouble remembering to pay their invoice. Either that, or they may ask for revisions for the delivered work or clarification before relenting to payment.

4. You Aren’t Organized

Understandably, running a small business requires you to lean on other people for support. But even if you have someone in charge of your invoice processing, it is still up to you to make sure that your invoices get paid on time.

Being unorganized is not a luxury that entrepreneurs can have. If you haven’t laid out terms for your services or you procrastinate on sending invoices, you will create a snowball effect that will ultimately collapse your enterprise. Not only should your finance department be organized with payment spreadsheets and reminders, but your employees should be dutifully aware of the process to get invoices paid on time.

5. You Don’t Have Multiple Payment Options

Payment options are a lucrative strategy to have in place simply because it serves as an incentive to get invoices paid on time. If you only allow for credit cards or checks, then you are doing you and your clients a disservice. Multiple payment options make it effective and easy for clients to pay you (on-time).

Payment channels such as PayPal offer safe and secure deposits. Most people these days are familiar with these services, so following up with a variety of payment options will motivate your client to pay on time.

READ MORE: Customer Relationship Management for Small Business


6. Your Client Questions The Invoice

Another obstacle that results in late payments is if your client questions your invoice. It could be that they are just confused about the formatting (which we’ll get to next) or there are additional fees that you didn’t disclose upon your initial agreement.

This is why it is vital to have a clear outline of your service or product and that your invoice directly reflects what your client received. Having a questionable invoice sets a precedent for your clients not to trust your business – and that can lead to a downfall in your reputation.

7. You Don’t Have Correct Invoice Formatting

Following up with that, it’s always important to have a cohesive and clear format to your invoices. Make sure to brand your invoice with company logos, contact information, and an address. Your invoice should also always be itemized, even if there is a contract in place that specifies the extent of your services. Having a clear invoice will make it next to impossible for your clients to question your services, therefore leading to invoices getting paid on time.

Here are a few other items you should have in your staple invoice format:

• Invoice number
• Invoice billing date
• Service start date
• Service end date
• Payment terms and options

8. You Don’t Follow Up

One misstep that will lead to a pile of unpaid invoices is not having a follow-up schedule system in place. You should always be aware of when your clients’ invoice should be paid, that way you can send out payment reminders. One study confirms that only 18% of 90-day invoices will actually get paid. So essentially, if you wait more than 30 days to send follow-up reminders, you are less likely to get paid at all.

On top of sending out invoice reminders, it’s important that you are sending the invoice to the correct person. This falls in line with your company’s organization. If you are a B2B business, then you may have to send the invoice to another department who takes care of payments. Ask the person you are working with directly who to send the invoice to. Then, do your due diligence to send the invoice and reminders to 2-4 people in that company so that someone knows to pick up the bill.

9. There Isn’t a Contract

Some freelance businesses don’t work on a contract basis for lack of knowledge on how to set them up. But working without a contract is like accepting a job without knowing the payout.

A contract is necessary to outline your company’s restrictions, payment options, fees, and expectations. It may seem like an unnecessary maneuver, but realistically it protects you and it protects your client should any of the conditions change throughout your business together.

10. You Don’t Assign a Late Fee

The most striking motivation to have your invoice get paid on time is to set up a late fee. Without implementing a late fee charge, your clients have nothing to lose by paying you late (or not paying you at all).

If you make it clear in your contract, invoice, and initial meeting that all invoices must be paid in full within 30 days, you will be more than likely to start seeing regular payments. If not, clients may take that as a sign that they are free to pay as much as they can whenever they can.

Contact a Collection agency

If you are finding it hard to get things in order or are stuck with too many accounts receivable, the do not hesitate to hire a collection agency. Do not attempt to hire a collection agency near you, instead hire one which is good, has higher collection rates.

Filed Under: Debt Recovery

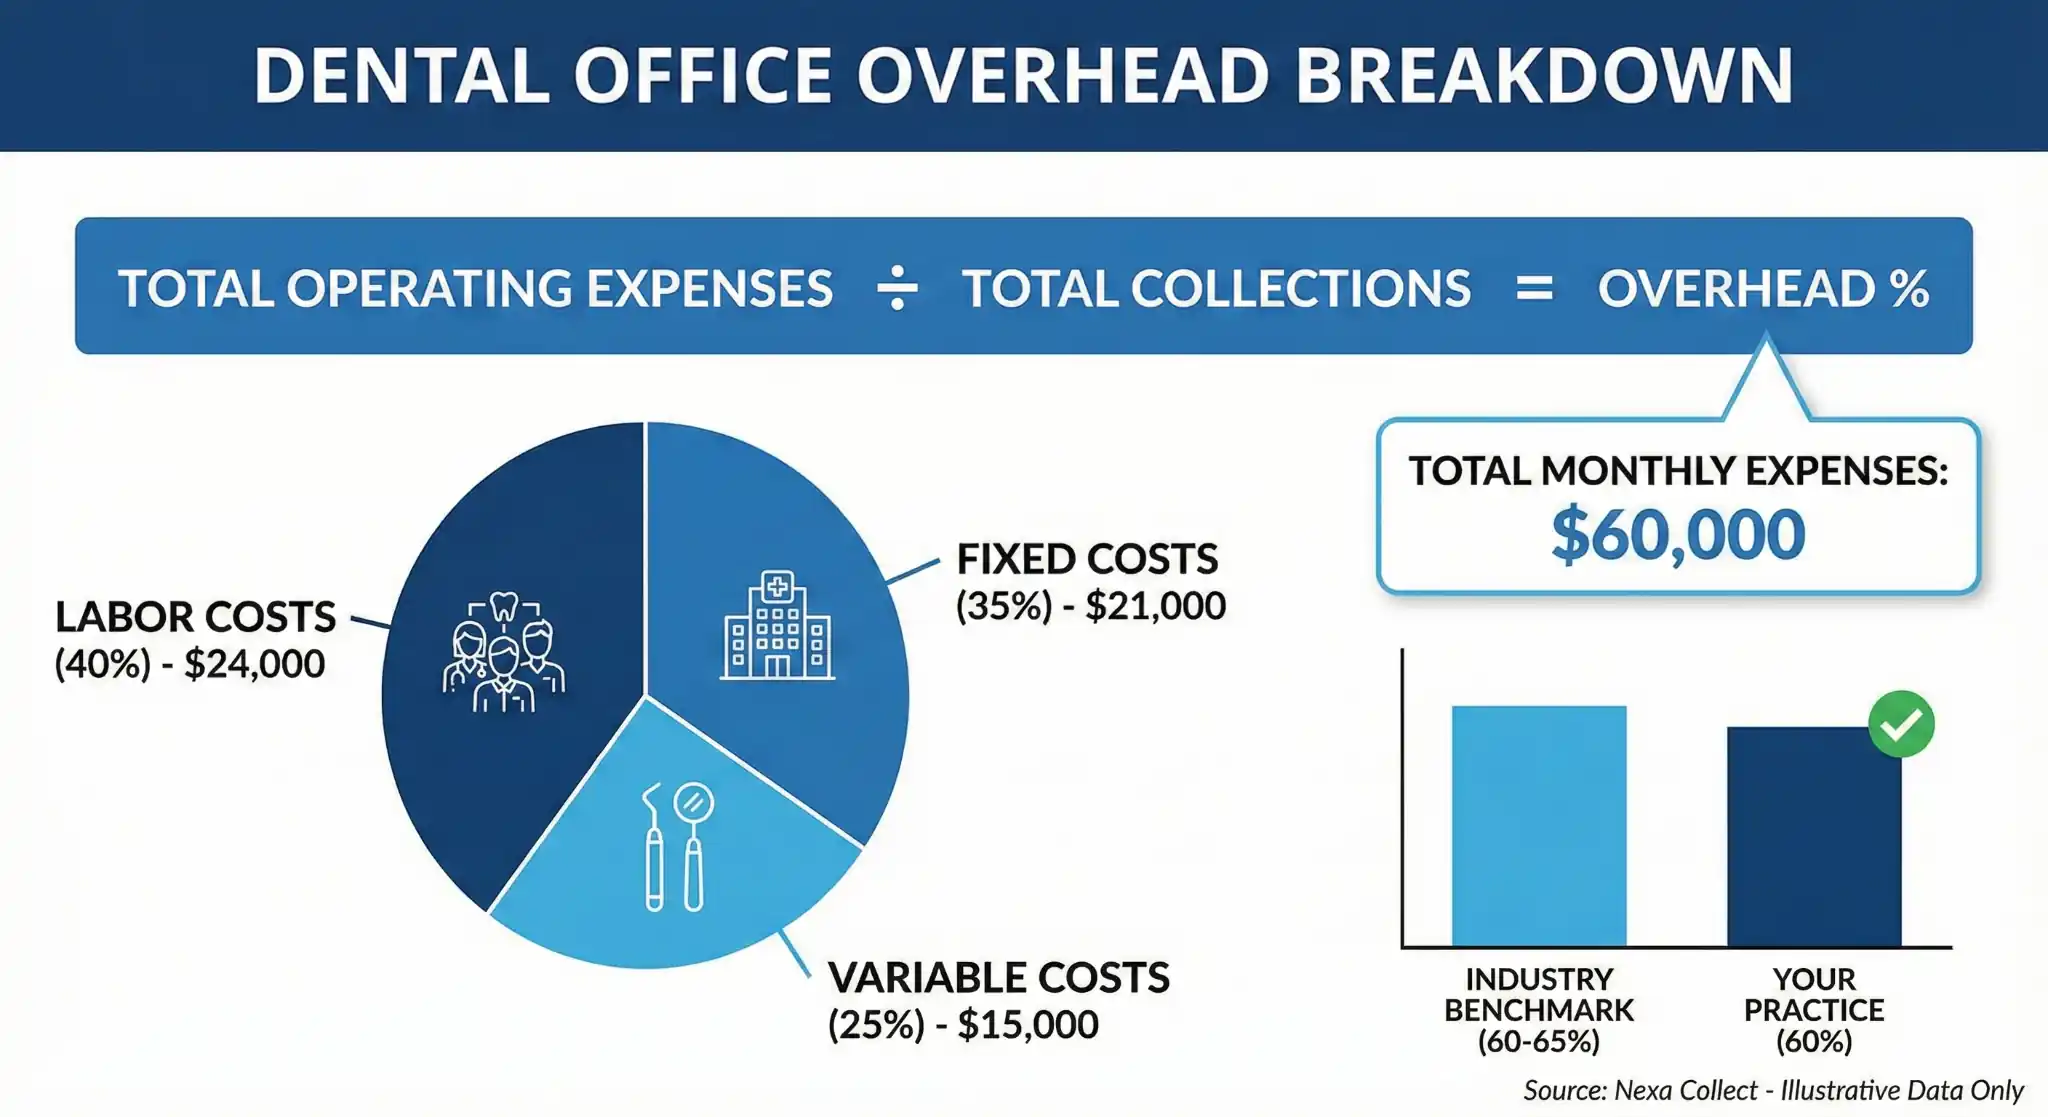
How to Calculate Dental Office Overhead

The Simple Guide to Profitability

In dentistry, “business” does not always equal “profitability.” You can have a packed waiting room and still struggle with cash flow if your overhead is out of control. Calculating your overhead isn’t just an accounting chore—it’s taking the financial pulse of your practice.

The Basic Formula

To find your overhead percentage, use this simple calculation:

(Total Operating Expenses ÷ Total Collections) x 100 = Overhead %

Example: If your annual operating expenses are $700,000 and your total collections are $1,000,000, your overhead is 70%.

blank


Step 1: Categorize Your Expenses

To get an accurate number, group your costs into three main buckets:

  1. Fixed Costs (The “Stay Open” Costs):
    These don’t change regardless of how many patients you see.

    • Rent/Mortgage

    • Utilities & Software Subscriptions

    • Insurance (Malpractice, Business)

    • Loan Payments

  2. Variable Costs (The “Production” Costs):
    these fluctuate based on your volume.

    • Dental Supplies (Gloves, composite, impression material)

    • Laboratory Fees

  3. Labor Costs (The Biggest Slice):

    • Staff Salaries & Benefits (Hygienists, Assistants, Front Desk)

    • Payroll Taxes

    • Note: Do not include the owner-dentist’s personal salary here.


Step 2: Know the Benchmarks

Where does your practice stand? According to industry standards, here is the breakdown of a healthy practice:

  • Total Overhead: 60% – 65% (The “Sweet Spot”)

  • Staff Labor: 24% – 28%

  • Dental Supplies: 5% – 6%

  • Lab Fees: 8% – 10%

  • Facility/Rent: 7% – 9%

The Red Flag: If your overhead is consistently above 75%, you aren’t running a business—you’re running a non-profit. It’s time to audit your supply waste or re-evaluate your scheduling efficiency.


Step 3: Increase the “Gap”

You can improve your overhead in two ways: Cutting costs or Increasing production. * Audit your supplies: Are you over-ordering?

  • Optimize the schedule: Are there gaps in the day where you are paying staff but not seeing patients?

  • Review Lab Fees: Negotiate better rates with your primary lab partners.

The Bottom Line

Understanding your overhead turns you from a “worker in the practice” into an “owner of the business.” Track these numbers monthly to ensure that your hard work translates into the take-home pay you deserve.

Filed Under: Debt Recovery

How To Benchmark Your Dental Practice

Dentist
If you are continuously looking for ways to set goals for your dental practice, your best bet could lie in your Dental AR benchmarks. Generally, when dentists discuss how to benchmark their practice, they will look at factors such as finding ways to reach new patient number goals. However, taking a look at your accounts receivable and delegating where your practice is having shortfalls will help in building a more profitable business structure.

Assigning dental accounts receivable (AR) benchmarks will help in not only growing a financially healthy business, but it will take off the weight that comes each time you sit down to pay the bills. And outlining methods in which your practice can meet these goals can only be done by laying out your current accounting situation and finding solutions.

Step 1: Set A 90-Day Goal

There is some debate on what the maximum age of your accounts receivable should be. Some believe only 20% of your AR should be over 60 days, while others suggest that you shouldn’t have any after a period of three months.

Falling in line with this strategy, you should at least set a benchmark for 90 days. That gives you three months to regulate your accounts receivable. At the end of those three months, your AR should, at the very minimum, make up 80% of your current patients’ payments. The other 20% can be made up of outstanding balances, but again, this number is pretty high. You can set your benchmarks for even better numbers depending on your current finances.

Step 2: Develop Sheets For Monthly Comparison

In relation to setting your dental AR benchmarks, it’s imperative that your monthly payment spreadsheets can be compared side by side. In other words, make sure you have your AR formatted so that you can compare January to February, February to March, and so on. At the top of each month, list your current AR followed by your goals. You should also have sections in these file dedicated to other contributors, such as the monthly number of credits, the amount or percentage of payments that are over 90 days, and the insurance estimation.

These sheets can also help highlight over the counter (OTC) collections which, as a general rule of thumb, should not exceed 45% of your office’s current production rate. In essence, a side-by-side spreadsheet of your AR will be immensely helpful if you are looking into news ways on how to benchmark your dental practice.

Step 3: Ensure Consistency in Payments

Besides automated computer filings, the spreadsheets like the ones mentioned above can help you see where there are inconsistencies in payments. Moreover, they will be able to easily indicate who is behind and by how much. These are the people you will need to reach out to first for payments (or risk sending them to collections). Then you can set a benchmark to determine the percentage of your collections so that you can make adjustments in processing payments.

In order to ensure consistency in payments, you need to have a strict regime about billing responsibilities. How often are reminders being sent out? Who is sending them out? Even with the trust in your team, it’s important to set standard operating procedures that indicate these responsibilities. You can implement a call log that references each time your office calls a patient for payment. This should be done for all email correspondences as well.

If your specific clientele is prone to missed payments, one way to help both them and your AR is to offer them a solution. It would be beneficial to accept credit partners like CareCredit from your patients to ensure your costs are being met at all times.

Step 4: Set Your Dental AR Benchmark at 1.0

This can be hard to master in a month-to-month benchmark goal. Having a dental AR benchmark at 1.0 can be difficult, but definitely not impossible. At this rate of performance, your production will be on par with your AR. In other words, if you’re producing $50,000 worth of production in your dental office in July, then your accounts receivable in July should reflect the same number.

In order to get to this benchmark, it’s important to follow the aforementioned procedures. But, like most financial hiccups, these things take time to remedy. If your AR is nowhere near this number, you should take your most recent AR numbers and use them to reflect in a year from now.

That’s right; you can take a full year in order to balance out your finances. But at the end of the year, if your dental AR benchmark isn’t met at the recommended 1.0, you may have bigger problems. However, a year will give you enough time to determine how much your collection rate is after taking out yearly production adjustments (i.e. charity or discounted procedures).

Step 5: Reduce Your Billing

And on top of everything, another benchmark that you should implement for your accounts receivable is a reduction in your billing process. And while you still need a regime for reaching out to patients for payment, this should be done in moderation.

Billing is radically overpriced; a single statement can cost anywhere from $5 to $10. Multiply that by the number of patients in your AR, and you have another hefty bill to deal with. And unfortunately, billing is a service all dentists need in order to run their business.

To cut back on costs, set a benchmark on how often you will bill your patients. By the end of the year, cut that number in half. You will want to send out bills well before the 90-day benchmark, and you can always send emails as an additional reminder. Whatever the case may be, a reduction in your billing will help ensure that your production and AR balance each other out by the end of the year.

If you need collections assistance in order to set benchmarks for your dental practice, contact us, we will ensure that your dental AR benchmarks will get easier by the year. We will assist you in reducing your accounts receivable by collecting money from unpaid bills, thereby improving your cash flow.

Filed Under: Debt Recovery

Credit Union Debt Collection: Recover Member Balances & Protect Community Trust

Credit unions run on trust their members can feel, which makes a badly handled delinquent account a different kind of risk than it is for a bank. Recover the balance the wrong way and you don’t just lose the receivable, you lose a member, their referrals, and a story that spreads through a tight-knit field of membership fast. Nexa Collections recovers past-due loans, overdraft balances, and charged-off accounts through a member-centric process built specifically for credit unions.

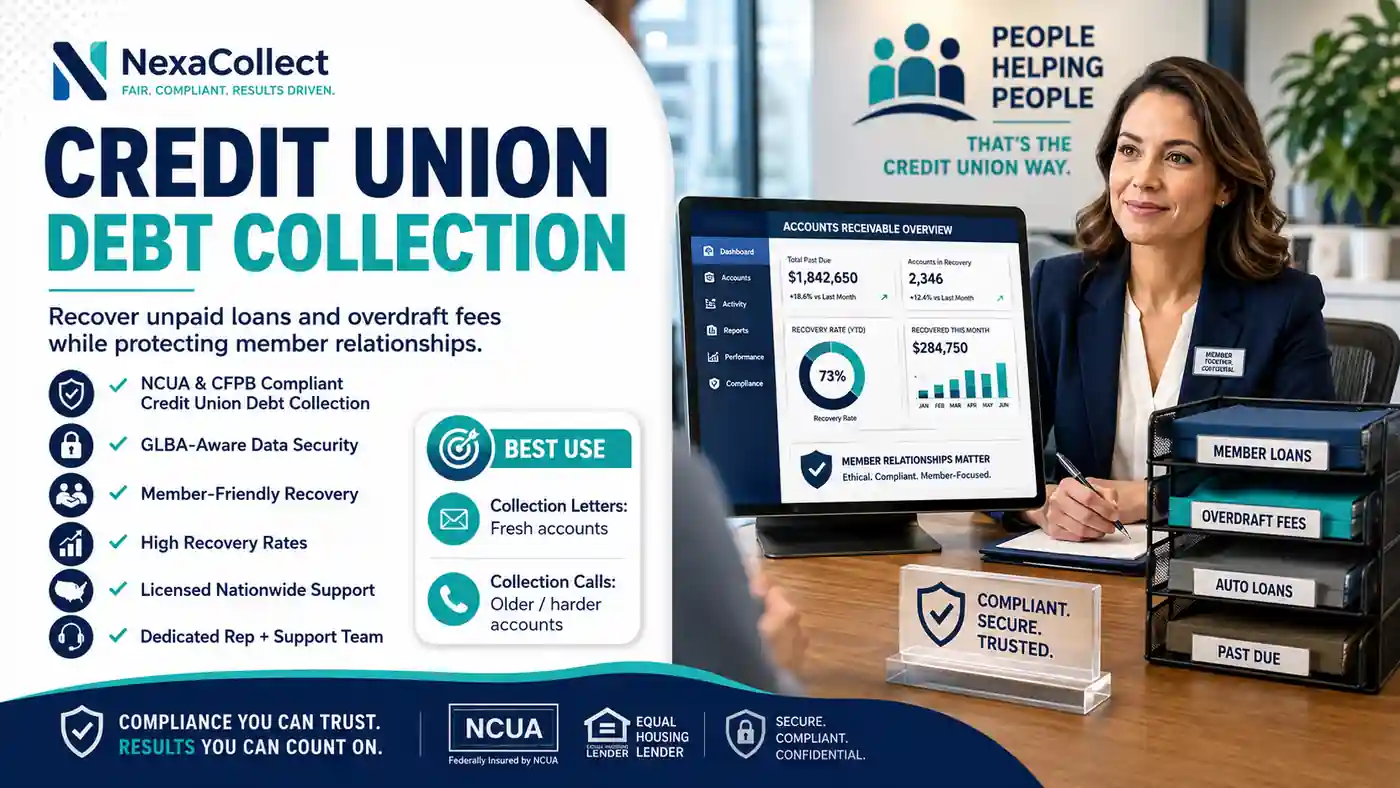
Credit union debt collection service highlighting NCUA and CFPB compliance, secure data handling, member-friendly recovery, high recovery rates, nationwide support, and dedicated account assistance.

Quick Answer: Credit union debt recovery requires balancing NCUA and CFPB regulatory compliance with a member-centric approach that protects community trust. Nexa provides 50-state licensed, GLBA and SOC 2 Type II secured credit union debt collection starting at a $15 Fixed Fee Service per account. Backed by a 4.85/5 rating across 2,000+ reviews and a dedicated financial services support team, our soft Fixed Fee approach helps credit unions recover overdrawn share accounts, credit card defaults, personal loans, and auto deficiency balances while retaining 100% of recovered principal.

Nexa provides reputation-safe approach,  equipped with all 50-state collections license, offering free credit reporting, free litigious debtor check, free bankruptcy scrub, and zero onboarding fees. Secure – SOC 2 Type II & HIPAA compliant. Over 2,000 online reviews rate us 4.85 out of 5. Every credit union is assigned a dedicated account executive, backed by a specialized financial services support team, not a general call queue.

Stop Losing Money. Get Paid Now


Credit unions now manage trillions in assets and a large, diverse loan book: auto, cards, HELOCs, personal loans, indirect paper, and small-business credit. With that growth has come more loans rolling into 60/90+ days past due, higher net charge-off ratios than in the low-rate years, rising delinquencies in auto and unsecured portfolios, and heavier exam focus on credit risk and third-party oversight. Inside many credit unions, a small team is juggling early-stage calls, repossessions, charge-offs, legal files, bankruptcies, and member service, it’s easy for late-stage, lower-priority accounts to fall through the cracks simply because there aren’t enough hours in the day.

AR Pain Points Credit Unions Struggle With

  • Thin internal collections staff — A handful of collectors handling everything from reminder calls to legal files.
  • Complex relationships — Co-borrowers, cross-collateralized loans, indirect portfolios, and members with multiple products.
  • Overdrafts and fee-driven balances — Small but noisy accounts that can generate complaints and bad reviews.
  • Reputation risk — One harsh collection experience can undo years of member goodwill and word-of-mouth.
  • Compliance pressure — Examiners expect documented processes, secure data handling, and controlled use of third-party vendors.

These are the reasons many credit unions keep early-stage work in-house, and push tougher, late-stage or charged-off accounts to a specialized agency that understands their environment.

Our Pricing

blank

Nexa $15 Fixed Fee Service. $15 flat fee per account, 0% commission, credit union retains 100% of recovered principal. Ideal for early-stage defaults and courtesy pay negative share accounts, typically under 120 days past due, where a formal third-party letter often gets attention and cures the balance.

Contingency Recovery (Late-Stage Defaults). Performance-based recovery for aged, uncontactable, or charged-off accounts. No fee is paid unless funds are recovered. Best for accounts over 120 days past due, broken promises, repeat delinquents, and charged-off balances your team doesn’t have time to chase. Legal action can be considered through a network attorney, with your approval, when the balance and circumstances justify it.

What $50,000 in Delinquent Share Accounts Actually Nets Your Credit Union

A simple static example, $50,000 in delinquent share account balances, an 80% eventual recovery rate ($40,000 collected):

Nexa $15 Fixed Fee Service Traditional 35% Contingency
Amount recovered $40,000 $40,000
Fee (50 accounts × $15) $750 $14,000 (35% of recovered)
Credit union keeps $39,250 (98.1%) $26,000 (65%)

Specialized Credit Union Product Portfolio Expertise

Negative Share / Courtesy Pay Defaults. Soft recovery for overdrawn checking and savings accounts before charge-off, the small, noisy balances that generate a disproportionate share of member complaints if mishandled.

Credit Card & Unsecured Personal Loans. Diplomatic outreach for past-due unsecured member credit lines.

Auto Loan Deficiency Balances. Recovering the remaining balance after collateral repossession and liquidation, or after an indirect loan default.

Indirect Lending Delinquencies. Managing defaults from dealer-originated credit union loans, where the member relationship began at the dealership rather than the branch.

Compliance That Protects Your Charter, Not Just Your Recovery Rate

Credit union collections carry a regulatory layer general collection agencies don’t always understand.

  • NCUA guidelines. Examiners expect documented third-party vendor oversight, and a collection partner should be built to satisfy that review, not just pass a sales conversation.
  • GLBA (Gramm-Leach-Bliley Act). Financial privacy standards governing how member data is stored, transmitted, and disposed of.
  • CFPB Regulation F, FDCPA, TCPA. Federal rules governing communication frequency, required disclosures, and prohibited practices.
  • SCRA (Servicemembers Civil Relief Act). Given how many credit unions serve military-affiliated fields of membership, this is routine due diligence, not an edge case. Before pursuing a servicemember’s account: interest on debt incurred before active duty began can be capped at 6% upon the member’s written request and supporting documentation; repossessing property financed before active duty generally requires a court order if the servicemember made a deposit or payment before entering service; and before any default judgment is entered against a non-responsive member, active-duty status must be verified against the Department of Defense’s database, entering judgment without that check is itself a violation.

In-House Collections vs. Traditional Aggressive Agency vs. Nexa’s $15 Fixed Fee Service

Factor In-House Collections Traditional Aggressive Agency Nexa’s $15 Fixed Fee Service
Upfront cost Staff time, no direct cash outlay Often 35-50% contingency regardless of account age $15 flat fee, credit union keeps 100% of what’s recovered
Member retention & community reputation Depends entirely on staff tone and training Low, aggressive scripts risk complaints and word-of-mouth damage Higher, diplomatic outreach designed to preserve the member relationship
Regulatory compliance (NCUA/Reg F/GLBA/SCRA) Depends on internal training and documentation discipline Varies, generic scripts may miss financial-institution-specific rules entirely Built around NCUA vendor-oversight expectations, GLBA, and SCRA from account intake
Account management Whoever’s available, often inconsistent Often a standard call center Dedicated account executive backed by a specialized financial services support team

What a Good Credit Union Collection Partner Looks Like

When you send accounts to an outside firm, you’re not just outsourcing phone calls, you’re trusting them with member relationships. You should expect bank-level security and privacy (GLBA mindset, secure file exchange, access controls), strong regulatory alignment with FDCPA, FCRA, Reg F, TCPA, and state rules, a member-friendly tone that’s firm but respectful and aligned with your brand and culture, omnichannel outreach (letters, calls, email, text where allowed, with proper consent), and actionable reporting, recovery by product, delinquency bucket, and campaign, so you can show results to leadership and examiners. A good partner feels like an extension of your AR team, not a black box you hope is doing the right thing.

Serving Credit Unions Nationwide

Need a Collection Agency? Contact Us

High Recovery rate. Referrals of existing Credit Union clients can be provided if requested. 

Internal Moves That Lower Delinquencies

External collections work best on top of solid internal practices. High-performing credit unions usually monitor portfolios frequently rather than just at month-end, reach out early at 15–29 days past due, offer realistic, time-bound workout options for short-term hardship, educate members about autopay, due dates, and the impact of missed payments, and segment high-risk groups (indirect auto, higher-risk tiers, repeat delinquents) to decide earlier when to move them to third-party collections. Your collection partner can help refine these strategies so you’re not relying on manual lists, scattered notes, and overloaded staff.

How a Specialized Agency Works With Your Credit Union

For late-stage and charged-off accounts, a credit-union-savvy agency can take over outbound campaigns on older auto, card, and unsecured loans, handle repossession deficiencies, judgments, and post-charge-off recovery, use skip-tracing and other tools within legal limits to locate harder-to-reach members, and recommend legal action only when it makes economic sense and fits your risk appetite. The tone matters: the goal is to recover what’s owed, explore realistic arrangements where possible, and avoid burning bridges with members you may want to keep in the long run.

Recent Recovery Results

Regional Federal Credit Union — Overdrawn Negative Share Accounts: 

A regional credit union placed 210 charged-off negative share accounts totaling $126,000. Using Nexa’s $15 Fixed Fee Service, the credit union recovered $88,200 within 40 days while keeping 100% of recovered principal for under $3,200 in total fixed fees.

Community Credit Union — Unsecured Personal Lines & Credit Cards: 

A community credit union faced $94,000 in defaulted unsecured personal lines of credit across 32 member accounts. Nexa’s soft Fixed Fee diplomatic outreach resolved 24 of the accounts in under 45 days, recovering $70,500 without a single CFPB complaint or damaged member relationship.


Credit Union Account Escalation Framework

When and how to transition delinquent member accounts to Nexa to maximize cash flow while protecting community trust.

Days 1–30 | In-House
Internal Member Outreach

Courtesy reminders, automated TCPA/SCRA pre-scrubbing, and soft phone calls prior to charge-off evaluation.

Days 31–90 | Nexa Step 1
$15 Fixed Fee Service

Diplomatic outreach for overdrawn share accounts, personal LOCs, and auto deficiencies. 100% principal retained.

Days 90+ | Nexa Step 3
Contingency Recovery Drive

Advanced skip-tracing, credit bureau reporting, asset verification, and legal escalation for uncontactable debtors.

Case Study: Overdrawn Negative Share Portfolio Recovery

Nexa $15 Fixed Fee Service Net

$85,050 Net Return

Based on submitting 210 overdrawn share accounts ($126,000 total balance) and recovering 70% diplomatically. Total fee: $3,150 ($15/account) while retaining 100% of recovered principal.

Traditional 35% Contingency Agency

$57,330 Net Return

35% commission consumes $30,870 out of your credit union’s recovered funds.

Credit Union Cash Advantage:
+$27,720 Saved

Launch $15 Member Recovery Drive

*NCUA, CFPB Reg F, TCPA, SCRA & GLBA Compliant. Active 50-State Licensing with SOC 2 Type II Security.


Frequently Asked Questions

How does Nexa maintain NCUA compliance and GLBA data privacy standards when collecting member accounts?

Every account is handled with the documented processes and vendor oversight NCUA examiners expect, secure file exchange, role-restricted access, and audit-ready reporting, alongside GLBA-aligned data privacy standards for how member financial information is stored, transmitted, and disposed of.

Can a $15 Fixed Fee Service help recover overdrawn negative share (courtesy pay) accounts before charge-off?

Yes, and this is exactly the account type it’s built for. Fixed-fee letter campaigns work well on fresh, small-balance negative share accounts, where a formal third-party notice often resolves the balance before it reaches charge-off, without the credit union paying a percentage of a balance that’s often modest to begin with.

How do you perform mandatory Servicemembers Civil Relief Act (SCRA) and TCPA checks prior to contacting members?

Active-duty status is checked against the Department of Defense’s database before any account involving a potential servicemember proceeds toward legal action, since a default judgment entered without that verification is itself a violation. TCPA compliance is handled through documented consent tracking for any autodialed or text communication, particularly relevant for reaching members on cell phones.

How does Nexa handle auto loan deficiency balances after collateral repossession and liquidation?

The deficiency, the gap between what the vehicle sold for at auction and what was actually owed, is pursued as a standard unsecured balance once the repossession and sale process is complete, following the same diplomatic, documented approach used for other credit union accounts.

Will using an outside agency trigger negative member feedback or CFPB complaints against our credit union?

Not with a member-centric process. Nexa’s diplomatic, firm-but-respectful approach is specifically designed to resolve balances without generating the kind of aggressive interaction that leads to complaints, protecting the credit union’s standing with both members and regulators.

Filed Under: Debt Recovery

Self Service Portal for Debt Collection: Easy, Compliant & Secure

Collection agency client portal

If you’re tired of email chains, spreadsheets, and “can you send an update?” follow-ups, a self-service client portal fixes the biggest problem in debt recovery: lack of real-time visibility.

With NexaCollect’s self-service collection portal, your team can place accounts, review activity, pull reports, and manage recalls/holds—without waiting on someone to respond.

Best for: CFOs, Controllers, AR Managers, Revenue Cycle teams, and owners who want speed, documentation, and accountability.


What a “Self-Service Collection Agency” Really Means

“Self-service” doesn’t mean you do the collections yourself.

It means you control and monitor the process through a secure portal:

  • You upload and manage placements

  • You can recall, pause, or update accounts when needed

  • You see activity notes and status changes as they happen

  • You can export reports for leadership, audits, or month-end close

In short: collections are still handled by the agency—your team simply gets control and transparency.

Need a Collection Agency? Contact us

Why This Matters in 2026 (Speed + Visibility Wins)

AR teams today are expected to do more with fewer people. The portal removes friction by making common actions instant:

  • No delays placing accounts

  • No waiting for a “status update”

  • No missing documentation during disputes

  • No messy reporting at month end

And when you’re moving fast, you also need to stay safe. Data security is no longer “nice to have.” IBM’s 2024 report put the average cost of a data breach at $4.88M—which is exactly why debtor data should never live in random spreadsheets and unsecured email threads.


What You Can Do Inside the Portal

Below is what most clients use daily—organized the way AR teams actually work.

Place & Manage Accounts

  • Bulk upload accounts using a spreadsheet (fast placements in volume)

  • Add single accounts one-by-one when needed

  • Upload supporting documents (contracts, invoices, statements, itemized billing, etc.)

  • Edit key account data (balance, contact info, notes, employer/business info where applicable)

  • Add special instructions (do-not-call windows, preferred contact channel, escalation notes)

Track Recovery Activity (Without Chasing Updates)

  • See account status changes (new, in progress, resolved, disputed, closed)

  • Review collector notes and action logs

  • Monitor payments, promises-to-pay, and settlement activity

  • Check if outreach attempts were made and outcomes recorded

Pause, Recall, or Update Accounts
Real AR is messy. Customers pay late, dispute, change addresses, or negotiate directly with you. The portal lets you act immediately:

  • Pause/hold an account (temporary stop)

  • Recall an account (permanent pullback)

  • Mark as paid, settled internally, bankrupt, deceased, business closed, etc.

  • Provide dispute documentation quickly to speed resolution

Reporting & Exports

  • Download recovery summaries for leadership

  • Export placement lists and status reports for month-end close

  • Track recovery performance by date range, bucket, or client group

  • Maintain documentation for internal controls and compliance reviews


The Security & Compliance Checklist You Should Demand

If you’re sending accounts to any partner, your minimum standard should include:

  • Role-based access (only the right team members can view actions/data)

  • Audit trails (who did what, and when)

  • Encryption in transit and at rest

  • Multi-factor authentication (MFA) support

  • Secure document storage (no “email attachments” as the system of record)

  • Policy-driven data handling aligned with regulatory expectations

This matters because the financial impact of poor security is massive—again, IBM’s 2024 benchmark placed breach costs at $4.88M on average.


How the Process Works (3 Simple Steps)

Step 1: Upload & Validate
Upload accounts (single or bulk). Include balances, contact details, and supporting documents if applicable.

Step 2: Collections Begin With the Right Approach
Our outreach is designed to recover funds without damaging your reputation—starting professional and escalating only when needed.

Step 3: Track, Manage, and Report
Your team monitors statuses, notes, payments, and outcomes in one place. You can pause/recall anytime, and export reports whenever leadership asks.


Who Uses This Portal (And Why)

CFOs / Controllers
Want predictable reporting, clean documentation, and less operational noise.

AR Managers
Need speed, visibility, and the ability to act instantly without delays.

Revenue Cycle / Medical Billing Teams
Need disciplined follow-up, strong documentation handling, and dispute workflows.

Owners / Operators
Want collections handled professionally while keeping full transparency.


Common Questions (FAQ)

Can I upload accounts in bulk?
Yes. Bulk upload is one of the most used features for high-volume placements.

Can I recall or pause an account anytime?
Yes. If a customer pays you directly or a dispute comes in, you can pause/hold or recall the account.

Will I be able to see what’s happening on each account?
Yes. Status changes and activity notes give you ongoing visibility without chasing updates.

Can I export reports for my leadership team?
Yes. Exports help with month-end close, performance reviews, and internal reporting.

Is online payment available for debtors?
If enabled in your program, online payment options can help reduce friction and speed resolution.


What Makes a Good Self-Service Collection Portal (Quick Checklist)

If you’re comparing options, use this list:

  • Fast bulk placements

  • Easy holds/recalls

  • Clean audit trails + notes

  • Reporting exports that match how finance teams work

  • Real security controls (not “email and spreadsheets”)


Ready to Try the Portal?

If you want a faster, cleaner way to place accounts and track recovery, we’ll walk you through the portal and show how it fits your workflow.

Contact NexaCollect for a complimentary consultation

Filed Under: Debt Recovery

  • « Go to Previous Page
  • Page 1
  • Interim pages omitted …
  • Page 39
  • Page 40
  • Page 41
  • Page 42
  • Page 43
  • Interim pages omitted …
  • Page 55
  • Go to Next Page »

Primary Sidebar


accounts receivable

Need a Collection Agency?
Kindly fill this form.
We’ll get in touch with you

    Please prove you are human by selecting the star.

    Compliance & Security

    • SOC 2 Type II Certified: Third-party audited data security and strict privacy controls.

    • HIPAA Compliant: Secure, legal processing of medical and municipal EMS accounts.

    • PCI-DSS Level 1: Highest tier of data encryption for secure payment processing.

    • FDCPA & FCRA Aligned: Full legal adherence to federal consumer protection laws.

    Recent Posts

    • Why Dental Patients Dispute Bills: The Nexa Collections Dental Account Dispute Index
    • 2027 Commercial Collections Benchmark: U.S. Late Payments, AR Risk and B2B Collection Trends
    • Bulk Account Placement: What a Collection Agency Actually Needs From You
    • Nationwide Debt Collection Agency Serving U.S. Cities
    • Chula Vista Collection Agency for Medical, B2B, Schools & Business Debt
    • Corpus Christi Collection Agency: Itemized Bill Rules for Practices
    • Riverside Collection Agency | For Logistics, Medical, Schools & Business Recovery
    • Collection Agency for Large Balances: High-Value B2B Debt Recovery

    Featured Posts

    • Medicare in 2026: A Simple Guide to Lower Drug Costs and New Benefits
    • Medical Debt Collection Agency: Patient-Friendly, HIPAA-Compliant Recovery
    • How Hospitals can use Data and AI to Improve Patient Care

    Copyright © 2026 NEXACOLLECT.COM | This content is provided for general informational purposes only and should not be considered legal advice. Collection laws and requirements may vary by state, account type, documentation, debtor status, and specific facts. Please consult qualified legal counsel for guidance regarding your particular situation. Nexa and its authorized collection partners service accounts in accordance with applicable federal and state collection requirements. Visit our home page to know more about us.

    X
    Need a Collection Agency?
    Contact Us