• Skip to main content
  • Skip to primary sidebar

Nexa Collections

  • Home
  • Serving
    • Medical
    • Dental
    • Small Business
    • Large Business
    • Commercial Collections
    • Government
    • Utilities
    • Fitness Clubs
    • Schools
    • Senior Care Facility
  • Contact Us
    • About us
    • Cost

Debt Recovery

A Compassionate, Compliant Approach to Assisted Living Collections

The resident who received care is almost never the person legally responsible for the bill. That single fact makes senior living collections unlike anything else in accounts receivable: the person you’re actually contacting is usually an adult child managing grief, probate paperwork, and a Medicaid application all at once, not someone who simply forgot to pay.

Quick answer: Senior living collections require treating the Responsible Party, typically an adult child or family guarantor, as a family liaison rather than a debtor, since aggressive tactics here don’t just risk one account, they risk your community’s local reputation. Nexa recovers private-pay arrears, Applied Income (Patient Liability), and post-death estate claims through dignity-first mediation, starting at a $15 fixed fee per account, with specialized handling for Medicaid spend-down timing and state-specific probate filing deadlines.
Assisted living collection agency providing compassionate, HIPAA-compliant recovery for unpaid private-pay balances, Medicaid spend-down arrears, and estate claims

An assisted living collection agency recovers unpaid private-pay balances, Medicaid spend-down arrears, and final-bill estate claims for senior care communities, including assisted living facilities (ALFs), memory care communities, skilled nursing facilities (SNFs), independent living communities, and home health agencies. Senior care collection is uniquely complex: liability typically rests with a Responsible Party, usually an adult child or family member, who may be simultaneously managing grief, estate paperwork, Medicaid applications, and their own financial obligations. The most effective assisted living collection agencies treat Responsible Parties as family liaisons, not debtors, recovering revenue through mediation and education rather than demand and pressure.

In senior care, you aren’t just managing a facility; you are managing a legacy. But when a resident’s Responsible Party stops responding, your mission to provide high-quality care is put at financial risk. The complexity of estate settlements and Medicaid spend-downs has made traditional, aggressive collections obsolete. If your approach feels like a cold demand, families will retreat or lash out. If it feels like a continuation of the care you provided, your community moves to the top of the payment priority list.

Nexa is equipped with all 50-state collections license, offering free credit reporting, free litigation check, free bankruptcy scrubs, and zero onboarding fees. Secure – SOC 2 Type II & HIPAA compliant. Over 2,000 online reviews rate us 4.85 out of 5. 

Protect Your Reputation & Recover Your Revenue


The Senior Care Financial Reality

  • The Sandwich Generation Is a Real, Measurable Phenomenon. According to AARP’s 2025 Caregiving in the U.S. report, approximately 63 million American adults provided unpaid care to a family member in the prior 12 months. A meaningful share of unpaid assisted living balances aren’t a refusal to pay, they’re a Responsible Party genuinely overwhelmed by probate, Medicaid paperwork, and caregiving obligations at the same time.
  • The Reputation Risk Is Structural, Not Hypothetical. A single family’s negative account of a “harsh” collections experience, shared on social media or with other prospective families, can affect a community’s census for months. This risk is specific to senior living in a way it isn’t for most industries, since referrals and reputation among local families are core to how communities fill beds.
  • The Spend-Down Clock. Once a resident moves toward Medicaid eligibility, the window to recover private-pay arrears closes rapidly. Timely, diplomatic intervention is the only way to secure these funds before that window shuts.

Why Senior Living Collections Is an Emotional Landmine

The “Responsible Party” vs. The Resident

We understand that the resident is almost never the one handling the checkbook. Our mediators are trained to engage the Responsible Party (often a grieving or stressed adult child) as a Family Liaison, not a debt collector. We bridge the gap between “I can’t pay” and “I won’t pay” by acting as a professional buffer.

Medicaid Pending & Estate Complexity

Generic agencies get lost in the weeds of Medicaid. We don’t. We understand the “Medicaid Pending” status and the estate settlement process. We speak the language of executors and probate attorneys, ensuring your facility is recognized as a priority creditor without causing a family feud.

The Reputation Shield

One disgruntled family member on social media can damage your census for months. Our Minimal Stress Policy ensures every interaction is recorded and randomly reviewed to maintain your community’s standing. We protect your brand while we recover your bottom line.


The Nexa “Dignity-First” Recovery Ladder

We separate “administrative confusion” from “bad debt” to maximize your recovery.

  • Step 1: The Account Reconciliation (Fixed Fee – $15). Ideal for accounts 60–90 days past due. A soft, third-party “nudge” that identifies simple misunderstandings or missing paperwork before they become legal disputes. You keep 100% of the money recovered.
  • Step 2: Specialized Mediation (Contingency). For high-balance aged debt or unresponsive estates. We perform deep-data bankruptcy and estate scrubs to find the path to payment. No Recovery = No Fee.
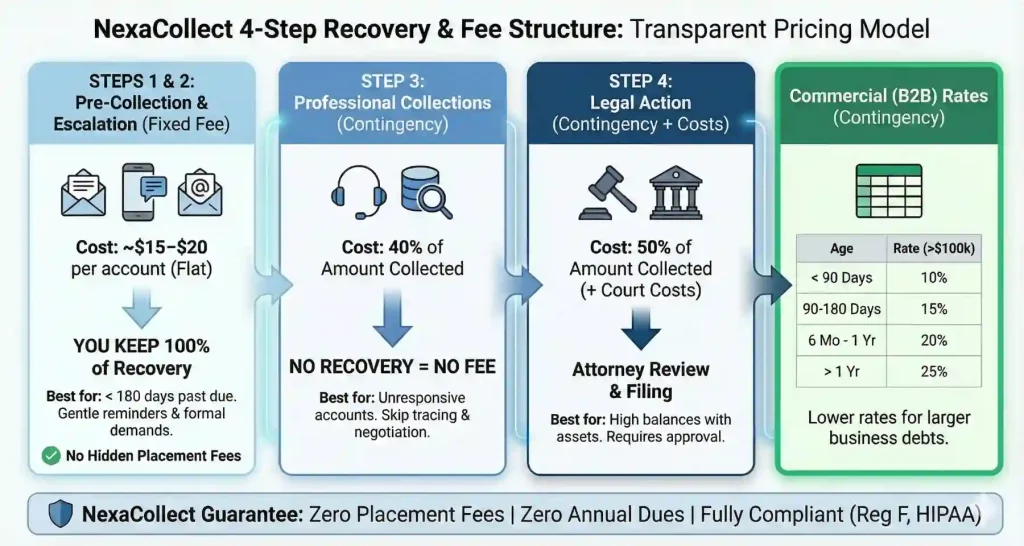
Nexa Collections fixed-fee and contingency pricing structure

See the full pricing breakdown for how these tiers compare across account types.

To ensure swift resolution and complete legal enforceability, each placed senior care account should include the signed resident admission agreement, financial guarantor or Power of Attorney (POA) designation, itemized level-of-care billing statements, and current Medicaid pending or spend-down records.


Our 4-Stage Compassionate Recovery Framework

  1. Secure Ingest & Audit: Safely import delinquent resident accounts via Excel into our secure portal, ensuring full data privacy.
  2. Responsible Party Identification: Review enrollment documentation to accurately identify and contact the designated responsible party or executor.
  3. Empathic Mediation: Initiate a highly professional, soft-touch communication sequence focused on clear financial mediation rather than aggressive collection.
  4. Structured Resolution: Establish flexible, legally compliant payment schedules to cleanly resolve outstanding private pay balances while protecting your facility’s community standing.

Key strength: We address core senior care billing friction directly, transition to Medicaid, power of attorney communication, family guarantor confusion, and probate/estate balance resolution.


Recent Recovery Results

Regional Memory Care Community: A facility carrying $86,000 in aged private-pay and Medicaid spend-down arrears across 40 accounts implemented Nexa’s dignity-first mediation approach. $61,000 recovered (71%) within 75 days, with zero negative family reviews and two Responsible Parties who later referred new residents to the community.

Multi-Facility SNF Operator: A three-location skilled nursing operator had $52,000 in unfiled estate claims where the probate window was at risk of closing. Nexa’s estate-monitoring process identified and filed creditor claims for all 18 accounts within statutory deadlines, recovering $38,500 through negotiated estate distributions.


Handling POA & Probate Cases

Power of Attorney (POA)

  • Verify & Direct: We confirm financial POA authority, then direct all outreach to the agent, never the incapacitated debtor.
  • Target Correct Assets: Pursue the principal’s funds, not the agent’s (unless the agent signed a personal guarantee).

Probate (Deceased Debtor)

  • POA Ends at Death: We stop contacting the POA agent immediately when the debtor dies.
  • File Court Claims: Identify the estate’s court-appointed Executor and file a formal Creditor’s Claim before state statutory deadlines.

Medicaid Spend-Down & Private-Pay Recovery: The Collection Window You Cannot Miss

The Medicaid spend-down is the most complex and most consequential billing scenario in assisted living finance. Understanding it, and acting within the right window, is the difference between recovering significant private-pay revenue and writing it off permanently.

What is a Medicaid spend-down?

Before a senior becomes eligible for Medicaid long-term care benefits, they must reduce their countable assets below the state’s Medicaid asset threshold (typically $2,000 for the applicant, with spousal protections for a community spouse). The process of depleting assets to this threshold is called the “spend-down.” During this period, the resident is paying privately, and those private-pay invoices are your most collectible accounts. Once Medicaid eligibility is established, the state begins covering room-and-board costs, but only from the eligibility date forward. Any private-pay arrears accrued before that date are not covered by Medicaid and must be collected separately.

The collection window and why timing matters

The private-pay collection window closes the moment Medicaid eligibility is established. Once the state begins paying, families often assume the pre-Medicaid arrears are “wiped out”, they are not, but recovering them becomes significantly harder after Medicaid kicks in. We intervene during the Medicaid pending period, typically 30–90 days, to:

  • Collect monthly applied income (patient liability) due during the pending period
  • Document and formally claim all pre-Medicaid private-pay arrears
  • Assist Responsible Parties in gathering spend-down documentation to avoid denial and delays that extend the private-pay period
  • Ensure the facility is notified immediately when Medicaid eligibility is established, closing the private-pay period cleanly on the billing ledger

Applied Income / Patient Liability, the most commonly missed revenue

Once Medicaid is active, most residents owe a monthly “Patient Liability” amount, sometimes called Applied Income, which is the portion of their income (typically Social Security and pension) that must be paid to the facility each month after deducting a small personal needs allowance. This amount is set by the state Medicaid agency and is legally obligatory. Despite this, many facilities routinely fail to collect Applied Income because families treat it as discretionary. We specialize in Applied Income education and collection, recovering monthly co-pays that internal teams consistently write off as too awkward to pursue.


Estate Claims & Probate: Recovering the Final Bill

When a resident passes away with an outstanding balance, collecting the final bill requires sensitivity, legal knowledge, and timeliness. Most facilities handle this internally, and most do it incorrectly, either too aggressively (damaging the family relationship and the community’s reputation) or too passively (missing the probate filing window and losing the claim entirely).

The probate filing window

Every state has a specific deadline for creditors to file claims against a deceased person’s estate, typically 3 to 6 months from the date of the executor’s appointment (which occurs when the will is filed with the probate court). Missing this window can permanently bar the facility from recovering the balance, even if the estate has sufficient assets. We monitor probate proceedings for accounts in our care and file creditor claims within the required window, never missing a filing deadline.

How we handle families in grief

Our estate claim process begins with a condolence acknowledgment, a formal, warm communication that expresses the facility’s sympathy for the family’s loss before any mention of the outstanding balance. This is not a collection tactic; it is a reflection of the relationship the facility had with the resident and family. The financial discussion follows only after the condolence has been acknowledged and the family has had time to understand the probate process. In our experience, families who feel respected during the estate process settle the facility’s claim at a significantly higher rate than those who receive an immediate demand letter.

Priority of claims in probate

State probate law establishes the priority in which creditors are paid from an estate. In most states, funeral and burial expenses are paid first, followed by estate administration costs, then priority creditors (which may include federal and state government claims), and then general unsecured creditors. Assisted living and skilled nursing facility claims are typically treated as general unsecured creditors, meaning the facility is paid after higher-priority claims are satisfied. We assess the estate’s asset profile and likely distribution before filing to give your business office a realistic recovery probability estimate.

Medicaid Estate Recovery Programs (MERP)

When a Medicaid-covered resident passes away, the state Medicaid agency has the right to recover its costs from the resident’s estate through the Medicaid Estate Recovery Program (MERP). In states with aggressive MERP enforcement, the Medicaid program’s estate recovery claim may compete with or take priority over the facility’s private-pay arrears claim. We are familiar with each state’s MERP rules and help your facility understand the interaction between the Medicaid estate claim and your facility’s private-pay arrears before filing, maximizing your net recovery position.


Specialized Recovery for the Full Continuum of Care

We provide expert-level recovery across all senior care sectors:

  • Assisted Living & Memory Care: Navigating the sensitivity of long-term cognitive care billing.
  • Skilled Nursing Facilities (SNF): Specialized handling of complex room-and-board arrears.
  • Independent Living: Maintaining a professional “neighborly” tone for active senior communities.
  • Hospice & Home Health: Treating the final stages of care with the absolute highest level of empathy and respect.

Frequently Asked Questions

Does this affect our standing with the state or local community?

No. We act as a professional mediator. Our goal is to solve the family’s billing confusion. By acting as a third party, we take the “heat” off your Executive Director, allowing your team to remain the “caring face” of the facility. Every call is recorded and randomly reviewed to ensure our collectors maintain your community’s reputation standards. Our Minimal Stress Policy governs every interaction, we are problem-solvers, not aggressors.

How do you handle “Involuntary Discharge” situations?

We aim to resolve the debt before it reaches that point. By establishing payment plans early, often during Stage 2 Medicaid mediation, we help families avoid the trauma of discharge while ensuring your facility gets paid. Where an involuntary discharge has already occurred, we pursue the outstanding balance through our standard mediation process with the Responsible Party, independent of the discharge status.

What about residents who have passed away?

We handle “Estate Claims” with extreme sensitivity. We offer condolences first and then work with the executor to ensure the facility’s final bill is included in the probate distribution. We file creditor claims within all state-specific probate deadlines and monitor the estate proceedings until the facility’s claim is resolved, whether through payment from estate assets, a negotiated settlement, or a documented determination that the estate is insolvent.

Who is legally responsible for an assisted living bill if the resident cannot pay?

Liability flows from the admission agreement. The person who signed as “Responsible Party” or “Guarantor” is personally accountable for the resident’s financial obligations, even if the resident’s own assets are insufficient to cover the bill. We review every admission agreement before pursuing a Responsible Party to confirm the legal basis for the claim. If the admission agreement does not contain a clear personal guarantee, we assess alternative recovery paths (estate claim, Medicaid Applied Income) rather than pursuing the family member on an unsupported basis.

Can you sue a family member for an unpaid assisted living bill?

Yes, if they signed as a guarantor or Responsible Party in the admission agreement. A signed admission agreement with a clear personal guarantee is a binding contract, and the Responsible Party is personally liable for unpaid balances regardless of their own financial relationship to the resident. We pursue legal escalation only with your explicit written approval and only where our legal team assesses that the Responsible Party has verifiable assets that can satisfy a judgment.

What is Applied Income / Patient Liability and why is it so hard to collect?

Applied Income (also called Patient Liability) is the monthly contribution that a Medicaid-covered resident must make toward their care costs, typically most of their Social Security and pension income after a small personal needs deduction. It is legally mandatory, set by the state Medicaid agency, and owed to the facility every month. Despite this, many facilities collect less than half of the Applied Income they are owed, because internal staff are uncomfortable pursuing it from families who believe Medicaid is “covering everything.” We specialize in Applied Income education and collection, explaining the obligation clearly, empathetically, and compliantly, and recovering monthly amounts that facilities have historically written off.

What is Medicaid spend-down and how does it affect collections?

Medicaid spend-down is the process by which a senior depletes their countable assets below the state Medicaid eligibility threshold (typically $2,000). During this period, the resident is paying privately, and those private-pay invoices are your most collectible accounts. Once Medicaid eligibility is established, the state covers costs going forward but not the pre-Medicaid private-pay arrears. The collection window for those arrears closes at the Medicaid eligibility date. We intervene during the Medicaid pending period to collect monthly Applied Income, claim pre-Medicaid arrears, and assist families with documentation to avoid delays that extend the private-pay period.

How do you handle a Responsible Party who claims they cannot afford to pay?

We distinguish between “I cannot pay” and “I am not prioritizing this payment.” For genuine hardship, we offer structured monthly installment plans calibrated to the Responsible Party’s stated financial capacity, keeping the account active and the relationship functional while recovering incrementally. For Responsible Parties who have resources but are deprioritizing the facility’s bill, we escalate gradually: credit bureau reporting (with your approval), formal demand correspondence citing the admission agreement’s personal guarantee provisions, and ultimately legal referral if appropriate. We never pursue a Responsible Party for more than they are legally obligated to pay under the admission agreement.

What happens when the Responsible Party and the estate executor are the same person?

This is common and requires careful navigation. We engage them simultaneously in two capacities: as the personal guarantor under the admission agreement (if applicable) and as the estate administrator responsible for ensuring creditors are paid before assets are distributed to heirs. We file a formal creditor claim with the probate court and separately assess personal guarantor liability under the admission agreement, pursuing whichever path yields the highest recovery while managing the dual-role relationship diplomatically.

Do you handle collections for senior living management companies with multiple facilities?

Yes. We serve single facilities and large senior living chains alike. For multi-facility operators, we provide consolidated corporate-level reporting across all locations, showing portfolio performance by facility, account stage, and recovery rate, while maintaining facility-level account management with the local team. Our 24/7 client portal supports multi-facility dashboard views and individual facility drill-downs. There is no minimum account volume and no additional setup fee for multi-facility onboarding.

How does Medicaid Estate Recovery (MERP) interact with our facility’s estate claim?

When a Medicaid-covered resident passes away, the state Medicaid agency has the right to recover its costs from the resident’s estate through the Medicaid Estate Recovery Program (MERP). In states with aggressive MERP enforcement, the Medicaid claim may compete with or take priority over your facility’s private-pay arrears. We assess each state’s MERP rules before filing, advise on priority positioning, and ensure your facility’s claim is filed in the correct form and timeframe to maximize recovery in the context of any competing Medicaid estate claim.

What billing and EMR systems do you integrate with for account placement?

We accept account placements via Excel/CSV export from any senior living management system or EMR. Common platforms our clients use include PointClickCare, MatrixCare, Eldermark, Yardi Senior Living, and AL Advantage. Our intake template maps to standard export fields, capturing resident name, Responsible Party contact information, account balance, account age, and payer source (private pay, Medicaid pending, estate). Most facilities complete onboarding and place their first accounts within one business day.

What is the minimum balance required for senior living debt placement?

We efficiently recover high-volume, small-balance ancillary charges and private pay balances, provided they meet our standard agency minimum of $50.00 per account. This allows your administrative staff to easily offload micro-debts without draining facility hours.


Hire a Senior Living collection agency: Contact us

References Available


Filed Under: Debt Recovery

Bankruptcy Debt Recovery Services for Creditors

Business Chapter 11 bankruptcy

When a customer files for bankruptcy, most businesses panic and immediately write off the debt. That is often a costly mistake.

While the “Automatic Stay” stops immediate collections, it does not mean your money is gone forever. Bankruptcy proceedings are complex, deadline-driven, and filled with opportunities for savvy creditors to recover funds. Nexa Collections ensures you don’t leave money on the table. We handle the administrative burden of bankruptcy claims so you can focus on your business.

The “Unclaimed Money” Reality

Did you know that in “Chapter 7 Asset Cases,” billions of dollars go unclaimed simply because creditors miss the deadline to file a “Proof of Claim“?

  • The Stat: Industry data suggests that a significant percentage of unsecured creditors never file paperwork, walking away from potential payouts. We ensure you are in the line to get paid when funds are distributed.


What Bankruptcy Recovery Services Do?

1. Filing the “Proof of Claim”

The court will not send you a check automatically. You must file a specific legal document detailing what you are owed and why.

  • Our Role: We gather your invoices and contracts to file a timely, accurate Proof of Claim. If the trustee liquidates assets, you will be on the official list for distribution.

2. Reclamation Rights (The 45-Day Rule)

Did you ship goods to the debtor recently? Under bankruptcy law, if you delivered goods within 45 days of the bankruptcy filing, you may have “Reclamation Rights” to demand those goods back before they are sold off.

  • Identify these opportunities immediately and file the necessary Reclamation Demands to recover your inventory.

3. Monitoring the “341 Meeting” & Dockets

Creditors are invited to the “Meeting of Creditors” (341 Meeting) to question the debtor, but busy business owners rarely have time to attend.

  • Still you must monitor court dockets for asset discoveries, dismissal of cases (which allows you to resume immediate collection), and distribution updates. 


Understanding the Chapters (And What They Mean for You)

Chapter 7: Liquidation (The Fire Sale)

  • The Scenario: The business is closing. The court trustee sells all non-exempt assets (equipment, real estate, inventory).

  • Your Move: We watch for the “Notice of Assets.” If the trustee finds money, we ensure your claim is filed instantly.

Chapter 11: Reorganization (The Comeback)

  • The Scenario: The business stays open but restructures its debt. They usually pay creditors pennies on the dollar over time.

  • Your Move: We review their “Plan of Reorganization.” If the plan is unfair or feasible, creditors can object. We help you vote on the plan and ensure you receive the promised payments.


How We Protect You

  • Stop the Harassment Risks: Violating the “Automatic Stay” (calling a bankrupt debtor) can result in massive fines for your company. We act as a firewall, ensuring all communication goes through proper legal channels.

  • Preference Defense: Sometimes, trustees try to “claw back” payments you received before the bankruptcy (called a Preference Action). We help validate that those payments were made in the “Ordinary Course of Business” to protect your cash.

Don’t Assume It’s a Total Loss

Bankruptcy is a legal maze, but it is also a path to repayment for those who know the rules.


Filed Under: Debt Recovery

10 Warning Signs Your Client is in Financial Trouble

Client in Financial Trouble
Receiving payments from clients is a crucial part of creating and maintaining positive cash flow in any business. However, a business income stream can quickly get out of balance when clients – whom you’ve delivered top-notch work in a timely and professional manner – decide not to pay their invoices.

When clients cannot settle their accounts, the business makes less profit, incurs losses and may even have to raise prices to break even. If there are too many delinquent accounts, reaching your break-even point might become a struggle.

Unfortunately, when most clients are having financial trouble they most likely will not disclose this fact to the companies they are doing business with. Instead, they just refrain from paying their invoices. In this article, I’ve put together a list of 12 telltale signs that your client is under financial distress.

  1. There’s no contract in place.

It is pertinent to have a contract in place when working with clients. A contract is a binding agreement that holds the client liable to pay all funds they owe a business. Furthermore, a contract is advantageous should you decide to take legal action against non-paying clients.

  1. The Client wants to use checks as its sole payment method.

For a business, accepting multiple types of payments is beneficial and aids in getting paid faster. Companies should, therefore, be wary of clients who demand to use checks as their sole means of payment. Paper checks give clients who had no intention of settling their account leeway to be fraudulent since paper checks allow clients to establish their grace period or keep writing bad checks. This means that you will probably never receive your money.

  1. Inconsistent payments and deadline extensions.

One of the most obvious signs that your client is having financial trouble is that their payments become inconsistent and they are constantly asking for deadline extensions. You may find that you are starting to receive only part of the payment of your invoices on one date and the remaining parts on another date. This is usually a clear sign that your client is having financial trouble.

  1. The company is becoming contentious.

Healthy cash flow is what keeps every company afloat. Clients who are experiencing financial stress will do anything to survive, including becoming contentious. They might look for any excuse to not pay up or complain about your service for no reason at all. In actuality what they’re trying to do is delaying payment or even completely avoid payment to ease their financial stress.

  1. Fishy contact information or becomes unreachable.

Perhaps the worst type of non-paying clients is the crooks whose intentions were to not pay you from the start. These are the types with unprofessional or spammy looking email addresses or are constantly changing numbers to become unreachable to people they owe. 

  1. The checks keep bouncing and changing banks.

One surefire red flag is when clients keep changing banks, and their checks keep bouncing. It is not unheard of that a check sent by a client bounced or that they switched bank once in a while, however, if that keeps occurring it is a good indication that they are in financial trouble and cannot settle the account.

  1. No accounts payable contact person or department.

If your client is a solopreneur or small business, they probably don’t have an accounts payable department. This can be a concern since your bill can become a low priority to them. It is therefore always best to make sure you’re dealing with a real company that will not sway from paying their bills on time by having an ironclad contract on hand.

  1. Profits are plummeting or layoffs.

For a company to survive long term, it needs to be profitable, thus you need to keep a watchful eye on your client’s profit margin. This can be difficult to spot, but one surefire way to tell is if the company is constantly laying off staff. You can also look for other evidence such as the profit-margin ratios of what might be happening to profits to get a glimpse of your client’s profit margin.

  1. Declining reputation or a bad news/scandal in the company.

How many big names and long-established businesses have we’ve seen fall because of a bad reputation, continuing bad press or a damning scandal in the company. Nowadays people no longer share their displeasure with a customer service department; they vent on social media for thousands to see. Bad press and scandals will tremendously affect a company’s reputation. As a result market shares can decline, which will lead to financial difficulties and the increased risk that they won’t be able to pay invoices on time.

  1. Making repeated and inconsistent excuses

If you have a client that repeatedly makes excuses and is constantly asking to extend the deadline, then there’s a good chance that they’re experiencing financial troubles. It is best to stop working with this client immediately.

Key points to keep in mind to ensure that your invoices are paid

To ensure that your invoices are paid, there are three key points you should keep in mind at all times:

  1. Be selective about your clients: before you start working with a client, it is always best to do a background check to spare yourself the unnecessary headache if it turns out that the client is experiencing financial distress.
  2. Always request a percentage upfront: One way to vet your clients is by requesting to receive a percentage of the payment upfront. Most companies that are financially stable won’t object to this request.
  3. Take legal action: If all else fails and your client still turns out to dodge what they owe you, You can always take legal action.

Conclusion:

When working with clients, your priority is to get paid as much as you can as quickly as possible. Check the above-mentioned list to find out if a company is experiencing financial trouble or not. Remember, sometimes, taking a reduced amount now could be a better option than hanging on for full payment later, which never arrives.

Filed Under: Debt Recovery

Common Problems in Accounts Receivable Management

Problems in AR Management
Accounts receivables (AR) are the lifeblood of your company. They are the positive end of the cash flow cycle and are necessary for paying bills, salaries, and your own creditors.  It also tends to be one of the largest assets a company owns.

Managing your AR effectively can help smooth out your finances and keep your company healthy and growing. However, there are a number of issues that can prevent your accounting department from collecting outstanding receivables properly.

The overarching problem that all AR teams face is accounts that don’t pay on time or don’t pay at all. But this is frequently a symptom of more specific, underlying problems in the management of your accounts receivables. Fixing these common problems will often lead to more consistent payments.

When attempting to fix any of the problems below, it’s important to remember that any solution must be applied consistently in order to be effective. Selectively applying policies or only following best practices when it’s convenient is a surefire way to fail.

Collecting On Invoices Takes Too Much Time

If your AR management team finds they spend too much time chasing down customers and helping them make payments, you may have a couple of issues that can be improved.

For one, it’s possible that you aren’t offering enough ways for your customers to pay you. If the limited payment methods you accept don’t align with the ways your customers want to pay, you’re certain to encounter problems.

So make sure you offer the full complement of payment methods available today, including credit cards, checks, direct bank account debits, digital services like PayPal, and mobile payment apps like Venmo.

You also want to collect payments digitally, and automatically, so that your AR teams don’t need to be involved. Embedding payment options directly inside of a digital invoice is the best way to handle this. Additionally, this makes things simple for your customers, which increases the speed with which they’ll pay.

Customers Complain They Aren’t Given Enough Time

Many companies pay their invoices at specific times each month. If they pay twice a month, they might choose the 15th and the end of the month. Payments made once a month could fall at the beginning, middle or end, and this date can be different from customer to customer.

The problem faced here is that your invoice releases may not align well with their schedule. Your terms might be Net 30, but if you send an invoice on the 20th and the customer pays at the end of the month, they may feel they only have ten days to pay you. If they opt to pay you at the end of the next month, they’ll wind up paying late. You may even decide to impose a late fee.

While it’s unreasonable for customers to think you can sync your invoices to their preferred payment window, you can help them by sending out invoices as soon as possible. Accounting software will generally help you automate the creation and sending of invoices, but you can also create an internal process that generates the invoice immediately upon delivery of the product or service.

Sending invoices digitally helps this situation by making invoices quicker and easier to submit and it saves them time, rather than waiting for the postal mail to arrive.

Getting Payments and Invoices to Match is Time Consuming

If you’re still manually matching payments to invoices, you’re wasting a lot of effort. Most advanced accounting packages can handle this labor-intensive task for you

Particularly when you invoice digitally and include direct access to a payment portal, you can control the flow of information between the payment source and your accounting software. This can help assure that each payment that’s made is tied to a specific invoice number for easy matching.

If you aren’t ready to automate your process digitally, there are still steps you can take. Make certain that every customer has a unique customer ID and tie that ID into your invoicing system, creating an invoice number for each invoice you send. Your invoice number might include the year, the client ID, and then a string of numbers that increments by one with each invoice. For example, the first invoice for your customer ABC Tech might read, 19ABC0001.

Make sure that clients include that invoice number with any payments they make. You’ll be able to immediately identify the account the payment belongs to and track down the matching invoice.

Invoices Missing Information

Some large companies require specific pieces of information on the invoices they receive, and when it’s missing or misformatted, payment delays can result.

For small businesses, it can be extremely challenging to generate custom invoices this way. Not only is it difficult to remember the specifics for each invoice version, but it’s also hard to keep multiple versions of your invoices on hand.

Invoicing software is the best way to solve this problem. You can create invoice templates that are specific to each customer that requires custom invoices. This way you do the work once and then rely on the software to keep everything straight for you.

Invoices Aren’t Getting to the Right People

Employees come and go. Businesses move locations. Departments shift between offices. Over time, the people, places and email addresses you’re sending your invoices to may change, and invoices that once got paid quickly might stop getting paid at all.

Using a CRM package to keep track of all of your customers can be a good way to make certain your contact information is kept up to date. These have tools built-in to help you keep up with the right decision-makers and billing contacts for each company you do business with.

Delinquent Accounts

No matter how good your invoicing practices are, some customers will always pay late. It’s likely that they’re exercising cash flow management on their end. But they might also be serious defaulters. The best way to deal with these customers is to build reminder automation into your collections process.

Either schedule reminder letters to be sent for each invoice you send, or better, create rules in your accounting software to send these letters at regular intervals for you. You can sculpt the language of the letters ahead of time. Just make certain that the reminders start out friendly and get progressively more demanding with each iteration. At some point, you need to decide whether severing the relationship with your client is better than the loss that they are causing. Always involve a debt collection agency if your bills are 90 days past due and recover money in a legal complaint way.

Phone calls are certainly warranted if an invoice becomes significantly overdue, but the more that you can leave your collections to your software, the more time you’ll have to solve other AR problems you’re facing.

If you need a Collection Agency to help you recover money from overdue accounts: Contact us

Filed Under: Debt Recovery

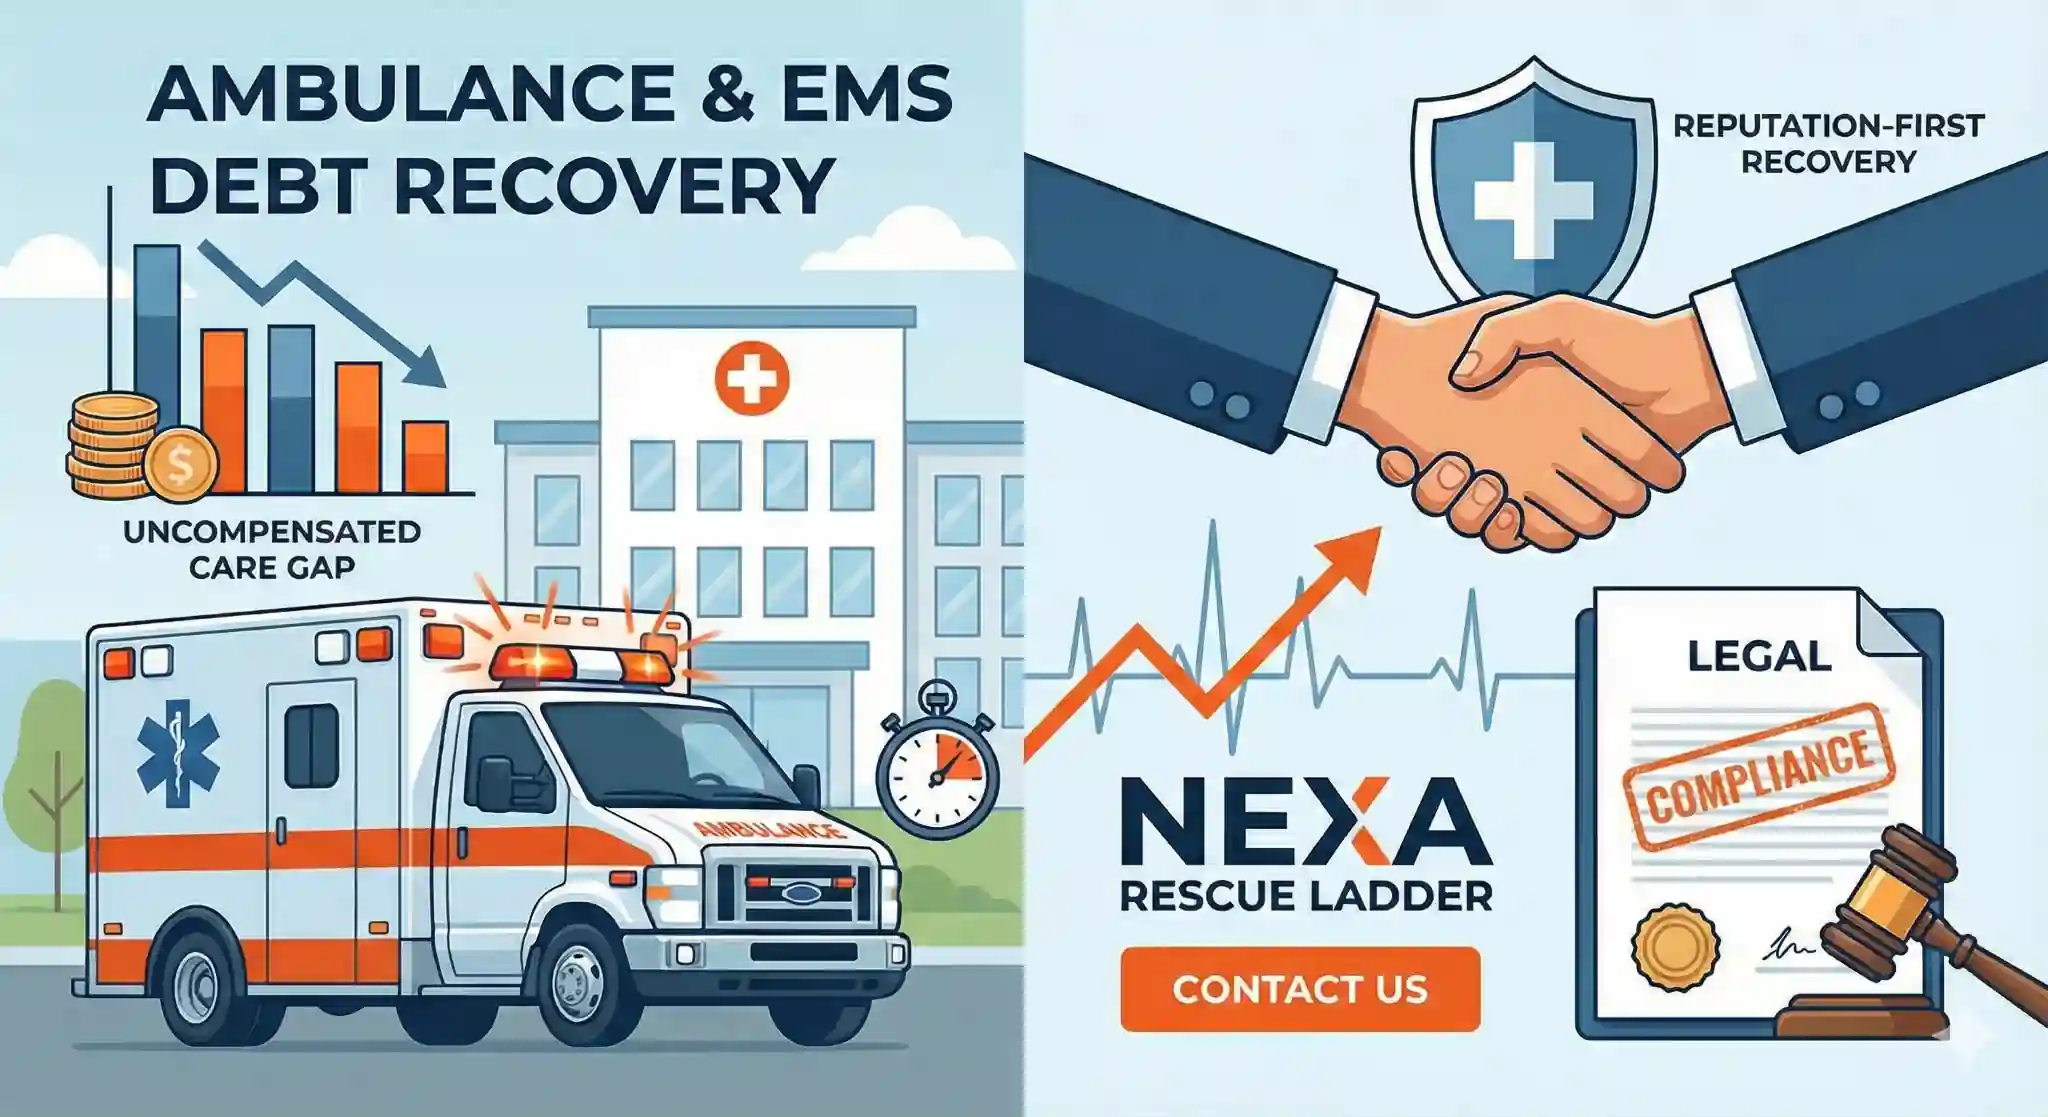
Ambulance Debt Collection | EMS Patient Revenue Recovery

Ambulance providers face a collection problem unlike almost any other healthcare business: the cost of responding keeps rising, insurance often pays only part of the bill, and the patient you are trying to collect from may already be dealing with hospital bills, lost wages, and financial stress from the same emergency. Waiting too long makes the problem worse—older EMS balances become harder to recover, while aggressive collection tactics can quickly damage the reputation of a municipal department or community ambulance service.

Nexa helps EMS providers separate insurance issues, patients who simply need a reminder, hardship cases, and true bad debt, then applies the appropriate HIPAA-compliant, patient-friendly recovery strategy before valuable accounts become uncollectible.

Reputation friendly ambulance and EMS debt recovery
Ambulance & EMS Debt Recovery: Recovering Revenue Without Compromising Community Trust. 

For EMS directors and municipal leaders, every siren represents a life-saving mission, but the financial “after-care” is increasingly a crisis of its own. In 2026, the gap between what it costs to roll a truck and what insurance actually pays has reached a critical breaking point.

Critical Warning: Emergency and ambulance services must act quickly to collect unpaid medical bills from patients as their financial condition can deteriorate very quickly following a medical crisis. When a household is hit with sudden, high-cost medical bills, the first 60 days are the “Golden Window” for recovery before competing debts and financial instability make collection very complicated.

Nexa provides 100% reputation-safe, equipped with all 50-state collections license, offering free credit reporting, free litigious patient check, free bankruptcy scrubs, and zero onboarding fees. Secure – SOC 2 Type II & HIPAA compliant. Over 2,000 online reviews rate us 4.85 out of 5. 

Need a Collection Agency? Restore Your EMS Cash Flow Today


The EMS Financial Reality (Industry Stats)

The “Ambulance Profit Gap” has widened significantly this year. According to the latest 2026 CMS Ground Ambulance Data (GADCS) and industry benchmarks:

  • $1,526 Under-Reimbursement: On average, across all payers, ambulance agencies are under-reimbursed by over $1,500 per transport compared to the actual cost of readiness.

  • $2,672 vs. $1,147: While the mean cost of a governmental ambulance transport has surged to $2,672, the mean reimbursement across all payers remains stuck near $1,147.

  • 37% Emergency Fragility: Recent Federal Reserve data shows that nearly 37% of adults cannot afford a $400 emergency expense. Since the average ambulance bill exceeds $1,200, patients move into financial distress almost immediately.

  • 45% Recovery Drop-off: If a patient balance isn’t addressed within the first 120 days, the likelihood of recovery drops by nearly half as patients deprioritize “one-time” emergency costs behind recurring monthly bills like rent and utilities.


The Nexa 4-Step “Rescue” Ladder

We separate “slow payers” from “bad debt” to maximize your recovery while protecting your department’s community image.

blank

Step 1: The Account Reconciliation (Fixed Fee – $15)

Ideal for accounts 60–90 days past due. Because patients’ financial conditions deteriorate so quickly, this “soft touch” reminder acts as a firm nudge to pay while they still have the liquidity.

  • The Result: The patient pays you directly. You keep 100% of the money.

Steps 2–4: Specialized Medical Mediation (Contingency)

For aged debt or patients who have “ghosted” your internal team. Our mediators use advanced skip-tracing and empathy-based negotiation to find solutions before the patient faces bankruptcy.

  • The Result: You only pay us if we recover your funds. No Recovery = No Fee.


Navigating the Regulatory Landscape

Ambulance collections are a legal minefield. Nexa is hard-coded for 2026 compliance with the newest state laws:

  • Oregon (HB 3243): Effective January 1, 2026, ground ambulances are prohibited from balance billing enrollees for more than the in-network cost-sharing amount.

  • Utah (HB 301): New 2025/2026 laws codify base rates and strictly prohibit ground ambulance providers from charging rates that exceed established caps.

  • Illinois (SB 2405): As of July 2025, non-participating ground ambulance providers must ensure enrollees incur no greater out-of-pocket costs than if the service were in-network.

  • New Hampshire (SB 245): Effective January 1, 2026, this law officially bans “balance billing” for ambulance rides. It also sets mandatory rates for how much companies can charge insurers, significantly changing the negotiation landscape for EMS providers.

  • California (AB 716) – The 12-Month Rule: While active since 2024, California’s law has a strict provision that creditors must know: You are prohibited from reporting adverse information to a credit agency or starting civil action against a patient for a minimum of 12 months after the initial billing. Nexa’s systems are pre-set to respect this “cool-down” period.

  • Maine (LD 1290): Maine now prohibits balance billing for all covered emergency and non-emergency ground ambulance transports. If no local rate is set, the law caps reimbursement at the lesser of 325% of Medicare or the billed charge, requiring precise coding to ensure you don’t over-bill and trigger a violation.

  • Texas (SB 2476): Since early 2024, Texas has banned balance billing for ground ambulance trips. However, in 2026, the focus has shifted to the Independent Dispute Resolution (IDR) portal. If a health plan underpays, we help you navigate the state-mandated mediation and arbitration process to secure the “just and reasonable” rate.

  • Washington State: The Balance Billing Protection Act has been expanded to include ground ambulances. It requires providers to bill health plans directly and strictly prohibits asking patients to “waive” their protections—a common mistake that can lead to heavy state fines.


Recent EMS Recovery Results

  • Private Ambulance Provider (FL): Recovered $280,000 in aged patient balances (120+ days) in just one quarter.

  • Municipal EMS Department (TX): Used our Step 1 Fixed-Fee service to recover $42,000 in “small balance” co-pays that had been sitting idle for six months.

  • NEMT Provider (CA): Reduced overall DSO (Days Sales Outstanding) by 32% within the first 6 months.


Frequently Asked Questions (FAQ)

1. Does the No Surprises Act protect patients from ground ambulance bills?

Not generally. The federal No Surprises Act protects patients from many out-of-network emergency bills and from covered air ambulance surprise bills, but it does not currently extend the same federal protection to ground ambulance services. State laws may provide additional protections, so an EMS provider must check the rules that apply to the patient, health plan, and state before pursuing a balance. CMS continues to treat ground-ambulance billing as a separate policy issue.

2. Can an ambulance provider collect the remaining balance when insurance underpays the claim?

Sometimes, but not automatically. Before billing or collecting from the patient, the EMS provider should determine whether the balance is legitimately the patient’s responsibility or whether a federal or state balance-billing restriction applies. This is especially important because several states now impose protections specifically on ground-ambulance bills, while federal No Surprises Act protections generally apply to air ambulances but not ground ambulances.

For this reason, insurance underpayments and true patient balances should be separated before an account enters collections. Nexa’s current page also emphasizes resolving insurance-denial issues before treating an account as ordinary patient debt.

3. When should an EMS or ambulance service send unpaid patient accounts to collections?

The best time is generally after insurance responsibility has been resolved and normal patient billing efforts have stalled—but before the account becomes heavily aged. Nexa currently positions accounts around 60–90 days past due for its early fixed-fee recovery stage, using softer outreach while the balance is still relatively fresh. Older or unresponsive accounts can then move to more intensive contingency recovery.

Early intervention is especially valuable for emergency-service bills because patients may simultaneously be dealing with hospital charges, lost income, deductibles, and other unexpected expenses.

4. What should an ambulance service do when an insurance claim is denied?

A denied ambulance claim should be reviewed before the patient is treated as responsible for the full balance. The provider should confirm the reason for denial, insurance information, medical-necessity documentation, coding, authorization requirements, and whether an appeal or corrected claim is appropriate.

For Medicare patients, for example, a patient can appeal when Medicare denies an ambulance service they believe should have been covered. Medicare also has specific Advance Beneficiary Notice requirements for certain non-emergency ambulance situations where the provider expects Medicare may not pay.

5. How much can a Medicare patient be charged for a covered ambulance trip?

When Original Medicare covers the ambulance trip, the patient generally pays 20% of the Medicare-approved amount after the Part B deductible. Medicare states that ambulance companies must accept the Medicare-approved amount as payment in full, so in most covered cases they cannot simply bill the patient for the difference between their normal charge and Medicare’s approved amount.

This makes payer verification especially important before placing a Medicare ambulance balance with a collection agency.

6. Can unpaid ambulance bills be reported to the credit bureaus?

Ambulance debt is generally treated as medical debt, so current medical-debt reporting restrictions matter. The CFPB currently states that unpaid medical debt over $500 and more than 365 days delinquent from the date of service could appear on a consumer credit report. State laws may impose additional restrictions, and some states specifically limit credit reporting or legal action involving medical debt.

For EMS providers, this is another reason to prioritize patient-friendly resolution, payment arrangements, hardship screening, and accurate insurance reconciliation before relying on credit reporting as a collection tool.

Need a Collection Agency for unpaid EMS Service bills?

Serving Nationwide: Contact us


Filed Under: Debt Recovery

Collection Agency for Manufacturing Companies

collection agency manufacturing company

Supply Chains Are Moving. Don’t Let Your Cash Flow Stall.

In the manufacturing sector, “Net 30” is rarely Net 30 anymore. With supply chain disruptions and rising material costs, clients are treating your invoices like interest-free loans.

You aren’t just selling a product; you are financing the raw materials, the labor, and the machine time. When a client delays a $50,000 payment, they are freezing your ability to restock inventory or repair a critical CNC machine.

The “Goodwill” Trap in B2B Collections

Manufacturers often hesitate to collect because of “the relationship.” You worry that a collection letter will offend a long-term distributor or jeopardizing a future contract.

  • The Reality: A client who values the relationship pays you on time. A client who ghosts you is managing their cash flow at your expense.

Nexa specializes in B2B Manufacturing Debt Recovery. We understand the difference between a disputed custom order and a simple refusal to pay. We help you enforce your terms without destroying your supply chain relationships.

The “Zero-Interest” Loan You Didn’t Approve

According to 2025 industry data, the average Days Sales Outstanding (DSO) in manufacturing has crept up to 56 days.

  • The Cost: If you operate on a 10% margin, a $20,000 bad debt requires you to generate $200,000 in new sales just to break even.

  • The Fix: You cannot afford to out-sell bad debt. You must collect it.

Why Nexa is the CFO’s Choice:

  • We Speak “UCC”: We understand the leverage of Uniform Commercial Code (UCC-1) filings and how to use them to secure your position against other creditors.

  • Early Intervention: Our Step 2 Flat-Fee Service ($15/account) is perfect for early-stage delinquency (45-60 days). It sends a professional “shot across the bow” that prioritizes your invoice over others.

  • Protect Your Name: We know your reputation in the industry is vital. Our agents (rated 4.85/5.0) act as professional mediators, not “junkyard dogs.”

A Recovery Workflow Built for Industry

We don’t treat a B2B manufacturing debt like a medical bill. Our process is designed for corporate finance departments.

Phase 1: The “Distributor Nudge” (Early Intervention)

  • Best For: Long-term clients who are “slow-walking” payments or claiming “check run” delays.

  • The Strategy: We deploy Step 2 (Flat-Fee). We send official third-party demands that reference your PO numbers and invoice dates. This signals that the account has been escalated to a professional firm.

  • The Result: The client’s AP department flags your invoice for immediate payment to avoid a credit mark. You keep 100% of the money. This is why we emphasize: Place accounts earlier (Day 60-90) for maximum recovery.

Phase 2: The “Contract Enforcement” (Late Stage)

  • Best For: Clients who have gone silent, custom order disputes, or companies showing signs of insolvency.

  • The Strategy: We move to Step 3 (Contingency). We use commercial skip-tracing to find the owners. We report the commercial debt to credit bureaus (Experian Business, Dun & Bradstreet), which threatens their ability to get financing elsewhere.

  • The Result: We leverage the threat of credit damage or legal action to force a settlement. We charge 20%-40%, but only if we succeed.

Real World Results: Recovering Industrial Revenue

Scenario A: The Custom Fabricator (Metalworks)

  • The Issue: A metal fabrication shop produced a $35,000 custom order for an automotive supplier. The supplier accepted the goods but stalled payment for 120 days, citing “cash flow tightness.”

  • The Fix: We ran a Litigious Check and found the supplier had pending lawsuits from other vendors. We moved immediately to Step 3, serving a demand that threatened a UCC lien enforcement.

  • The Outcome: The supplier, fearing a freeze on their own credit lines, wired the full balance within 5 business days.

Scenario B: The Food Processor (Packaging)

  • The Issue: A packaging manufacturer was owed $12,000 by a regional food brand. The brand claimed “quality issues” only after the invoice was 90 days past due—a common stalling tactic.

  • The Fix: We requested the signed Proof of Delivery (POD) and the initial QC acceptance report. We sent these with a formal legal demand letter.

  • The Outcome: Faced with documented proof that destroyed their dispute, the debtor agreed to a 3-month payment plan. The manufacturer recovered the funds and kept the client on “Pre-Pay” terms for future orders.

FAQ: B2B Debt Recovery

Q: Will sending a client to collections ruin the relationship?

A: Paradoxically, it often saves it. Financial ambiguity ruins relationships. By professionally enforcing your terms, you reset the dynamic. Once the debt is paid, you can resume business on clear terms (e.g., credit limits or deposits).

Q: Can you help if the debtor is in another state?

A: Yes. Manufacturing supply chains are global. We are licensed in all 50 states, so if you are in Ohio but your debtor is in Texas, we can pursue them seamlessly.

Q: What if they have filed for Bankruptcy?

A: We offer a Free Bankruptcy Check before we start. If they have already filed, we will advise you on whether to file a Proof of Claim or write it off, saving you time and legal fees.

Stop Financing Your Customers

Your margins are for your growth, not your client’s float. Secure your revenue with a partner that understands the mechanics of manufacturing debt.

Click here to Contact Us and start your recovery campaign.


Filed Under: Debt Recovery

  • « Go to Previous Page
  • Page 1
  • Interim pages omitted …
  • Page 37
  • Page 38
  • Page 39
  • Page 40
  • Page 41
  • Interim pages omitted …
  • Page 55
  • Go to Next Page »

Primary Sidebar


accounts receivable

Need a Collection Agency?
Kindly fill this form.
We’ll get in touch with you

    Please prove you are human by selecting the star.

    Compliance & Security

    • SOC 2 Type II Certified: Third-party audited data security and strict privacy controls.

    • HIPAA Compliant: Secure, legal processing of medical and municipal EMS accounts.

    • PCI-DSS Level 1: Highest tier of data encryption for secure payment processing.

    • FDCPA & FCRA Aligned: Full legal adherence to federal consumer protection laws.

    Recent Posts

    • Why Dental Patients Dispute Bills: The Nexa Collections Dental Account Dispute Index
    • 2027 Commercial Collections Benchmark: U.S. Late Payments, AR Risk and B2B Collection Trends
    • Bulk Account Placement: What a Collection Agency Actually Needs From You
    • Nationwide Debt Collection Agency Serving U.S. Cities
    • Chula Vista Collection Agency for Medical, B2B, Schools & Business Debt
    • Corpus Christi Collection Agency: Itemized Bill Rules for Practices
    • Riverside Collection Agency | For Logistics, Medical, Schools & Business Recovery
    • Collection Agency for Large Balances: High-Value B2B Debt Recovery

    Featured Posts

    • 6 Ways to Enhance your Customer Invoicing Experience
    • Pros and Cons of a Software Engineer Career
    • Pharmacy Debt Collection: Recovering Co-Pays, LTC Contracts & DME Balances

    Copyright © 2026 NEXACOLLECT.COM | This content is provided for general informational purposes only and should not be considered legal advice. Collection laws and requirements may vary by state, account type, documentation, debtor status, and specific facts. Please consult qualified legal counsel for guidance regarding your particular situation. Nexa and its authorized collection partners service accounts in accordance with applicable federal and state collection requirements. Visit our home page to know more about us.

    X
    Need a Collection Agency?
    Contact Us