• Skip to main content
  • Skip to primary sidebar

Nexa Collections

  • Home
  • Serving
    • Medical
    • Dental
    • Small Business
    • Large Business
    • Commercial Collections
    • Government
    • Utilities
    • Fitness Clubs
    • Schools
    • Senior Care Facility
  • Contact Us
    • About us
    • Cost

Debt Recovery

Collection Agency for Plastic Surgeons: Recover Unpaid Bill

plastic surgery
Nearly 2 million Americans undergo plastic surgery every year. Unfortunately, thousands of these patients default on their payment obligations, and many of these receivables are eventually forwarded to a Collection Agency.

Since cosmetic surgery is considered an elective surgery, it is usually not covered by regular insurance. Even though most patients use their Cash Savings, Health Cards ( like Care Credit Card), PatientFi, and Personal Credit Cards to make payments, many patients make payment arrangements directly with the doctor’s office. These arrangements can vary in detail and scope.

Most popular plastic surgery procedures include: Breast augmentation, Liposuction, Eyelid surgery, Nose surgery, Tummy Tuck and Tumor removal. It is estimated that Americans spend over 16 billion dollars annually on cosmetic and plastic surgeries. Since the cost of these procedures run from $3,000 to upwards of $25,000, non-payment by just a few patients can have a huge impact on the cash flow and profitability of the doctor’s office.

The in-house staff at the plastic surgeon’s office is really not qualified or experienced to handle past-due bills beyond sending a few reminder letters and making phone calls. This is where a Debt Collection Agency comes in and attempts to recover the unpaid bill more persistently, diplomatically and (most important) legally. Collection agencies have tools and subscriptions to various services that assist in a successful recovery of the medical bill. They can even initiate legal action against the patient by taking him to court if nothing else works.

The moment a Collection Agency is involved, the whole equation changes. Frankly, no one wants to hear from a Collection Agency.

The patient knows that the case has been forwarded to a professional debt collector and all those excuses he has been giving to the plastic surgeon’s office so far will not work anymore. They will now have to face all possible recovery measures permissible under the law.

The fees charged by collection agencies are worth the investment. In-fact if a plastic surgeon wishes, the case can be directly assigned for contingency collections in which there are no fees unless a recovery is made.

A plastic surgeon should hire a collection agency carefully. It is important to know whether the agency has extensive experience with medical collections and if it is insured. Do not go for a collection agency simply because it is near you, go for the better one instead. Your collection agency should be licensed to collect in the state where your debtors are located.

Just a handful of collection agencies perform the Litigious Patient scrub to check if the patient has a history of filing lawsuits ( or frivolous lawsuits), in such cases, the collection agency will advise the doctor’s office to take an alternate approach just to be safe.

If you need a debt collection agency with extensive experience in medical collections: Contact Us
Filed Under: Debt Recovery

Collision Repair Debt: Recovering “Pocketed Checks” & Deficiency Balances

body shop

In the auto body industry, you aren’t just fighting rust and bent frames; you are fighting a payment system designed to fail you.

The most dangerous phrase in a shop owner’s life is: “The insurance company said they mailed the check to me, I’ll bring it in when it arrives.“

When that customer ghosts you, it isn’t just a late payment. In many jurisdictions, spending an insurance payout designated for repairs is a form of insurance fraud or theft by conversion. You need a collection partner who knows how to use that leverage.

Need a Collection Agency for your Automotive Workshop: Contact Us

The 3 Hidden Revenue Leaks in Body Shops

1. The “Direction to Pay” Violation

You had the customer sign a Direction to Pay. The insurer ignored it (or claimed “clerical error”) and mailed a $4,500 check to the vehicle owner. The owner cashed it and stopped answering your calls.

  • The Agency Fix: This requires a specialized “misappropriation of funds” demand. A standard “please pay us” letter is weak here. The debtor needs to understand that this is bordering on criminal liability.

2. The “Lien Sale” Deficiency

You have a car that has been racking up storage fees for 60 days. The bill is $8,000. The car is a totaled 2014 sedan worth only $2,000 at auction.

  • The Trap: Most shops think, “I’ll just do a lien sale.”

  • The Reality: The lien sale gets you $2,000. You are still out $6,000. This is called a Deficiency Balance.

  • The Solution: You can (and should) send that remaining $6,000 balance to collections. The lien sale does not wipe the debt clean; it only offsets it.

3. “Project Purgatory” (Restoration Stalls)

Restoration shops face a unique nightmare: The “open checkbook” client who suddenly snaps the wallet shut when the car is stripped to the frame.

  • The Risk: You have a bay occupied by a non-rolling chassis. You can’t put a lien on a pile of parts easily, and you can’t push it outside to rust.

  • The Fix: Aggressive contract enforcement to recover “lost bay time” and labor hours already sunk into the tear-down.

Recent Results: Real Recovery Scenarios

These are actual types of cases specialized automotive agencies are resolving in 2025.

  • Case Study #1: The ADAS Calibration Dispute

    • The Debt: $1,450.

    • The Story: A customer picked up their vehicle but refused to pay for the “Post-Scan” and “Radar Calibration,” claiming it was a “money grab” that the insurance adjuster initially hesitated to approve.

    • The Outcome: The agency utilized the OEM Repair Procedures documentation to prove the safety necessity of the charge. The customer paid in full once the agency clarified the liability of driving an uncalibrated vehicle.

  • Case Study #2: The “Pocketed” Supplement

    • The Debt: $4,200.

    • The Story: Shop released a truck after the primary repair. A hidden damage supplement was approved later. The insurer sent the supplement check to the vehicle owner, who used it to pay their mortgage.

    • The Outcome: The collection team treated this as a wrongful retention of funds. Facing a potential credit score collapse and legal escalation regarding the misappropriated funds, the debtor arranged a 3-month repayment plan.

Frequently Asked Questions

Q: Can a collection agency help if I didn’t get a signature on the final invoice?

A: It is harder, but yes. If you have the pre-authorization to repair and text messages/emails approving the work or acknowledging the completion, that is often enough evidence to validate the debt. Digital footprints count.

Q: Does sending a customer to collections void the warranty on their repair?

A: Generally, yes. Most standard repair contracts state that warranties are only valid on “paid in full” invoices. A collection agency can use this as leverage: “Mr. Smith, your lifetime paint warranty is void until this $500 deductible is settled.”

Q: I charged storage fees because they left the car for 3 weeks after it was ready. Can I collect that?

A: Only if your initial intake paperwork clearly lists your daily storage rate and the “grace period” (e.g., Storage charges of $75/day begin 48 hours after notice of completion). If this was posted clearly, it is a valid, collectible debt.


Stop acting as a free bank for your customers.

If you need a cost-effective Collection Agency to help you recover past-due bills: Contact Us


Filed Under: Debt Recovery

Ohio Medical Debt Collection: Recover Patient Balances Simply & Diplomatically

Ohio medical debt collection requires a careful balance between recovering unpaid patient balances and protecting patient relationships. Nexa helps Ohio hospitals, clinics, physicians, and other healthcare providers recover overdue accounts using patient-friendly, HIPAA- and FDCPA-compliant collection practices. Our options include a $15 fixed-fee service where you keep 100% of recoveries, plus contingency-based collections for harder-to-recover accounts—all designed to improve cash flow while protecting your reputation. Ohio medical debt collection agency
Quick Answer: An Ohio medical collection agency must balance HIPAA data security and the Ohio Consumer Sales Practices Act (CSPA – ORC § 1345) with soft-touch patient outreach. Nexa Collections provides 50-state licensed, HIPAA-compliant medical debt collection starting at a $15 Fixed Fee Service per account. Backed by SOC 2 Type II security, signed Business Associate Agreements (BAAs), and a 4.85/5 rating across 2,000+ reviews, our soft Fixed Fee approach helps Ohio hospitals, clinics, and private practices recover unpaid co-pays, deductibles, and self-pay balances while retaining 100% of recovered principal.
🛡️ HIPAA & Signed BAA Compliant | ⚖️ Ohio CSPA (ORC § 1345) Aligned | 🏷️ $15 Fixed Fee Service | ⭐️ 4.85/5 Rated

Our Pricing

Nexa $15 Fixed Fee Service.  $15 flat fee per account, 0% commission, practice retains 100% of recovered principal. Ideal for early-stage patient balances, 30–90 days past due. Contingency Recovery (Late-Stage Defaults).  Performance-based recovery for aged, uncontactable, or out-of-state patients, no fee unless funds are recovered. Contrast this against traditional agencies charging 40% contingency fees.

blank

Nexa provides reputation-safe, equipped with all 50-state collections license, offering free credit reporting, free litigious debtor check, free bankruptcy scrub, and zero onboarding fees. Secure – SOC 2 Type II & HIPAA compliant. Over 2,000 online reviews rate us 4.85 out of 5. Backed by a responsive client support team!

Need a Collection Agency? Contact us


What $50,000 in Delinquent Ohio Medical A/R Actually Nets You

A simple static example on a $50,000 delinquent portfolio, an 80% eventual recovery rate ($40,000 collected):
Nexa $15 Fixed Fee Service Traditional 40% Contingency
Amount recovered $40,000 $40,000
Fee (50 accounts × $15) $750 $16,000 (40% of recovered)
Practice keeps $39,250 (98.1%) $24,000 (60%)

Specialized Ohio Healthcare Expertise

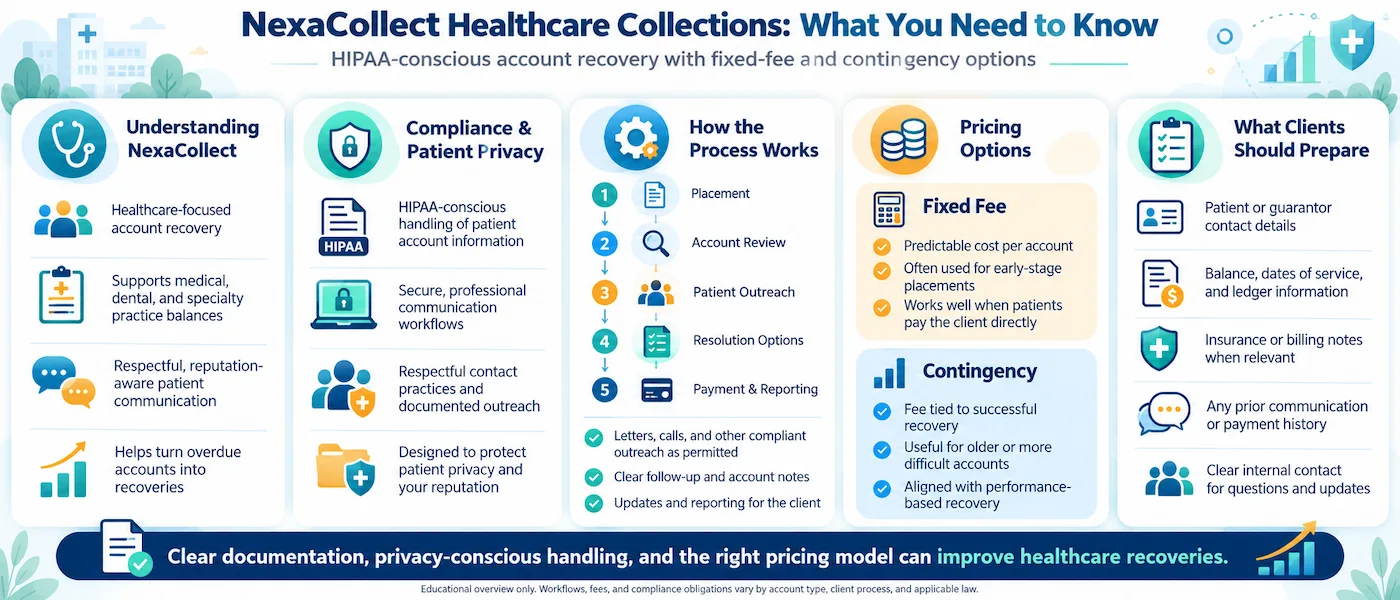
CSPA & Ohio Revised Code § 1345 Compliance. Ohio’s Consumer Sales Practices Act reaches further than the federal FDCPA alone, it’s been applied specifically to debt collection activity, including by assignees and collection agencies, not just original creditors. Outreach that’s technically FDCPA-compliant but ignores CSPA’s broader “unfair, deceptive, or unconscionable” standard still creates real exposure in Ohio. Out-of-State & Border-State Patient Recovery.  Ohio borders Kentucky, Indiana, Pennsylvania, West Virginia, and Michigan, and plenty of patients commute or relocate across those lines. 50-state licensing means an account doesn’t stall the moment a patient’s address changes. High-Deductible & Co-Pay Recovery.  Resolving patient-responsibility balances post-insurance adjudication without damaging patient-doctor trust, the same diplomatic approach used across every Nexa healthcare account. Statute of Limitations & Charity Care.  Ohio’s statute of limitations for medical debt is generally 6 years from the date the debt became overdue, longer than many states, so aged accounts still have real value, but the earlier an account is placed, the higher the recovery odds. For non-profit hospitals, Ohio Revised Code § 5112.17 governs charity-care eligibility, patients below the federal poverty level must be offered both care and financial assistance, and confirming that screening happened is part of keeping an account collection-ready before it’s placed. HIPAA-conscious patient account recovery, the collection process, fixed-fee and contingency pricing options, and information healthcare providers should prepare.

In-House Billing Staff vs. Traditional 40% Agency vs. Nexa $15 Fixed Fee Service

Factor In-House Billing Staff Traditional 40% Agency Nexa $15 Fixed Fee Service
Upfront cost Staff overtime, no direct cash outlay Often 40%+ contingency regardless of account age $15 flat fee, practice keeps 100% of what’s recovered
Ohio legal compliance (CSPA/ORC § 1345/FDCPA/Reg F) Depends on internal training and documentation discipline Varies, generic scripts may miss CSPA’s broader standard entirely Built around CSPA, FDCPA, and Regulation F from account intake
HIPAA & BAA security alignment Depends on internal protocols Varies by agency SOC 2 Type II certified, signed BAA on every account
Border-state / out-of-state recovery Limited to accounts staff can personally track Varies, some agencies aren’t licensed beyond one region Licensed in all 50 states, no interruption when a patient relocates

Recent Industry Case Results (Ohio Medical Recovery)

  • Case Result 1 (Multi-Specialty Medical Practice – Cleveland, OH): A multi-specialty clinic in Cleveland placed 150 past-due patient accounts totaling $60,000 in uncollected co-pays and deductible remainders. Utilizing Nexa’s $15 Fixed Fee Service, the practice recovered $42,000 within 35 days while retaining 100% of recovered principal for under $2,250 in total fixed fees—saving over $14,500 compared to traditional agencies charging 40% contingency fees.

  • Case Result 2 (Regional Surgical & Outpatient Center – Columbus, OH): An outpatient surgery center in Columbus faced $78,000 in defaulted self-pay balances across 28 accounts, including out-of-state patients from neighboring Kentucky and Pennsylvania. Nexa’s diplomatic, soft-touch Fixed Fee outreach resolved 19 accounts in under 40 days, recovering $54,600 with zero Ohio CSPA disputes and zero negative Google or Healthgrades reviews.

Frequently Asked Questions

How does Nexa ensure compliance with the Ohio Consumer Sales Practices Act (CSPA – ORC § 1345) during patient outreach?

By treating CSPA’s “unfair, deceptive, or unconscionable” standard as its own compliance layer, not something automatically covered by FDCPA adherence alone. Since CSPA has been applied specifically to debt collection agencies acting as assignees, every Ohio account is handled with that broader standard in mind, not just federal minimums.

Can a $15 Fixed Fee Service recover small patient co-pays and remaining insurance deductibles?

Yes, this is exactly the account type it’s built for. A professional, low-cost demand letter often resolves smaller, fresher balances without the practice paying a percentage of an amount that’s already modest.

How do you collect past-due balances from patients who reside in neighboring states like Kentucky, Indiana, or Pennsylvania?

Through 50-state licensing, which means an account doesn’t require switching agencies or losing continuity the moment a patient crosses one of Ohio’s five state borders. The same team stays on the account regardless of where the patient ends up.

How does Nexa guarantee HIPAA compliance and PHI protection with a signed Business Associate Agreement (BAA)?

Every medical account is processed under a signed BAA, with SOC 2 Type II certified data security governing storage and transmission. Outreach is limited to the balance owed, never the underlying clinical details.

How do soft diplomatic demand letters prevent unhappy patients from posting negative online reviews on Google or Healthgrades?

By resolving the balance through a calm, professional notice rather than an aggressive call, since most negative reviews stem from a confrontational interaction, not from receiving a formal letter. A diplomatic first touch is often enough to resolve the account before it ever becomes a public complaint.

Stop using a “one-size-fits-all” strategy in a state with complex liability traps.

Click here for a Free Compliance Audit of Your Ohio Bad Debt

Filed Under: Debt Recovery

Pennsylvania Medical Debt Collection Agency

A Pennsylvania medical debt collection agency helps hospitals, clinics, dental practices and other healthcare providers recover unpaid patient balances while navigating the state’s stricter collection environment. Because Pennsylvania generally restricts wage garnishment for medical debt, effective recovery relies more heavily on patient-friendly negotiation, compliant payment arrangements and appropriate legal remedies when necessary. Choose an agency experienced with HIPAA, FDCPA and Pennsylvania collection requirements, secure data handling, reputation protection and healthcare-specific accounts.

Pennsylvania medical debt collection agency

How to Recover Revenue When Two of the Usual Tactics Don’t Exist

Most collection strategies rest on two levers: garnish the wages, or wreck the credit score. In Pennsylvania, for medical debt, neither one is actually available right now, and an agency that doesn’t know that isn’t just ineffective, it’s selling your practice a strategy built on threats it legally can’t make good on.

Lever one, wage garnishment, doesn’t exist here. 
Pennsylvania law (42 Pa.C.S.A. § 8127) broadly prohibits wage garnishment for consumer debt, including medical bills. This isn’t a loophole or a technicality, it’s one of the strongest debtor protections in the country, and Pennsylvania is one of only a handful of states with it. The only exceptions are child support, taxes, federal student loans, and unpaid rent, none of which apply to a medical balance. A debtor who’s done any research knows this, so a collector who threatens garnishment anyway doesn’t just fail, they lose credibility for everything they say after.

Lever two, credit reporting as a nationwide federal ban, also isn’t currently active. 
A federal rule that would have broadly restricted medical debt on credit reports was finalized in early 2025, then vacated by a federal court in July 2025. There’s no nationwide ban in effect right now. Some protection still exists at the margins, the major credit bureaus voluntarily exclude paid debt and balances under $500 as their own policy, but “the CFPB banned this” is not an accurate description of where things currently stand, and leaning on it as leverage is a second empty threat stacked on the first.

HIPAA-conscious patient account recovery, the collection process, fixed-fee and contingency pricing options, and information healthcare providers should prepare.

What’s Actually In the Toolbox

Once you take those two off the table, three things remain, and they’re genuinely effective when used correctly.

Voluntary payment, collected early. 
With no legal hammer waiting in the background, getting a patient to pay before an account ages is disproportionately valuable here. A courteous, clearly-worded notice, sent while the balance is still fresh, resolves a meaningful share of accounts that would otherwise sit and age with no real remedy behind them.

Negotiated resolution. 
Since threats don’t move the needle, the actual skill is finding real, voluntary liquidity, a tax refund, savings, family assistance, and structuring a settlement around it. This is a different skill than sending a form letter, and it’s the difference between an agency that talks tough and one that actually collects.

Bank levies and property liens, after judgment. 
Wages can’t be touched, but a bank account can be levied once a court judgment is obtained, though Pennsylvania exempts $300 from that levy, so the remaining balance is what’s actually reachable. A judgment also becomes a lien against real property in the county where it was entered, which can complicate a future sale or refinance until it’s satisfied. Neither requires garnishment to work.

Does Pennsylvania really ban wage garnishment for all medical debt, with no exceptions?

The ban is broad but not absolute. Wages are protected from garnishment for medical debt and other ordinary consumer debt with only four narrow exceptions: child support, taxes, federal student loans, and unpaid rent. A medical balance itself doesn’t fall into any of those categories, so for practical purposes, garnishment isn’t a real option for recovering it.

If the CFPB’s credit-reporting ban isn’t currently active, can medical debt still show up on a patient’s credit report?

In limited cases, yes. The federal rule that would have banned it broadly was vacated in court, so there’s no nationwide ban right now. The credit bureaus’ own separate voluntary policy still excludes paid balances and amounts under $500, but a larger, unpaid, older balance can still legally appear, this is a narrower, less certain form of leverage than “the government banned this,” which is the inaccurate version some agencies still use.


Stop relying on empty threats. Start using a strategy that works in Pennsylvania.

Click here to Request a Quote & Audit


The Rest of the Landscape

Pennsylvania’s Act 6 sets a default legal interest rate of 6% on debts where no specific contract states a different rate, worth checking before an agency assumes a higher rate applies. The statute of limitations for most medical debt is 4 years from the date of the last payment or missed payment; past that window, the debt is time-barred, and pursuing it anyway risks a countersuit rather than a recovery.

Patients across Pennsylvania’s major health systems, Allegheny Health Network in Pittsburgh, Penn Medicine in Philadelphia, and others, are frequently confused by complex EOBs. Outreach that helps a patient actually understand what insurance didn’t cover tends to resolve balances faster than outreach that skips straight to a demand.

Pricing

See the full pricing breakdown for how these compare across account types.

Flat-Fee Notices (Steps 1-2, ~$15/account). 
Courteous, clearly-worded notices sent as an extension of your billing office. Best for accounts where voluntary payment is the realistic outcome. You keep 100% of what’s recovered.

Negotiated Resolution (Step 3, 40% contingency). 
For non-responsive accounts, structured settlement negotiation aimed at real liquidity rather than empty threats.

Judgment & Asset Execution (Step 4, 50% contingency). 
Bank levies and property liens, pursued only where the balance and circumstances justify legal escalation, with client approval.

blank

Nexa provides reputation-safe, equipped with all 50-state collections license, offering free credit reporting, free litigious debtor check, free bankruptcy scrub, and zero onboarding fees. Secure – SOC 2 Type II & HIPAA compliant. Over 2,000 online reviews rate us 4.85 out of 5. 

Need a Medical Collection Agency? Contact us


Filed Under: Debt Recovery

Illinois Healthcare Debt Collection: Recover Patient Balances & Protect Practice Reputation

Ask five people what changed in Illinois medical debt law this year and you’ll get five confident, slightly different answers. That’s because “Illinois medical debt has changed” is really shorthand for three separate legal threads that get blended together constantly, one of them solid and operational, one genuinely still unsettled, and one so new most agencies haven’t caught up to it yet. Getting the three straight matters more than reciting the headline, whether you’re running medical debt collection in-house or through a partner.

blank

Nexa provides reputation-safe, equipped with all 50-state collections license, offering free credit reporting, free litigious debtor check, free bankruptcy scrub, and zero onboarding fees. Secure – SOC 2 Type II & HIPAA compliant. Over 2,000 online reviews rate us 4.85 out of 5. 

Need an Illinois Medical Collection Agency? Contact us


Thread One: The Screening Requirement (Solid, Operational, 2024)

The Protect Illinoisans from Unfair Medical Debt Act requires hospitals to screen uninsured patients for public health insurance programs and financial assistance before pursuing collection, and to provide language interpreters where requested. This is the least ambiguous of the three threads: it’s in effect, it’s operational, and it changes what “clean” documentation looks like before an account should ever reach collections. A collection partner that isn’t verifying this screening happened before making the first call is creating exposure that has nothing to do with how politely they ask for payment.

Thread Two: The Credit-Reporting Ban (Real, But Less Settled Than It Sounds)

Illinois Public Act 103-0648, a separate law from the screening act above, took effect January 1, 2025, and makes it unlawful for a consumer reporting agency to include medical debt on an Illinois resident’s credit report. This sits on top of the state’s broader collection agency laws, not in place of them. This is frequently described as a done deal. It isn’t quite.

In October 2025, the CFPB itself stated that federal law (the Fair Credit Reporting Act) may not permit states to ban medical debt from credit reports at all, echoing a federal court’s July 2025 ruling that struck down the CFPB’s own broader medical-debt reporting rule and specifically flagged that FCRA may preempt state-level bans like Illinois’s. None of this has overturned the Illinois law yet, that would require the federal government to actually sue and win. But it means the honest description is “currently in effect, with real legal uncertainty about how long that lasts,” not “permanently settled.” A collection strategy built entirely on “credit reporting no longer works here” is betting on a specific legal outcome that hasn’t actually happened yet.

Separate from Illinois’s own law, the major credit bureaus also maintain their own nationwide voluntary policy: no reporting of medical balances under $500, and paid balances get removed. That bureau policy isn’t affected by any of the state-level legal uncertainty above, it applies regardless of what happens to Illinois’s specific statute.

Thread Three: Coerced Debt Protections (New, and Not Yet on Most Agencies’ Radar)

Effective January 1, 2026, Illinois’s amended Collection Agency Act (via HB 3352 and SB 2457) creates protections for “coerced debt,” debt a patient didn’t willingly incur due to fraud, duress, domestic violence, or identity theft. Once a patient files a statement of coerced debt, collection activity must pause, and ignoring that filing carries real penalties. This is recent enough that a lot of collection workflows, including plenty of agencies still marketing themselves on 2024’s changes, haven’t built it into their process yet.


What This Actually Means for Pricing and Process

None of the three threads change the basic math of getting paid, they change what has to be true before pursuing payment. This is exactly the kind of nuance that makes outsourcing accounts receivable to a specialist worthwhile rather than handling it entirely in-house. Nexa’s process is built around confirming screening documentation exists (Thread One), treating credit reporting as a secondary tool rather than primary leverage given the genuine uncertainty around it (Thread Two), and checking for a coerced-debt filing before escalating an unresponsive account (Thread Three).

Phase 1 (Fixed Fee, ~$15/account): Diplomatic, clearly-worded notices, no aggressive legal jargon, for patients who simply forgot or misread their EOB. You keep 100% of what’s recovered.

Phase 2 (40% Contingency): For non-responsive accounts, specialists negotiate payment plans that respect Illinois’s disposable-earnings garnishment limits rather than pursuing garnishment against patients who are legally judgment-proof. Every account is also screened against active bankruptcy filings before any escalation.

Phase 3 (50% Contingency, Legal): Escalation through an Illinois attorney network when warranted, respecting the state’s judgment interest rules for smaller balances.

blank


Does the credit-reporting ban mean Illinois medical debt has no real collection leverage left?

Not entirely, and treating it that way misreads where things stand. The ban is currently in effect, so it shouldn’t be relied on as a threat, but it also hasn’t been overturned, so it’s not simply gone either. The practical move is building a strategy that doesn’t depend on credit-reporting leverage at all, communication, documented payment plans, and legitimate legal escalation where warranted, rather than betting on either version of the story being permanently true.

How does the “coerced debt” law actually change a collection workflow?

It adds a checkpoint before escalation: once a patient files a statement of coerced debt, claiming the balance stems from fraud, duress, domestic violence, or identity theft, collection activity has to pause while that claim is reviewed, and continuing to pursue payment after a filing carries real penalty exposure. Building this check into intake now, rather than after a complaint, is the difference between routine compliance and a preventable violation.


Why Illinois Practice Managers Choose Us

HIPAA-conscious patient account recovery, the collection process, fixed-fee and contingency pricing options, and information healthcare providers should prepare.

We navigate the Chicago-vs-downstate divide. Collecting in Naperville looks different from collecting in Carbondale, and outreach adjusts accordingly rather than using one script statewide.

We protect non-profit “community benefit” status. For non-profit hospitals, aggressive collections can threaten tax-exempt standing. Respectful outreach protects both community reputation and the revenue needed to keep operating.

We understand Illinois’s wage protection limits. Illinois protects a larger share of disposable earnings from garnishment than the federal standard, so energy goes toward accounts that can actually yield results rather than judgment-proof pursuits.

Illinois by the Numbers

Roughly 17% of Illinois residents carry some form of medical debt, and that rate climbs past 20% for households earning under $35,000 annually. Cook County has one of the state’s highest concentrations of medical debt, and Black and Hispanic communities are affected at nearly double the rate of white residents. Medical bills remain a leading cause of bankruptcy filings statewide.

Regional Focus

Chicagoland & Cook County: high-volume recovery for urgent care chains and dental networks.
Central Illinois (Peoria/Bloomington): working alongside large regional health systems to recover copays and deductibles.
Rockford & Northern Illinois: supporting private practices navigating a shifting regional economy.

Additional FAQs

What is the statute of limitations for medical debt in Illinois?

Generally 5 years for unwritten contracts, which covers most standard medical bills, and 10 years for written contracts. See how statutes of limitations work for how this plays out once a debt is time-barred. Waiting that long makes collection significantly harder in practice; the strongest recovery window is the first 90 days past due.

Do you handle the mandatory financial-assistance screening for us?

Not as a substitute for your own billing department, but as a final check: accounts that look like they haven’t been properly screened get flagged so the gap can be fixed before it becomes a violation, rather than after.

If you’re still comparing options, see how to select a collection agency before making a final call.

Need a Medical Collection Agency in Illinois? Contact Us

Filed Under: Debt Recovery

Unpaid Bail Bond: Collection Agency to Recover Money

bail bond collection agency

Bail bond agents help their customers at the time when they need them the most, yet many customers do not fulfill their obligation to make payments on time.

Recovering money from such clients (debtors) is not easy. Debt collection laws prohibit even the creditors in most states from using threatening language, unlawful pressure tactics or making false statements, making the recovery process even harder.

A Bail Bond is a type of surety bond facilitated by a bail agent or Bail Bondsman who secures the release of a defendant from jail. The surety bond, acts as insurance that the accused will show up in court when ordered to do so. A bail bond company will usually accept a cosigner with a good credit score when enrolling for a payment plan.

If payments are delayed, a bail bond agent usually imposes a late fee that is added to the principal amount. However, if a debtor who has failed to make payments/installments on the previously agreed amount, he will find extremely hard to make further payments because the balance just went up due to the added interest. Chances that this person will become delinquent on his bills rise significantly after 60 days of non-payment.

It is extremely common for Bail Bond businesses to involve a Collection Agency which makes persistent efforts to recover money from the debtor. Involvement of a Debt Collection Agency also protects the relationship of Bail Bond agents with their customers and limit legal liabilities.

Need a Collection Agency for your Bail Bond Business?
Serving Nationwide. Contact us 

A cost-effective collection agency with extensive experience in recovering money from the customers of bail bond industry. Please make sure you have all the backup documentation ready if debt verification is requested by the debtor.

A bail bond collection agency will also ensure that all debt collection laws are followed, reducing the chances of a counter lawsuit from the debtor. They are often able to recover the balance in full or renegotiate a new payment plan with the debtor. To prevent delinquent accounts going permanently red, hiring a bail bond collection agency is the best bet.

Instead of relying on wishful thinking and wasting time, it is extremely important to forward the account quickly to a bail bond Collection Agency because the chances to recovering money from the debtor and the cosigner fall significantly as the time passes by.  These accounts are directly assigned for contingency collections due to the nature of intensity and diplomatic efforts required.

A professional Bail Bond collection agency will run several checks against the debtor, the most important one being the Skip Trace, which in most cases enables to find the latest address and phone number of the debtor if he is hiding.

Collection agencies are insured for any potential lawsuit that may come during the due course of recovering the debt. They may take the debtor to court if the amount is significant and may attempt to garnish wages or attempt to attach assets if the state law permits them to do so.


Filed Under: Debt Recovery

  • « Go to Previous Page
  • Page 1
  • Interim pages omitted …
  • Page 36
  • Page 37
  • Page 38
  • Page 39
  • Page 40
  • Interim pages omitted …
  • Page 55
  • Go to Next Page »

Primary Sidebar


accounts receivable

Need a Collection Agency?
Kindly fill this form.
We’ll get in touch with you

    Please prove you are human by selecting the heart.

    Compliance & Security

    • SOC 2 Type II Certified: Third-party audited data security and strict privacy controls.

    • HIPAA Compliant: Secure, legal processing of medical and municipal EMS accounts.

    • PCI-DSS Level 1: Highest tier of data encryption for secure payment processing.

    • FDCPA & FCRA Aligned: Full legal adherence to federal consumer protection laws.

    Recent Posts

    • Why Dental Patients Dispute Bills: The Nexa Collections Dental Account Dispute Index
    • 2027 Commercial Collections Benchmark: U.S. Late Payments, AR Risk and B2B Collection Trends
    • Bulk Account Placement: What a Collection Agency Actually Needs From You
    • Nationwide Debt Collection Agency Serving U.S. Cities
    • Chula Vista Collection Agency for Medical, B2B, Schools & Business Debt
    • Corpus Christi Collection Agency: Itemized Bill Rules for Practices
    • Riverside Collection Agency | For Logistics, Medical, Schools & Business Recovery
    • Collection Agency for Large Balances: High-Value B2B Debt Recovery

    Featured Posts

    • Collection Agency for Snow Removal Companies
    • Top 10 Financial Issues Faced by Dentists
    • How to Choose a Collection Agency: 14-Point Checklist (With Red Flags)

    Copyright © 2026 NEXACOLLECT.COM | This content is provided for general informational purposes only and should not be considered legal advice. Collection laws and requirements may vary by state, account type, documentation, debtor status, and specific facts. Please consult qualified legal counsel for guidance regarding your particular situation. Nexa and its authorized collection partners service accounts in accordance with applicable federal and state collection requirements. Visit our home page to know more about us.

    X
    Need a Collection Agency?
    Contact Us