• Skip to main content
  • Skip to primary sidebar

Nexa Collections

  • Home
  • Serving
    • Medical
    • Dental
    • Small Business
    • Large Business
    • Commercial Collections
    • Government
    • Utilities
    • Fitness Clubs
    • Schools
    • Senior Care Facility
  • Contact Us
    • About us
    • Cost

Debt Recovery

Collection Agency for Rehab Centers and Physiotherapists

Healing Your Bottom Line: Strategic Recovery for Rehab Centers & Physiotherapy

In the current healthcare landscape, patient care is a high-touch commitment. Whether you are running an outpatient clinic or a specialized rehab center, the bond between therapist and patient is your practice’s strongest asset. However, when unpaid balances linger, they threaten the financial health of your facility and the focus of your medical staff. You need a recovery partner that mirrors your professional standards: firm enough to secure results, yet empathetic enough to keep your reputation intact across the nation.

Nexa provides a reputation-safe approach, equipped with all 50-state collections license, offering free credit reporting, free litigious debtor check, free bankruptcy scrub, and zero onboarding fees. Secure – SOC 2 Type II & HIPAA compliant. Over 2,000 online reviews rate us 4.85 out of 5. 

Need a Collection Agency? Contact us


Transparent Recovery Options

We provide clear, performance-driven pricing to suit the cash flow needs of medical practices across the country:

  • The Flat-Fee Approach: Just $15 per account. You retain 100% of the recovered funds.

  • The Performance Model: A 40% contingency fee. If our Account Reconciliation Team doesn’t recover your money, you don’t pay a cent.

Money Saver Tip: Many of our partners effectively receive our fixed-fee service for free by declaring it as a Business Expense in taxes after consulting with their CPA.


The Velvet Hammer: Why Cooperative Mediation Wins

A patient’s journey from injury to recovery is built on trust. Breaking that trust with aggressive, “old-school” collection tactics can lead to negative feedback and a damaged professional brand. We use a diplomatic style we call the “Velvet Hammer”—firm enough to ensure your invoice moves to the top of the pile, but respectful enough to protect your 5-star reputation.

By working with the debtor rather than against them, we foster a genuine “will to pay.” Our team utilizes a litigation scrub and bankruptcy check to ensure we are pursuing viable accounts, while our bilingual Spanish-speaking collectors ensure clear communication across diverse patient demographics. Involvement of the Account Reconciliation Team significantly improves recovery rates; the earlier you assign the debt, the better the results.


Recent Recovery Results

Outpatient Physical Therapy

A high-volume clinic had an aging balance of $4,200 from a long-term rehabilitation patient who had stopped responding to billing reminders.

  • Step 1: We performed an address check via USPS and a skip trace to find the patient’s updated contact details after a cross-state move.

  • Step 2: Our team initiated recorded, empathetic calls to discuss a voluntary repayment schedule.

  • Step 3: The balance was paid in full within 30 days, allowing the clinic to avoid a total loss.

Occupational Rehab Center

A regional rehab facility faced a $6,000 dispute regarding a complex insurance co-pay that the patient felt was inaccurate.

  • Step 1: The Account Reconciliation Team conducted a financial scrub to verify the debtor’s actual ability to pay.

  • Step 2: We utilized modern email and text outreach to bridge communication gaps and provide digital documentation.

  • Step 3: Secured a settlement for 90% of the balance within two weeks, preserving the patient-provider relationship for future care.


The Rehab Recovery Red Flag Box: 3 Common Pitfalls

  1. Staff Overextension: Forcing your highly trained front-office staff to act as debt collectors. It ruins morale and takes them away from patient care.

  2. Delaying the Assignment: Letting accounts sit past the 90-day mark. Current data shows that early intervention is the strongest predictor of successful recovery.

  3. The “Loud” Agency Risk: Using an agency that uses aggressive tactics. In a digital world, one “shouting” collector can trigger a wave of negative online reviews for your clinic.


Compliance and Integrity

We treat your reputation as if it were our own. All calls are recorded and randomly reviewed to prevent “rogue collector” behavior and mitigate “review-bomb” risks. Our process is fully compliant with federal rules including the FDCPA, HIPAA, and the Fair Credit Reporting Act (FCRA). We utilize:

  • USPS Address Checks: To ensure all notices are delivered accurately.

  • Skip Tracing: To locate debtors who have moved within the “Current” billing cycle.

  • Credit Reporting: Available when permitted and requested to provide extra leverage for high-balance accounts.


National Physiotherapy & Rehab FAQs

How do you handle patients who say they “forgot” to pay after their session?
We use a proactive approach including email and text reminders to make payment as easy as possible. Our goal is to make your invoice the first one they want to resolve by providing a respectful, easy-to-follow path to payment.

Why shouldn’t I just let my office manager handle these calls?
Your employees should focus on the core work they were hired for—helping people heal. Collections is a specialized skill that most medical professionals find uncomfortable. By letting our Account Reconciliation Team handle it, you reduce staff burnout and improve your actual recovery percentage.

How does the “Velvet Hammer” approach protect my online reviews?
Most negative reviews stem from patients feeling harassed or unheard. By using mediation rather than confrontation, we solve the underlying payment issue without creating the friction that leads to a “review-bomb.” All interactions are recorded to ensure your practice is never associated with unprofessional behavior.
Filed Under: Debt Recovery

Wellness Industry Collections: Protecting Your Revenue and Your Reputation

In the spa and salon industry, your brand is built on relaxation and trust. However, unpaid memberships, “no-show” fees, and bounced payments for high-end beauty packages can disrupt your cash flow.

You need a recovery partner that understands the “Velvet Hammer” approach: firm enough to get paid, but respectful enough to ensure your 5-star Yelp or Google rating stays intact.

Nexa provides a reputation-safe approach, equipped with all 50-state collections license, offering free credit reporting, free litigious debtor check, free bankruptcy scrub, and zero onboarding fees. Secure – SOC 2 Type II & HIPAA compliant. Over 2,000 online reviews rate us 4.85 out of 5. We recover your funds without the “debt collector” drama.

Need a Collection Agency? Contact us


Two Lanes to Restore Your Cash Flow

  • Fixed-fee $15: Ideal for small balances like membership dues or service no-shows. You keep 100% of the money we recover.

  • Contingency (20%–40%): No recovery, no fee. Best for larger medical spa balances or older accounts that require intensive skip tracing.

blank

Why Spas and Salons Choose the Velvet Hammer

  • Bilingual Outreach: We provide Spanish-speaking collectors to ensure clear communication with your entire client base.

  • MedSpa Compliance: For medical spas, we are fully HIPAA compliant, ensuring patient privacy is protected during the recovery of cosmetic procedure fees.

  • Credit Reporting: If a balance remains unpaid, we offer credit reporting (where permitted) to provide the necessary leverage to settle the account.

Red Flag Box: 3 Signs a Client is Avoiding Payment

  1. The “Dissatisfied” Retrospective: They loved the service during the appointment but suddenly “found an issue” once the invoice arrived.

  2. Card-on-File Failures: Recurring membership payments begin declining, and the client stops responding to your front desk.

  3. The Chargeback Threat: Using credit card disputes as a way to avoid paying for services already rendered.

Frequently Asked Questions

Can you collect on “No-Show” fees?

Yes. If your intake forms clearly state your cancellation policy, we can professionally mediate those balances to ensure your time is compensated.

Will this hurt my local reputation?

No. We use a “concierge” style of communication. Most clients pay simply because a third party has stepped in to document the commitment, not because of aggressive tactics.

Do you handle Medical Spa (MedSpa) accounts?

Yes. We specialize in the unique regulatory needs of MedSpas, balancing debt recovery with the strict privacy standards required for medical aesthetic procedures.

Contact us for your debt collection needs.

Filed Under: Debt Recovery

What Golf has Taught me about Debt Collections

debt collection golf

Being an avid golfer and working in the collection industry for the last 22 years, it wasn’t long enough that I started to find so many similarities between the two.

1. Practice and Patience

Like Golf, debt collection is an art that requires sufficient time to learn and improve the game. Then there are days when we have excellent collection results and others when nothing seems to be working, precisely similar to the day-to-day fluctuations we experience in golf.

Keep your patience, continue to introspect, and stay focused. Put up a smile, clear your head, and start your next call with a positive attitude.

Do you need a Collection Agency for your Golf Course? Contact Us

Golf courses have huge operating expenses. Their accounts receivables may include recovery from contractors (pavers, cart repairers, etc), credit card reversals, unpaid membership fees, damages and more. You must keep a signed contract/receipt/invoice to support the debt.

2. Play Smarter, Not Harder:

Apply too much force in the game of golf, and your shots start to go haywire. A successful debt collector needs to have an acute presence of mind. He should know how to handle the call based on the responses they get from the debtor and somehow make him pay. Smart and straightforward tactics work far better than brute force and anger.

Best collection rates in the industry are achieved with good acumen and the presence of mind, not by simply pushing too hard or blindly sticking to a script that your boss has given you.

3. Never use a Driver for shorter shots.

When your ball is 90-120 yards away from the hole, we use Irons, not the Driver. Suggesting the right product to the client is very important.

Low-cost collection letters are more suitable for debts that are no more than one year old. Collection calls are suitable for accounts over that limit and Legal suit as a last resort. Suggesting the most optimum solution to your client will lower their collection cost,  and make them stick with your agency for a long time.

4. Concentration:

Before starting a collections call, remove your mind from those daily “Breaking News”, forget about your social media conversations, and put the phone aside. Everything that can potentially distract you during your conversation with the debtor.  Exactly what my golf trainer says … Stay focused – razor sharp.

5. Control of Emotions

Debtors deal with crappy calls all day long. It is crucial to control your emotions, most importantly your anger. Just like in golf, the game is all but over once you are agitated.

6. Short Game is more important:

Every collection call need not be a 10+ minute conversation, probably only in those cases where the outstanding debt is too high. Time is money for debt collectors. It is important to remember that you are not working to hear long stories of your debtors but to collect debt in optimum time.

The idea is to reach the target in a minimum number of shots. Similarly, in Debt Collections, the idea is to recover maximum money with the minimum number of contacts.

7. Buy a good golf set: Not the cheapest one, not the costliest one

You can buy a bargain golf set for as low as $200. But most of us know they are not too good. They will likely spoil your game. There is a reason most people buy branded golf sets like TaylorMade, Callaway, Titleist, Ping etc. These golf sets have the appropriate design, metal and technology to get the best shots. A golfer does not need to break the bank, but a decent branded set will come between $500 to $1000.  This will improve your game and accuracy and last you for many years.

Similarly, never go for a collection agency just because it has the lowest fees. Good collection agencies invest a lot of quality manpower, technology, and services to provide maximum returns. So even if you have to pay 10%-15% extra for a better collection agency, go for it. Higher returns will make that little extra investment/fee look minuscule.

If you are looking for a good collection agency: Contact Us


Filed Under: Debt Recovery

Flat Fee Collection Agency: Written Demands Letter Service

Professional collection letters offer an amicable and effective way to recover newer debts. They often outperform emails and phone calls because they cannot be filtered or blocked, they create the written record required for compliant collection activity, and they can shift a debtor’s mindset from “this is a debt I can ignore” to “this is a creditor I need to address.”

Before mailing, each account is screened for address accuracy and bankruptcy status. The service costs a flat $15 per account and resolves approximately 7 out of 10 accounts placed 60–90 days past due—often before any contingency fee applies.

A person holding collection letter in hand and looks concerned


Why Smart Collection Letters Are the “Secret Weapon” of Debt Recovery

In a digital-first world, it is easy to assume that an email or a text message is the fastest way to get paid. While those tools have their place, the physical collection letter remains the heavyweight champion of debt recovery.

Why? Because a professional collection letter is more than just a piece of paper. It is a legal instrument, a psychological trigger, and—when done correctly—a data-driven tool that locates debtors who are trying to hide.

Note: Consumers can easily use technology to block debt collector’s phone calls, but they cannot block the US Postal Service from delivering mail to their physical address. This ensures your demand letters bypass digital filters and establish the mandatory “paper trail” required for legal notifications and future escalation.

Flat Fees Collection Letters

Here is why upgrading to a professional third-party letter service is the most cost-effective move you can make for your bottom line.

1. The Power of “Smarter” Mail (Data Scrubbing)

One of the biggest reasons internal billing fails is that you are often mailing invoices to a “dead” address or pursuing a debtor who legally cannot pay.

We don’t just stuff envelopes; we run your accounts through a sophisticated data scrub before a single stamp is used. This “Smarter Mail” approach includes:

  • Change of Address (NCOA) Scrub: People move frequently, often to avoid debt. We run your list against the USPS National Change of Address database. If your debtor has moved, we find their new address automatically, ensuring your demand lands in their hands, not an empty mailbox.

  • Bankruptcy Screening: Trying to collect from a debtor who has filed for bankruptcy is not just futile; it’s illegal. It violates the “Automatic Stay” and can lead to severe fines. We screen for active bankruptcy filings before we mail, saving you the cost of the letter and the risk of a federal lawsuit.

  • Litigious Defaulter Check: Some professional debtors make a living by trapping businesses into technical violations of collection laws and then suing them. We identify these habitual litigants upfront, allowing us to handle their accounts with extreme caution or advise you to close the file to protect your business.

2. The Psychological Shift: From “Vendor” to “Creditor”

When a customer sees an envelope from your business, they see a familiar vendor they can negotiate with or ignore. When they see a colored envelope from a third-party agency, the psychological dynamic changes instantly.

  • Breaking the Cycle: A third-party letter signals the end of the “service” phase and the beginning of the “recovery” phase. It creates a sense of urgency that a standard “Past Due” stamp simply cannot match.

  • The “Paper Weight” Effect: An email can be deleted with a swipe. A physical letter sits on the kitchen counter or the CEO’s desk. It occupies physical space, serving as a tangible, nagging reminder that the debt is real and is not going away.

3. Compliance and the “Paper Trail”

In the event of a dispute or future litigation, documentation is everything.

  • FDCPA Compliance: The Fair Debt Collection Practices Act requires specific disclosures (the “Validation Notice”) to be sent to consumers. Our letters are drafted by legal experts to ensure strict compliance, protecting your brand from liability.

  • Proof of Diligence: If you eventually decide to sue a debtor (Step 4), you must prove you made every reasonable effort to collect. A series of documented, professional demand letters provides the court with irrefutable evidence of your due diligence.

4. By the Numbers: Why Print Performs

Data consistently shows that physical mail cuts through the digital noise.

  • 100% Delivery Potential: Unlike emails which are often blocked by spam filters or buried in “Promotions” tabs, physical mail has a 100% deliverability rate to valid addresses.

  • Higher Engagement: Studies show that direct mail has a significantly higher cognitive engagement rate than digital media. People spend more time reviewing a letter than they do scanning an email.

  • 70% Resolution: When accounts are sent to us between 60 and 90 days past due, our flat-fee letter service resolves roughly 7 out of 10 accounts without ever needing to pay a contingency fee.

5. Stop Wasting Equity on High Fees

The old way of collecting—waiting 6 months and then handing over 50% of the debt to an agency—is a bad deal for you.

  • The Flat-Fee Revolution: Our Step 1 & 2 service allows you to send these powerful, data-scrubbed letters for a fixed cost (e.g., $15 per account).

  • Keep Your Money: If a $5,000 debt is paid after receiving our letter, you pay $15, not $2,000. You keep the equity where it belongs: in your business.

Providing Flat-Fee Services Nationwide

Need a Debt Collection Agency? Contact Us

Frequently Asked Questions

Are collection letters more effective than emails or phone calls?

Often, yes. Physical mail can’t be filtered into a spam folder or blocked the way calls and emails can, and a letter sitting on a counter or desk works as a tangible reminder that a deleted email doesn’t. USPS delivery also creates a documented paper trail that’s useful if an account ever needs to escalate.

What is a “Smarter Mail” data scrub?

Before a letter goes out, the account is checked against the USPS National Change of Address database to catch a debtor who’s moved, screened for active bankruptcy filings (since collecting from someone under an automatic stay can be illegal), and flagged if the debtor has a history of suing collectors over technical violations.

Do collection letters need to comply with the FDCPA?

Yes. The Fair Debt Collection Practices Act requires specific disclosures, including a validation notice, in early collection communications. A letter missing those disclosures can expose the sender to liability rather than protect against it.

How much does a professional collection letter service cost?

A flat-fee letter service typically runs around $15 per account, regardless of the balance owed — compared to a contingency agency that might take a much larger share of whatever is eventually recovered.

How long does it take to see results from a collection letter?

Results vary, but accounts placed between 60 and 90 days past due tend to respond fastest, since the debt is still fresh and the debtor hasn’t mentally written it off yet.

Can a collection letter alone lead to legal action?

Not by itself, but a documented series of professional letters serves as evidence of due diligence if an account eventually needs to move to litigation — courts generally want to see that reasonable collection efforts were made first.

Are collection letters cost effective?

Yes. Professional letter services benefit from bulk printing and mailing rates that are difficult to match in-house — sending letters yourself often costs two to three times as much per piece. The margin on this service is thin enough that it’s priced closer to a convenience than a profit center for the agency.

What happens if the debtor disputes the debt?

If a debtor disputes the debt or a letter comes back undeliverable, the letter service typically pauses rather than continuing to escalate automatically. From there, you can resolve the dispute directly with the debtor, or move the account into the contingency service if you’d like the agency to step in and handle it.

Are there any hidden fees once I’ve paid the fixed fee?

No. The flat fee covers the full letter sequence with nothing added later, and if the debtor pays as a result, payment goes directly to you as the creditor — the agency doesn’t take a cut or route the payment through itself.

Can sending a collection letter hurt my reputation?

Unlikely, if the debt is legitimate. A collection letter is one of the more measured ways to raise an unpaid balance, especially compared to phone calls or credit reporting. A debtor who ignores it is generally aware that more assertive steps, like phone contact or eventual credit reporting, are the next escalation, not a surprise.

Take the Next Step

Stop sending invoices into the void. Use a system that cleans your data, protects your legal standing, and demands attention.

Click here to Contact Us and upgrade your recovery strategy today.

Filed Under: Debt Recovery

Beyond the Bill: Protecting Your Firm’s AR and Reputation During Collections

tax debt recovery

For most CPAs and tax preparers, the end of tax season brings a familiar, frustrating reality: the “collection tail.” While you’ve successfully navigated the latest tax code changes and met the April deadlines, a significant portion of your revenue remains locked in unpaid invoices.

The average cost for a simple 1040 with Schedule C is approximately $457, while corporate returns for S-Corps and Partnerships frequently start at $1,850. When these fees go unpaid, it isn’t just a nuisance; it’s a direct hit to your firm’s Days Sales Outstanding (DSO) and overall valuation. Statistics show that once an accounting invoice passes the 90-day mark, the probability of collecting it in full drops to roughly 69%.

However, the accounting industry faces a unique challenge. Unlike a traditional retailer, you cannot simply “repossess” a tax filing. You are bound by Treasury Circular 230, which mandates the prompt return of client records necessary for tax compliance, even if fees are unpaid. Furthermore, pursuing aggressive fee suits is cited by the AICPA as one of the leading triggers for defensive malpractice claims.

At NexaCollect, we provide a diplomatic, 50-state licensed solution that recovers your fees without triggering the “negligence” counterclaims that haunt firm partners.

Need a Collection Agency? Contact us


The 4-Step “Waterfall” for Financial Professionals

Accounting firms require a structured, low-friction recovery system. Our phased approach is designed to function as an extension of your billing department, not a “heavy-handed” debt collector.

blank

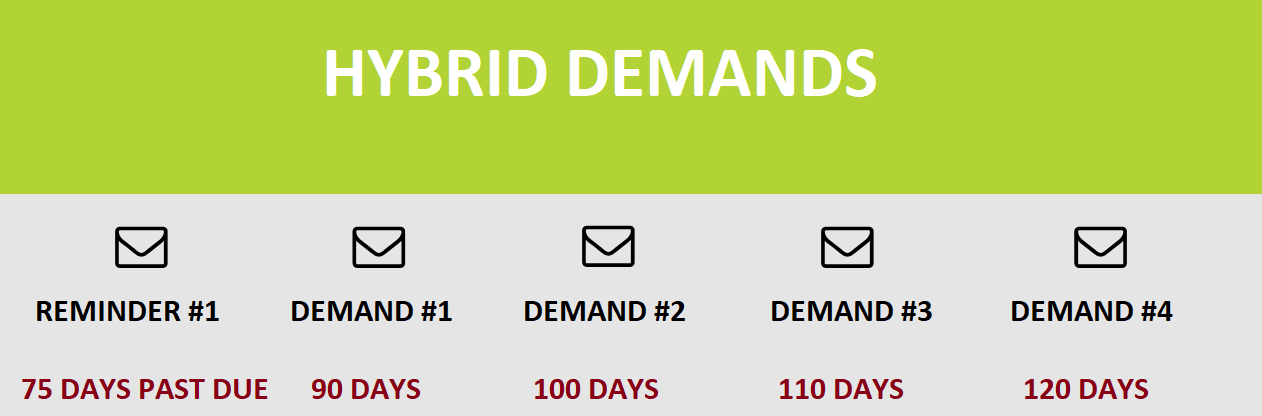
Step 1: The “Audit” Reminder (Fixed Fee ~$15)

This is our most popular tier for CPAs. We send professional reminders in your firm’s name.

  • The Strategy: It frames the unpaid balance as a simple administrative oversight or a “missing document” issue.

  • The Benefit: You keep 100% of the recovery. Because the contact comes from you, it preserves the “Trusted Advisor” relationship while securing the cash.

Step 2: Formal Agency Transfer (Fixed Fee ~$15)

If the client ignores the internal nudge, the account transitions to NexaCollect’s name. This signals to the client that the professional engagement has reached a formal billing impasse. This step often resolves “procrastinator” debtors who wait until the last possible second to prioritize their CPA’s bill.

Step 3: Contingency Recovery (40%)

For the most stubborn “slow-pays,” our specialists engage in intensive, call-based negotiations. We operate on a “No Recovery, No Fee” basis.

  • Tactical Advantage: We handle the “service dissatisfaction” excuses that accountants hate to deal with, allowing you to focus on high-value advisory work.

Step 4: Legal Review & Escalation

For high-balance corporate fees, we provide attorney-vetted escalation. This ensures that if litigation is necessary, it is handled with the highest level of legal scrutiny to prevent any blowback to your firm’s license or reputation.


Compliance as a Shield: Circular 230 & TCPA

Accountants are naturally risk-averse, and for good reason. A single TCPA (Telephone Consumer Protection Act) or FDCPA violation can cost thousands in fines.

NexaCollect is built on a foundation of Bulletproof Compliance:

  • Circular 230 Literacy: We understand that while you can withhold “work products” (like a finished return you haven’t filed), you cannot withhold original client records. Our process ensures you stay on the right side of the Office of Professional Responsibility (OPR).

  • Reputation Preservation: Our 4.85-star Google rating is the highest in the industry. We are often complimented by the debtors we collect from for our professionalism. This ensures your firm isn’t the subject of a 1-star review “revenge post.”

  • Malpractice Avoidance: By using a diplomatic third party, you avoid the “angry confrontation” that often leads a client to invent a “negligence” claim to get out of paying their bill.


The “Service Resolution” Template

Accountants often struggle to find the right words. Use this template during Step 1 to move the needle without losing the client.

Subject: Action Required: Finalizing Your [Year] Tax Engagement

Dear [Client Name],

In reviewing our files for the [Year] tax season, we noted that Invoice #[Number] for $[Amount] remains outstanding.

We take great pride in our accuracy and the tax savings we’ve identified for you. If there is a question regarding your filing or if you require additional documentation to finalize your payment, please let us know immediately.

Please remit payment via [Link] or contact our office by [Date] to ensure your account remains in good standing for the upcoming quarterly planning sessions.

Sincerely, [Partner Name / Billing Dept]


Why Wait for May 1st?

Accounting debt is highly seasonal. Invoices that go unpaid during the “crunch” months of February through April are significantly harder to collect once the client’s tax refund has been spent.

Don’t let your hard work become a tax write-off. With NexaCollect, you get the security of a 50-state license, the trust of a 4.85-star rating, and a process designed to protect your firm’s most valuable asset: its reputation.

Contact NexaCollect Today for a Confidential AR Review

Filed Under: Debt Recovery

Media & Publishing Debt Recovery: Recovering Revenue, Protecting the Brand

blank

In the media industry, your brand is built on trust and community presence. Whether you run a local weekly or a national digital magazine, the last thing you want is a reputation for being heavy-handed with your readers or your local advertisers.

However, the reality of publishing in 2026 is that margins are thinner than ever. Between “zombie” digital subscriptions with expired credit cards and local advertisers who ghost your sales reps after a three-month campaign, revenue leakage is likely costing your publication 15% to 20% of its annual profit.

Nexa provides a “Brand-Safe” recovery system specifically tuned for the publishing cycle. We protect your masthead’s reputation while ensuring you actually get paid for the space you’ve already filled.

Recover Your Media Revenue Today


The Publishing Profit Gap (By the Numbers)

  • $2,800: The average uncollected balance for a small-to-mid-sized local advertiser.

  • 42%: The increase in recovery rates when an account is moved to a third-party partner before it hits 90 days.

  • $15: The cost of our Step 1 Fixed-Fee service—less than the cost of your billing clerk spending half a day on the phone.

  • 10-12%: The amount of subscription revenue lost annually due to “passive churn” (unresolved billing issues).


The Nexa 4-Step Recovery Ladder

blank

We handle two very different types of debt with two very different strategies:

Track A: High-Volume Subscriptions (Fixed Fee)

Chasing a $60 or $120 annual subscription internally is a losing game—the labor costs more than the debt.

  • Step 1: We send professional, white-labeled “Account Reconciliation” notices.

  • The Result: The reader pays you directly. The relationship stays intact, and you keep 100% of the money.

Track B: Advertising & Commercial Accounts (Contingency)

When a local business owes $5,000 for a print/digital spread and stops answering emails, it’s no longer a “billing error”—it’s a bad debt risk.

  • Steps 2–4: Our specialized B2B mediators step in. We use professional skip-tracing and direct negotiation to secure the funds.

  • The Result: You only pay us if we collect (No Recovery, No Fee). We focus on “Resolution Mediation” to keep the door open for future ad buys.


Industry Laws & Compliance: Protecting Your Publication

Publishers face unique legal hurdles that generic agencies often overlook:

  • FTC “Negative Option” Rule: The FTC is highly focused on how subscriptions are renewed and canceled. We ensure our recovery language matches the latest transparency requirements to protect you from “hidden fee” lawsuits.

  • FDCPA & TCPA Compliance: We assume the regulatory risk. Our systems are hard-coded to follow “Time of Day” and “Frequency of Contact” rules, ensuring your publication is never associated with harassment.

  • Digital Data Security: Our platform is secure and fully audited, ensuring that your subscriber lists remain confidential and protected.


Recent Recovery Results

  • Regional Newspaper Group: A 4-paper group had $110,000 in “small balance” subscription debt. Nexa recovered $58,000 in 60 days using our $15 Fixed-Fee service.

  • Specialty Trade Magazine: An advertiser owed $12,500 for a year-long digital sponsorship. Our contingency team negotiated a full settlement in 22 days after the advertiser had ignored the sales rep for six months.


Frequently Asked Questions (FAQ)

1. Will you drive away our advertisers?

No. Most ad debt is caused by a “dispute” (a missing PO, a typo in the ad, or a missed deadline). Our mediators are trained to find the “point of friction” and solve it so the client feels heard and the check gets cut.

2. Can you handle “transient” subscribers?

Yes. For print publications, people move and forget to update their billing. Our skip-tracing technology finds their new address and ensures the notice gets into their hands.

3. Why use an agency for a $45 subscription?

Because $45 multiplied by 1,000 “zombie” subscribers is $45,000. Our Fixed-Fee system is designed to make recovering these small amounts profitable for you.

Serving Publishers Nationwide

Need a Collection Agency for subscription bills? Contact Us


Filed Under: Debt Recovery

  • « Go to Previous Page
  • Page 1
  • Interim pages omitted …
  • Page 44
  • Page 45
  • Page 46
  • Page 47
  • Page 48
  • Interim pages omitted …
  • Page 55
  • Go to Next Page »

Primary Sidebar


accounts receivable

Need a Collection Agency?
Kindly fill this form.
We’ll get in touch with you

    Please prove you are human by selecting the tree.

    Compliance & Security

    • SOC 2 Type II Certified: Third-party audited data security and strict privacy controls.

    • HIPAA Compliant: Secure, legal processing of medical and municipal EMS accounts.

    • PCI-DSS Level 1: Highest tier of data encryption for secure payment processing.

    • FDCPA & FCRA Aligned: Full legal adherence to federal consumer protection laws.

    Recent Posts

    • Why Dental Patients Dispute Bills: The Nexa Collections Dental Account Dispute Index
    • 2027 Commercial Collections Benchmark: U.S. Late Payments, AR Risk and B2B Collection Trends
    • Bulk Account Placement: What a Collection Agency Actually Needs From You
    • Nationwide Debt Collection Agency Serving U.S. Cities
    • Chula Vista Collection Agency for Medical, B2B, Schools & Business Debt
    • Corpus Christi Collection Agency: Itemized Bill Rules for Practices
    • Riverside Collection Agency | For Logistics, Medical, Schools & Business Recovery
    • Collection Agency for Large Balances: High-Value B2B Debt Recovery

    Featured Posts

    • Self Service Portal for Debt Collection: Easy, Compliant & Secure
    • Psychiatry Medical Billing & AR Issues: Debt Collections
    • Considerations Before Buying a 3D Printer

    Copyright © 2026 NEXACOLLECT.COM | This content is provided for general informational purposes only and should not be considered legal advice. Collection laws and requirements may vary by state, account type, documentation, debtor status, and specific facts. Please consult qualified legal counsel for guidance regarding your particular situation. Nexa and its authorized collection partners service accounts in accordance with applicable federal and state collection requirements. Visit our home page to know more about us.

    X
    Need a Collection Agency?
    Contact Us