• Skip to main content
  • Skip to primary sidebar

Nexa Collections

  • Home
  • Serving
    • Medical
    • Dental
    • Small Business
    • Large Business
    • Commercial Collections
    • Government
    • Utilities
    • Fitness Clubs
    • Schools
    • Senior Care Facility
  • Contact Us
    • About us
    • Cost

Debt Recovery

Insurance Recoupment Defense: Stop The “Clawback”

Standard debt collectors dial phones. We fight audits.

If you have received a demand letter from an insurance payer asking for money money back—or worse, if they are already withholding funds from your current checks to pay off an “old debt”—you are facing Recoupment.

This is not a collections issue. It is a legal and compliance dispute. Treating it like standard bad debt is why most practices lose these battles.

At NexaCollect, we don’t just ask them to stop; we audit the auditors.

Need a Collection Agency? Contact us


Why Switch? The “Takeback” Letter is Not a Bill.

Most collection agencies operate on a simple model: they harass patients to pay $50 copays. But when UHC, Aetna, or a Medicare MAC demands $50,000 back because of an “alleged coding error” from two years ago, a standard agency is useless. They cannot argue ERISA law, and they cannot audit a CPT code.

The Landscape Has Changed in 2026:
Insurance payers are now using AI-driven “Predictive Overpayment” models. In 2024 alone, initial claim denial rates spiked to 11.8%, and automated recoupment demands increased by over 20% in the commercial sector. They are using algorithms to find patterns and demand bulk refunds, hoping you are too busy to fight back.

The Nexa Difference:

  • Force Multiplier for Billing Staff: Your billing team is built to submit new claims, not fight forensic legal battles on old ones. We handle the heavy lifting so they don’t burn out.

  • Reputation-Safe Dispute Resolution: We argue on regulatory and contractual grounds—never aggression. This preserves your contract status with the payer while protecting your bank account.

  • The “Investigation” Shield: Under the revised CMS 60-Day Rule (effective Jan 1, 2025), proper investigation protocols can pause the refund clock for up to 180 days. We know how to trigger these pauses to buy you time and leverage.

The “Takeback” Danger Zone: 3 Risks of Waiting

  1. Statute of Limitations: Many states have strict “clawback” windows (often 12–24 months). If you don’t initiate the recoupment professionally and quickly, the money is legally gone.

  2. Provider Resistance: Providers often view recoupment as a “hidden tax.” Our mediators bridge the gap, explaining the data clearly to reduce friction.

  3. Offsetting Complications: While future payment offsetting is common, it can lead to reconciliation nightmares. Direct recovery through Nexa keeps your books clean.


Q&A: The Executive Guide to Recoupment Defense

Q: Why does a collection agency letter work when my rebills failed?

A: It triggers a “Statutory Countdown.” When you simply resubmit a claim, it goes back into the automated claims queue—often to be denied by the same algorithm. A Legal Demand Letter is different. It is classified as a “Pertinent Communication” under state Unfair Claims Settlement Practices Acts.

  • The Shift: It forces the carrier to route your claim out of the automated queue and into the “Dispute Resolution” or “Legal” department.

  • The Timer: In most states, once this letter is received, the carrier is legally required to respond within a stipulated timeframe (typically 15 to 30 days). If they ignore it, they risk “Bad Faith” litigation penalties.

  • The Result: Your case is finally prioritized and reviewed by a human specialist, not a bot.

Q: Is it legal for them to just take money out of my current checks?

A: Often, yes—but they must follow strict procedural rules. This is called “offsetting.” However, under ERISA laws, if the original plan was self-funded (which many employer plans are), the insurer may not have the right to offset funds from a different patient’s claim to pay for the first one. We audit every offset to ensure they aren’t robbing Peter to pay Paul illegally.

Q: How far back can they go?

A: It depends on your state and your contract.

  • Commercial Payers: Usually limited by state “Lookback Periods.” For example, Florida generally limits recoupment to 30 months, while Texas prompt pay laws have a 180-day limit for certain clawbacks. If your contract is silent, general state statutes of limitation (often 4-6 years) might apply.

  • Medicare (RAC Audits): Generally 3 years, but can go back further if “fraud” is alleged (which they use loosely).

  • The Defense: We frequently get demands thrown out simply because they violate the “Lookback Period” by even one day.

Q: Can we fight a “Medical Necessity” recoupment?

A: Absolutely. These are the most common and the most beatable. Payers often use automated “black box” algorithms to deny care as “not medically necessary” without a human doctor ever reviewing the chart. We force them to produce the clinical credentials of the reviewer. If an algorithm made the decision, we challenge the validity of the audit itself.


Recent Results:

We do not use hypothetical examples. These are real scenarios handled by specialized defense teams.

Scenario A: The “AI Algorithm” Mass Sweep

  • The Threat: A mid-sized Surgical Center received a bulk demand for $420,000. A major commercial payer’s AI algorithm flagged every instance of a specific CPT modifier used over the last 18 months, claiming it was “unbundled” incorrectly.

  • The Defense: We utilized the No Surprises Act dispute framework and clinical coding guidelines to prove the AI failed to account for the specific anesthesia time units associated with the procedure.

  • The Result: The demand was reduced to $12,500 (a 97% reduction) after we proved the vast majority of claims were compliant.

Scenario B: The “Silent” Offset

  • The Threat: An Out-of-Network provider noticed their revenue dropped by 15% overnight. The payer had silently begun withholding $15,000 per month from current checks to satisfy a disputed overpayment from 2021 regarding “Usual and Customary” rates.

  • The Defense: We issued a legal demand citing a breach of ERISA procedural requirements, specifically the failure to provide a “Full and Fair Review” before commencing recoupment (citing Montanile v. Board of Trustees precedents).

  • The Result: The offsetting stopped immediately. The $85,000 already withheld was returned to the provider, and the original dispute was moved to mediation.


Ready to Stop the Bleeding?

A recoupment demand is a time-sensitive legal threat. Every day you wait is a day the “Lookback Period” might expire or the “60-Day Rule” might lock you in.

Do not let them audit you into the red.
Get a Free Audit Defense Consultation

Filed Under: Debt Recovery

Speed Up Medical Insurance Claims with a Collection Agency

Medical Insurance collection agency

Most medical and dental professionals struggle to recover money from insurance companies in a timely manner. While some insurers consistently process claims within 30 days, others can take up to 120 days to pay. This unpredictability in the reimbursement process leads to cash flow challenges and other operational issues.
 
Medical insurance claims submitted by doctors, dentists, and hospitals with proper documentation must be paid within established time limits, or the insurers may face penalties and other sanctions. These requirements, known as “prompt-pay statutes,” are primarily enforced within the healthcare industry.
 

Helping Medical Professionals to Recover Unpaid Insurance Claims !

Serving Nationwide: Contact Us

When a third-party collection agency contacts an insurance company, the insurer is reminded of its obligation to pay claims promptly. Failing to resolve medical insurance claims on time can result in a violation of state law.

Once an insurance company receives a collection notice from a professional collection agency, they are under pressure to act fast.

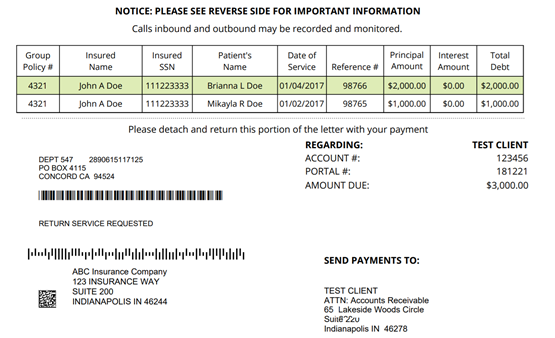
Collection Notice ( Sample)

We have made repeated attempts to resolve this matter with no response from your office. This leaves us no alternative but to pursue this debt through more intense collection methods.

We hope that further efforts will be avoided on this account by sending payment in full to the address in the bottom portion of the letter.

As of the date of this letter, the balance due and owing is stated above. Because of interest that may vary from day to day, the amount due on the day you pay may be greater. Hence, if you pay the amount shown above, an adjustment may be necessary after we receive your check, in which event we will inform you before depositing the check for collection. For further information, please write the undersigned.

THIS COMMUNICATION IS FROM A DEBT COLLECTOR. THIS IS AN ATTEMPT TO COLLECT A DEBT AND ANY INFORMATION OBTAINED WILL BE USED FOR THAT PURPOSE.

These laws and payout periods vary from state to state in terms of operation, complexity, and severity. However, they all share the common goal of compelling insurers to promptly and fully pay all legitimate claims. Debt issues in the BSFI market are anticipated to grow significantly over the next 10 years.

Non-timely reimbursements is a leading cause of stress and burnout among medical professionals, then why not outsource unpaid medical insurance claims to a professional agency and get paid faster.

Examples of “prompt-pay statutes” law in some states.

Texas Insurance prompt payment statute:
The Texas Prompt Pay Act (“TPPA”) is codified in the Texas Insurance Code as Subchapter J of Chapter 843 (governing health maintenance organizations (HMOs)) and Subchapters C and C-1 of Chapter 1301 (governing preferred provider organizations (PPOs)).

California prompt payment statute:
California Health & Safety Code 1371. A health care service plan, including a specialized health care service plan, shall reimburse claims or a portion of a claim, whether in-state or out-of-state, as soon as practicable but no later than 30 working days after receipt of the claim by the health care service plan, or if the health care service plan is a health maintenance organization, 45 working days after receipt of the claim by the health care service plan.

Florida Insurance prompt payment statute:
Florida statute 627.6131, otherwise known as the “Prompt Pay Statute,” requires insurance companies to make decisions and pay out on claims quickly. The timeframe created by this legislation depends on how the claim was received, either electronically or physically.

New York State prompt payment law health insurance:
Law § 3224-a (McKinney 2000) requires payment of health claims by health insurance companies within 45 days of receipt of such claim; N.Y. Ins. Law § 5106 (McKinney 2000) requires motor vehicle no-fault providers to pay health claims arising from vehicular accidents to be paid within 30 days of receipt of such claim.

North Carolina: 30 days for payment or denial.

North Dakota, Georgia: 15 days

Ohio, Oregon, Delaware, Idaho, Kansas, Kentucky, Maine, Maryland, Massachusetts, Minnesota, Montana, Nevada, Wisconsin: 30 days

Oklahoma, Colorado, Pennsylvania, Missouri, Nebraska, Vermont, Virginia, Wyoming: 45 days

Alabama, Arkansas: 30-45 days

Arizona: 30 days after the claim is approved

Louisiana: 25 to 45 days

Mississippi: 25-35 days

( days refer to “working” days)

References:
www.tlrfoundation.com/sites/default/files/pdf/TLR_Prompt_Pay_PDF_V01.pdf
danahyandmurray.com/florida-prompt-payment-statute/
www.dfs.ny.gov/insurance/ogco2002/rg207242.htm

Filed Under: Debt Recovery

Online Reviews of Collection Agencies: They Don’t Matter

Online Review of Collection Agency

Are you trying to shortlist a Collection Agency by looking at their Google reviews or Yelp rating? According to inc.com – 88% of customers read an online review, influencing their buying decision. But, a single bad review can undo the value of 40 good customer experiences.

Those online review methodologies work well for restaurants and doctors, but the same criteria does not work well for the Debt Collections industry.

  • Most negative reviews are left by debtors who hate debt collectors anyway. That is because the Collection Agency recovered some money from them, which they were not planning to pay.
  • Some disgruntled employees who could not adapt to the pressure of being a Debt Collector leave a negative review about the job or the workplace. Maybe they could not make enough money as a debt collector and left a negative online Google review.
  • Many clients submit highly disputed debts to a collection agency and expect that those debts will somehow be magically recovered. If a debt is highly disputed or too old, even a collection agency may not be able to recover those. No collection agency will recover 100% of the debts assigned.
  • Satisfied people are often thankless. Not many clients who get good returns take the pain to leave a review for a Collections Agency on Google or Yelp. No one wants to publically announce online that they use the services of a collection agency. Some clients leave positive reviews because their Collection Agency Rep requested them to do so. Dissatisfied customers are more vocal, and so are the debtors.
  • Competitors may intentionally try to plant fake negative reviews to sink the business of their rivals.
  • Many businesses, including collection agencies, often hire “Reputation management firms” and professional marketing firms to ensure good online ratings, which has almost nothing to do with the real recovery rates of that collection agency. They attempt to game the online review system.

Need a Good Collection Agency?

Serving Doctors & Businesses Nationwide ➧ Contact us 


Higher Recovery Rates: Top-Notch Customer Service

Still looking for a 5-star rating on BBB and Google. Let us help you!

We are not saying there is no way to gauge a collection agency, but due to the nature of the job they perform, they simply cannot be evaluated by general public reviews.

Many people from the accounts receivable industry crack jokes by saying that it is quite possible that a Collection Agency with horrible ratings on Google could be the best one (since it recovered so much money, it landed up annoying too many people). We are not recommending you use this judgment criterion either.

Many agencies that are rated higher on Google do so by requesting their employees, friends and only satisfied customers to leave 5-star reviews and thereby artificially raise their ratings. Unlike sites like Amazon,  where we have a “Verified Buyer” tag next to a review, generic online reviews like those on Google/Yelp have no way to know whether the reviewer has even used a service or if the reviewer is a debtor, employee or someone else. Therefore these reviews are subjected to manipulation.

Some agencies simply push their ratings higher to take advantage of Search Engine Optimization. However, some agencies are genuinely rated higher, but we are talking very broadly. Better Business Bureau (BBB) ratings are a lot more reliable.

The right way to gauge a collection agency is by their recovery rates, product offerings, adherence to the debt collection laws, and the experience of their management and staff.

The medical industry uses Collection Agencies a lot. May you have a friend who is a doctor, he can recommend a good collection agency.

References:
www.inc.com/andrew-thomas/the-hidden-ratio-that-could-make-or-break-your-company.html

Filed Under: Debt Recovery

Debt Collection for Car Rental Industry

rental car

Minimizing the accounts receivable has become extremely important for the Car Rental industry. Chargebacks, vehicle damages, fuel charges, tire damage, one-way drop-off, and parking tickets are common issues that rental car companies face.

Online ride-sharing services already present enormous growth challenges for the industry. Therefore losing money to unpaid bills further impacts the cash flow.

Need a collection agency with experience in your industry? Contact us

Car rental companies like Enterprise Rent-A-Car, Hertz, and Avis have been fiercely competing with Uber, Lyft, and Turo, which are genuine businesses but probably have an unfair business advantage due to low operating costs and taxes.

Leaving money uncollected from past-due accounts is like leaving money on the table. An effective accounts receivable strategy is vital to survive, and Debt Collection Agencies play a critical role in recovering outstanding debt for car rental companies.

Statistics indicate that accounts over 60-90 days past due should be promptly transferred to a collection agency for a better recovery. Collection Agencies can recover money most effectively with their vast pool of resources and partnerships. They will efficiently collect money from lease breaks, repossessions, damages, and credit card chargebacks.

Collection Letters Service
  • Upfront cost for 5 Collection Letters is about $15 per account.
  • Debtors pay directly to you, no other fees. Low-cost option.
  • Good for accounts less than 120 days past due.
Collection Calls Service
  • Contingency fee only. No upfront or other fees.
  • Agency gets paid a portion of the money they recover.  No recovery-No fees.
  • Best for accounts over 120 days. A debt collector calls debtor many times.
  • If everything fails, a possible Legal Suit is recommended by the attorney.

Equipped with advanced Skip Tracing services and a collection staff that recovers money all year long, they utilize services like Collection letters, Collection calls and Legal suits. They follow a multi-step approach to recover money from people who have defaulted on their payments.

Collection agencies collect money empathetically and diplomatically by following federal and state collection laws. This will give you much-needed money for growth and transforming your fleet to EV’s as the times change.

Filed Under: Debt Recovery

Laundry and Dry Cleaning Service: Debt Collections Agency

Laundry Collection Agency
Overdue accounts receivable for the Laundry and Dry Cleaning Service industries is an ongoing problem. Hiring an in-house person to deal with accounts receivable, even with prior experience in the collections industry is still not all that effective because collections are still being done under the name of your laundry company instead of a professional collection agency.

Fact: Customers are incredibly concerned when recovery is initiated under the name of a debt collection agency. They were not so serious when recovery was being made using your own Company’s own name.

Contact us for your professional debt collection needs.

Additionally, collection agencies enroll for expensive “Scrub services” for “Change of Address“, “Bankruptcy” and “Litigious Customer” checks. Enrolling in these services for a standard entity like a Laundry Company is not practical because these Scrubs are too expensive per account. Collection agencies buy these subscription services, and these scrubs are cheaper for them.

Creating internal aging reports, monitoring accounts for delinquency, and follow-up with overdue invoices works well for the first 90 days. Beyond that, there is no point in pursuing recovery under your own name. If a client has not paid in 90 days, what is the possibility that they will pay any time soon ( or ever)? Extremely low!

Collection agencies are licensed and bonded, so if a counter-lawsuit arises, their insurance policy almost always covers lawyer fees and damages filed by the client. They keep their staff up to date with constant changes in collection laws, something which an in-house employee of a laundry company cannot keep up with because he works pretty much in solitude.

Delinquent customers are fearful of an account getting transferred to a Collections Agency. They are concerned that their account could be reported to a credit reporting agency and possibly be transferred for a legal suit. For accounts with higher balances, a collection agency will likely forward the account to one of their national network of attorneys to file a lawsuit.

You cannot win a football match by hiring a single player; you need a full team with varying roles to achieve the desired results. A Collections Agency works as a team, with each debt collection department playing a different role.

In short, an in-house staff has little chance to compete with the recovery rate that a collections agency can achieve. If you include the salary of your in-house employee, printing costs, benefits, mailing, follow-up and all the hidden costs, a collection agency turns out to be a lot cheaper and more effective choice.

Collection Demands Service
  • The upfront cost for 5 Collection Letters is about $15 per account.
  • Debtors pay directly to you, no other fees. Low cost option.
  • Good for accounts less than 120 days past due.
Collection Calls Service
  • Contingency fee only. No upfront or other fees.
  • Agency gets paid a portion of the money they recover.  No recovery-No fees.
  • Best for accounts over 120 days. A debt collector calls debtor many times.
  • If everything fails, a possible Legal Suit is recommended by the attorney.

Collections agencies have been recovering money for their clients for decades. Almost no one can beat their efficiency and cost of collecting the debt.

Check here: Cost of hiring a collections agency

Filed Under: Debt Recovery

Pharmacy Debt Collection: Recovering Co-Pays, LTC Contracts & DME Balances

Pharmacy Bill Recovery: Protecting Your 3% Margin

In independent pharmacy, the math has changed. With PBM reimbursements often dipping below acquisition cost (NADAC) and DIR fee disputes still squeezing cash flow on older claims, the days of “letting it slide” are over.

Pharmacy collections service for recovering patient co-pays, specialty medication balances, long-term care invoices and DME accounts with secure, patient-friendly and reputation-safe support.

Quick Answer: Recovering Past-Due Pharmacy Balances
Pharmacy debt collection recovers unpaid co-pays, LTC facility house accounts, specialty medication deductibles, and unreturned DME rentals through HIPAA-compliant outreach that never discloses specific medication names, NDC codes, or treatment categories, only the balance owed. Nexa includes free skip tracing and PMS-compatible batch uploads, starting at a $15 fixed-fee letter for accounts under 120 days old.


The hard truth:
 If your net profit margin is hovering around 1.8% to 3%, you must fill approximately $2,700 worth of prescriptions just to offset a single $50 uncollected co-pay.

You cannot afford to be the community bank. Whether it’s uncollected patient deductibles for high-cost specialty meds or a nursing home that’s 90 days late on their “house account,” you need a recovery partner who understands the unique financial ecosystem of a pharmacy.


Nexa provides a reputation-safe approach, equipped with all 50-state collections license, offering free credit reporting, free litigious debtor check, free bankruptcy scrub, and zero onboarding fees. Secure – SOC 2 Type II & HIPAA compliant. Over 2,000 online reviews rate us 4.85 out of 5. 

Need a Collection Agency? Contact us


The “PBM Audit” Shield: Why You Must Collect

Most owners view collections as “revenue recovery.” You must view it as audit defense.

PBM contracts and federal Anti-Kickback statutes generally prohibit the “routine waiver of co-pays.” If an auditor sees a pattern of uncollected balances on your books, they can accuse you of offering illegal inducements to patients.

  • The Threat: The PBM can claw back the entire reimbursement (the full cost of the drug), not just the uncollected $20 co-pay. On a specialty Rheumatoid Arthritis medication, a waived co-pay could trigger a $3,000 recoupment.
  • The Solution: Assigning these debts to a collection agency creates an irrefutable paper trail. It proves to the auditor that you made a “commercially reasonable effort” to collect, protecting your full reimbursement.

HIPAA: What Can and Can’t Be Said During Collections

Collecting a pharmacy balance means discussing money, not medicine. Every outreach stays limited to the account balance and payment options, never the specific drug name, NDC code, diagnosis, or treatment category behind the charge. A debtor’s family member or an answering machine hearing “you owe $340” is a normal collections call; the same message referencing a specific medication is a HIPAA exposure the practice, not just the collector, is accountable for.

The 4 Hidden Revenue Leaks in Pharmacy

Your “accounts receivable” likely hides four specific types of debt. A general medical collection agency treats them all the same, but a pharmacy specialist knows the difference.

1. The LTC & Facility Trap (B2B Debt)

If you service long-term care (LTC) facilities, group homes, or hospices, you likely bill them monthly on “net-30” terms.

  • The Risk: When facility ownership changes or an administrator quits, your $15,000 monthly invoice often falls into a black hole.
  • The Fix: This is commercial debt, not consumer debt. It requires an agency that knows how to pierce the corporate veil and demand payment from the facility’s CFO, not the patient.

2. Specialty Medication Deductibles

You dispensed a $4,000 Hepatitis C drug. The insurance covered $3,000. The patient owes a $1,000 deductible.

  • The Scenario: You set up a compassionate payment plan. The patient pays the first installment and then stops answering calls.
  • The Reality: You’ve already paid the wholesaler. That $1,000 loss wipes out the profit of your next 500 routine scripts. These high-balance accounts must be prioritized immediately.

3. DME (Durable Medical Equipment) Rentals

If you rent hospital beds, nebulizers, or crutches, you face a unique problem: the equipment is gone, and the payments stopped.

  • The Fix: An agency can recover the fair market value of the unreturned equipment, ensuring you aren’t left with a depreciating asset and zero revenue.

4. PBM Clawback Residuals (The “DIR Hangover”)

A federal rule effective January 1, 2024 moved most Medicare Part D DIR fees to be assessed at the point of sale instead of retroactively, which has genuinely reduced new clawback exposure. But it hasn’t eliminated the problem: many pharmacies are still working through unresolved pre-2024 clawback disputes, and the reform only covers Medicare Part D specifically, not every commercial PBM contract. Broader federal PBM reform (capping fees, banning spread pricing) has stalled in Congress, even as individual states move faster on their own. The practical result: reconciling what a PBM actually paid against what your system expected is still an active, ongoing part of pharmacy AR, not a solved problem from 2024.

Compounding Pharmacies: The “Refill” Trap

Compounding pharmacies face a specific hazard: the custom med. Unlike a generic pill you can return to the shelf, a compounded cream is a sunk cost ($80–$150 in labor and materials) the moment it’s made.

  • The Danger: Patients often order a refill before paying for the previous month. If you ship batch #2 without collecting on batch #1, you’re compounding your losses.
  • The Strategy: Implement a strict “Collections Hold” policy. Let the agency chase the old debt while you require “Credit Card on File” for all future fills.

In-House Staff vs. Aggressive Collections vs. Nexa’s $15 Fixed-Fee

Factor In-House Staff Aggressive/Generic Agency Nexa Step 1 ($15 Fixed-Fee)
Cost Staff time, no direct cash outlay Often 30%+ contingency regardless of account age $15 flat per account, you keep 100% recovered
HIPAA exposure High, techs aren’t trained on minimum-necessary disclosure Varies, generic scripts risk mentioning treatment details Built around balance-only communication, no drug names or NDC codes
Patient retention Depends entirely on staff tone under pressure Low, aggressive scripts drive patients to competitors Higher, diplomatic first-contact letter preserves the relationship
Recovery speed Slow, competes with clinical workload Fast but relationship-costly Days to a few weeks for fresh accounts

Pharmacies Want a Collection Agency That:

  • Understands HIPAA is non-negotiable. A data breach is more expensive than the debt. Your agency must be SOC 2 Type II certified and understand exactly what “minimum necessary information” means when talking to a debtor.
  • Can handle “soft” vs. “hard” collections. Soft: for the elderly patient who simply forgot her $30 bill, diplomatic reminders preserving the relationship. Hard: for the nursing home administrator ignoring a $12,000 invoice, legal demands, credit reporting, corporate pressure.
  • Offers fixed-fee pre-collection. You shouldn’t pay 30% to collect a fresh debt. Look for agencies offering flat-fee letters (e.g., $15/account) for debts under 120 days old.
  • Knows the “Part D” donut hole. Agents should be trained to explain why a patient owes money (e.g., “Mrs. Jones, you hit your coverage gap, which is why this bill is higher than usual”). Educated patients are more likely to pay.
  • Integrates with modern PMS. Whether you use PioneerRx, McKesson, or Micro Merchant, the agency should accept digital file uploads to save your techs from manual data entry.

Stop Turning Techs Into Debt Collectors

Your technicians are trained to navigate insurance adjudications and fill prescriptions accurately. They are not trained to have conflict-heavy financial arguments.

Forcing your front-line staff to chase bad debt leads to two things: staff burnout (a morale killer, asking care-focused staff to play “bad cop”) and the “nice guy” write-off (techs naturally letting it slide to avoid awkwardness at the counter).

Outsourcing creates a healthy separation. Your staff remains the “healthcare heroes,” while the agency handles the uncomfortable financial enforcement.


Transparent, Pharmacy-Friendly Pricing

Accounting receivables don’t all look the same, so the fee model shouldn’t either.

Fixed-Fee Recovery ($15/account)

Best suited to early-stage receivables — invoices where the debtor relationship is still fresh and a firm, professional nudge is likely enough. Debtors pay 100% directly to you. There are no commissions taken from what’s recovered. Can be claimed as a business expense so this service can essentially be 100% free for you.

Contingency Service (20%–40%)

Built for older, disputed, or “ghosted” accounts that need sustained investigation, skip tracing, and negotiation. No Recovery, No Fee — Nexa is paid only when the account is successfully collected.

Nexa Collections fixed-fee and contingency pricing structure for restoration company debt recovery

Frequently Asked Questions

Can a collection agency collect unpaid pharmacy bills without violating HIPAA?

Yes, when outreach is limited to what’s actually necessary to collect: the balance owed, the account, and payment options, never the specific medication, NDC code, or diagnosis behind the charge. A debtor’s household hearing “you owe $340” doesn’t reveal anything protected; the same call referencing a specific drug name would.

How do independent pharmacies collect past-due copays without losing local customers?

Through diplomatic, low-cost first contact rather than aggressive scripts. A soft, third-party reminder letter, typically far cheaper than a full contingency collection effort, resolves many balances from patients who simply forgot or fell behind, without the confrontation that turns a loyal customer into a lost one.

What is the best way to recover unpaid custom compounding medication costs?

Prevention plus fast escalation. Since a compounded medication is a sunk material and labor cost the moment it’s made, requiring a card on file for future fills stops new losses immediately, while the existing unpaid balance should move to collections quickly rather than waiting, since a refill shipped on top of an unpaid prior batch only compounds the loss.

How does Nexa handle LTC and nursing home pharmacy receivables?

As commercial debt, not consumer debt. A facility’s monthly house account is pursued at the corporate level, directed at the administrator or CFO who actually controls payment, rather than treated like an individual patient balance, which matters when facility ownership changes or an administrator leaves and the invoice risks falling into a black hole.

Can we deny refills if a patient is in collections?

This depends on state law and the type of medication. Generally, emergency or life-sustaining medication cannot be denied, but purely elective medications can be refused, or the patient can be converted to cash-on-delivery status until the balance is resolved.

What about unpaid “house accounts”?

The average independent pharmacy writes off roughly 1.5% of total revenue annually due to unpaid house accounts. If a long-standing customer hasn’t paid in 90 days, assigning the account to an agency lets the pharmacy stay the trusted local business while the collection conversation happens somewhere else.

Is it worth collecting a $40 co-pay?

On its own, maybe not. In aggregate, yes. A hundred unpaid $40 co-pays is $4,000 in pure profit lost, and most agencies allow small balances to be batched together for efficient, low-cost processing rather than chased one at a time. Secondly, you do not want to build your pharmacy’s reputation to be one which does nothing is co-pay is not paid, resulting in further more defaults.


Stop filling prescriptions for free.

Serving Pharmacies Nationwide

Need a Collection Agency? Contact Us


Filed Under: Debt Recovery

  • « Go to Previous Page
  • Page 1
  • Interim pages omitted …
  • Page 43
  • Page 44
  • Page 45
  • Page 46
  • Page 47
  • Interim pages omitted …
  • Page 55
  • Go to Next Page »

Primary Sidebar


accounts receivable

Need a Collection Agency?
Kindly fill this form.
We’ll get in touch with you

    Please prove you are human by selecting the key.

    Compliance & Security

    • SOC 2 Type II Certified: Third-party audited data security and strict privacy controls.

    • HIPAA Compliant: Secure, legal processing of medical and municipal EMS accounts.

    • PCI-DSS Level 1: Highest tier of data encryption for secure payment processing.

    • FDCPA & FCRA Aligned: Full legal adherence to federal consumer protection laws.

    Recent Posts

    • Why Dental Patients Dispute Bills: The Nexa Collections Dental Account Dispute Index
    • 2027 Commercial Collections Benchmark: U.S. Late Payments, AR Risk and B2B Collection Trends
    • Bulk Account Placement: What a Collection Agency Actually Needs From You
    • Nationwide Debt Collection Agency Serving U.S. Cities
    • Chula Vista Collection Agency for Medical, B2B, Schools & Business Debt
    • Corpus Christi Collection Agency: Itemized Bill Rules for Practices
    • Riverside Collection Agency | For Logistics, Medical, Schools & Business Recovery
    • Collection Agency for Large Balances: High-Value B2B Debt Recovery

    Featured Posts

    • Modern AR Collection Process: Recover More, Spend Less, Protect Relationships
    • Texas Restoration Collections | $15 Fixed-Fee Debt Recovery
    • Lower Medical AR Days: 5 Proven Tactics

    Copyright © 2026 NEXACOLLECT.COM | This content is provided for general informational purposes only and should not be considered legal advice. Collection laws and requirements may vary by state, account type, documentation, debtor status, and specific facts. Please consult qualified legal counsel for guidance regarding your particular situation. Nexa and its authorized collection partners service accounts in accordance with applicable federal and state collection requirements. Visit our home page to know more about us.

    X
    Need a Collection Agency?
    Contact Us