• Skip to main content
  • Skip to primary sidebar

Nexa Collections

  • Home
  • Serving
    • Medical
    • Dental
    • Small Business
    • Large Business
    • Commercial Collections
    • Government
    • Utilities
    • Fitness Clubs
    • Schools
    • Senior Care Facility
  • Contact Us
    • About us
    • Cost

Search Results for: the bureaus

Suing for Unpaid Bills: The Legal Process, Costs & When to Walk Away

legal collections

The “Nuclear Option”: Why You Should Hesitate Before You Sue

Filing a lawsuit feels like taking control. You are angry, you are right, and you want justice. But in the world of debt collection, justice is expensive.

Before you pay a retainer to an attorney, you must understand that the court system is not designed to be your accounts receivable department. It is slow, unpredictable, and often favors the debtor.

The 3 Biggest Disadvantages of Legal Action

If you ask a lawyer, they might say “you have a strong case.” If you ask a CFO, they will ask you to look at these three risks:

1. The “Sunk Cost” Trap (Good Money After Bad)

Litigation is “front-loaded.” You must pay filing fees ($200-$500), process server fees ($100+), and attorney retainers ($2,000+) upfront.

  • The Risk: If you sue for $10,000 and spend $4,000 to win, you have only recovered $6,000—and that is only if the debtor actually pays.

  • The Reality: If the debtor files for Bankruptcy Chapter 7 the day before the trial, your lawsuit dies instantly, and your $4,000 in legal fees is gone forever.

2. The Public Record (Reputation Damage)

Lawsuits are public records.

  • The Risk: Future clients or partners can see that you are litigious. If you are a contractor or a service provider, getting a reputation for “suing your customers” can hurt your sales pipeline more than the bad debt itself.

  • The Time Sink: You will lose dozens of hours gathering evidence, sitting in depositions, and waiting in hallways at the courthouse. Your time is worth money—factor that into the cost.

3. The Judgment is Just Paper

Winning a lawsuit does not mean a check magically appears in your mailbox.

  • The Risk: A court Judgment gives you the right to collect, but it doesn’t force the money out of their pocket. You still have to pay more money to the Sheriff to garnish wages or levy bank accounts. If the debtor works “under the table” or changes banks, your judgment is a worthless piece of paper suitable for framing.


WARNING: The “Counter-Suit” Boomerang

This is the danger most business owners ignore until it is too late. When you sue a debtor, you are handing them a weapon.

To defend themselves, a debtor’s attorney will look for any reason to file a Counter-Claim against you. Suddenly, you aren’t just fighting to get paid $5,000; you are fighting to defend yourself against a $50,000 lawsuit.

Common Counter-Suit Triggers:

  • Breach of Contract: “I didn’t pay because the work was defective/late/incomplete.” Now the court has to inspect your work, dragging the case on for months.

  • FDCPA Violations: If you (or your staff) called them too many times, called their workplace, or threatened them, they can sue you under the Fair Debt Collection Practices Act.

  • Defamation: Did you tell a vendor or neighbor that this person “doesn’t pay their bills”? That could be grounds for a defamation counter-suit.

Insider Advice: Never rush into a lawsuit out of anger. If your internal documentation isn’t perfect, a counter-suit could bankrupt you. Consider hiring a collection agency before you jump to an attorney to sue your debtor. 


The 9 Steps of a Debt Lawsuit (The Realistic Version)

If you have weighed the risks and determined the debtor has assets (Real Estate, W-2 Income) worth seizing, here is the roadmap:

1. The Final Demand (The “Shot Across the Bow”)

Send a formal “Notice of Intent to Sue” via Certified Mail.

  • Reality: This letter often works better than the lawsuit itself. It shows you are serious.

2. Filing the Complaint

You file the paperwork with the court clerk.

  • Reality: If you are an LLC or Corporation, most states require you to hire a lawyer. You typically cannot represent yourself in higher courts.

3. Service of Process

A Sheriff or Process Server hands the papers to the debtor.

  • Reality: Professional debtors know how to “dodge service.” If you can’t find them to hand them the paper, the lawsuit stops dead.

4. The Answer Period

The debtor has 20-30 days to respond.

  • Reality: Most ignore it. If they do, you win by default. If they file an “Answer” denying the debt, get ready to write another check to your lawyer.

5. Discovery & Depositions

Both sides trade emails, texts, and documents.

  • Reality: This is the expensive part. Lawyers charge hourly to read your emails.

6. Mediation (Mandatory in many states)

The judge may force you to sit in a room and try to settle before letting you go to trial.

  • Reality: You often end up settling for 60% of the debt just to make the legal fees stop.

7. Trial

You present your case to a Judge (or Jury).

  • Reality: Bench trials (judge only) are faster. Jury trials are unpredictable and expensive.

8. Judgment

You win! The court says they owe you money plus interest.

9. Enforcement (The Hard Part)

Now the hunt begins.

  • Bank Levy: You freeze their checking account. (Only works if you know where they bank).

  • Wage Garnishment: You take 25% of their net pay. (Only works if they have a steady W-2 job).

  • Property Lien: You put a cloud on their home title. (You only get paid when they sell the house).

The Bottom Line: Calculation

Do not sue if:

  • The debt is under $2,500 (Small claims fees will eat the profit).

  • The debtor is unemployed, self-employed, or “Judgment Proof.”

  • Your own paperwork (contracts/change orders) is messy or unsigned.

Consider a Collection Agency if:

  • You want to avoid legal fees (Agencies work on contingency—no win, no fee).

  • You want to preserve your reputation.

  • You want to report the debt to Credit Bureaus rather than a court docket.


Litigation is a tool, not a guarantee.
Filed Under: Debt Recovery

New Jersey Medical Collection Agency for Healthcare Providers: Local Experience Matters!

New Jersey medical debt collection has changed—and healthcare providers need a recovery strategy that has changed with it. From physician and dental practices in Newark and Jersey City to hospitals and urgent care centers in Hackensack and Edison, ophthalmologists, surgery centers, senior living communities, and healthcare groups across the state, unpaid patient balances can quickly become a serious revenue-cycle problem.

Under New Jersey’s Louisa Carman Medical Debt Relief Act, providers now face stricter rules on when medical debt can enter collections, how much interest may be charged, wage garnishment, payment plans, and credit reporting. That makes outdated, pressure-driven collection tactics both ineffective and risky.

Nexa helps New Jersey medical providers recover past-due patient accounts through compliant, patient-sensitive outreach, structured payment solutions, persistent follow-up, and appropriate escalation—protecting your cash flow without sacrificing the patient relationships and reputation you worked years to build.

Medical debt collection services for New Jersey doctors, dentists, hospitals, urgent care and senior living provider

Nexa provides 100% reputation-safe, equipped with all 50-state collections license, offering free credit reporting, free litigious debtor check, free bankruptcy scrub, and zero onboarding fees. Secure – SOC 2 Type II & HIPAA compliant. Over 2,000 online reviews rate us 4.85 out of 5. Easy to use and backed by a responsive client support team.

Need a Medical Collection Agency in New Jersey? Contact us


Deep Analysis: The 3 New Barriers to Revenue in NJ

The Louisa Carman Act introduced three specific “revenue blockers” that most national agencies are not prepared for.

1. The “600% FPL” Garnishment Ban

  • The Law: Effective July 2025, New Jersey prohibits wage garnishment for medical debt if the patient’s income is below 600% of the Federal Poverty Level.

  • The Risk: This is not just for “low income” patients. For a family of four, 600% of the FPL is nearly $187,000. This effectively removes the threat of garnishment for the vast majority of your middle-class patients.

  • Our Solution: We shift focus away from wage garnishment (which is now often impossible) and towards asset execution (bank levies) and voluntary settlement negotiation based on psychological urgency rather than legal threats.

2. The “Credit Reporting” Blackout

  • The Law: Medical debt can no longer be reported to credit bureaus if it is under $500 (regardless of date) or for any services provided after July 22, 2024. Any reported debt that violates this becomes legally void.

  • The Risk: The traditional agency tactic of “wrecking their credit score” to force payment is now illegal in New Jersey.

  • Our Solution: We rely on direct contact frequencies and attorney-backed demand letters. Since we can’t hurt their credit score, we use the “nuisance factor” of consistent, compliant professional follow-up to drive payment.

3. The Mandatory 120-Day “Freeze”

  • The Law: You cannot engage in any collection actions until 120 days after the first bill is sent. During this time, you must offer a reasonable payment plan (max 3% interest).

  • The Risk: Sending an account to collections at “Day 90” (the industry standard) is now a violation of state law.

  • Our Solution: We have adjusted our intake API to automatically reject NJ files younger than 120 days, protecting you from accidental “early placement” liability.


Our 4-Step “Garden State” Recovery System

We have calibrated our model to clear the hurdles of N.J.S.A. 2A:44 (Liens) and the new Medical Debt Relief Act.

Phase 1: The “Charity Care” Scrub (Pre-Collection)

  • The Strategy: New Jersey regulations (N.J.A.C. 10:52-11.5) strictly mandate that hospitals screen patients for the Charity Care Program before billing.

  • The Action: We audit your files to ensure this screening is documented. If a patient claims hardship, we pause collection and help facilitate the Charity Care application. This often results in you getting paid by the State rather than chasing a broke patient.

  • Cost: Included in service.

Phase 2: The “Safe Harbor” Outreach (Steps 1 & 2)

  • The Strategy: Once the 120-day freeze lifts, we send the legally required “30-Day Pre-Collection Notice” which includes the mandatory statement that the debt will not be reported to credit bureaus.

  • The Psychology: We use this notice to offer a “Final Amnesty” payment plan that complies with the state’s new 3% interest cap.

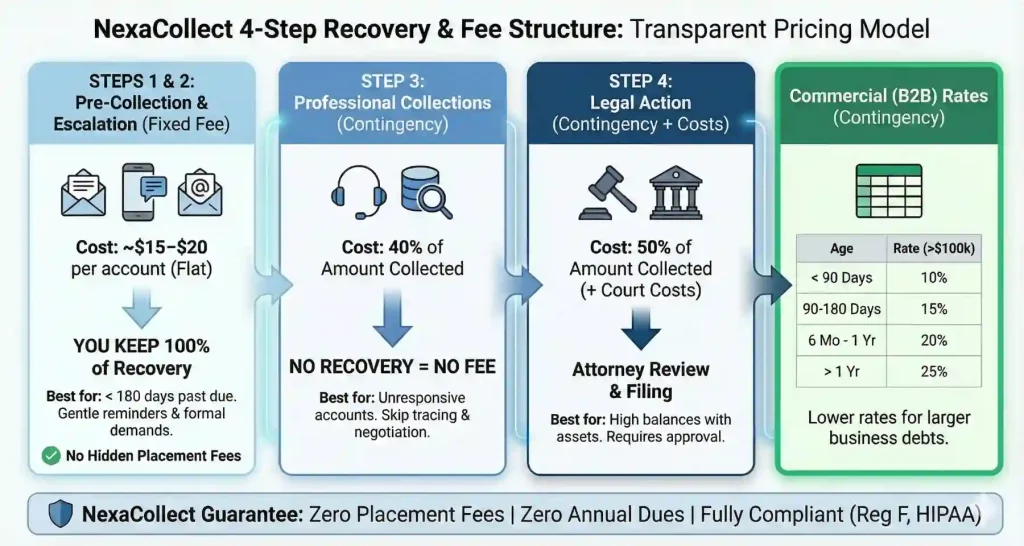
  • The Cost: Flat fee (approx. $15/account). You keep 100% of recoveries.

Phase 3: The “Lien & Levy” Escalation (Step 3)

  • The Strategy: Since wage garnishment is restricted for many, we look for other liquidity.

  • For Accident Cases: We utilize N.J.S.A. 2A:44-41 to file hospital liens with the county clerk. These liens attach specifically to personal injury settlements, ensuring you get paid before the patient receives their check.

  • The Cost: 40% contingency.

Phase 4: Strategic Litigation (Step 4)

  • The Strategy: For high-income debtors (above the 600% threshold) or those with significant assets, we file suit in the Superior Court of New Jersey. We target bank accounts and property liens, which are often more effective than wage garnishment in NJ anyway.

  • The Cost: 50% contingency.


Regional Strategy: One State, Two Markets

We adjust our approach based on the patient’s economic zone.

Region Economic Profile Collection Strategy
North Jersey (Bergen/Hudson) High Income / Commuter High usage of payment plans. We structure plans to fit the “3% interest” rule, making them attractive alternatives to ignoring the bill.
South Jersey (Camden/Gloucester) Philly Metro / Mixed Heavy focus on Insurance Cleanup. Many patients here cross state lines for care; we are experts at resolving “Out of Network” disputes with PA-based insurers (like Independence Blue Cross).
The Shore (Monmouth/Ocean) Seasonal / Retail We time our calls to align with seasonal cash flow for business owners and service workers.

FAQ: The Executive Summary

What is the Louisa Carman Medical Debt Relief Act in New Jersey?

The Louisa Carman Medical Debt Relief Act is a New Jersey law that significantly changed how healthcare providers and collection agencies can pursue unpaid medical bills. Among other protections, it limits medical-debt credit reporting, requires reasonable payment-plan options, restricts when collection actions may begin, caps interest, and limits wage garnishment for certain patients. As of July 22, 2025, the major collection protections of New Jersey’s Louisa Carman Medical Debt Relief Act are fully in effect.

How long must a New Jersey healthcare provider wait before taking collection action on an unpaid medical bill?

In New Jersey, a medical creditor or medical debt collector generally cannot take collection action until 120 days after the first medical bill was sent and the patient has been offered a reasonable payment plan. At least 30 days before collection action begins, the patient must also receive an additional bill and notice describing the intended collection action and deadline.

Can unpaid medical debt be reported to credit bureaus in New Jersey?

New Jersey prohibits medical creditors and medical debt collectors from reporting medical debt for healthcare services performed on or after July 22, 2024. The law also prohibits consumer reports from containing paid medical debt or medical debt below $500, regardless of when that debt was incurred.

What type of payment plan must be offered for medical debt in New Jersey?

A reasonable payment plan should be based on what the patient can afford and, when income is known, generally cannot require monthly payments exceeding 3% of the patient’s monthly income. The law provides for repayment periods that may range from six months to five years, requires at least a 60-day grace period for late payments, and caps interest at 3% per year.

Can wages be garnished for unpaid medical bills in New Jersey?

New Jersey restricts wage garnishment for medical debt. A medical creditor or debt collector cannot garnish the wages of a patient whose annual income is below 600% of the federal poverty level. Because poverty guidelines can change, eligibility should be evaluated using the applicable current threshold.

Can a medical bill be sent to collections while an insurance appeal is pending in New Jersey?

If a healthcare provider knows that an internal review, external review, or other health-insurance appeal related to the bill is pending, New Jersey law generally prohibits the provider from referring that unpaid charge to a medical debt collector. Collection communications and lawsuits regarding those charges are also restricted while the qualifying appeal is pending.


Need a NJ Collection Agency? Contact us

Filed Under: Debt Recovery

Pennsylvania Medical Debt Collection Agency

A Pennsylvania medical debt collection agency helps hospitals, clinics, dental practices and other healthcare providers recover unpaid patient balances while navigating the state’s stricter collection environment. Because Pennsylvania generally restricts wage garnishment for medical debt, effective recovery relies more heavily on patient-friendly negotiation, compliant payment arrangements and appropriate legal remedies when necessary. Choose an agency experienced with HIPAA, FDCPA and Pennsylvania collection requirements, secure data handling, reputation protection and healthcare-specific accounts.

Pennsylvania medical debt collection agency

How to Recover Revenue When Two of the Usual Tactics Don’t Exist

Most collection strategies rest on two levers: garnish the wages, or wreck the credit score. In Pennsylvania, for medical debt, neither one is actually available right now, and an agency that doesn’t know that isn’t just ineffective, it’s selling your practice a strategy built on threats it legally can’t make good on.

Lever one, wage garnishment, doesn’t exist here. 
Pennsylvania law (42 Pa.C.S.A. § 8127) broadly prohibits wage garnishment for consumer debt, including medical bills. This isn’t a loophole or a technicality, it’s one of the strongest debtor protections in the country, and Pennsylvania is one of only a handful of states with it. The only exceptions are child support, taxes, federal student loans, and unpaid rent, none of which apply to a medical balance. A debtor who’s done any research knows this, so a collector who threatens garnishment anyway doesn’t just fail, they lose credibility for everything they say after.

Lever two, credit reporting as a nationwide federal ban, also isn’t currently active. 
A federal rule that would have broadly restricted medical debt on credit reports was finalized in early 2025, then vacated by a federal court in July 2025. There’s no nationwide ban in effect right now. Some protection still exists at the margins, the major credit bureaus voluntarily exclude paid debt and balances under $500 as their own policy, but “the CFPB banned this” is not an accurate description of where things currently stand, and leaning on it as leverage is a second empty threat stacked on the first.

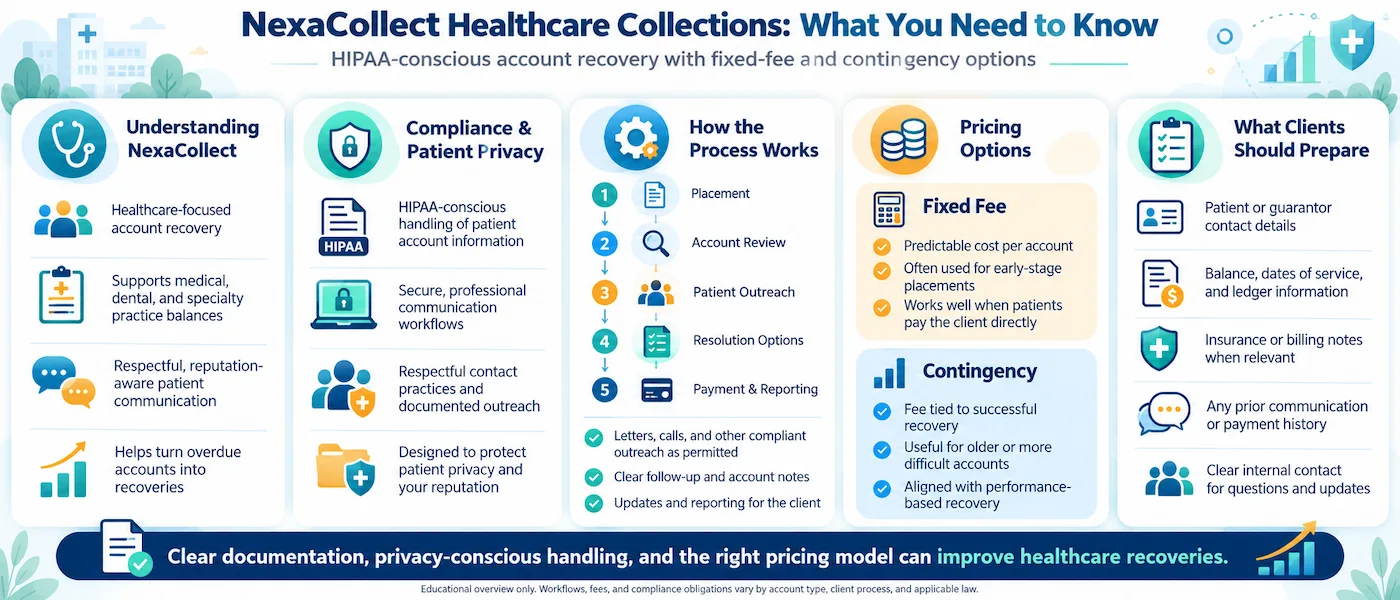
HIPAA-conscious patient account recovery, the collection process, fixed-fee and contingency pricing options, and information healthcare providers should prepare.

What’s Actually In the Toolbox

Once you take those two off the table, three things remain, and they’re genuinely effective when used correctly.

Voluntary payment, collected early. 
With no legal hammer waiting in the background, getting a patient to pay before an account ages is disproportionately valuable here. A courteous, clearly-worded notice, sent while the balance is still fresh, resolves a meaningful share of accounts that would otherwise sit and age with no real remedy behind them.

Negotiated resolution. 
Since threats don’t move the needle, the actual skill is finding real, voluntary liquidity, a tax refund, savings, family assistance, and structuring a settlement around it. This is a different skill than sending a form letter, and it’s the difference between an agency that talks tough and one that actually collects.

Bank levies and property liens, after judgment. 
Wages can’t be touched, but a bank account can be levied once a court judgment is obtained, though Pennsylvania exempts $300 from that levy, so the remaining balance is what’s actually reachable. A judgment also becomes a lien against real property in the county where it was entered, which can complicate a future sale or refinance until it’s satisfied. Neither requires garnishment to work.

Does Pennsylvania really ban wage garnishment for all medical debt, with no exceptions?

The ban is broad but not absolute. Wages are protected from garnishment for medical debt and other ordinary consumer debt with only four narrow exceptions: child support, taxes, federal student loans, and unpaid rent. A medical balance itself doesn’t fall into any of those categories, so for practical purposes, garnishment isn’t a real option for recovering it.

If the CFPB’s credit-reporting ban isn’t currently active, can medical debt still show up on a patient’s credit report?

In limited cases, yes. The federal rule that would have banned it broadly was vacated in court, so there’s no nationwide ban right now. The credit bureaus’ own separate voluntary policy still excludes paid balances and amounts under $500, but a larger, unpaid, older balance can still legally appear, this is a narrower, less certain form of leverage than “the government banned this,” which is the inaccurate version some agencies still use.


Stop relying on empty threats. Start using a strategy that works in Pennsylvania.

Click here to Request a Quote & Audit


The Rest of the Landscape

Pennsylvania’s Act 6 sets a default legal interest rate of 6% on debts where no specific contract states a different rate, worth checking before an agency assumes a higher rate applies. The statute of limitations for most medical debt is 4 years from the date of the last payment or missed payment; past that window, the debt is time-barred, and pursuing it anyway risks a countersuit rather than a recovery.

Patients across Pennsylvania’s major health systems, Allegheny Health Network in Pittsburgh, Penn Medicine in Philadelphia, and others, are frequently confused by complex EOBs. Outreach that helps a patient actually understand what insurance didn’t cover tends to resolve balances faster than outreach that skips straight to a demand.

Pricing

See the full pricing breakdown for how these compare across account types.

Flat-Fee Notices (Steps 1-2, ~$15/account). 
Courteous, clearly-worded notices sent as an extension of your billing office. Best for accounts where voluntary payment is the realistic outcome. You keep 100% of what’s recovered.

Negotiated Resolution (Step 3, 40% contingency). 
For non-responsive accounts, structured settlement negotiation aimed at real liquidity rather than empty threats.

Judgment & Asset Execution (Step 4, 50% contingency). 
Bank levies and property liens, pursued only where the balance and circumstances justify legal escalation, with client approval.

Nexa provides reputation-safe, equipped with all 50-state collections license, offering free credit reporting, free litigious debtor check, free bankruptcy scrub, and zero onboarding fees. Secure – SOC 2 Type II & HIPAA compliant. Over 2,000 online reviews rate us 4.85 out of 5. 

Need a Medical Collection Agency? Contact us


Filed Under: Debt Recovery

Illinois Healthcare Debt Collection: Recover Patient Balances & Protect Practice Reputation

Ask five people what changed in Illinois medical debt law this year and you’ll get five confident, slightly different answers. That’s because “Illinois medical debt has changed” is really shorthand for three separate legal threads that get blended together constantly, one of them solid and operational, one genuinely still unsettled, and one so new most agencies haven’t caught up to it yet. Getting the three straight matters more than reciting the headline, whether you’re running medical debt collection in-house or through a partner.

Nexa provides reputation-safe, equipped with all 50-state collections license, offering free credit reporting, free litigious debtor check, free bankruptcy scrub, and zero onboarding fees. Secure – SOC 2 Type II & HIPAA compliant. Over 2,000 online reviews rate us 4.85 out of 5. 

Need an Illinois Medical Collection Agency? Contact us


Thread One: The Screening Requirement (Solid, Operational, 2024)

The Protect Illinoisans from Unfair Medical Debt Act requires hospitals to screen uninsured patients for public health insurance programs and financial assistance before pursuing collection, and to provide language interpreters where requested. This is the least ambiguous of the three threads: it’s in effect, it’s operational, and it changes what “clean” documentation looks like before an account should ever reach collections. A collection partner that isn’t verifying this screening happened before making the first call is creating exposure that has nothing to do with how politely they ask for payment.

Thread Two: The Credit-Reporting Ban (Real, But Less Settled Than It Sounds)

Illinois Public Act 103-0648, a separate law from the screening act above, took effect January 1, 2025, and makes it unlawful for a consumer reporting agency to include medical debt on an Illinois resident’s credit report. This sits on top of the state’s broader collection agency laws, not in place of them. This is frequently described as a done deal. It isn’t quite.

In October 2025, the CFPB itself stated that federal law (the Fair Credit Reporting Act) may not permit states to ban medical debt from credit reports at all, echoing a federal court’s July 2025 ruling that struck down the CFPB’s own broader medical-debt reporting rule and specifically flagged that FCRA may preempt state-level bans like Illinois’s. None of this has overturned the Illinois law yet, that would require the federal government to actually sue and win. But it means the honest description is “currently in effect, with real legal uncertainty about how long that lasts,” not “permanently settled.” A collection strategy built entirely on “credit reporting no longer works here” is betting on a specific legal outcome that hasn’t actually happened yet.

Separate from Illinois’s own law, the major credit bureaus also maintain their own nationwide voluntary policy: no reporting of medical balances under $500, and paid balances get removed. That bureau policy isn’t affected by any of the state-level legal uncertainty above, it applies regardless of what happens to Illinois’s specific statute.

Thread Three: Coerced Debt Protections (New, and Not Yet on Most Agencies’ Radar)

Effective January 1, 2026, Illinois’s amended Collection Agency Act (via HB 3352 and SB 2457) creates protections for “coerced debt,” debt a patient didn’t willingly incur due to fraud, duress, domestic violence, or identity theft. Once a patient files a statement of coerced debt, collection activity must pause, and ignoring that filing carries real penalties. This is recent enough that a lot of collection workflows, including plenty of agencies still marketing themselves on 2024’s changes, haven’t built it into their process yet.


What This Actually Means for Pricing and Process

None of the three threads change the basic math of getting paid, they change what has to be true before pursuing payment. This is exactly the kind of nuance that makes outsourcing accounts receivable to a specialist worthwhile rather than handling it entirely in-house. Nexa’s process is built around confirming screening documentation exists (Thread One), treating credit reporting as a secondary tool rather than primary leverage given the genuine uncertainty around it (Thread Two), and checking for a coerced-debt filing before escalating an unresponsive account (Thread Three).

Phase 1 (Fixed Fee, ~$15/account): Diplomatic, clearly-worded notices, no aggressive legal jargon, for patients who simply forgot or misread their EOB. You keep 100% of what’s recovered.

Phase 2 (40% Contingency): For non-responsive accounts, specialists negotiate payment plans that respect Illinois’s disposable-earnings garnishment limits rather than pursuing garnishment against patients who are legally judgment-proof. Every account is also screened against active bankruptcy filings before any escalation.

Phase 3 (50% Contingency, Legal): Escalation through an Illinois attorney network when warranted, respecting the state’s judgment interest rules for smaller balances.


Does the credit-reporting ban mean Illinois medical debt has no real collection leverage left?

Not entirely, and treating it that way misreads where things stand. The ban is currently in effect, so it shouldn’t be relied on as a threat, but it also hasn’t been overturned, so it’s not simply gone either. The practical move is building a strategy that doesn’t depend on credit-reporting leverage at all, communication, documented payment plans, and legitimate legal escalation where warranted, rather than betting on either version of the story being permanently true.

How does the “coerced debt” law actually change a collection workflow?

It adds a checkpoint before escalation: once a patient files a statement of coerced debt, claiming the balance stems from fraud, duress, domestic violence, or identity theft, collection activity has to pause while that claim is reviewed, and continuing to pursue payment after a filing carries real penalty exposure. Building this check into intake now, rather than after a complaint, is the difference between routine compliance and a preventable violation.


Why Illinois Practice Managers Choose Us

HIPAA-conscious patient account recovery, the collection process, fixed-fee and contingency pricing options, and information healthcare providers should prepare.

We navigate the Chicago-vs-downstate divide. Collecting in Naperville looks different from collecting in Carbondale, and outreach adjusts accordingly rather than using one script statewide.

We protect non-profit “community benefit” status. For non-profit hospitals, aggressive collections can threaten tax-exempt standing. Respectful outreach protects both community reputation and the revenue needed to keep operating.

We understand Illinois’s wage protection limits. Illinois protects a larger share of disposable earnings from garnishment than the federal standard, so energy goes toward accounts that can actually yield results rather than judgment-proof pursuits.

Illinois by the Numbers

Roughly 17% of Illinois residents carry some form of medical debt, and that rate climbs past 20% for households earning under $35,000 annually. Cook County has one of the state’s highest concentrations of medical debt, and Black and Hispanic communities are affected at nearly double the rate of white residents. Medical bills remain a leading cause of bankruptcy filings statewide.

Regional Focus

Chicagoland & Cook County: high-volume recovery for urgent care chains and dental networks.
Central Illinois (Peoria/Bloomington): working alongside large regional health systems to recover copays and deductibles.
Rockford & Northern Illinois: supporting private practices navigating a shifting regional economy.

Additional FAQs

What is the statute of limitations for medical debt in Illinois?

Generally 5 years for unwritten contracts, which covers most standard medical bills, and 10 years for written contracts. See how statutes of limitations work for how this plays out once a debt is time-barred. Waiting that long makes collection significantly harder in practice; the strongest recovery window is the first 90 days past due.

Do you handle the mandatory financial-assistance screening for us?

Not as a substitute for your own billing department, but as a final check: accounts that look like they haven’t been properly screened get flagged so the gap can be fixed before it becomes a violation, rather than after.

If you’re still comparing options, see how to select a collection agency before making a final call.

Need a Medical Collection Agency in Illinois? Contact Us

Filed Under: Debt Recovery

New York Medical Debt Collection Agency for Healthcare Providers

New York has rewritten the rules for medical and dental debt faster than almost any other state: a three-year statute of limitations instead of six, a ban on wage garnishment and home liens for hospital and provider judgments, and a law that keeps most medical debt off consumer credit reports entirely. A new NYC rule taking effect September 1, 2026 adds further limits on contact frequency and stronger notice requirements for medical accounts. None of this means medical debt in New York is uncollectible. It means the old playbook, credit-reporting threats and slow-moving lawsuits, no longer works, and providers need a partner built around patient-centered outreach, accurate account aging, and strict compliance instead.


New York Medical Collection agency, Hipaa Compliant

If your current collection partner is still threatening credit reporting, talking about wage garnishments, or dragging out lawsuits, they are working off an outdated playbook, and you are the one carrying the risk.

Why switch? The hidden cost of using the wrong agency

Many New York providers are still partnered with agencies that were a decent fit ten years ago, but not today. Common warning signs: they still talk about using credit reporting as leverage, even though New York now blocks most provider-reported medical debt from credit reports; they push long, drawn-out lawsuits, ignoring that the statute of limitations on medical debt is now only three years, and that hospitals and many providers cannot enforce medical judgments with wage garnishments or home liens; they don’t mention New York City licensing and disclosure rules or the need for a city collector’s license to collect from NYC residents; and their scripts clearly aren’t written for a state where medical debt can no longer be used to damage a patient’s credit score.

If your agency is still operating as if New York were any other state, you may be leaving recoverable dollars on the table, carrying more legal risk than necessary, and spending internal time cleaning up patient complaints, regulator inquiries, and lawyer letters.

We work New York medical and dental accounts directly, under the state’s current rules, rather than passing your file to a third party.

Nexa provides  reputation-safe, 50-state licensed collections, with free credit reporting, free litigation and bankruptcy scrubs, and zero onboarding fees. Secure, SOC 2 Type II and HIPAA compliant. Over 2,000 online reviews rate us 4.85 out of 5.

Need a Collection Agency? Contact us.


What has actually changed? A snapshot of New York medical debt rules

Here are the big shifts every New York provider should know:

Credit reporting of medical debt is heavily restricted. State law prevents most New York hospitals, health care professionals, and ambulance providers from reporting medical debt to credit agencies. Medical and many dental debts from New York providers aren’t supposed to appear on consumer credit reports. Medical charges buried inside a general credit card balance can still show up as part of that card debt, but that’s a card issue, not provider-reported medical debt.

The statute of limitations for medical debt is now three years. Under CPLR § 213-d, the period to sue on most medical debts was shortened from six years to three, measured from the date of treatment rather than the date of last payment, which dramatically narrows the window for lawsuits.

No wage garnishments or home liens for many medical judgments. Hospitals and similar providers can no longer enforce many medical debt judgments through wage garnishment or liens on primary residences.

Stronger hospital financial assistance and consent rules. New York requires standardized financial assistance programs, limits what hospitals can bill certain low- and middle-income patients, and caps interest rates on medical judgments for qualifying patients.

New, broader New York City collection rules take effect September 1, 2026. NYC’s Department of Consumer and Worker Protection finalized amended rules extending coverage to original creditors, not just third-party collectors, capping contact at three communications per account within a seven-day period, requiring opt-in consent for electronic communications, and adding medical-debt-specific disclosure requirements, including notice that medical debt cannot be reported to credit bureaus.

National trend away from medical credit reporting. Major credit bureaus have already stopped reporting paid medical collections and medical debts under a certain threshold, and federal regulators continue pushing lenders to stop using medical bills in credit decisions, further reducing the value of credit-reporting pressure as a collection tactic.

All of this means New York policy deliberately makes old-school, aggressive collection tactics less effective. The only sustainable path now is patient-centric, compliant recovery.

Recent results: how Nexa operates in New York

These are illustrative, fresh examples aligned with how Nexa approaches New York accounts today.

Manhattan multi-specialty practice, Midtown NYC:
A multi-specialty group near Midtown had about $220,000 in patient balances between 90 and 180 days, with a heavy mix of high-deductible plans and self-pay accounts. Their previous agency was still talking about “sending to credit” and filing suits four or five years after service, completely out of sync with New York’s shorter statute and credit-reporting rules. After Nexa took over these accounts, they were re-aged and prioritized to stay within the three-year window, scripts were rewritten to emphasize financial assistance, realistic payment plans, and clear explanations instead of threats, and within nine months, about 41% of the assigned dollars were resolved through payments or structured plans, with noticeably fewer complaints bouncing back to the practice.

Brooklyn dental group, family-oriented practice:
A dental group in Brooklyn had roughly $135,000 in overdue balances, many under $1,200, from families juggling multiple visits and orthodontic treatments. Their previous agency kept hinting at credit damage, which was no longer realistic and only generated angry calls and poor reviews. After Nexa took over, messaging shifted to a collaborative tone with flexible plans and clear breakdowns of insurance versus patient responsibility, professional multi-channel reminders replaced harsh threats, and over seven months, the practice resolved about 48% of the dollars placed, with far fewer reputation issues and less staff time spent apologizing for a vendor’s behavior.

These examples show that even with tight state policies, a meaningful share of A/R is still recoverable, when the agency actually understands New York.

How your data and payments are handled

Every account Nexa handles moves through a secure client portal with encrypted transfer, never email attachments or unsecured file sharing. A signed Business Associate Agreement is in place before any protected health information is shared, consistent with HIPAA requirements. All patient contact follows FDCPA guidelines, New York’s medical debt statutes, and the city’s debt collection rules, including the contact-frequency and notice requirements taking effect this September. Data is used only for the accounts placed with us.

Where Nexa fits in

Our team works New York medical and dental accounts directly, built around the state’s shorter statute of limitations, the ban on wage garnishment and home liens, and the credit-reporting restrictions covered above.

What we do:

  • Prioritize accounts by age so nothing quietly crosses the three-year window unaddressed.
  • Use patient-centered outreach, payment plans, and settlement options instead of credit-reporting threats that New York law no longer allows for most medical debt.
  • Track New York City’s contact-frequency limits and disclosure requirements, including the rules taking effect September 1, 2026.
  • Sign a Business Associate Agreement (BAA) and handle every account through a secure, encrypted portal.

Pricing is straightforward, and you choose the model per account:

Nexa Collections fixed-fee and contingency pricing for New York medical debt recovery

  • Fixed-Fee Recovery ($15/account): ideal for early-stage receivables. Debtors pay 100% directly to you, with no commission taken out.
  • Contingency Service (20%-40%): performance-based recovery for older or harder accounts. No recovery, no fee.

For more on how Nexa’s medical collections process works for patient balances, or for exact rates, see the full breakdown of Nexa’s fixed-fee and contingency pricing. Nexa also supports dental-specific collection strategies, senior care and assisted living facilities, and commercial and business accounts across New York.

Need a Collection Agency? Contact us.


New York FAQ

If medical debt can’t go on credit reports, is there any point sending accounts to collections?

Yes. Credit reporting was always just one tool, and often a blunt one. Recovery in New York now relies more on thoughtful, timely patient outreach, realistic payment plans and settlements, and early placement well before the three-year mark. The right approach can still recover a large share of overdue balances without credit reporting.

Are dental debts treated differently from medical debts in New York?

Most bills from licensed health care professionals, including many dental providers, are treated similarly to medical debt under New York’s newer protections, covered by the same credit-reporting bans and consumer protections as hospital bills.

What does HIPAA compliance really mean in the collection context?

Any agency handling New York medical or dental accounts should sign a Business Associate Agreement, use encrypted systems with restricted PHI access, train staff on minimum-necessary disclosure, and avoid leaving detailed medical information in voicemails or letters.

How do New York’s hospital financial assistance rules affect collections?

Hospitals must maintain clear financial assistance programs, limit what they can bill eligible patients, and cap interest rates in certain circumstances. This means more screening for assistance eligibility, tighter billing rules, and more accounts that should be reduced or converted to charity care rather than pursued aggressively.

Does the shorter three-year statute of limitations really matter?

Yes. Waiting too long to place accounts can quietly erase legal options. A smarter approach defines clear placement triggers, such as 90 or 120 days past due, tracks debt age accurately, and flags time-barred accounts so lawsuits aren’t threatened where they’re no longer legally available.

Are lawsuits still worth considering for medical debt in New York?

Rarely as a default. The window to sue is shorter, wage garnishment and home liens are restricted for hospital and provider debt, and courts are watching medical cases closely. Legal action should be rare, strategic, and well documented rather than routine.

What’s changing under New York City’s new debt collection rules?

Effective September 1, 2026, NYC’s amended rules extend coverage to original creditors, cap contact to three communications per account within a seven-day period, require opt-in consent for electronic communications, and add specific medical-debt notice requirements, including disclosure that medical debt cannot be reported to credit bureaus.

How is patient data secured during the collections process?

Accounts move through a secure, encrypted client portal rather than email attachments. A signed Business Associate Agreement is in place before protected health information is shared, consistent with HIPAA, alongside FDCPA and New York-specific requirements.

Where does Nexa fit into New York medical collections?

We work New York medical and dental accounts directly, built around the state’s shorter statute of limitations, the wage garnishment and lien ban, and current credit-reporting restrictions.

Filed Under: Medical

Florida Medical Collection Agency: Local Experience Matters!

It’s February in a Tampa clinic waiting room, and half the patients checking in have a Michigan or Ohio driver’s license. By April, most of them will be gone until next winter, along with any balance that didn’t get resolved while they were still in town. That’s the real shape of the Florida medical billing problem: not compliance for its own sake, but a hard seasonal deadline most practices don’t realize they’re racing against, layered on top of a state that already has some of the toughest collection rules in the country.

Roughly 1 in 12 Floridians has medical debt in collections, typical balances run around $1,500, and close to 1 in 9 residents is uninsured, so a lot of care goes straight to self-pay. For hospitals, dentists, physicians, urgent care centers, and senior living centers, that’s slow cash flow and rising write-offs, made worse by a compliance layer, the Florida Consumer Collection Practices Act (FCCPA), stricter and more penalty-heavy than the federal HIPAA and FDCPA alone.


Nexa provides reputation-safe, equipped with all 50-state collections license, offering free credit reporting, free litigious debtor check, free bankruptcy scrub, and zero onboarding fees. Secure – SOC 2 Type II & HIPAA compliant. Over 2,000 online reviews rate us 4.85 out of 5.

Serving medical offices, dentists, hospitals, urgent care centers, ophthalmologists and senior living providers.

Need a Florida Medical Collection Agency? Contact us


The Snowbird Calendar

Florida practices are really running three different collection windows at once, and most billing policies don’t distinguish between them.

November through April, patients are here. This is the only real window to collect from a seasonal resident face to face, or at least while their Florida contact information still works. A balance that slips past this window doesn’t disappear, it just gets dramatically harder to collect.

April and May, they leave. Addresses and phone numbers on file go stale fast. A collection partner without licensing in the patient’s home state simply loses the account here; one licensed in all 50 states doesn’t.

Summer onward, the account is either resolved or it’s aging badly. By the time snowbirds return next winter, an unresolved balance from the prior season is often past the point where a friendly reminder does anything.

Does a Florida medical collection agency actually need out-of-state licensing to matter?

Yes, specifically because of this calendar. A seasonal resident who leaves Florida in April is only reachable, legally, by an agency licensed in whatever state they’ve gone home to. Nexa holds active licenses in all 50 states for exactly this reason, so a snowbird account doesn’t quietly die the moment the patient crosses the state line.


What Waiting Actually Costs You

Say a practice is carrying $50,000 in delinquent balances at the start of snowbird season, an entirely realistic number for a mid-sized group. Assume an 80% eventual recovery rate, $40,000 collected either way. The only real question is what it costs to get there.

A traditional agency charging 40% contingency keeps $16,000 of that recovery, leaving the practice $24,000. Nexa’s $15 fixed-fee model, applied across roughly 50 accounts, costs about $750 total, leaving the practice $39,250, over 98% of what’s actually recovered. The math doesn’t change because Nexa is cheaper to run; it changes because the fee is priced per account, not as a percentage of the money you were already owed.

How much does a $15 Fixed Fee Service actually save compared to a traditional 40% agency?

On a typical $50,000 delinquent portfolio recovering $40,000, the difference is roughly $15,000, $39,250 net under the fixed-fee model versus $24,000 net under a traditional 40% contingency structure. The gap widens further on larger portfolios, since the fixed-fee cost scales with account count, not dollar volume.


The Compliance Layer You Can’t Skip

Florida doesn’t just apply the federal FDCPA, it layers the FCCPA (Florida Statute § 559.55 and surrounding sections) on top, which reaches further than federal law: it can apply to anyone collecting a consumer debt in the state, including a practice’s own front-desk staff, not just outside collectors. Aggressive or misleading language from your own billing office can create liability the same way it would for a third-party agency.

Florida also formally treats certain steps, selling the debt, lawsuits, liens, garnishments, credit reporting, or denying medically necessary care over an unpaid bill, as “Extraordinary Collection Actions.” Before any of those, hospitals and ambulatory surgery centers generally have to bill available insurance first, send a clear itemized bill, screen for financial assistance, and give proper written notice with a real chance to resolve the balance.

How does Nexa stay compliant with both the FCCPA and Extraordinary Collection Action rules?

By treating Florida’s layered requirements as the starting framework for every account, not an afterthought applied after a generic script. That means confirming insurance was billed, financial-assistance screening happened where required, and proper notice was given before any account reaches the point where credit reporting or legal escalation is even considered, backed by SOC 2 Type II data security and a signed Business Associate Agreement for every PHI-containing account.

HIPAA-conscious patient account recovery, the collection process, fixed-fee and contingency pricing options, and information healthcare providers should prepare.


Two Practices, One Winter

An urgent care network with 180 past-due accounts totaling $72,000 in co-pays and deductibles used the fixed-fee service and recovered $50,400 in 35 days, spending under $2,700 in fees, more than $17,000 less than a traditional 40% agency would have kept.

A Tampa surgical practice facing $85,000 across 35 accounts, several of them snowbird patients already back in their home states, recovered $59,500 in under 40 days without a single FCCPA dispute or negative review, precisely because the outreach stayed diplomatic and the out-of-state accounts didn’t require a separate agency relationship to pursue.


What This Should Feel Like From the Patient’s Side

Will a soft, diplomatic collection process actually stop patients from leaving negative reviews?

In most cases, yes, because the confrontation that generates a bad review rarely comes from receiving a professional letter, it comes from a heated phone call or a billing office that feels adversarial. A calm, third-party demand tends to resolve the balance quietly, which protects the practice’s Google and Healthgrades presence better than an aggressive internal collections push ever does.

Every account carries PHI even after it’s past due, which means the same HIPAA discipline that governs clinical records applies here too: a signed BAA, encrypted data handling, minimum-necessary access, and a documented trail of every contact.


Key services a medical collection agency must offer in Florida:

  • Compliance with Florida Collection Laws and HIPAA Regulations
  • Amicable Patient Communication and Debt Resolution
  • Tailored Collection Strategies for Medical Practices
  • Skip Tracing to Locate Hard-to-Reach Patients
  • Credit Reporting to Major Bureaus When Appropriate
  • Flexible Payment Plan Options for Patients
  • Secure Online Payment Portal for Easy Bill Settlement
  • Regular Progress Reports and Transparent Account Management
  • Pre-Collection Services to Resolve Debts Early
  • Legal Support for Unresolved Cases, If Needed

These services ensure effective debt recovery while maintaining compliance and patient relations.

Schedule a No-Obligation Consultation Today

Filed Under: Medical

  • « Go to Previous Page
  • Page 1
  • Interim pages omitted …
  • Page 11
  • Page 12
  • Page 13
  • Page 14
  • Page 15
  • Interim pages omitted …
  • Page 27
  • Go to Next Page »

Primary Sidebar


accounts receivable

Need a Collection Agency?
Kindly fill this form.
We’ll get in touch with you

    Please prove you are human by selecting the flag.

    Compliance & Security

    • SOC 2 Type II Certified: Third-party audited data security and strict privacy controls.

    • HIPAA Compliant: Secure, legal processing of medical and municipal EMS accounts.

    • PCI-DSS Level 1: Highest tier of data encryption for secure payment processing.

    • FDCPA & FCRA Aligned: Full legal adherence to federal consumer protection laws.

    Recent Posts

    • Why Dental Patients Dispute Bills: The Nexa Collections Dental Account Dispute Index
    • 2027 Commercial Collections Benchmark: U.S. Late Payments, AR Risk and B2B Collection Trends
    • Bulk Account Placement: What a Collection Agency Actually Needs From You
    • Nationwide Debt Collection Agency Serving U.S. Cities
    • Chula Vista Collection Agency for Medical, B2B, Schools & Business Debt
    • Corpus Christi Collection Agency: Itemized Bill Rules for Practices
    • Riverside Collection Agency | For Logistics, Medical, Schools & Business Recovery
    • Collection Agency for Large Balances: High-Value B2B Debt Recovery

    Featured Posts

    • Jobs that Cannot be Replaced by AI
    • Top Threats for Ophthalmology Practices
    • Impact on Power Grids due to El Nino

    Copyright © 2026 NEXACOLLECT.COM | This content is provided for general informational purposes only and should not be considered legal advice. Collection laws and requirements may vary by state, account type, documentation, debtor status, and specific facts. Please consult qualified legal counsel for guidance regarding your particular situation. Nexa and its authorized collection partners service accounts in accordance with applicable federal and state collection requirements. Visit our home page to know more about us.

    X
    Need a Collection Agency?
    Contact Us