• Skip to main content
  • Skip to primary sidebar

Nexa Collections

  • Home
  • Serving
    • Medical
    • Dental
    • Small Business
    • Large Business
    • Commercial Collections
    • Government
    • Utilities
    • Fitness Clubs
    • Schools
    • Senior Care Facility
  • Contact Us
    • About us
    • Cost

Search Results for: the bureaus

Ambulance Debt Collection | EMS Patient Revenue Recovery

Ambulance providers face a collection problem unlike almost any other healthcare business: the cost of responding keeps rising, insurance often pays only part of the bill, and the patient you are trying to collect from may already be dealing with hospital bills, lost wages, and financial stress from the same emergency. Waiting too long makes the problem worse—older EMS balances become harder to recover, while aggressive collection tactics can quickly damage the reputation of a municipal department or community ambulance service.

Nexa helps EMS providers separate insurance issues, patients who simply need a reminder, hardship cases, and true bad debt, then applies the appropriate HIPAA-compliant, patient-friendly recovery strategy before valuable accounts become uncollectible.
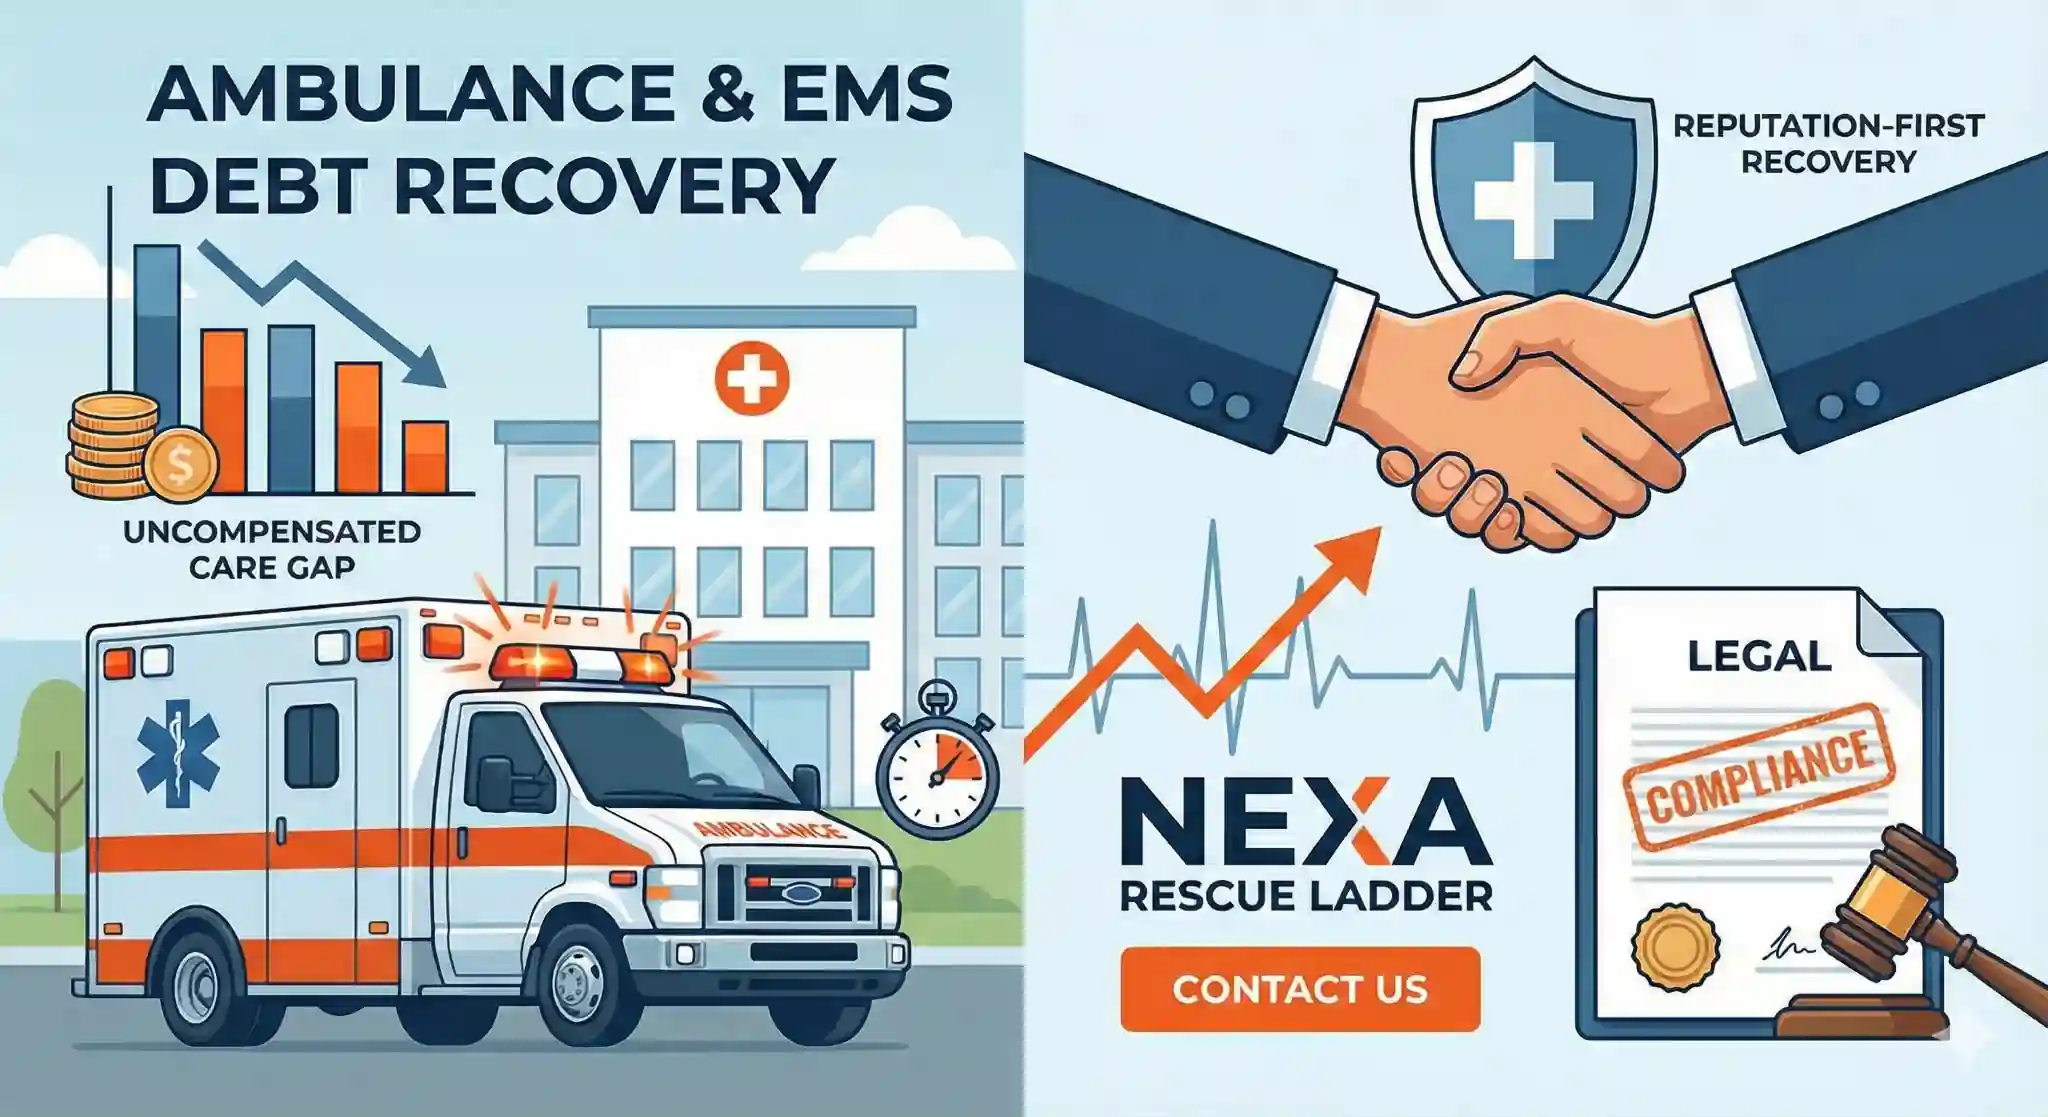
Reputation friendly ambulance and EMS debt recovery
Ambulance & EMS Debt Recovery: Recovering Revenue Without Compromising Community Trust. 

For EMS directors and municipal leaders, every siren represents a life-saving mission, but the financial “after-care” is increasingly a crisis of its own. In 2026, the gap between what it costs to roll a truck and what insurance actually pays has reached a critical breaking point.

Critical Warning: Emergency and ambulance services must act quickly to collect unpaid medical bills from patients as their financial condition can deteriorate very quickly following a medical crisis. When a household is hit with sudden, high-cost medical bills, the first 60 days are the “Golden Window” for recovery before competing debts and financial instability make collection very complicated.

Nexa provides 100% reputation-safe, equipped with all 50-state collections license, offering free credit reporting, free litigious patient check, free bankruptcy scrubs, and zero onboarding fees. Secure – SOC 2 Type II & HIPAA compliant. Over 2,000 online reviews rate us 4.85 out of 5. 

Need a Collection Agency? Restore Your EMS Cash Flow Today


The EMS Financial Reality (Industry Stats)

The “Ambulance Profit Gap” has widened significantly this year. According to the latest 2026 CMS Ground Ambulance Data (GADCS) and industry benchmarks:

  • $1,526 Under-Reimbursement: On average, across all payers, ambulance agencies are under-reimbursed by over $1,500 per transport compared to the actual cost of readiness.

  • $2,672 vs. $1,147: While the mean cost of a governmental ambulance transport has surged to $2,672, the mean reimbursement across all payers remains stuck near $1,147.

  • 37% Emergency Fragility: Recent Federal Reserve data shows that nearly 37% of adults cannot afford a $400 emergency expense. Since the average ambulance bill exceeds $1,200, patients move into financial distress almost immediately.

  • 45% Recovery Drop-off: If a patient balance isn’t addressed within the first 120 days, the likelihood of recovery drops by nearly half as patients deprioritize “one-time” emergency costs behind recurring monthly bills like rent and utilities.


The Nexa 4-Step “Rescue” Ladder

We separate “slow payers” from “bad debt” to maximize your recovery while protecting your department’s community image.

Step 1: The Account Reconciliation (Fixed Fee – $15)

Ideal for accounts 60–90 days past due. Because patients’ financial conditions deteriorate so quickly, this “soft touch” reminder acts as a firm nudge to pay while they still have the liquidity.

  • The Result: The patient pays you directly. You keep 100% of the money.

Steps 2–4: Specialized Medical Mediation (Contingency)

For aged debt or patients who have “ghosted” your internal team. Our mediators use advanced skip-tracing and empathy-based negotiation to find solutions before the patient faces bankruptcy.

  • The Result: You only pay us if we recover your funds. No Recovery = No Fee.


Navigating the Regulatory Landscape

Ambulance collections are a legal minefield. Nexa is hard-coded for 2026 compliance with the newest state laws:

  • Oregon (HB 3243): Effective January 1, 2026, ground ambulances are prohibited from balance billing enrollees for more than the in-network cost-sharing amount.

  • Utah (HB 301): New 2025/2026 laws codify base rates and strictly prohibit ground ambulance providers from charging rates that exceed established caps.

  • Illinois (SB 2405): As of July 2025, non-participating ground ambulance providers must ensure enrollees incur no greater out-of-pocket costs than if the service were in-network.

  • New Hampshire (SB 245): Effective January 1, 2026, this law officially bans “balance billing” for ambulance rides. It also sets mandatory rates for how much companies can charge insurers, significantly changing the negotiation landscape for EMS providers.

  • California (AB 716) – The 12-Month Rule: While active since 2024, California’s law has a strict provision that creditors must know: You are prohibited from reporting adverse information to a credit agency or starting civil action against a patient for a minimum of 12 months after the initial billing. Nexa’s systems are pre-set to respect this “cool-down” period.

  • Maine (LD 1290): Maine now prohibits balance billing for all covered emergency and non-emergency ground ambulance transports. If no local rate is set, the law caps reimbursement at the lesser of 325% of Medicare or the billed charge, requiring precise coding to ensure you don’t over-bill and trigger a violation.

  • Texas (SB 2476): Since early 2024, Texas has banned balance billing for ground ambulance trips. However, in 2026, the focus has shifted to the Independent Dispute Resolution (IDR) portal. If a health plan underpays, we help you navigate the state-mandated mediation and arbitration process to secure the “just and reasonable” rate.

  • Washington State: The Balance Billing Protection Act has been expanded to include ground ambulances. It requires providers to bill health plans directly and strictly prohibits asking patients to “waive” their protections—a common mistake that can lead to heavy state fines.


Recent EMS Recovery Results

  • Private Ambulance Provider (FL): Recovered $280,000 in aged patient balances (120+ days) in just one quarter.

  • Municipal EMS Department (TX): Used our Step 1 Fixed-Fee service to recover $42,000 in “small balance” co-pays that had been sitting idle for six months.

  • NEMT Provider (CA): Reduced overall DSO (Days Sales Outstanding) by 32% within the first 6 months.


Frequently Asked Questions (FAQ)

1. Does the No Surprises Act protect patients from ground ambulance bills?

Not generally. The federal No Surprises Act protects patients from many out-of-network emergency bills and from covered air ambulance surprise bills, but it does not currently extend the same federal protection to ground ambulance services. State laws may provide additional protections, so an EMS provider must check the rules that apply to the patient, health plan, and state before pursuing a balance. CMS continues to treat ground-ambulance billing as a separate policy issue.

2. Can an ambulance provider collect the remaining balance when insurance underpays the claim?

Sometimes, but not automatically. Before billing or collecting from the patient, the EMS provider should determine whether the balance is legitimately the patient’s responsibility or whether a federal or state balance-billing restriction applies. This is especially important because several states now impose protections specifically on ground-ambulance bills, while federal No Surprises Act protections generally apply to air ambulances but not ground ambulances.

For this reason, insurance underpayments and true patient balances should be separated before an account enters collections. Nexa’s current page also emphasizes resolving insurance-denial issues before treating an account as ordinary patient debt.

3. When should an EMS or ambulance service send unpaid patient accounts to collections?

The best time is generally after insurance responsibility has been resolved and normal patient billing efforts have stalled—but before the account becomes heavily aged. Nexa currently positions accounts around 60–90 days past due for its early fixed-fee recovery stage, using softer outreach while the balance is still relatively fresh. Older or unresponsive accounts can then move to more intensive contingency recovery.

Early intervention is especially valuable for emergency-service bills because patients may simultaneously be dealing with hospital charges, lost income, deductibles, and other unexpected expenses.

4. What should an ambulance service do when an insurance claim is denied?

A denied ambulance claim should be reviewed before the patient is treated as responsible for the full balance. The provider should confirm the reason for denial, insurance information, medical-necessity documentation, coding, authorization requirements, and whether an appeal or corrected claim is appropriate.

For Medicare patients, for example, a patient can appeal when Medicare denies an ambulance service they believe should have been covered. Medicare also has specific Advance Beneficiary Notice requirements for certain non-emergency ambulance situations where the provider expects Medicare may not pay.

5. How much can a Medicare patient be charged for a covered ambulance trip?

When Original Medicare covers the ambulance trip, the patient generally pays 20% of the Medicare-approved amount after the Part B deductible. Medicare states that ambulance companies must accept the Medicare-approved amount as payment in full, so in most covered cases they cannot simply bill the patient for the difference between their normal charge and Medicare’s approved amount.

This makes payer verification especially important before placing a Medicare ambulance balance with a collection agency.

6. Can unpaid ambulance bills be reported to the credit bureaus?

Ambulance debt is generally treated as medical debt, so current medical-debt reporting restrictions matter. The CFPB currently states that unpaid medical debt over $500 and more than 365 days delinquent from the date of service could appear on a consumer credit report. State laws may impose additional restrictions, and some states specifically limit credit reporting or legal action involving medical debt.

For EMS providers, this is another reason to prioritize patient-friendly resolution, payment arrangements, hardship screening, and accurate insurance reconciliation before relying on credit reporting as a collection tool.

Need a Collection Agency for unpaid EMS Service bills?

Serving Nationwide: Contact us


Filed Under: Debt Recovery

Texas Medical & Healthcare Debt Collection Agency

To run a successful medical practice or hospital, you need to be able to get paid in full for the services you provide. If you are a doctor or work on the business side in a hospital in the state of Texas, you know the aggravation of medical debt collection. This is a problem the medical community all over the country faces but in Texas, there are state-specific challenges to deal with. Here is the current state of Texas medical debt collection.

Medical Debt in Texas

Debt, in general, is a problem in the United States and Texas is one of the “leaders” in this issue. 71 million Americans have debts that are currently in collection. Texas is second, only to Louisiana, in the percentage of residents who have debts in collection. A hefty 44% of all Texans face collection which equates to approximately 12.7 million Texas residents or, almost 18% of the total number of Americans with pending dent collection. A big portion of this debt is related to medical bills. The overall median medical debt in collections for a person in Texas is $850.

Need a Medical Collection Agency in Texas: Contact us

Texas Medical Collection Laws

Medical debt collectors in Texas are beholden to the Federal laws on the books that relate to debt collection. These can be found by looking at the Federal Trade Commission website. There are some Texas-specific laws that creditors need to know. One is that Texas is a homestead state which means, in most cases, a debtor’s home cannot be taken away to pay a debt. Also, wages can only be garnished in Texas in certain cases and unpaid medical bills are not one of them. These and other Texas laws relating to medical debt collection can be found on the Texas Attorney General’s website.

There is another, lesser-known, law in Texas that applies specifically to the timing of medical billing. A Texas civil statue states that you must “bill a patient or other responsible person for services provided to the patient not later than the first day of the 11th month after the date the services are provided.” This makes the timing of medical billing even more crucial in Texas.

Bond Requirement: In Texas, third-party debt collectors and credit bureaus must post a $10,000 bond with the secretary of state.

Communication: Under the TDCA, a debtor has the right to request in writing that a debt collector or creditor cease communication with them. Once a cease communication request has been made, the collector is limited to filing a lawsuit or discontinuing their collection efforts.

Statute of Limitations: Texas law sets forth a four-year statute of limitations for many types of debt, including credit card debt and medical debt. This means a debt collector cannot sue a consumer for a debt that is more than four years old.

Texas provides protections to consumers through state laws that align with the federal Fair Debt Collection Practices Act (FDCPA), along with some additional provisions under the Texas Debt Collection Act (TDCA)

Problems Faced by Doctors and Hospitals Texas

 While the issue of medical debt collection is not unique to Texas, many of the problems it causes here are. One of the biggest problems facing Texas doctors and hospitals is the financial viability of hospitals located in the most rural areas of the state. 131 rural hospitals across the country have closed their doors since 2010 and 23 of them (or just under 18%) have been in Texas. In addition to these hospitals that have closed, about 50% of Texas’ 150 or so rural hospitals are in financial danger.

Another challenge facing Texas doctors and hospitals is that the state has some of the largest amounts of uninsured residents in the country. There are more uninsured people in Texas than California even though the west coast state has 40% more people. These two factors are big challenges for doctors and hospitals in Texas and a major reason why medical debt is such a huge concern.

Filed Under: Medical

Collection Agency for Manufacturing Companies

collection agency manufacturing company

Supply Chains Are Moving. Don’t Let Your Cash Flow Stall.

In the manufacturing sector, “Net 30” is rarely Net 30 anymore. With supply chain disruptions and rising material costs, clients are treating your invoices like interest-free loans.

You aren’t just selling a product; you are financing the raw materials, the labor, and the machine time. When a client delays a $50,000 payment, they are freezing your ability to restock inventory or repair a critical CNC machine.

The “Goodwill” Trap in B2B Collections

Manufacturers often hesitate to collect because of “the relationship.” You worry that a collection letter will offend a long-term distributor or jeopardizing a future contract.

  • The Reality: A client who values the relationship pays you on time. A client who ghosts you is managing their cash flow at your expense.

Nexa specializes in B2B Manufacturing Debt Recovery. We understand the difference between a disputed custom order and a simple refusal to pay. We help you enforce your terms without destroying your supply chain relationships.

The “Zero-Interest” Loan You Didn’t Approve

According to 2025 industry data, the average Days Sales Outstanding (DSO) in manufacturing has crept up to 56 days.

  • The Cost: If you operate on a 10% margin, a $20,000 bad debt requires you to generate $200,000 in new sales just to break even.

  • The Fix: You cannot afford to out-sell bad debt. You must collect it.

Why Nexa is the CFO’s Choice:

  • We Speak “UCC”: We understand the leverage of Uniform Commercial Code (UCC-1) filings and how to use them to secure your position against other creditors.

  • Early Intervention: Our Step 2 Flat-Fee Service ($15/account) is perfect for early-stage delinquency (45-60 days). It sends a professional “shot across the bow” that prioritizes your invoice over others.

  • Protect Your Name: We know your reputation in the industry is vital. Our agents (rated 4.85/5.0) act as professional mediators, not “junkyard dogs.”

A Recovery Workflow Built for Industry

We don’t treat a B2B manufacturing debt like a medical bill. Our process is designed for corporate finance departments.

Phase 1: The “Distributor Nudge” (Early Intervention)

  • Best For: Long-term clients who are “slow-walking” payments or claiming “check run” delays.

  • The Strategy: We deploy Step 2 (Flat-Fee). We send official third-party demands that reference your PO numbers and invoice dates. This signals that the account has been escalated to a professional firm.

  • The Result: The client’s AP department flags your invoice for immediate payment to avoid a credit mark. You keep 100% of the money. This is why we emphasize: Place accounts earlier (Day 60-90) for maximum recovery.

Phase 2: The “Contract Enforcement” (Late Stage)

  • Best For: Clients who have gone silent, custom order disputes, or companies showing signs of insolvency.

  • The Strategy: We move to Step 3 (Contingency). We use commercial skip-tracing to find the owners. We report the commercial debt to credit bureaus (Experian Business, Dun & Bradstreet), which threatens their ability to get financing elsewhere.

  • The Result: We leverage the threat of credit damage or legal action to force a settlement. We charge 20%-40%, but only if we succeed.

Real World Results: Recovering Industrial Revenue

Scenario A: The Custom Fabricator (Metalworks)

  • The Issue: A metal fabrication shop produced a $35,000 custom order for an automotive supplier. The supplier accepted the goods but stalled payment for 120 days, citing “cash flow tightness.”

  • The Fix: We ran a Litigious Check and found the supplier had pending lawsuits from other vendors. We moved immediately to Step 3, serving a demand that threatened a UCC lien enforcement.

  • The Outcome: The supplier, fearing a freeze on their own credit lines, wired the full balance within 5 business days.

Scenario B: The Food Processor (Packaging)

  • The Issue: A packaging manufacturer was owed $12,000 by a regional food brand. The brand claimed “quality issues” only after the invoice was 90 days past due—a common stalling tactic.

  • The Fix: We requested the signed Proof of Delivery (POD) and the initial QC acceptance report. We sent these with a formal legal demand letter.

  • The Outcome: Faced with documented proof that destroyed their dispute, the debtor agreed to a 3-month payment plan. The manufacturer recovered the funds and kept the client on “Pre-Pay” terms for future orders.

FAQ: B2B Debt Recovery

Q: Will sending a client to collections ruin the relationship?

A: Paradoxically, it often saves it. Financial ambiguity ruins relationships. By professionally enforcing your terms, you reset the dynamic. Once the debt is paid, you can resume business on clear terms (e.g., credit limits or deposits).

Q: Can you help if the debtor is in another state?

A: Yes. Manufacturing supply chains are global. We are licensed in all 50 states, so if you are in Ohio but your debtor is in Texas, we can pursue them seamlessly.

Q: What if they have filed for Bankruptcy?

A: We offer a Free Bankruptcy Check before we start. If they have already filed, we will advise you on whether to file a Proof of Claim or write it off, saving you time and legal fees.

Stop Financing Your Customers

Your margins are for your growth, not your client’s float. Secure your revenue with a partner that understands the mechanics of manufacturing debt.

Click here to Contact Us and start your recovery campaign.


Filed Under: Debt Recovery

Will a Collection Agency Ruin My Business Relationship?

It isn’t uncommon for people to have unpaid debt wind up at a Collection Agency. Sometimes they forget that they have an outstanding balance and other times, they simply don’t have the money to pay the lump sum.

If you are a business owner, you may have been forced to make the difficult decision to send your delinquent customer or a business partner to a debt collector.

Most B2C debt is transferred to a collection agency after 60-90 days of non-payment. Most B2B partners try to postpone making this move, but if they are dodging your requests for payments, you may have not have had any other choice. The question is, will this move ruin your business relationship?

Debt collectors are often met with a negative connotation. Your delinquent customer or a business partner probably won’t be happy to learn that you sent their balance to a collector. The good news is, debt collectors use a diplomatic approach specifically so that your business relationship remains in good standing. They understand the importance of business relationships and work hard to preserve it. They will work with the debtor in order to consolidate or get rid of their debt entirely.

To get a full grasp of this concept, let’s look at how a collection agency works in order to determine how it affects your business relationship.

Understanding How Debt Collectors Work

If you decide to send someone’s unpaid balance to a collection agency, they will be immediately notified; usually via phone call or a collection letter. These contacts are often met with apprehension because being sent to collections can possibly effect the debtor’s credit score if the creditor has requested the collection agency to report the debt to the credit bureaus. And, naturally, this can ruin their chances of getting a car, a house, or a business loan.

When Debt Is Sent To Collections

It’s difficult to know when it is time to write off the unpaid debt as a loss. If you have been working with your business partner for some time, you may wait for months or even years before you decide to send their debt to collections. However the chances of recovering the past due amount go down by about 10% each month. The longer you wait, higher the chances are that you will never recover your money.

There is no set dollar amount or time frame that depicts when it’s time to write off unpaid balances. If you get the impression that your partner isn’t going to pay off their capital or they haven’t made an effort to set up payments, you should absolutely cut your losses.

Debt can be sent to a collection agency 31 days past the due date, though many wait until after three to six months of nonpayment. It is recommended to use Debt Collection Letters after 60 days past due date. If the debt is over 120 days or more past due then go for the Collection Calls service.

How It Affects The Debtor’s Credit Score

Not everyone’s credit score is affected unless the original creditor instructs the collection agency to report the debt to the credit bureaus. Generally speaking, those with higher credit scores are often penalized more points than those who have a lower credit score. The amount owed will also determine how many points will be shaved off their credit score.

How A Collection Agency Will Approach Your Delinquent Customer or Business Partner

If someone owes you money, knowing how collection agencies approach debtors can help you rest easy about your decision. In the past, the tact of a debt collector was to make relentless phone calls demanding payment. And if you’re looking to maintain your business relationship, having put your partner in this situation is obviously going to cause some tension.

However, now with the Fair Debt Collection Practices Act (FDCPA), agencies use a more subdued approach when contacting your partner or associate.

Talk To Your Associate First

As the original creditor, you can only send someone to collections 31 days after the payment is past due. The best practice to maintain your business relationship is to talk with your associate first. Have a system in place to send out reminders that payment is due. This includes regular emails, phone calls, and other points of contact.

Approaching your associate about their late payment first can help preserve your relationship. This is recommended instead of sending them straight to collections without warning or notice of this action.

 The Fair Debt Collection Practices Act

This act was created once it had been made clear that, “Abusive debt collection practices contribute to the number of personal bankruptcies, to marital instability, to the loss of jobs, and to invasions of individual privacy.” Along with other reasoning established in this act, debt collectors may not be abusive or vexatious when approaching debtors.

Instead, collection agencies will approach your partner in an amicable way. They may even give guidance on setting up payments to their debt. With these practices, you can rest assured that sending someone’s debt to an agency should not ruin your business relationship. We only recommend notifying your business associate first and educate them on your impending decision to write off their debt. Once you’ve made your decision, the debt agency will take the reins to help settle the outstanding balance.

Conclusion

No Collection Agency can guarantee that your business relationship with the debtor will remain intact during the collection process. However, this article simply conveys you that all good collection agencies use diplomatic and an amicable way to collect a debt, rather than the common notion that debt collectors are intensive, abusive or threatening. This drastically ups the chances to retain your business relationship. If any agency uses threat tactics, it just violated the debt collection laws.

Filed Under: Debt Recovery

Direct Credit Control (DCC) – Debt Collection

Directory >> USA >> California >> Los Angeles >> Direct Credit Control

Direct Credit Control, Inc. (DCC) is a full-service, third-party collection agency with over 30 years of combined collection experience. Each month, DCC reports all valid collection debts to TransUnion LLC and Experian, the National Credit Bureaus. DCC works only in the state of California.

Contact Address:
Direct Credit Control, Inc.
2512 Artesia Blvd
Suite 140-D
Redondo Beach CA 90278

Headquarters Address:
3333 Wilshire Boulevard,
7th Floor
Los Angeles, CA 90010

Phone:

Client Services
(888) 860-2950

Collection Office
(310) 937-3333,
(877) 673-6337

Fax:
(310) 861-1818

Email/Contact:
PBishop@DirectCreditControl.com

Additional Information:

We collect on ALL types of consumer debts. Medical, Dental, Student Tuition, Property Management, Auto Dealerships and judgments.

DCC is not a letter service; each account is assigned to one of our “in-house”, telephone demand collectors. Of course we use collection notices and demands sent by mail, but all collection dun notices are sent by the collector in charge of the account. Collection notices and telephone calls may be directed to a debtor’s place of employment.

Website:
DirectCreditControl.com

Source of information / References:
Information emailed to us by: PBishop@DirectCreditControl.com on 09/24/2019

Make changes to this page? or Add a new collection agency listing?
If you own this collection agency and there is a need to update information presented on this page, kindly email us at “directory@NexaCollect.com“

Information presented about this collection agency may not be 100% accurate or may have changed since we created this page. Kindly visit the agency’s website for the most up to date information.

US Debt Collection Laws: A Guide for Business Owners

debt recovery laws

The Ultimate Guide to USA Debt Collection Laws: Compliance, Statutes, and Recovery

Navigating the landscape of debt recovery in the United States is like walking through a minefield. For business owners and creditors, the goal is simple: recover overdue revenue. However, the path to payment is governed by a complex web of federal acts and state-specific regulations.

One misstep—an accidental call too early in the morning or a letter sent to the wrong address—can result in lawsuits that cost far more than the original debt.

At NexaCollect, we believe that knowledge is leverage. This guide breaks down the essential collection laws you must know and explains why partnering with a nationwide, licensed agency is your best defense against liability.


1. The Federal Framework: The “Big 6” Collection Laws

Federal laws set the baseline for debt collection across all 50 states. While these primarily target third-party collection agencies (like us), original creditors must adhere to many of these standards to avoid “Unfair, Deceptive, or Abusive Acts or Practices” (UDAAP) claims.

A. The Fair Debt Collection Practices Act (FDCPA)

This is the “constitution” of debt collection. Enacted in 1977, it prohibits abusive practices.

  • Communication Limits: Collectors cannot call before 8:00 AM or after 9:00 PM (local time).

  • Harassment: No threats of violence, use of profane language, or repeated calling to annoy.

  • False Statements: Collectors cannot claim to be attorneys or government officials if they are not, nor can they threaten legal action they do not intend to take.

  • Validation: The debtor must be sent a written “Validation Notice” within 5 days of initial contact, detailing the debt and their right to dispute it.

B. The Fair Credit Reporting Act (FCRA)

This law governs how debt is reported to bureaus (Equifax, Experian, TransUnion).

  • Accuracy: Creditors and agencies must report accurate information.

  • Disputes: If a consumer disputes a debt, the furnisher of information must investigate and correct errors within 30 days.

  • 7-Year Rule: Most negative credit information must be removed after seven years.

C. The Telephone Consumer Protection Act (TCPA)

In the modern era, this act is a major source of litigation.

  • Robocalls: It strictly restricts the use of auto-dialers and pre-recorded messages to cell phones without express consent.

  • Revocation: Consumers can revoke consent to be called at any time.

D. Servicemembers Civil Relief Act (SCRA)

This protects active-duty military personnel.

  • Interest Caps: Interest on pre-service debts is often capped at 6%.

  • Legal Protections: It creates high hurdles for obtaining default judgments against active servicemembers.

E. Gramm-Leach-Bliley Act (GLBA)

While primarily for financial institutions, this affects collection by mandating strict privacy rules regarding how non-public personal information (NPI) is shared and protected.

F. HIPAA (Medical Debt):

For healthcare providers, the Health Insurance Portability and Accountability Act (HIPAA) mandates that collection agencies must sign a Business Associate Agreement (BAA) and strictly limit the use of Protected Health Information (PHI) to the minimum necessary for recovery.


2. State-Specific Nuances: Where It Gets Tricky

Federal law is the floor, not the ceiling. Many states have enacted “mini-FDCPAs” that are stricter than federal law.7 A nationwide agency must use software that automatically adjusts to these local rules.

California: The Rosenthal Act

  • Scope: Unlike the federal FDCPA, California’s Rosenthal Act applies to original creditors as well as third-party agencies.

  • Recording: California is a “two-party consent” state, meaning you cannot record a collection call unless the debtor agrees.

New York: Consumer Credit Fairness Act

  • Statute of Limitations: Recently reduced from 6 years to 3 years for consumer credit transactions.

  • Notice: Requires specific, detailed notices to be mailed to debtors before and during the legal process.

Texas: Texas Debt Collection Act (TDCA)

  • Bonding: Third-party agencies must file a surety bond with the Texas Secretary of State.

  • Fee Limits: Strict limits on adding collection fees unless explicitly authorized by the contract and state law.

Massachusetts: Frequency Limits

  • Strict Contact: Collectors generally cannot initiate a communication with a debtor (via phone or text) more than twice within a seven-day period.

Florida: FCCPA

  • Consumer Protection: Prohibits communicating with a debtor if the creditor knows the debtor is represented by an attorney. Violations carry statutory penalties even without actual damages.


3. The Statute of Limitations (SOL) Guide

The Statute of Limitations is the time period a creditor has to file a lawsuit to collect a debt. Once this expires, the debt is “time-barred.” You can still ask for payment, but you cannot sue.

Note: B2B (Written Contracts) often have longer SOLs than Open Accounts (Credit Cards).

State Open Account (Credit Card) Written Contract Oral Contract
California 4 Years 4 Years 2 Years
Florida 4 Years 5 Years 4 Years
Georgia 4 Years 6 Years 4 Years
Illinois 5 Years 10 Years 5 Years
New York 3 Years 3 Years 3 Years
Texas 4 Years 4 Years 4 Years
Pennsylvania 4 Years 4 Years 4 Years

(Disclaimer: Laws change frequently. Always consult a legal professional for specific case advice.)


4. Why You Need a Full-Spectrum, Licensed Agency

Given the complexity of the laws above, managing collections in-house is risky. Here is why partnering with NexaCollect is the smartest move for your bottom line and your brand.

A. Nationwide Coverage & Licensing

We are licensed and bonded to collect in all 50 states. If your debtor moves from Texas to New York, you don’t need a new agency. We follow them, adjusting our compliance protocols automatically to match their new jurisdiction.

B. Protecting Your Reputation (High Google Ratings)

The old “break their knees” approach to collections is dead. It results in lawsuits and 1-star reviews that kill your future sales.

  • Our Approach: We view ourselves as an extension of your customer service. We use diplomatic, firm, and respectful mediation to recover funds. This is why our agency maintains high Google ratings—we treat people with dignity.

C. The Full Spectrum Model: Fixed-Fee to Legal

Most agencies force you into a 40% contingency fee immediately. We don’t. We offer a tiered approach designed to save you equity:

  1. Step 1 & 2 (Fixed-Fee): For a low flat rate (e.g., $15/account), we act as a third-party intervention. You keep 100% of the money recovered here.

  2. Step 3 (Contingency): If they don’t pay, we escalate to intensive calls. We only charge a percentage (typically 40%) if we collect.

  3. Step 4 (Legal): If the debtor has assets but refuses to pay, our network of specialized attorneys can litigate.

D. Commercial vs. Consumer Expertise

Laws for collecting B2B (Commercial) debt differ vastly from Consumer debt. The FDCPA primarily protects consumers. Commercial collections allow for more aggressive strategies. Our team is trained to distinguish between the two, maximizing pressure on businesses while staying compliant with consumers.


Summary

Debt collection in the USA is not just about persistence; it’s about precision. With the FDCPA, TCPA, and state laws like the Rosenthal Act watching every move, you need a partner who understands the rules of the game.

NexaCollect offers the compliance shield you need with the recovery results you deserve.

Ready to recover your revenue without the risk?

Contact Us Today for a Free Quote

Filed Under: Debt Recovery

  • « Go to Previous Page
  • Page 1
  • Interim pages omitted …
  • Page 12
  • Page 13
  • Page 14
  • Page 15
  • Page 16
  • Interim pages omitted …
  • Page 27
  • Go to Next Page »

Primary Sidebar


accounts receivable

Need a Collection Agency?
Kindly fill this form.
We’ll get in touch with you

    Please prove you are human by selecting the flag.

    Compliance & Security

    • SOC 2 Type II Certified: Third-party audited data security and strict privacy controls.

    • HIPAA Compliant: Secure, legal processing of medical and municipal EMS accounts.

    • PCI-DSS Level 1: Highest tier of data encryption for secure payment processing.

    • FDCPA & FCRA Aligned: Full legal adherence to federal consumer protection laws.

    Recent Posts

    • Why Dental Patients Dispute Bills: The Nexa Collections Dental Account Dispute Index
    • 2027 Commercial Collections Benchmark: U.S. Late Payments, AR Risk and B2B Collection Trends
    • Bulk Account Placement: What a Collection Agency Actually Needs From You
    • Nationwide Debt Collection Agency Serving U.S. Cities
    • Chula Vista Collection Agency for Medical, B2B, Schools & Business Debt
    • Corpus Christi Collection Agency: Itemized Bill Rules for Practices
    • Riverside Collection Agency | For Logistics, Medical, Schools & Business Recovery
    • Collection Agency for Large Balances: High-Value B2B Debt Recovery

    Featured Posts

    • Lean Management for Universities
    • Minimizing Inaccurate Credit Reporting by Credit Unions
    • Overcome Competition and Market Saturation in Dental Profession

    Copyright © 2026 NEXACOLLECT.COM | This content is provided for general informational purposes only and should not be considered legal advice. Collection laws and requirements may vary by state, account type, documentation, debtor status, and specific facts. Please consult qualified legal counsel for guidance regarding your particular situation. Nexa and its authorized collection partners service accounts in accordance with applicable federal and state collection requirements. Visit our home page to know more about us.

    X
    Need a Collection Agency?
    Contact Us