• Skip to main content
  • Skip to primary sidebar

Nexa Collections

  • Home
  • Serving
    • Medical
    • Dental
    • Small Business
    • Large Business
    • Commercial Collections
    • Government
    • Utilities
    • Fitness Clubs
    • Schools
    • Senior Care Facility
  • Contact Us
    • About us
    • Cost

Search Results for: the bureaus

Collection Agency in Ohio for Business, School & Medical Debt Recovery

In Ohio, the deadline for collecting a debt depends on exactly what kind of account you have. From Columbus and Cleveland to Cincinnati, Toledo and Akron, NexaCollect helps businesses and medical providers recover past-due balances while navigating Ohio’s different rules for consumer, commercial and contract debt.

Many written contracts and covered consumer transactions carry a 6-year limitation period, while certain non-written contracts and contracts for the sale of goods can have a 4-year window. The difference matters: identify the debt correctly, document it properly and act before valuable recovery options narrow.
Nexa provides 100% reputation-safe, equipped with all 50-state collections license, offering free credit reporting, free litigation/bankruptcy scrubs, and zero onboarding fees. Secure – SOC 2 Type II & HIPAA compliant.

Need a Collection Agency? Contact us


The Nexa Advantage: Cost-Effective Recovery

We offer two transparent pricing tiers to protect your margins in Idaho’s competitive market:

  • Fixed-Fee Recovery ($15/account): Ideal for early-stage delinquency. Your clients pay 100% of the funds directly to you, while Nexa handles the professional outreach.

  • Contingency Service (40%): Our “No Recovery, No Fee” model. We assume all risk and legal costs; you only pay a percentage of what we successfully collect.

  • Zero Onboarding Fees: No setup costs, no hidden tech fees, and no monthly retainers.

Industries We Serve in Ohio

  • Manufacturing & Logistics: B2B recovery for automotive and steel suppliers in the “Crossroads of America.” We handle high-value freight brokerage and warehousing disputes with a focus on the 6-year contract statute.

  • Healthcare, Dental & Medical: 100% HIPAA-compliant. We are fully prepared for the Ohio Medical Debt Fairness Act (2026), maintaining your right to collect via mediation while adhering to new interest caps and indigency screening rules.

  • Colleges & Universities: From Ohio State to local private institutions, we manage tuition recovery and bursar accounts with a focus on student-first mediation and preserving alumni relationships.

  • K-12 Private & Charter Schools: Managing unpaid enrollment fees with a diplomatic approach tailored for Ohio’s growing school choice landscape and the EdChoice expansion.

  • Accountants & CPA Firms: Recovery of professional service fees. We understand the “net-30” billing cycle and use professional mediation to ensure you get paid without damaging client rapport.

  • Banks & Credit Unions: Expert handling of delinquent consumer loans and deficiency balances using Ohio’s aggressive 21-year judgment life.

  • Construction & Trades: Revenue recovery for HVAC, electrical, and general contractors (Experts in ORC Chapter 1311 Mechanic’s Liens and 75-day filings).

  • B2B Commercial, Restoration & Waste Management: High-speed recovery for service providers who need cash flow restored immediately to stay competitive in the Midwest.

Sector Spotlight: The Ohio Dental “squeeze”

Ohio’s dental market is uniquely pressured. While the average dental practice in the state generates over $1 million in revenue, operational overhead consumes nearly 62% of that income. You cannot afford to lose the remaining margin to bad debt.

  • The Uninsured Gap: Nearly 19% of Ohio children lack dental insurance—that is four times the rate of those without medical insurance. This creates a massive volume of “self-pay” responsibility that parents often struggle to manage.

  • The “Oral Contract” Risk: Many dental offices rely on simple sign-in sheets or verbal agreements for copays. Under Ohio law, these are often classified as “oral contracts,” which now have a strict 4-year statute of limitations. If your current agency is sitting on 5-year-old debt, they are chasing ghosts.


The Consumer Minefield: Why Federal Rules Aren’t Enough

If your agency follows a generic “50-State” playbook, they will miss the Ohio-specific traps that defense attorneys love to exploit.

1. The “Portfolio Acquisitions” Trap (SB 13)

  • The Law: Ohio distinguishes between “Written Contracts” (6 years) and “Open Accounts” (4 years).

  • The Risk: Following the legal precedent of Portfolio Acquisitions, LLC v. Feltman, courts frequently classify credit card debt and loose medical invoices as “Open Accounts.”

  • The Reality: If your agency waits until year 5 to file suit—thinking they are safe—the judge will dismiss the case with prejudice. You lose the money and pay legal fees.

  • Our Solution: We run a “Date of Service” Audit immediately. Any account approaching the 48-month mark is flagged for immediate escalation.

2. HCAP & The Indigent Defense

  • The Law: Ohio’s Hospital Care Assurance Program (HCAP) mandates free care for residents below the poverty line.

  • The Risk: With 41% of adults carrying healthcare debt, many of your patients may legally qualify for retroactive HCAP status. Suing them isn’t just futile; it invites an Attorney General investigation.

  • Our Solution: We screen for HCAP eligibility before we dial. If a patient qualifies, we help you process the claim to get paid by the state pool, rather than harassing a family that cannot pay.


The B2B Advantage: The “Cognovit” Nuclear Option

While consumer collections are getting harder, Ohio offers B2B creditors a weapon that exists in almost no other state.

  • The Weapon: The Cognovit Note (Ohio ORC § 2323.13).

  • The Power: If your commercial contract includes this specific clause (and the required warning text), the debtor waives their right to a trial.

  • The Result: We can walk into a court and obtain a judgment against a non-paying business in as little as 24 hours. No hearings. No delays. We freeze their assets before they even know we’ve filed.

  • The Catch: This is strictly illegal for consumer debts. We only use this for your commercial accounts, ensuring we stay on the right side of the law.


Real Ohio Recovery Scenarios

Here is how our specific knowledge of the Ohio Revised Code translates into recovered dollars.

Case Study 1: The “Handshake” Hygiene Bill (Dental)

  • The Client: A multi-location pediatric dental group in Cincinnati.

  • The Problem: They had $90,000 in unpaid orthodontic overages. The parents had agreed verbally to the extra costs, but the paperwork was thin. The debt was approaching 4.5 years old.

  • The Nexa Strategy: We recognized that under SB 13, these “verbal” agreements were already time-barred (4-year limit). Instead of wasting money on lawsuits we would lose, we pivoted to a “Credit Reporting Amnesty” campaign. We offered to settle for 60% if paid immediately, leveraging the fact that we could still report the debt to credit bureaus even if we couldn’t sue.

  • The Result: Recovered $38,000 from parents who wanted to clear their credit for mortgage applications, salvaging revenue that was legally uncollectible in court.

Case Study 2: The “Cognovit” Fast-Track (Construction)

  • The Client: A heavy equipment supplier in Akron.

  • The Problem: A contractor rented three bulldozers, racked up $55,000 in fees, and went silent. Rumors swirled that the contractor was liquidating assets to flee the state.

  • The Nexa Strategy: We reviewed the rental agreement and found a valid Cognovit Warning. We bypassed standard letters entirely. We filed for a Confession of Judgment on Monday morning. By Tuesday afternoon, we had a judgment and a bank attachment order served on their primary operating account.

  • The Result: We seized the full $55,000 before the contractor could drain the account.


Quick Guide: Ohio Collection Laws

For your reference, here is the cheat sheet on what is (and isn’t) legal in the Buckeye State.

Feature Consumer Debt (B2C) Commercial Debt (B2B)
Confession of Judgment VOID / ILLEGAL LEGAL (Allows instant judgment).
Statute of Limitations 6 Years (Written) / 4 Years (Oral/Open) 6 Years (Written) / 4 Years (Oral/Open).
Wage Garnishment 25% (Continuous Order allowed) 25% (Continuous Order allowed).
Medical Interest Rate Proposed Cap at 3% (HB 257) Contract Rate or Statutory 8%.
Hospital Liens NO STATE STATUTE (Contractual only) N/A

Frequently Asked Questions About Debt Collection in Ohio

1. How long does an Ohio business have to collect an unpaid invoice?

There is no single deadline for every unpaid invoice in Ohio. A written contract generally has a 6-year limitation period, while a contract that is not in writing generally has a 4-year period. Contracts for the sale of goods are generally subject to a separate 4-year UCC limitation period. The correct deadline depends on the transaction and supporting documentation.

2. Do I need a signed contract to collect an unpaid debt in Ohio?

No. An unpaid debt does not necessarily need a signed written contract to be collectible in Ohio. However, documentation can affect both your ability to prove the debt and the time available for legal action. Ohio generally gives non-written contracts a 4-year limitation period, while covered consumer transactions generally have a 6-year period whether or not the agreement was reduced to writing.

3. How long can an Ohio business collect unpaid B2B invoices for goods?

Contracts for the sale of goods generally have a 4-year statute of limitations in Ohio. Ohio’s version of UCC §2-725 applies to breach-of-contract actions involving sales of goods, and the parties may contractually shorten that period to no less than one year but generally cannot extend it. This distinction is especially important for manufacturers, distributors, equipment suppliers and wholesalers.

4. Can wages be garnished to collect a debt in Ohio?

Yes, but an Ohio creditor generally must first obtain a judgment before garnishing wages. Ohio’s garnishment procedure then limits the amount that can be withheld using statutory calculations involving 25% of disposable earnings and a protected amount based on the federal minimum wage. Additional exemptions and procedural requirements may apply.

5. What is the deadline for filing a mechanic’s lien in Ohio?

Ohio’s mechanic’s-lien deadline depends on the type of project. A lien involving a one- or two-family dwelling generally must be recorded within 60 days after the claimant’s last labor or materials. Many other projects use a 75-day deadline, while certain oil-and-gas-related liens have a 120-day deadline. Contractors should address unpaid accounts well before these deadlines.

6. How much does a collection agency cost in Ohio?

NexaCollect offers two primary collection options for Ohio creditors: a $15 fixed-fee program for qualifying earlier-stage accounts and a 40% contingency program for accounts requiring more intensive collection activity. Under the fixed-fee option, payments go directly to the client; under contingency collections, the fee is based on amounts successfully recovered.


Popular Cities:
  • Columbus
  • Defiance
  • Gahanna
  • Hamilton
  • New Albany
  • Mason
  • Ohio
  • Berea
  • Hudson
  • Rocky River
  • Beachwood
  • Cleveland
  • Toledo
  • Dayton

New York Collection Agency | Business, School & Medical Debt Recovery

In New York, overdue accounts can lose legal leverage fast. From Manhattan and Long Island to Buffalo, Rochester and Albany, NexaCollect helps businesses and medical providers recover past-due balances while navigating New York’s 3-year deadlines for consumer-credit and medical-debt actions, the statewide ban on medical-debt credit reporting, and increasingly strict New York City collection rules.

And for NYC accounts, the compliance bar gets even higher on September 1, 2026, when the new SHIELD Collection Rule takes effect. The strategy is simple: act early, document the debt and use the right compliant recovery path before your options narrow.

Sample business invoice and account statement representing managed debt collection in New York

Navigating the 3-Year “Drop-Off”

In New York—from the global financial hubs of Manhattan and the industrial centers of Buffalo and Rochester to the tech corridors of Albany—doing business requires a level of compliance that most national agencies simply cannot reach. In 2026, the stakes are higher than ever. With the Consumer Credit Fairness Act slashing the window to sue for consumer debt to just 3 years and the total ban on medical debt credit reporting, the old “wait and see” approach is a recipe for total loss. You don’t just need a collector; you need a New York-licensed strategist who can secure your revenue before it becomes legally uncollectible “zombie debt.”

Nexa provides reputation-safe, equipped with all 50-state collections license, offering free credit reporting, free litigation/bankruptcy scrubs, and zero onboarding fees. Secure – SOC 2 Type II & HIPAA compliant.

Need a Collection Agency? Contact us


The New York Legal Landscape (2026 Summary)

New York laws are designed to protect the debtor. If your agency doesn’t hit the 3-year deadline or fails to provide the mandatory Notice of Lawsuit, your claim is dead on arrival.

Debt Category Statute of Limitations New York Statute (CPLR)
Consumer/Credit Card 3 Years CPLR § 214-i
Medical Debt 3 Years CPLR § 213-d
B2B / Commercial 6 Years CPLR § 213(2)
Wage Garnishment 10% Cap (Strict) CPLR § 5231
Judgments 20 Years CPLR § 211(b)

Critical New York Rules for 2026:

  • The 3-Year Consumer Trap: Under the CCFA, consumer debt (including medical) expires in just 3 years. Making a partial payment no longer “restarts” the clock. Nexa’s high-speed “Step 1” demand service is essential to identify solvent debtors before the 36-month cliff.

  • Fair Medical Debt Reporting Act: New York hospitals and providers are prohibited from reporting medical debt to credit agencies. Nexa utilizes judicial judgments and bank levies to maintain “teeth” where credit threats no longer exist.

  • The $17.00 Wage Shield: As of Jan 1, 2026, the NYC/Long Island/Westchester minimum wage is $17.00/hr. Under New York law, you cannot garnish a debtor’s wages unless they earn more than 30x the minimum wage ($510/week). Nexa scrubs your accounts to ensure you aren’t suing “judgment-proof” individuals.

  • NYC-Specific Restrictions: New York City has its own set of restrictive laws that complicate collections. With the new 2026 mayor-elect signaling even tougher enforcement through the DCWP, NYC clients should avoid collecting money themselves. The regulatory climate is so pro-debtor that professional mediation is the only safe path. Note: NYC pressure is limited by law; therefore, our Step 2 Fixed-Fee service is the most strategic entry point to trigger payment without the risk of high-commission litigation.


Cost-Effectiveness: The Nexa Advantage

New York compliant debt collection agency trust badge featuring $15 fixed fee and nationwide recovery network

  • Fixed-Fee Recovery ($15/account): Ideal for early-stage and high-volume accounts. Debtors pay 100% directly to you. No commissions.

  • Contingency Service (20%–40%): Performance-based recovery. No Recovery, No Fee.


Industries We Serve in New York

  • Manufacturing & Logistics: B2B recovery for the automotive and industrial sectors in Upstate New York. We handle high-value freight brokerage and warehousing disputes, utilizing the 6-year commercial statute to your advantage.

  • Healthcare & Medical: 100% HIPAA-compliant. We specialize in navigating the 3-year medical statute and the total reporting ban, using mediation to preserve patient trust across the Mount Sinai, NYU Langone, and Northwell regional footprints.

  • Colleges & Universities: From the SUNY system to private Ivy League institutions, we manage tuition and bursar recovery with a focus on student-first mediation and institutional reputation.

  • K-12 Private & Charter Schools: Managing unpaid enrollment fees with a sensitive, diplomatic approach tailored for New York’s competitive educational landscape.

  • Accountants & CPA Firms: Recovery of professional service fees. We understand the “net-30” billing cycle and use professional mediation to ensure you get paid without damaging client rapport.

  • Banks & Credit Unions: Expert handling of delinquent consumer loans and deficiency balances using New York’s strict CCFA compliance frameworks.

  • Construction & Trades: Revenue recovery for HVAC, electrical, and general contractors. We are experts in New York Lien Law Article 2 and the strict 8-month filing window for private projects.

  • B2B Commercial, Restoration & Waste Management: High-speed recovery for service providers in the Tri-State area who need immediate cash flow to manage high operational and labor costs.


Recent New York Recovery Results

Case 1: Manhattan-Area Specialty Surgical Center (Medical)

  • The Problem: $165,000 in aging patient debt approaching the 3-year statute. The clinic could no longer report to credit bureaus due to the new NY ban.

  • The Result: Nexa implemented a legal-forward mediation strategy, recovering $112,000 in 70 days via bank levies and professional settlements.

Case 2: Buffalo-Based Industrial Supplier (B2B)

  • The Problem: A $58,000 unpaid invoice from a vendor who claimed “supply chain insolvency.”

  • The Result: Utilizing New York’s 6-year contract statute and a formal pre-legal demand, Nexa secured a full $58,000 recovery plus interest in just 32 days.


Frequently Asked Questions (FAQ)

1. What is the statute of limitations on consumer debt in New York?

New York generally provides a three-year limitation period for actions arising from consumer credit transactions under CPLR § 214-i, shortened from six years by the Consumer Credit Fairness Act. The CCFA also imposes additional pleading, proof and notice requirements on consumer credit lawsuits, so documentation quality matters as much as timing. Both points push in the same direction: aging consumer accounts lose options quickly in New York, and thin files lose them faster.

2. How is medical debt treated differently in New York?

Several ways. An action on medical debt by a qualifying New York hospital or healthcare professional generally must be commenced within three years of treatment under CPLR § 213-d. Separately, CPLR § 5231 provides that no amount may be imposed through an income execution on a judgment arising from a medical-debt action brought by a qualifying hospital or healthcare professional — meaning wage garnishment is generally unavailable as a remedy on those judgments. Medical accounts are also subject to the credit reporting prohibition described below. Taken together, these narrow the enforcement toolkit considerably, which is why documentation and compliant communication carry more of the load on New York medical files.

3. Can medical debt be reported to credit bureaus in New York?

No. New York law prohibits consumer reporting agencies from reporting or maintaining medical debt in a consumer’s credit file. For healthcare providers, this removes credit reporting as a recovery lever entirely, making professional communication, accurate documentation and workable payment resolution the practical path on unpaid patient balances.

4. What changes under New York City’s SHIELD Rule on September 1, 2026?

The SHIELD Rule (6 RCNY § 5-77) takes effect September 1, 2026 and is among the most significant municipal debt collection changes in the country. Key provisions:

  • Original creditors are covered, not only third-party collectors, once account servicing ends and collection activity begins. Hospitals and businesses collecting their own NYC receivables should assess whether they are in scope.
  • Communication cap: no more than three communications or attempted communications per account in any seven consecutive days, counting phone, text and email together, with limited-content messages included. A collector generally may not contact the consumer again in that period once the consumer has responded.
  • Disputes at any time: consumers may dispute or request verification at any point in the collection lifecycle, not only within the federal 30-day window.
  • Verification with a deadline: documentation must be produced within 60 days of a request — at minimum a charge-off account statement, a signed contract or application, and a final balance statement, with a default judgment alone insufficient. If it isn’t produced, the collector must send a Notice of Unverified Debt and generally loses the ability to collect the account.
  • Medical debt carries additional dispute protections.

The most stringent dispute and verification provisions apply to accounts for which a validation notice is required on or after September 1, 2026, excluding accounts purchased before that date.

5. Does a collection agency need a license to collect debts in New York City?

Yes, for covered consumer collections. A business that regularly collects or attempts to collect personal or household debts from New York City residents generally needs a Debt Collection Agency License from the NYC Department of Consumer and Worker Protection, and that requirement applies even where the agency is located outside New York State. Creditors placing NYC consumer accounts should confirm their agency’s licensure before placement.

6. How long can a business collect B2B debt in New York?

Many contractual B2B claims are subject to a six-year limitation period under CPLR § 213. The applicable deadline depends on the transaction, though — New York’s UCC generally provides a four-year period for contracts for the sale of goods. A supplier and a service provider with similar-looking invoices can therefore be working against different clocks, so commercial accounts are best evaluated against the underlying agreement rather than by category.

7. How much of a debtor’s wages can be garnished in New York?

An income execution generally cannot exceed 10% of a judgment debtor’s gross income, with further limits applying based on disposable earnings. New York also protects earnings below the greater of 30 times the applicable federal or state minimum hourly wage, and other statutory restrictions may reduce the amount available further. Note the separate rule for medical-debt judgments described above, where income execution is generally unavailable.

8. How much does a collection agency cost in New York?

Nexa offers a $15 fixed-fee recovery option for qualifying earlier-stage accounts, under which recovered payments go directly to the client, alongside contingency collection for accounts requiring more intensive effort. The appropriate program and contingency rate depend on account type, age, balance and complexity.


Get a Free Analysis? Contact us

  • New York City
  • Bohemia
  • Poughkeepsie
  • Mount Sinai
  • Geneseo
  • Westbury
  • Commack
  • Arcade
  • Syosset
  • Buffalo
  • Valhalla
  • Babylon
  • Thornwood
  •  Amherst
  • Bellmore
  • Staten Island
  • Baldwin
  •  Bath
  • Tonawanda
  • Cheektowaga
  • Coram
  • East Northport
  • Elmsford
  • Fairport
  • Farmingdale
  • Flushing
  • Plainview
  • New York
  • Hewlett
  • Hicksville
  • Hornell
  • Inwood
  • Lindenhurst
  • Nesconset
  • Newburg
  • Patchogue
  • Syracuse
  • Tarrytown
  • Garden City
  • Melville
  • White Plains

Collection Agency in Nevada | Compliant & Effective

In Nevada—from the high-velocity gaming and tourism sectors of Las Vegas and Henderson to the logistics powerhouses of Reno and Sparks—cash flow is the lifeblood of the desert economy. But as of January 1, 2026, the legal landscape has shifted. With the full implementation of AB 204, medical debt collection is now under a 180-day “extraordinary action” freeze, and Nevada’s $10,000 automatic bank exemption has made traditional asset seizures more complex than ever. You don’t just need a collector; you need a Nevada-licensed strategist who knows how to break through these new shields using surgical mediation and sophisticated skip-tracing.

Nexa provides 100% reputation-safe, equipped with all 50-state collections license, offering free credit reporting, free litigation/bankruptcy scrubs, and zero onboarding fees. Secure – SOC 2 Type II & HIPAA compliant.

Need a Collection Agency? Contact us


The Nevada Legal Landscape

Nevada offers one of the strongest “Statutes of Repose” for written contracts in the West, but new debtor protections require a “compliance-first” approach to avoid FID penalties.

Debt Category Statute of Limitations Nevada Law (NRS)
Written Contracts 6 Years NRS § 11.190(1)(b)
Oral / Open Accounts 4 Years NRS § 11.190(2)(c)
Medical Debt 6 Years AB 204 / SB 248 Rules
Wage Garnishment 18% – 25% Cap NRS § 31.295
Judgments 6 Years (Renewable) NRS § 11.190

Critical Nevada Rules for 2026:

  • The 180-Day Medical Freeze (AB 204): As of 2026, health care entities and agencies are prohibited from “extraordinary collection actions”—including credit reporting, lawsuits, or garnishments—until 180 days after the first bill. Nexa’s specialized medical workflow ensures you stay compliant while maximizing early-stage “soft” recovery.

  • The $10,000 Bank Shield: Nevada law now protects up to $10,000 in a debtor’s bank account from attachment. Nexa uses advanced asset-scrubbing to identify accounts that exceed this threshold, ensuring your legal spend is never wasted on “exempt” funds.

  • SB 248 Notice Requirements: Before any action is taken on medical debt, a specific 60-day notice must be sent via registered/certified mail. Our systems are hard-coded to automate this, preventing the technical errors that lead to dismissed cases.

  • Garnishment Math: Nevada limits garnishment to the lesser of 25% of disposable earnings (18% if weekly wages are under $770) or the amount by which income exceeds 50x the federal minimum wage.


Cost-Effectiveness: The Nexa Advantage

  • Fixed-Fee Recovery ($15/account): Best for high-volume, early-stage debt. Debtors pay 100% directly to you.

  • Contingency Service (20%–40%): Performance-based recovery. No Recovery, No Fee.


Industries We Serve in Nevada

  • Logistics & Distribution: B2B recovery for the Reno-Tahoe and North Las Vegas hubs. We handle high-value freight brokerage and warehousing disputes for the “Crossroads of the West.”

  • Healthcare & Medical: 100% HIPAA-compliant. We are the masters of SB 248 and AB 204 compliance, helping Vegas and Henderson practices recover funds without violating the 180-day extraordinary action ban.

  • Gaming & Entertainment: Specialized recovery for unpaid markers, corporate events, and vendor disputes in the world’s entertainment capital. We do not collect gambling related amounts.

  • Colleges & Universities: From UNLV to UNR, we handle tuition fee recovery and housing balances, balancing firm tactics with the need to preserve institutional reputation.

  • Accountants & CPA Firms: Recovery of professional service fees. We understand the Nevada business tax cycle and ensure you get paid without damaging client rapport.

  • Banks & Credit Unions: Expert handling of delinquent consumer loans and deficiency balances using Nevada’s 6-year judgment renewal window.

  • Construction & Trades: Revenue recovery for HVAC, electrical, and general contractors. We specialize in NRS Chapter 108 (Mechanic’s Liens) to secure your right to payment.

  • B2B Commercial & Restoration: High-speed recovery for service providers in the booming Nevada restoration and commercial waste sectors.


Recent Nevada Recovery Results

Case 1: Las Vegas Multi-Specialty Surgery Center (Medical)

  • The Problem: $155,000 in aging patient debt. The client was paralyzed by the new AB 204 notice requirements and 180-day freeze.

  • The Result: Nexa implemented a compliant “Step 1” notification system, recovering $92,000 in 75 days purely through mediation, avoiding the need for “extraordinary actions.”

Case 2: Reno Logistics & Freight Broker (B2B)

  • The Problem: A $48,000 unpaid freight invoice from a California-based vendor using a Reno warehouse.

  • The Result: Utilizing Nevada’s 6-year written contract statute and a formal pre-legal demand, Nexa secured a full $48,000 recovery plus interest in just 19 days.


Frequently Asked Questions (FAQ)

1. Can I still sue for medical debt in Nevada?

Yes, but only after the 180-day freeze and the 60-day notice period have passed. Nexa manages this timeline for you to ensure your lawsuit isn’t dismissed on a technicality.

2. What is the $10,000 bank exemption?

Nevada protects the first $10,000 in a debtor’s bank account from being seized by creditors. We skip-trace for high-net-worth indicators to ensure we only target accounts that are legally reachable.

3. Does Nexa handle credit reporting?

Yes. For all eligible non-medical accounts, we report to the major bureaus. For medical debt, we follow the 180-day reporting delay required by 2026 law.

Popular cities:

  • Las Vegas
  • Reno
  • Henderson

Collection Agency in Montana for Business, School & Medical Debt Recovery

NexaCollect helps Montana businesses, medical practices, schools, and organizations recover past-due accounts through professional, reputation-focused debt collection. We serve creditors across Montana, including Billings, Missoula, Bozeman, Great Falls, Helena, and Kalispell. Choose a $15 fixed-fee option for fresher accounts or contingency collections for harder-to-recover balances.

Compliant and low cost Montana Collection Agency

Nexa provides reputation-safe, equipped with all 50-state collections license, offering free credit reporting, free litigation/bankruptcy scrubs, and zero onboarding fees. Secure – SOC 2 Type II & HIPAA compliant.

Need a Collection Agency?

Contact us to discuss the right recovery approach for your Montana receivables.


Why Montana Businesses Choose NexaCollect

Past-due accounts drain staff time and cash flow. NexaCollect gives Montana creditors a structured way to pursue receivables while keeping communication professional.

  • $15 Fixed-Fee Collections: Ideal for earlier-stage accounts; you keep 100% of recovered payments.

  • 40% Contingency Collections: For older consumer accounts; no recovery, no contingency fee.

  • Reputation-Focused Communication: Firm, respectful outreach designed to protect customer and patient relationships.

  • Account Screening: Bankruptcy and litigation screening can help identify accounts that need different handling.

  • Nationwide Reach: Useful when a Montana creditor has debtors in other states.

  • Secure Handling: SOC 2 Type II and HIPAA-aligned processes support sensitive account information.

Debt Collection Costs for Montana Businesses

Fixed-Fee Recovery

For about $15 per account, NexaCollect can send professional collection demands while the client keeps 100% of recovered payments. This is generally best suited to fresher accounts (30 to 90 days past due).

Contingency Collections

Older or more difficult consumer accounts can move to full collection activity at a typical 40% contingency fee. If nothing is recovered, there is no contingency fee. Commercial B2B pricing may vary based on account size, age, and complexity.

Montana Debt Collection Laws: What Creditors Should Know

Montana creditors should consider both federal requirements and state-specific rules before escalating an account.

Contract Limitation Periods

MCA § 27-2-202 currently provides six years for actions founded on an instrument in writing and five years for contracts, accounts, or promises not founded on an instrument in writing. The correct limitation period can depend on the underlying documents and circumstances.

Wage Garnishment

Under MCA § 25-13-614, ordinary judgment garnishment is generally limited to the lesser of 25% of disposable weekly earnings or the amount by which those earnings exceed 30 times the federal minimum hourly wage. Different rules apply in certain situations.

Judgments

MCA § 27-2-201 generally provides a 10-year period for actions upon qualifying judgments.

> Noted: Older, disputed, or legally complex accounts should be reviewed individually before legal action is considered.

Industries We Serve Across Montana

Medical & Healthcare Collections

Patient-sensitive debt recovery for medical practices, clinics, and other healthcare providers, with privacy, compliance, and practice reputation protection in mind. Learn more about our Medical Collection Agency Services.

Commercial & B2B Collections

Recovery of unpaid invoices, contractual balances, and other business receivables for Montana companies. Explore our Commercial Collection Agency Services.

Construction & Trades

Past-due account recovery for contractors, HVAC companies, electricians, and other trade service businesses.

Schools & Education

Recovery of qualifying tuition, enrollment, and educational balances using relationship-sensitive communication.

Professional Services

Debt recovery for accountants, consultants, legal practices, and other professional firms seeking payment without unnecessary client friction.

Manufacturing & Logistics

Commercial collection support for businesses serving customers throughout Montana and across state lines.

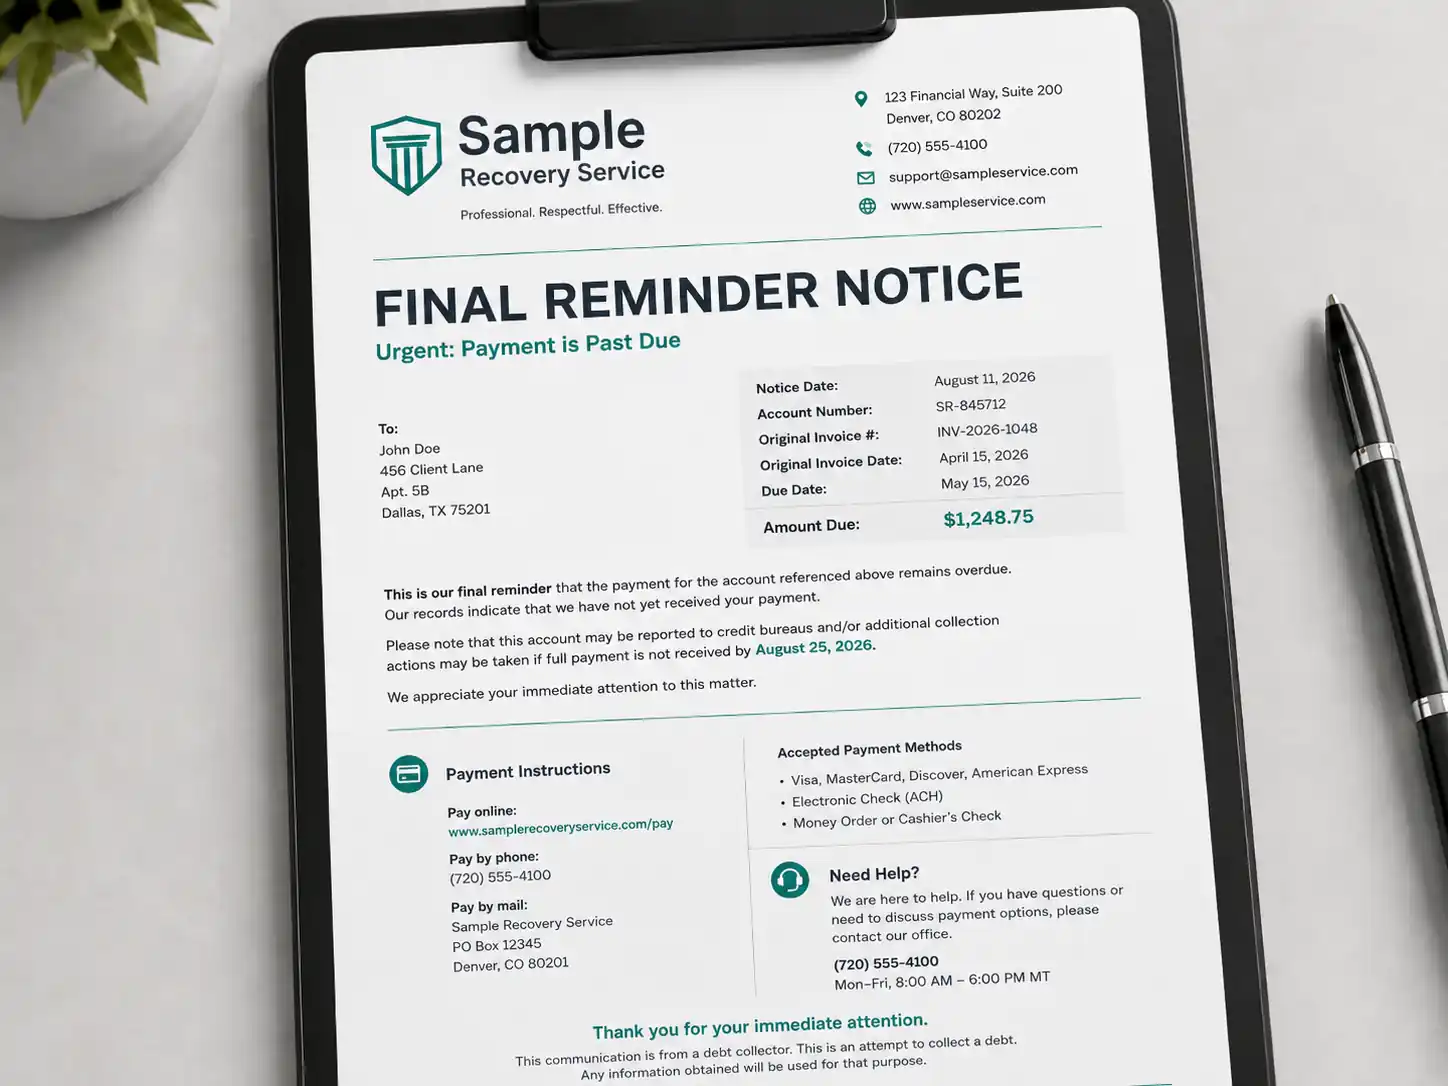
Final reminder notice from a sample collection agency showing a past-due account, amount owed, payment instructions, and contact details.

How Our Montana Collection Process Works

  1. Submit the Account: Provide debtor information, invoices, statements, contracts, and payment history through our secure portal.

  2. Review & Screen: We evaluate available documentation and identify issues such as bankruptcy or litigation risk.

  3. Professional Collection Activity: The account enters the appropriate fixed-fee or contingency collection process.

  4. Recovery & Updates: You receive account updates and recovered funds according to the selected service.

Frequently Asked Questions About Montana Debt Collection

How much does a collection agency cost in Montana?

NexaCollect offers fixed-fee collections starting around $15 per account and contingency collections for older accounts. Consumer contingency service is typically 40%, while commercial B2B rates can vary depending on balance size, account age, and complexity.

How long can a business pursue a debt in Montana?

It depends on the obligation. Montana currently provides six years for actions founded on a written instrument and five years for certain contracts, accounts, or promises not founded on a writing (MCA § 27-2-202). Other limitation periods may apply depending on the account.

When should a Montana business send an account to collections?

Businesses generally benefit from addressing unpaid accounts before they become severely aged. If normal invoices, reminders, and follow-up attempts are no longer producing payment, professional collection activity can reduce the time employees spend chasing the same balance.

Can NexaCollect handle medical collections in Montana?

Yes. Medical accounts are handled using patient-sensitive collection practices designed to protect provider relationships while following applicable privacy, consumer-protection, and collection requirements.

Can a Montana business collect from a debtor in another state?

Yes. Nationwide collection capability can simplify recovery when a Montana company’s customer or debtor is located in another state, subject to applicable collection requirements.

Does NexaCollect report accounts to credit bureaus?

Credit reporting may be available for eligible accounts when permitted under applicable laws and credit bureau policies. Medical debt requires additional care because applicable reporting requirements and bureau policies can differ.

What documents should I provide to start collections?

Useful documentation includes accurate debtor contact information, invoices, statements, contracts or agreements, payment history, and records of previous collection attempts. Complete documentation helps a collection agency evaluate and work the account efficiently.


Ready to Recover Past-Due Accounts in Montana?

Stop spending valuable staff time chasing the same unpaid invoices. NexaCollect can help you choose a cost-effective collection approach based on the age, type, and complexity of your accounts.

Start Recovering Your Montana Receivables Today


Popular cities:

  • Missoula
  • Helena
  • Great Falls
  •  Havre
  • Kalispell
  • Miles City

Collection Agency in Missouri for Businesses, Schools & Medical Practices

Nexa provides professional debt collection services for businesses, medical practices, schools and organizations throughout Missouri, including St. Louis, Kansas City, Springfield and Columbia. We recover commercial and consumer accounts using compliant, reputation-focused collection methods, with fixed-fee and contingency options available. Our nationwide collection capabilities include skip tracing, bankruptcy screening, litigation review and credit reporting for eligible accounts.

Good collection agency for a Missouri business

Nexa provides reputation-safe, equipped with all 50-state collections license, offering free credit reporting, free litigation/bankruptcy scrubs, and zero onboarding fees. Secure – SOC 2 Type II & HIPAA compliant.

Need a Collection Agency? Contact us


Why Missouri Businesses Choose Nexa

Missouri businesses face unique cash flow challenges across diverse industries—from agriculture and manufacturing to healthcare and professional services. Partnering with a professional collection agency helps creditors reclaim overdue revenue without sacrificing customer relationships or corporate reputation.

NexaCollect serves as an extension of your accounts receivable department. Our approach focuses on diplomatic, professional communication that encourages prompt resolution. Whether you manage a private medical practice in St. Louis or a commercial supply company in Kansas City, our streamlined debt recovery programs provide:

  • Transparent Pricing Options: Choose between a low fixed-fee model or competitive contingency-based recovery.

  • Reputation Protection: Firm, respectful outreach designed to protect your brand image and customer goodwill.

  • Multistate & Nationwide Coverage: Collect from debtors who have relocated outside Missouri while remaining fully compliant with interstate regulations.

  • Advanced Recovery Tools: Access to sophisticated skip tracing, account monitoring, and credit bureau reporting for eligible accounts.

Debt Collection Costs for Missouri Businesses

Understanding collection agency fees shouldn’t be complicated. NexaCollect offers flexible pricing structures tailored to the age, volume, and type of accounts you need to recover.

1. $15 Fixed-Fee Collection Option

For early-stage delinquencies (typically 30 to 90 days past due), our fixed-fee program allows creditors to send professional demand letters for a flat fee of $15 per account.

  • 0% Commission: Your business keeps 100% of all recovered payments.

  • Direct Payments: Debtors are directed to pay your business directly.

  • Early Intervention: Resolves past-due balances quickly before they require intensive recovery efforts.

2. Contingency Collection Option

For aged, uncontactable, or complex accounts, our contingency option provides performance-based debt recovery.

  • No Recovery, No Fee: You only pay a percentage fee if we successfully collect funds on your behalf.

  • Full-Service Recovery: Includes advanced skip tracing, phone outreach, and customized resolution plans.

Note: Please verify current contingency fee schedules with a NexaCollect account representative to ensure alignment with your specific account portfolio.

Need help recovering past-due accounts in Missouri?
Contact Nexa to discuss your accounts and collection options.


Missouri Debt Collection Laws: Key Points for Creditors

Creditors operating in Missouri must ensure their debt recovery strategies align with federal guidelines and relevant state statutes. Utilizing a compliant collection agency helps protect your organization from regulatory risks.

Statute of Limitations

In Missouri, the statutory time limit for enforcing debts depends on the nature of the underlying obligation and documentation:

  • Written Contracts for Payment of Money: Certain actions based on writings for the payment of money or property may fall under Missouri’s 10-year limitation period under RSMo §516.110.

  • Open Accounts and General Contracts: Other contractual obligations, including open book accounts and store accounts, generally fall under the 5-year limitation period under RSMo §516.120.

Determining the applicable limitation period depends heavily on specific account facts and contract documentation.

Wage Garnishment

When a debt is reduced to a legal judgment, Missouri law limits the amount of an employee’s disposable earnings that may be subjected to garnishment under RSMo §525.030. Calculations take into account statutory thresholds aligned with the federal minimum wage. Additionally, statutory protections may apply to qualifying Missouri residents who qualify as heads of a family.

Attorney Fees

Contractual or statutory attorney fees may be recoverable in certain qualifying cases—such as specific written contracts or promissory notes—when explicit contractual terms and statutory requirements are satisfied. Attorney fee recovery is not automatic in every debt collection scenario and depends on individual account agreements.

Medical and Consumer Accounts

Collecting consumer and medical debt in Missouri requires strict adherence to federal protections, including the Fair Debt Collection Practices Act (FDCPA), Regulation F, and the Health Insurance Portability and Accountability Act (HIPAA). Debt recovery strategies must balance effective resolution with rigorous data privacy and patient confidentiality standards.

Note: Requirements can vary by account and circumstances.


Industries We Serve in Missouri

NexaCollect delivers tailored debt recovery solutions designed for the specific commercial realities of Missouri’s key economic sectors.

Medical & Healthcare Collections

Patient responsibility balances continue to rise with high-deductible healthcare plans. As a specialized Missouri medical collection agency, we provide HIPAA-compliant, reputation-conscious outreach to resolve patient balances, co-pays, and deductibles while preserving patient trust for healthcare practices and regional clinics.

Commercial and B2B Collections

B2B debt recovery requires a sophisticated, diplomatic approach to protect valuable trade relationships. Our commercial collection agency Missouri team handles defaulted supply line invoices, unpaid vendor receivables, and trade contract balances efficiently across St. Louis, Kansas City, and regional commercial hubs.

Small Business Debt Collection

Unpaid invoices severely disrupt local cash flow. As a trusted small business collection agency Missouri partner, we help local service providers, retailers, and trade specialists collect outstanding debts without paying exorbitant commission fees.

Schools, Colleges & Universities

Educational institutions face delicate balances when collecting past-due tuition, lab fees, and housing accounts. We provide respectful, clear communication methods that resolve educational debts while respecting student and alumni relationships.

Construction & Contractor Collections

Delayed payments on trade materials, progress billings, and subcontractor work stall active job sites. Our construction debt collection Missouri specialists understand mechanics’ lien timelines and trade payment structures to help contractors recover earned revenue.

Banks & Credit Unions

We assist financial institutions with early-stage delinquencies, charged-off accounts, and deficient balance recoveries while adhering to strict banking privacy and regulatory standards.

Logistics & Transportation Collections

Freight short-pays, fuel surcharge disputes, and unpaid bills of lading demand rapid attention. We help Missouri logistics providers and freight brokers recover unpaid transport invoices quickly.

Professional Services

Accounting firms, legal practices, marketing agencies, and consulting firms rely on NexaCollect to collect unbilled retainers and aged invoices diplomatically, ensuring professional client boundaries are respected.

How Our Missouri Debt Collection Process Works

Recovering past-due accounts with NexaCollect is straightforward and efficient:

  1. Submit Accounts

    Client provides account details, outstanding invoices, statements, debtor contact details, and relevant supporting contract documentation through our secure client portal.

  2. Account Review

    NexaCollect reviews the debt documentation, performs initial data verification, and determines the appropriate, compliant collection approach.

  3. Professional Collection Activity

    Collection specialists initiate contact with debtors using firm, compliant, and reputation-conscious outreach methods across written and verbal channels.

  4. Recovery & Reporting

    Clients receive regular status updates and transparent reporting, receiving recovered funds promptly according to their selected collection program option.

Recent Recovery – Client Case Study

Regional Property Restoration Provider

  • Challenge: A Missouri property mitigation firm accumulated 140 past-due accounts totaling $84,000 in uncollected property owner insurance deductibles and self-pay balances.

  • Solution: The business submitted the accounts into NexaCollect’s $15 fixed-fee recovery program to initiate diplomatic demand outreach.

  • Result: Within 35 days, 98 accounts were successfully resolved, recovering $58,800 in cash flow while allowing the client to retain 100% of their recovered principal for a flat fee cost of under $2,100.

Related Debt Collection Services

  • Medical Collection Agency

  • Commercial Collection Agency

Frequently Asked Questions About Missouri Debt Collection

What is the best collection agency for a Missouri business?

The best collection agency depends on your business needs, account volume, and industry type. Look for an agency with transparent fees, multistate capabilities, strong regulatory compliance, robust reporting tools, and a proven track record of protecting client reputations.

How much does a collection agency charge in Missouri?

Collection costs depend on the service model you choose. NexaCollect offers a $15 fixed-fee option per account where clients keep 100% of recovered funds, as well as a traditional contingency model where fees are charged as a percentage of funds successfully collected.

When should a Missouri business send an account to collections?

Most businesses benefit from placing accounts between 60 and 90 days past due. As accounts age past 90 days, the statistical probability of full recovery declines significantly.

How long can a debt be collected in Missouri?

Statutes of limitations in Missouri depend on the type of debt and documentation. Actions on certain written agreements for the payment of money may fall under a 10-year limit (RSMo §516.110), while open accounts and general contracts typically fall under a 5-year limit (RSMo §516.120).

Can a collection agency collect B2B debt in Missouri?

Yes. NexaCollect routinely recovers commercial debts, including unpaid trade invoices, commercial lease balances, vendor contract defaults, and professional service retainers across Missouri.

Does NexaCollect handle medical collections in Missouri?

Yes. We provide specialized, HIPAA-compliant medical debt collection for practices, outpatient clinics, and healthcare networks, prioritizing patient privacy and practice reputation.

Can a Missouri collection agency report debts to credit bureaus?

Eligible accounts may be reported to major credit bureaus when legally permissible, subject to applicable federal regulations, consumer disclosure requirements, and credit bureau reporting policies.

Does NexaCollect serve Kansas City and St. Louis?

Yes. NexaCollect serves businesses across St. Louis, Kansas City, Springfield, Columbia, St. Charles, Independence, and rural commercial communities statewide.

Can NexaCollect collect from debtors outside Missouri?

Yes. NexaCollect maintains nationwide collection capabilities to recover past-due accounts from individuals or business entities that have relocated outside Missouri.

What information should I provide to start debt collection?

To achieve optimal recovery results, provide complete debtor contact information, itemized invoices, account statements, signed contracts or service agreements, payment histories, and records of prior internal collection attempts.

Ready to Recover Your Past-Due Missouri Accounts?

Stop letting overdue receivables stall your business growth. Contact NexaCollect today to learn how our transparent, reputation-focused collection programs can restore your cash flow.

Get Started with NexaCollect Today


Popular Cities:

  • St. Charles
  • Hazelwood
  • Chesterfield
  • Fenton
  • North Kansas City, Missouri
  • St. Joseph
  • St Louis
  • Washington
  • Springfield
  • Columbia

Licensed Debt Collection Agency for Minnesota Businesses & Institutions

Quick Summary: Recovering overdue accounts in Minnesota requires balancing state licensing through the Minnesota Department of Commerce (Minn. Stat. §§ 332.31–332.44) with firm, respectful outreach. Nexa Collections gives Minnesota commercial suppliers, schools, restoration firms, alarm providers, and healthcare practices a soft $15 Fixed Fee Service per account (0% commission), allowing you to recover delinquent accounts while keeping 100% of your principal.

🛡️ Minn. Stat. § 332.33 Licensed | ⚖️ MN Dept. of Commerce Registered | 🏷️ $15 Fixed Fee Service | ⭐️ 4.85/5 Rated

Collection agency in Minnesota serving Minneapolis, St. Paul, Rochester, and Duluth

In Minnesota, from the medical technology corridors of the Twin Cities and the industrial centers of Duluth to the agricultural economies of Rochester and St. Cloud, doing business takes a balance of “Minnesota Nice” and legal precision. The Minnesota Debt Fairness Act reshaped what actually works here: medical debt can no longer be reported to credit bureaus, the first $4,000 in a debtor’s bank account is shielded, and garnishment now scales with income instead of running at a flat rate. Agencies still relying on credit-report pressure are working with a tool this state largely took away.

Nexa provides reputation-safe, equipped with all 50-state collections license, offering free credit reporting, free litigation/bankruptcy scrubs, and zero onboarding fees. Secure – SOC 2 Type II & HIPAA compliant. Backed by a responsive client support team.

Need a Collection Agency? Contact us


Cost-Effectiveness: The Nexa Advantage

Nexa Collections fixed-fee and contingency pricing for Minnesota businesses

  • $15 Fixed Fee Service: Best for early-stage defaults, roughly 30–90 days past due. A flat $15 per account, 0% commission, and the debtor pays you directly, so you keep 100% of recovered principal. See the full pricing breakdown.
  • Contingency Recovery (20%–40%): For aged accounts, unreachable debtors, and skip-trace situations. No recovery, no fee.

What $50,000 in Delinquent Minnesota A/R Actually Nets You

A static example on a $50,000 delinquent portfolio, assuming an 80% eventual recovery rate ($40,000 collected):

Nexa $15 Fixed Fee Service Traditional 40% Contingency
Amount recovered $40,000 $40,000
Fee (50 accounts × $15) $750 $16,000 (40% of recovered)
You keep $39,250 (98.1%) $24,000 (60%)

Industries We Serve in Minnesota

  • Commercial (B2B): Manufacturing suppliers, agri-business supply chains, and B2B trade lines across Minneapolis, St. Paul, and Rochester, including freight brokerage, warehousing, and fabrication disputes where a single invoice can carry real weight.
  • Schools & Educational Institutions: Tuition balances, private school fees, vocational training fees, and higher education student accounts, handled with a student-first tone that protects enrollment relationships in tight-knit school communities.
  • Restoration Companies: Property mitigation invoices, water and fire restoration balances, and uncollected insurance deductibles, resolved before adjuster delays harden into a standoff with the homeowner.
  • Small Businesses: Professional services, local trade contractors, and commercial vendors statewide, where one unpaid invoice is a genuine cash-flow event rather than a rounding error.
  • Alarm & Security Companies: Recurring monthly monitoring contracts, equipment installment balances, and service defaults, recovered without the local-reputation damage this referral-driven industry can’t afford.
  • Healthcare & Medical Practices: HIPAA-compliant patient balance recovery for co-pays, high-deductible remainders, and outpatient clinic accounts, under signed BAAs and built entirely around mediation rather than credit reporting, which Minnesota law now restricts anyway.

Real-World Recovery Results

Property Restoration (Minneapolis / St. Paul, MN)

140 uncollected insurance deductible accounts totaling $84,000 placed. Recovered $58,800 in 35 days using the $15 Fixed Fee Service for under $2,100 in total fees, saving over $21,000 versus a 40% contingency arrangement.

Commercial Equipment Supplier (Rochester / Duluth, MN)

$92,000 in defaulted B2B supply invoices across 30 accounts. Diplomatic Fixed Fee outreach recovered $64,400 across 21 accounts in under 40 days, with zero Department of Commerce disputes.


Minnesota Legal & Regulatory Compliance

Minnesota changed the rules meaningfully in 2024–2025, and several of those changes cut directly against how traditional agencies operate.

Debt Category Statute of Limitations Minnesota Statute
Written & Oral Contracts 6 Years Minn. Stat. § 541.05
Consumer Debt (non-revivable) 6 Years, permanently Minn. Stat. § 541.053
Medical Debt Reporting Restricted Minnesota Debt Fairness Act / Ch. 332C
Wage Garnishment Allowed (income-based sliding scale) Minn. Stat. § 550.37
Judgments 10 Years (Renewable) Minn. Stat. § 541.04

What actually matters in practice:

  • Consumer debt can’t be revived here. Under Minn. Stat. § 541.053, once the six-year window on a consumer debt closes, “the statute of limitations is not revived by the collection of a payment.” A partial payment does not restart the clock, which is the opposite of how states like Michigan work. Collectors who assume a token payment buys more time are wrong in Minnesota, and acting on that assumption creates real exposure. It also means early placement matters more here than in revival states.
  • Every letter has to say who licenses us. Minn. Stat. § 332.37 requires written collection correspondence to carry the disclosure “This collection agency is licensed by the Minnesota Department of Commerce.” It’s a small detail that out-of-state template letters routinely miss, and it’s a compliance defect on its face.
  • The medical reporting ban is real, but not necessarily permanent. Minnesota restricts medical debt on consumer credit reports, and that’s in force today. Worth knowing: in October 2025 the CFPB stated that federal law (FCRA) may not permit states to ban medical debt from credit reports at all, an unresolved question affecting Minnesota and roughly a dozen other states. Nothing has overturned Minnesota’s law. But we build medical recovery on mediation and judicial remedies rather than credit-report leverage, which means the strategy holds regardless of how that question lands.
  • The $4,000 bank shield. The last $4,000 in a debtor’s account is protected. Asset-location scrubbing identifies genuinely solvent debtors before you spend on legal escalation.
  • Sliding-scale garnishment. Garnishment now scales with income rather than running flat, protecting lower-wage earners entirely. Filing on the old flat assumption gets orders rejected.
  • No unauthorized fees. Minn. Stat. § 332.37 also bars collecting interest, fees, or expenses not authorized in the original contract, so what your agreement actually says governs what’s collectable.

We operate under active Minnesota Department of Commerce licensing (Minn. Stat. § 332.33), full FDCPA and CFPB Regulation F compliance, SOC 2 Type II data security, and signed Business Associate Agreements on every medical account.


Frequently Asked Questions

Is Nexa licensed by the Minnesota Department of Commerce?

Yes. Minnesota requires collection agencies to be licensed by the Department of Commerce under Minn. Stat. § 332.33, and registered collectors must be individually registered with the commissioner. Minnesota also requires our written correspondence to state that we’re licensed by the Department of Commerce, a disclosure built into our letters rather than added as an afterthought.

How does the $15 Fixed Fee Service help Minnesota restoration companies collect unpaid deductibles?

A restoration deductible goes stale fast: the emergency is over, the adjuster has moved on, and the homeowner’s urgency evaporates. A professional demand letter sent while the balance is fresh resolves a meaningful share of these before the account hardens into a dispute. At $15 flat, with the homeowner paying you directly, you keep 100% of what comes back, which matters when the deductible itself may only be a few thousand dollars.

Can private schools and educational institutions in Minnesota use Nexa to recover overdue tuition?

Yes, and tone genuinely determines the outcome here. Families may re-enroll, and they talk to other families, so outreach stays professional and solution-oriented rather than confrontational. That approach resolves the balance while protecting enrollment relationships, which are usually worth more than the individual account.

How does Minnesota’s 6-year statute of limitations affect B2B debt recovery?

Most written and oral contract claims get six years under Minn. Stat. § 541.05. The critical wrinkle is on the consumer side: under § 541.053, an expired consumer debt cannot be revived by a later payment. A collector used to states where partial payment restarts the clock will get this wrong. For B2B accounts especially, the practical takeaway is to place early rather than assuming a future payment will buy back time.

How does diplomatic outreach protect alarm and security companies from bad Google reviews?

Alarm companies live on neighborhood referrals, so a single hostile collection call can cost more than the monitoring contract was worth. Most negative reviews trace back to a confrontational phone exchange, not to receiving a professional written notice. Resolving the balance through a calm, formal letter keeps the dispute private, which is usually the whole point.


Contact us for Collections

Popular cities:

  • Ham Lake
  • Coon Rapids
  • St. Paul
  • Eden Prairie
  • Minneapolis
  • Montrose
  • Anoka
  • Cambridge
  • Plymouth
  • Champlin
  • Coon Rapids
  • Albert Lea
  • Alexandria
  • « Go to Previous Page
  • Page 1
  • Interim pages omitted …
  • Page 23
  • Page 24
  • Page 25
  • Page 26
  • Page 27
  • Go to Next Page »

Primary Sidebar


accounts receivable

Need a Collection Agency?
Kindly fill this form.
We’ll get in touch with you

    Please prove you are human by selecting the flag.

    Compliance & Security

    • SOC 2 Type II Certified: Third-party audited data security and strict privacy controls.

    • HIPAA Compliant: Secure, legal processing of medical and municipal EMS accounts.

    • PCI-DSS Level 1: Highest tier of data encryption for secure payment processing.

    • FDCPA & FCRA Aligned: Full legal adherence to federal consumer protection laws.

    Recent Posts

    • Nationwide Debt Collection Agency Serving U.S. Cities
    • Chula Vista Collection Agency for Medical, B2B, Schools & Business Debt
    • Corpus Christi Collection Agency: Itemized Bill Rules for Practices
    • Riverside Collection Agency | For Logistics, Medical, Schools & Business Recovery
    • Collection Agency for Large Balances: High-Value B2B Debt Recovery
    • Baltimore Collection Agency | Medical, Commercial, Schools & More
    • Commercial and B2B Collection Agency in Detroit
    • Boston Medical Collection Agency | Serving Hospitals, Physicians & Dentists

    Featured Posts

    • Recommendations for Debt Collectors Working from Home
    • How Debt Collectors Recover Money From Debtors on Phone?
    • Maryland Medical Collections: Local Expertise for Healthcare Providers

    Copyright © 2026 NEXACOLLECT.COM | This content is provided for general informational purposes only and should not be considered legal advice. Collection laws and requirements may vary by state, account type, documentation, debtor status, and specific facts. Please consult qualified legal counsel for guidance regarding your particular situation. Nexa and its authorized collection partners service accounts in accordance with applicable federal and state collection requirements. Visit our home page to know more about us.

    X
    Need a Collection Agency?
    Contact Us