• Skip to main content
  • Skip to primary sidebar

Nexa Collections

  • Home
  • Serving
    • Medical
    • Dental
    • Small Business
    • Large Business
    • Commercial Collections
    • Government
    • Utilities
    • Fitness Clubs
    • Schools
    • Senior Care Facility
  • Contact Us
    • About us
    • Cost

Search Results for: the bureaus

Kinum Inc – Debt Collection Agency

Directory >> USA >> Virginia  >>Virginia Beach >> Kinum Inc

The Kinum Complete System includes two phases: Connect and Collect.

These services include Friendly 1st party reminders, Third-party reminders, Contingency collections and Legal intervention.

Kinum’s two-phase process begins by establishing a connection with the debtor through respectful and consistent communication. This initial phase aims to recover debts through friendly reminders rather than confrontational demands. If this softer approach does not yield results, the collection phase escalates efforts, while still aiming to preserve the relationship between the client and their customer.

Unused connect (written demands) accounts never expire and cost between $10 to $25 per account based on number of accounts you buy.

Their service includes bankruptcy check, change of address check and litigious debtor scrubs. Option report unpaid debts to credit bureaus. We noticed that Kinum Collections has a pretty good rating online, unusual for a collection agency. They are licensed to collect in all 50 states and Puerto Rico.

Address:
8200 Haverstick Rd., Ste. 220
Virginia Beach, VA 23452

Phone:
(888) 471-0280

Fax:
(877) 504-3190

Email:
kinum.com

Got a Letter or Call from Kinum?
Please visit Kinum.com and use the “Pay a debt” link to make a payment.

Website:
www.kinum.com

Source of information / References:
kinum.com/collecting-accounts-receivables/
kinum.com/contact-us/
apsmemberservices.com/apswebforms/client/kinum/

Make changes to this page? or Add a new collection agency listing?
If you own this collection agency and there is a need to update information presented on this page, kindly email us at  “directory@NexaCollect.com”

Nexacollect.com has shortlisted Kinum as one of the agencies which it recommends for collections service. Kinum is primarily recommended for schools and medical collections.

Information presented about this collection agency may not be 100% accurate or may have changed since we created this page. Kindly visit the agency’s website for the most up to date information.

Calabasas Debt Collection Agency | Licensed California Recovery

Your Capital is Frozen in the 818. It’s Time to Thaw the Ledger.

Calabasas is a global brand for a reason. From the high-tier professional suites at The Commons to the tech-focused corporate hubs along the Ventura Corridor, business here is defined by high stakes and high expectations.

But there is a specific “Calabasas Problem” when it comes to cash flow: The High-End Stall.

In the 818 and the neighboring Santa Monica Mountains, debtors aren’t usually broke; they are “managing.” They use your unpaid invoices to fund their own growth or lifestyle, banking on the fact that you won’t want to cause a scene in such a tight-knit, prestige-driven community.

If you are a business owner in Calabasas, you’ve likely spent months sending “courtesy reminders” that get ignored. You are being used as a zero-interest line of credit.

NexaCollect breaks that cycle. We provide a sophisticated, ultra-compliant recovery system that matches the professional caliber of Calabasas while ensuring your revenue actually hits your bank account.

Nexa provides a reputation-safe approach, equipped with all 50-state collections license, offering free credit reporting, free litigious debtor check, free bankruptcy scrub, and zero onboarding fees. Secure – SOC 2 Type II & HIPAA compliant. Over 2,000 online reviews rate us 4.85 out of 5. 

Need a Collection Agency? Contact us


The Calabasas Strategic Brief: Precision Over Pressure

1. The “Rosenthal” Minefield

California’s Rosenthal Fair Debt Collection Practices Act is arguably the strictest in the nation. One improper phone call or a poorly worded email from an untrained internal staffer can trigger a lawsuit against you.

  • The Reality: We are compliance experts. We navigate the Rosenthal Act and the latest CFPB regulations so you don’t have to. We allow you to insulate your brand from legal liability while still securing your payment.

2. Speed is the Only Leverage

The data is clear: Placing accounts earlier yields significantly better results. * The Number: Accounts placed within 60 days have a 95% higher probability of full recovery than those left to sit for 180 days.

  • The Fix: In a market where businesses can relocate or restructure overnight, waiting is your greatest risk. We engage your debtors immediately with a third-party presence that commands attention.

3. The 4.85/5.0 Reputation Standard

In Calabasas, your reputation is your currency. You can’t hire a “boiler room” agency that treats people like criminals.

  • The Fix: We hold a dominant 4.85 out of 5.0 rating because we use psychological mediation. We preserve your public image on Google and social media by resolving debts through professional negotiation rather than blunt-force harassment.


A Scalable System for Premium Portfolios

We don’t believe in taking half your money if a professional nudge can solve the problem.

The Tier The Strategy The Cost
Tier 1: Flat-Fee Demand Official third-party letters sent in our name. Perfect for the “ghosting” phase. $15 per account
Tier 2: Full Recovery Intensive skip-tracing, phone negotiation, and credit bureau reporting. 40% (Contingency)
Tier 3: Legal Enforcement 50-state attorney network for wage garnishment and bank levies. 50% (Contingency)

By utilizing our Tier 1 service, you maximize your internal resources without adding to your payroll, clearing out your A/R backlog for a fraction of the cost of a new hire.


Ventura Corridor Success Files

The Corporate Tech Dispute

  • Scenario: A software consultant near Malibu Canyon Rd was owed $28,000. The client claimed a “technicality” was holding up the wire transfer for four months.

  • Our Move: We deployed a Tier 1 ($15) demand that signaled a formal transition to third-party collections.

  • The Result: The “technicality” vanished within 48 hours. The client paid in full to avoid a mark on their corporate credit profile. Cost to Consultant: $15.

The Luxury Service Provider

  • Scenario: A high-end landscaping and design firm was owed $45,000 across multiple residential projects.

  • Our Move: Our diplomatic negotiators contacted the homeowners.

  • The Result: We recovered $32,000 in 30 days. Because our tone remained professional and elite, the firm received zero negative reviews and even maintained future service contracts with two of the debtors.


FAQ: Calabasas Intelligence

Q: Can you collect if the debtor has moved out of California?

A: Yes. We are licensed in all 50 states. If they moved to Nevada, Texas, or New York to escape the bill, our system follows them and enforces the debt under their new jurisdiction.

Q: Do you report to credit bureaus?

A: During our Contingency phase (Tier 2), we report to Equifax, Experian, and TransUnion. For many high-net-worth debtors, a credit hit is a non-starter, which often forces a settlement immediately.

Q: Is there a minimum debt amount?

A: No. Because of our $15 flat-fee model, it is finally profitable to go after those $200 and $500 balances that previously weren’t worth the effort.

Reclaim Your Working Capital

Stop acting as an unpaid bank for your clients. Partner with a recovery firm that understands the economy of Calabasas.

Would you like a free Bankruptcy & Litigious Scrub for your outstanding invoices?

Cedar Falls Collections: College Town + Manufacturing = Tricky AR

Cedar Falls is not just another small Midwestern town. It anchors the Waterloo–Cedar Falls metro, with around 40,000+ residents, and is home to the University of Northern Iowa (UNI).

The local economy leans heavily on:

  • Educational services (UNI and public schools)

  • Retail trade

  • Health care & social assistance

  • A strong regional manufacturing base in the broader Cedar Valley area

That mix translates into very specific receivables:

  • Student and housing balances (tuition, fees, damages, parking, and off-campus rentals)

  • Medical and dental AR from families and students juggling deductibles and co-pays

  • Small-business and industrial invoices tied to manufacturers and local services

If your current partner treats Cedar Falls like “just another college town,” you may be carrying more risk and more old AR than you need to.

Nexa provides a reputation-safe approach, equipped with all 50-state collections license, offering free credit reporting, free litigious debtor check, free bankruptcy scrub, and zero onboarding fees. Secure – SOC 2 Type II & HIPAA compliant. Over 2,000 online reviews rate us 4.85 out of 5. 

Need a Collection Agency? Contact us


Why Cedar Falls AR Misbehaves

Common Cedar Falls patterns:

  • Academic calendar cash flow – Tuition, housing, and fee balances spike around semester transitions.

  • Student transience – Addresses, phones, and emails change frequently, so skip-tracing and good data matter.

  • Mixed incomes – UNI staff and professionals with solid salaries alongside students and lower-wage service workers, plus a regional manufacturing workforce with overtime swings.

If your process doesn’t reflect those realities—timing contacts around semesters and paydays, adjusting tone for students vs. long-time residents—your recovery will lag.


Iowa’s Legal Framework – What Your Partner MUST Understand

Iowa adds its own layer of rules on top of federal law. Any agency handling Cedar Falls accounts should be fluent in at least three areas:

1. Iowa Debt Collection Practices Act (IDCPA)

Iowa’s Fair Debt Collection Practices provisions sit in the Iowa Consumer Credit Code, including section 537.7103 and related rules. In broad strokes:

  • They mirror and expand on federal FDCPA protections for consumer debts.

  • The Iowa Act can apply to original creditors collecting their own debts, not just third-party agencies.

  • Prohibited practices include harassment, false threats of legal action, misrepresenting amounts, or contacting consumers at obviously inconvenient times or places.

This means a Cedar Falls hospital, clinic, school, or landlord can’t simply say “IDCPA doesn’t apply—we’re not a third-party collector.” Internal and external collection behavior both matter.

2. Statute of Limitations – Longer Than Many States

Iowa’s statute of limitations rules are relatively generous to creditors:

  • Written contracts: generally up to 10 years

  • Unwritten / oral contracts & many open accounts: generally 5 years

In practice:

  • You often have a longer window to sue than in many states, especially on written agreements.

  • Collectors still cannot threaten lawsuits on debts that are actually time-barred under Iowa Code chapter 614.

  • Paperwork matters: if you’re going to rely on a long limitations period, you need clean documentation (contracts, itemization, payment history).

A good agency will track date of last payment and contract type on each file, and clearly flag time-barred or borderline accounts.

3. Garnishment & Exemptions

Iowa allows wage and bank garnishment only after a judgment—the creditor must sue and win first.

Key points:

  • Courts can issue wage-garnishment orders, but exemptions and caps apply (Iowa Code chapter 642 and related exemption rules).

  • Iowa’s exemption statute (627.6) protects certain homestead, personal property, tools, and benefits from execution.

For Cedar Falls creditors, that means:

  • Garnishment is a tool, but not a magic wand—net take-home after exemptions may be modest on lower-income debtors.

  • A smart partner uses garnishment selectively and focuses first on voluntary plans and settlements, especially for smaller balances.


Medical Debt & Credit Reporting – Moving Target

Nationally, medical-debt rules have been all over the map:

  • The major credit bureaus removed many paid medical collections and smaller balances from reports starting in 2022–23.

  • A federal rule to ban medical debt from most credit reports and from many lending decisions was finalized, then struck down by a federal judge in 2025 and never fully implemented.

Result for Iowa providers and hospitals, including Cedar Falls:

  • Credit-report threats are much weaker and less reliable than they were a few years ago.

  • Bureaus still keep some larger medical debts, but with narrower rules, longer waiting periods, and more disputes.

Effective modern agencies focus on:

  • Early outreach, clean statements, and accurate insurance posting

  • Patient-friendly payment plans and hardship options

  • Avoiding over-reliance on “we’ll hurt your credit” messaging, which is both risky and less effective.

(All of this is general information, not legal advice. Always confirm specifics with your own attorney.)


Federal Laws Still Apply in Cedar Falls

On top of Iowa law, your Cedar Falls collection partner must obey:

  • FDCPA – No harassment, false threats, misrepresentation, or unfair practices on consumer debts.

  • FCRA – Accurate credit reporting, prompt updates when accounts are paid or settled, and proper dispute handling.

  • HIPAA – For medical and dental accounts, strict PHI protection, Business Associate Agreements, and “minimum necessary” disclosure.

  • TCPA – Rules on auto-dialers, prerecorded messages, and SMS to cell phones (critical for student and younger populations).

If your agency shrugs off these acronyms, you are the one carrying the risk.


Cedar Falls Reality: Who Actually Owes You Money?

Given the local industry mix, your delinquent accounts likely cluster around:

  • Education-related debt – Tuition, dorm damage, parking fines, and other university or private-school balances.

  • Healthcare AR – Hospital, clinic, behavioral-health, dental, and specialist bills from students and long-time residents.

  • Retail and services – Mid-ticket consumer purchases, memberships, and service contracts.

  • Manufacturing & B2B invoices – Local suppliers and contractors extending terms to plants, shops, and regional businesses.

A Cedar Falls-savvy agency will:

  • Distinguish student vs. non-student accounts and adjust tone and negotiation accordingly.

  • Offer multi-channel outreach (email, text where permitted, letters, calls) to track a mobile, student-heavy population.

  • Separate consumer vs. commercial debts, so IDCPA protections and FDCPA rules are applied properly.


What a Good Cedar Falls-Focused Agency Should Deliver

For Cedar Falls accounts, your ideal partner should be able to:

  • Explain how they comply with Iowa’s Debt Collection Practices Act and federal FDCPA.

  • Show how they track 10-year vs. 5-year limitations periods, and flag debts that are approaching or past those windows.

  • Demonstrate a plan for education and healthcare heavy AR, including semester-aware outreach for student balances.

  • Provide reports that clearly separate:

    • Consumer vs. commercial accounts

    • Collectible vs. time-barred files

    • Small-balance vs. high-balance placements

Their strategy should help you:

  • Keep legal risk low while recovering more

  • Stretch your in-house billing/AR team without new hires

  • Protect your reputation in a close-knit college/manufacturing community


When It Might Be Time to Switch

It’s worth re-evaluating your current collection relationship if:

  • Recovery on Cedar Falls placements has stalled or declined

  • You’re hearing more about collector tone than about resolved balances

  • Your reports don’t clearly show which accounts are near or past Iowa’s limitation periods

  • Your agency never mentions Iowa-specific rules, IDCPA protections, or changes in medical-debt credit reporting

Those are strong signals that you’re getting a generic national approach, not something built for Iowa and the Cedar Valley.


Quick FAQ

Q: Why is collecting in Cedar Falls different from other Iowa cities?
Because you’re dealing with a college town plus a manufacturing and retail base. That means higher student churn, academic-year cycles, and a very mixed income profile. Your collection playbook has to work for both UNI students and long-time manufacturing families.

Q: Does the long 10-year statute of limitations mean I should just wait?
Not really. A longer limitations period simply preserves your right to sue for longer—it doesn’t make old debt easier to collect. In practice, accounts placed earlier with clear documentation outperform very old placements, even in Iowa.

San Diego Collection Agency for Businesses, Healthcare & Schools

San Diego businesses don’t all collect the same way—and that’s exactly why local knowledge matters.

From La Jolla biotech and medical firms to Gaslamp hospitality groups, North County contractors, schools, healthcare providers, and professional-service companies across San Diego County, overdue accounts can quickly become a drag on cash flow.

Nexa helps San Diego organizations recover unpaid balances through professional, cost-effective, reputation-safe collection strategies designed around the type and age of each account. We combine persistent follow-up, flexible payment resolution, and stronger escalation when needed—while keeping patient, customer, and business relationships in mind.

The goal is simple: recover more of what you’re owed without putting your brand, customer relationships, or hard-earned reviews at risk.

San Diego collection agency helping businesses, healthcare providers and schools recover overdue accounts
Nexa provides  reputation-safe, equipped with all 50-state collections license, offering free credit reporting, free litigious debtor check, free bankruptcy scrub, and zero onboarding fees. Secure – SOC 2 Type II & HIPAA compliant. Over 2,000 online reviews rate us 4.85 out of 5. 

Need a San Diego Collection Agency? Contact us


Why San Diego Businesses Choose Us

We know that every dollar matters. Our process is built to maximize your recovery while minimizing your risk and stress.

  • Protecting Your Reputation is Our Priority
    We are not an old-school collection agency. We are professional revenue partners. Our team is trained in empathetic, respectful communication. We resolve accounts in a way that protects your customer relationships and your public reputation.
  • Cost-Effective with Proven Results
    We operate on a contingency-based model. If we don’t collect, you don’t pay. This makes our service a truly cost-effective solution, aligning our success with yours. Our blend of advanced technology and skilled specialists delivers results.
  • Nationwide Coverage, Local Service
    While our roots are deep in Southern California, our reach is national. We are fully licensed and insured to collect in all 50 states and Puerto Rico, giving you a single, compliant partner for all your accounts.
  • Ironclad Compliance
    You don’t need to be an expert in debt collection law—that’s our job. We ensure 100% compliance with all federal laws (like the FDCPA) and California’s specific regulations, including the Rosenthal Act.

Industries We Serve in San Diego

Serving Businesses Across San Diego County: NexaCollect provides tailored commercial and medical debt recovery across all major regional hubs, including the Torrey Pines & UTC biotech cluster, Sorrento Valley tech corridor, Downtown San Diego, Mission Valley, and Carlsbad & North County.

We have proven expertise across San Diego’s key industries:

  • Healthcare: (Biotech, Medical Device, Dental Practices, Clinics)
  • Property Management: (HOAs, Apartment Complexes)
  • Business to Business (B2B): (Defense Contractors, Tech Startups)
  • Small Business
  • Hospitality & Tourism
  • Education & Private Schools
  • Utilities & Services

Local Results for Local Businesses

We recently helped a healthcare provider near Balboa Park recover $220,000 in past-due patient accounts in 90 days, all while maintaining their high patient satisfaction scores. For a B2B tech firm in Sorrento Valley, we successfully resolved 80% of their aged receivables, providing a critical cash flow boost.

Our Simple 4-Step Recovery Process

collection agency fee

  1. Step 1: Secure Account Review
    You securely place accounts through our easy-to-use online portal. Our team immediately reviews them for compliance and accuracy.
  2. Step 2: Professional & Compliant Outreach
    We initiate respectful, multi-channel communication (letters, calls, and emails) that is fully compliant with all state and federal laws.
  3. Step 3: Resolution and Negotiation
    Our trained specialists work with individuals to find amicable solutions. We are experts at negotiating payment plans that get your accounts resolved.
  4. Step 4: Recovery & Remittance
    We process payments securely and remit the funds directly to you. You have 24/7 access to our portal for real-time status updates.

A Client’s Guide to California Collection Laws

We handle all compliance, but here are the key laws clients should know:

  • The Rosenthal Fair Debt Collection Practices Act:
    This is California’s state-level law. It mirrors many federal FDCPA rules but also applies them directly to original creditors, not just third-party agencies. It sets strict rules on communication and prohibits any unfair or deceptive practices.
  • California Consumer Privacy Act (CCPA):
    This law governs data privacy and security. We manage all data with the highest level of security, ensuring your business and your customers’ information is protected.
  • Statute of Limitations:
    In California, the time limit to file a lawsuit to recover most debts (based on a written contract) is four years.

Frequently Asked Questions in SD

1. What types of San Diego businesses and organizations can Nexa help with collections?

Nexa helps medical and dental practices, biotech and medical-device companies, technology firms, defense contractors, schools, property managers, HOAs, hospitality businesses, professional firms, and other San Diego organizations recover overdue accounts. This industry-specific approach is particularly relevant in San Diego, where life sciences, technology, military and defense, manufacturing, tourism, and international trade are major parts of the local economy.

2. Can San Diego medical and dental providers still send unpaid patient balances to collections if California prohibits medical debt credit reporting?

Yes. California’s prohibition on furnishing medical debt to consumer credit reporting agencies does not prohibit legitimate medical debt from being professionally collected. Under SB 1061, medical debt generally cannot be furnished to consumer credit bureaus, and contracts creating medical debt on or after July 1, 2025 must contain specific statutory language. San Diego hospitals, physicians, dentists, clinics, imaging centers and other healthcare providers can therefore still pursue valid patient balances, but the collection strategy must comply with California’s medical-debt requirements.

3. How do California’s newer small-business debt rules affect B2B collections in San Diego?

California expanded the Rosenthal Fair Debt Collection Practices Act beginning July 1, 2025 to cover certain commercial debts involving natural-person debtors or guarantors where qualifying commercial credit is $500,000 or less. This does not mean every corporate invoice is treated like consumer debt, but it does mean some small-business and personally guaranteed obligations now require additional care. That can be particularly relevant for San Diego’s startups, professional firms, contractors, technology companies and other owner-operated businesses.

4. Why does military experience matter when collecting debts in San Diego?

San Diego has one of the country’s largest concentrations of military and defense activity, so creditors are more likely to encounter accounts involving active-duty servicemembers. The federal Servicemembers Civil Relief Act (SCRA) provides qualifying servicemembers with protections involving matters such as certain pre-service interest rates, repossessions and default judgments. Military status therefore becomes especially important when an account may require legal escalation rather than ordinary collection outreach.

5. Does a collection agency handling San Diego accounts need to be licensed in California?

Generally, a company engaging in debt collection in California must comply with the state’s Debt Collection Licensing Act and DFPI oversight requirements, subject to statutory exemptions. California also imposes collection-conduct requirements through laws such as the Rosenthal Act. Using a properly authorized and compliance-focused partner is particularly important for San Diego businesses handling consumer, medical or qualifying small-business accounts.

6. Can Nexa collect accounts for a San Diego business when the customer or debtor has moved outside California?

Yes. San Diego businesses frequently have customers, patients and commercial accounts that extend beyond Southern California. Nexa provides nationwide collection coverage and states that it is licensed and insured to collect across all 50 states and Puerto Rico, allowing a San Diego organization to use one recovery partner for both local and out-of-state accounts. The applicable collection requirements can vary depending on where the debtor resides and the type of account.

Need a Collection Agency? Contact us


About San Diego

  • Hub: Biotech/life sciences, defense/aerospace, wireless/telecom, tourism, clean energy.

  • Notables: Qualcomm, Illumina, Dexcom, ResMed, General Atomics, Sempra, WD-40, Petco.

  • Big employers: U.S. Navy & Marine Corps, UC San Diego, Sharp HealthCare, Scripps Health, SD Unified School District, Qualcomm.

  • Famous for: Beaches & surf, Balboa Park/San Diego Zoo, La Jolla, Comic-Con, near-perfect weather.


Norfolk Debt Collection for Maritime, Healthcare & Businesses

Norfolk’s economy moves through contracts, cargo and command structures. Your receivables should not get stuck between them.

Few cities have Norfolk’s mix of commercial complexity. The city is home to the world’s largest naval base, the Port of Virginia, a deep concentration of shipbuilding and marine-service companies, major healthcare systems, Old Dominion University, logistics operators, defense contractors and advanced manufacturers. Norfolk Economic Development specifically identifies maritime, transportation, logistics, healthcare, life sciences, technology and advanced manufacturing as core industries.

That means an overdue account might involve a vessel repair, a disputed demurrage charge, a university balance, a government purchase order, a medical account or a defense-related subcontract.

Don’t let your revenue sit at anchor while your business tries to move forward.

Nexa brings structure to those receivables without bringing unnecessary friction to the relationship. We combine reputation-safe recovery, a $15 fixed-fee option for newer accounts, contingency collections for tougher balances, 100% HIPAA-compliant healthcare workflows and nationwide reach.

In a city built around moving ships, cargo and missions on schedule, your cash flow should move with the same discipline.

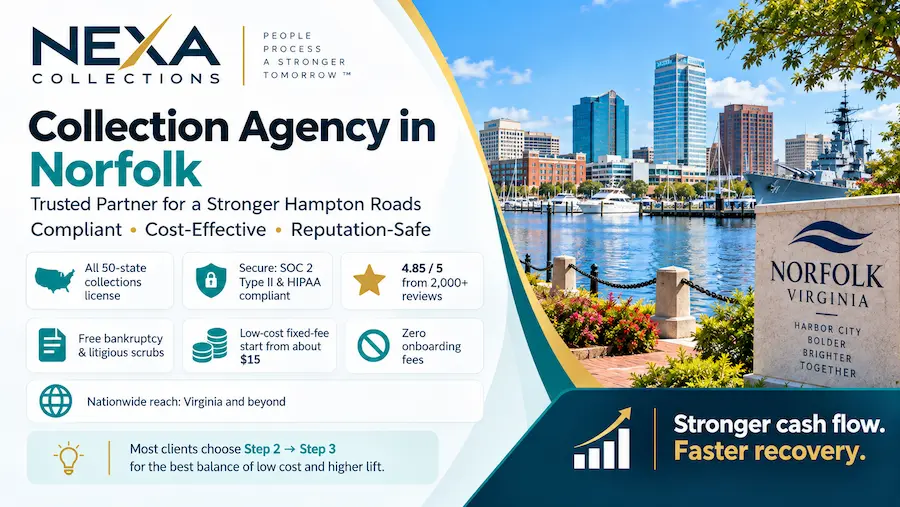
Norfolk Virginia waterfront with USS Wisconsin and downtown skyline representing maritime, defense, healthcare and commercial debt recovery

Nexa provides a reputation-safe approach, equipped with all 50-state collections license, offering free credit reporting, free litigious debtor check, free bankruptcy scrub, and zero onboarding fees. Secure – SOC 2 Type II & HIPAA compliant. Over 2,000 online reviews rate us 4.85 out of 5. 

Need a Norfolk Collection Agency? Contact us


Recent Recovery Results:

Marine Electronics Supplier — Fixed Fee | 94% Recovered
A Hampton Roads supplier placed $11,000 in fresher vessel-service invoices. Follow-up recovered $10,340 — 94%.

Commercial B2B Collections

Healthcare Staffing Company — Contingency | 82% Recovered
A Norfolk-area healthcare vendor assigned $28,000 in aging facility invoices. Recovery produced $22,960 — 82%.

Medical Collection Services

Government IT Subcontractor — Contingency | 70% Recovered
A regional technology firm placed $40,000 in completed-project receivables. Documentation-led recovery returned $28,000 — 70%.

Government Collection Services


Our 4-Step Engine for Maximum Recovery


We use a systemic approach that escalates pressure only when necessary.

  • Step 1: First-Party Outreach ($15/account) We send courteous reminders under your name. It looks like it came from your billing department. This is perfect for early-stage delinquency where a simple nudge works best.

  • Step 2: Third-Party Demands ($15/account) We switch to our name. The debtor receives a formal demand letter. This psychological shift often motivates immediate payment to prevent credit score damage. Most Norfolk clients see the best ROI here.

  • Step 3: Contingency Collections (40% fee) If they still refuse to pay, we launch a full investigation. We use advanced skip-tracing to find debtors who may have moved out of Downtown. We only get paid if we collect.

  • Step 4: Legal Action (50% fee) For high-value debts where assets are available, our legal network reviews the case for litigation. We handle the heavy lifting; you make the final call.


Norfolk Debt Recovery FAQ:

Can a Norfolk ship repairer or marine supplier place a lien on a vessel that has not paid its invoice?

Potentially, yes.

Federal maritime law generally gives a party that provides “necessaries” to a vessel on the order of the owner or another authorized person a maritime lien on the vessel. Necessaries can include qualifying repairs, supplies, towage and other services needed by the vessel. The claimant may potentially bring an in-rem action against the vessel to enforce the lien.

There is an important Norfolk-specific exception: this federal maritime-lien provision does not apply to a public vessel, so work involving a Navy or other government vessel needs to be analyzed differently.

For collection, preserve the vessel name and official number, work authorization, repair orders, parts invoices, delivery records, master or owner approvals and payment history.

Commercial B2B Collection Services


A Port of Virginia customer disputes demurrage or detention charges. Who can legally be billed, and how quickly?

Federal Maritime Commission rules are unusually specific.

A vessel-operating common carrier or marine terminal operator generally must issue qualifying detention or demurrage invoices within 30 calendar days after the charges were last incurred. An NVOCC generally has 30 days from the date of the underlying invoice it received.

The invoice generally can be issued only to the party for whose account the transportation or storage was provided and who contracted with the billing party, or to the consignee as defined by the rule. The same charge cannot simply be sent simultaneously to multiple parties. The billed party must also receive at least 30 days to request mitigation, a refund or waiver.

The FMC says a detention or demurrage invoice that fails to include required information can eliminate the billed party’s obligation to pay that particular charge.

For a Norfolk port-related collection, the invoice itself may be just as important as the underlying shipment documents.

Commercial Collection Services


What happens when an Old Dominion University account reaches 120 days past due?

Old Dominion University currently states that when the principal balance reaches 120 days past due and is forwarded to collections, repayment arrangements must generally be made directly with the collection agency.

ODU also currently adds a 25% collection fee to an account forwarded at that stage. A financial hold can restrict registration and other university services, and ODU states that a financial hold can be placed when a past-due balance exceeds $500.

Failure to attend a registered course does not, by itself, eliminate the underlying tuition responsibility; the student normally must complete the applicable withdrawal process to qualify for release or refund of charges.

For education collections, tuition, housing, returned payments, financial-aid adjustments and other charges should remain clearly itemized.

School & Education Collection Services


Can a Norfolk hospital or collection agency report unpaid medical debt to the credit bureaus?

No—not qualifying medical debt covered by Virginia’s prohibition.

Virginia law states that qualifying medical providers may not report any portion of a medical debt to a consumer reporting agency. It separately prohibits a collection entity collecting or attempting to collect medical debt from reporting that collection activity to a consumer reporting agency.

Virginia now also has additional medical-debt collection protections. Among them, qualifying extraordinary collection actions generally cannot begin until 120 days after the final invoice due date, and the patient generally must receive at least 30 days’ advance notice before such action. For large healthcare facilities and medical-debt buyers, interest or late fees generally cannot begin until 90 days after the final invoice due date and are capped at 3% annually.

That makes accurate classification especially important for Norfolk hospitals, specialty practices and medical groups.

Medical Collection Services


A company supplied goods or services to the City of Norfolk. How long can payment take if the contract is silent?

Virginia’s local-government Prompt Payment law provides the default.

If the contract does not establish another payment date, a Virginia locality generally must pay no later than 45 days after the goods or services are received or 45 days after the invoice is rendered, whichever is later.

If there is a defect or problem that will prevent payment, the local agency generally must notify the supplier within 20 days after receiving the invoice or goods/services. Unless the contract provides otherwise, finance charges assessed for qualifying late payment generally may not exceed 1% per month.

For a Norfolk government receivable, preserve the purchase order, procurement contract, invoice, proof of delivery, acceptance documentation and any written dispute notice.

Government Collection Services


Does active-duty military status mean a Norfolk debt cannot be collected?

No—but the Servicemembers Civil Relief Act can materially change how certain debts and legal actions must be handled.

For qualifying obligations incurred before military service, the SCRA can cap interest at 6% per year once the servicemember properly invokes the protection. Interest above 6% must generally be forgiven rather than deferred.

The SCRA also provides protections involving default judgments and the ability to stay certain civil proceedings. For example, when a servicemember has not appeared in a civil lawsuit, the creditor must address the defendant’s military status, and additional court procedures can apply before a default judgment is entered.

That distinction is especially relevant in Norfolk, where the city is home to the world’s largest naval base and Hampton Roads has one of the country’s largest military populations.

A military account is therefore not automatically uncollectible, but it should be screened for applicable SCRA protections before escalation.


Industries We Serve in Norfolk

Maritime, Ship Repair & Marine Suppliers: Recovery for shipyards, vessel-repair companies, marine electronics providers, equipment suppliers and port-service businesses. Norfolk’s location supports a dense shipbuilding, ship-repair and maritime workforce.

Freight, Logistics & Port Businesses: B2B recovery for freight forwarders, marine cargo companies, warehouses, transportation firms and logistics providers operating around the Port of Virginia.

Defense & Government Contractors: Recovery for defense suppliers, engineering firms, technology contractors and businesses supporting Naval Station Norfolk and other federal or municipal operations.

Healthcare & Medical: 100% HIPAA-compliant recovery for hospitals, physician groups, specialty clinics and healthcare organizations. Norfolk’s healthcare and life-sciences sector includes Sentara Norfolk General, CHKD and a substantial medical-services base.

Dental & Orthodontics: Reputation-sensitive recovery for dental practices, orthodontists and specialty dental providers.

Colleges, Universities & Training Providers: Tuition, program fees, institutional receivables and other documented education balances for universities, colleges and training organizations.

CPA, Accounting & Professional Services: Recovery of consulting, accounting, engineering and other professional-service fees while protecting ongoing client relationships.

Construction, Restoration & Trades: Recovery for general contractors, restoration companies, HVAC, electrical, roofing and specialty trades.

Banks & Credit Unions: Recovery of qualifying loan, overdraft and deficiency balances while respecting Virginia exemptions, SCRA protections and applicable post-judgment rules.

Advanced Manufacturing & Technology: B2B recovery for manufacturers, industrial suppliers, IT firms, cybersecurity providers and technology businesses.


Ready to unclog your cash flow?

Get a Free Quote for Your Norfolk Business

Why Piscataway Businesses Need a Smarter A/R Strategy

In Piscataway, business moves fast. From the research labs on Busch Campus to the logistics hubs along Corporate Place, this isn’t just a college town—it’s a critical engine of New Jersey’s economy.

But if your invoices are unpaid, your growth is stalled.

Too many local businesses—whether in biotech, logistics, or healthcare—are relying on outdated “collection agencies” that use aggressive tactics and charge 40-50% fees. This approach might work for a generic debt buyer, but in a tight-knit corporate community like Middlesex County, it burns bridges.

You need a partner that understands the specific pressures of the New Jersey market: high costs, strict regulations, and the need for speed.

Nexa provides a reputation-safe approach, equipped with all 50-state collections license, offering free credit reporting, free litigious debtor check, free bankruptcy scrub, and zero onboarding fees. Secure – SOC 2 Type II & HIPAA compliant. Over 2,000 online reviews rate us 4.85 out of 5. 

Need a Collection Agency? Contact us

Our 4-Step Process: Control & Compliance

  • Step 1: First-Party Outreach ($15): We act as your internal billing team, sending courteous reminders. Ideal for early-stage B2B or patient balances.

  • Step 2: Third-Party Demands ($15): A formal escalation letter from us. This professional nudge resolves most accounts.

  • Step 3: Contingency (40%): For stubborn accounts, our expert team takes over. No recovery, no fee.

  • Step 4: Legal Forwarding (50%): If litigation is required, we manage the entire process through our vetted attorney network.

The New Standard for Central Jersey Collections

We are not a traditional agency. We are a modern accounts receivable partner.

Old-school agencies wait until an account is “dead,” charge you half the recovery, and treat your clients like enemies. We flipped the model. We prioritize early, fixed-fee intervention that resolves balances before they damage your reputation or your bottom line.

How We Helped a Local Logistics Firm

A mid-sized logistics company near Hoes Lane was struggling with B2B invoices that were 60+ days past due. They feared that hiring a collection agency would alienate their long-term shipping partners. We implemented our Step 2 (Third-Party Demand) service. Instead of a contingency fee, we sent professional, firm demand letters for a flat $15 per account. The result? They recovered $52,000 in overdue revenue in just 40 days, retained every client relationship, and paid zero percentage fees.

3 Reasons to Switch Your Collection Strategy

1. We Navigate the “Louisa Carman” Law

New Jersey’s debt collection landscape shifted dramatically in 2024 with the Louisa Carman Medical Debt Relief Act. This law bans reporting medical debt to credit bureaus, caps interest at 3%, and prohibits collection actions until 120 days after the first bill. If your current agency isn’t 100% up to speed on these 2025 regulations, they are a liability. We ensure you stay compliant while still recovering what is owed.

2. We Keep Traffic Moving

Just like avoiding the bottleneck at the River Road and Route 18 interchange, we remove friction from your billing process. Our system identifies the right time to escalate, ensuring you don’t waste time on accounts that will never pay while maximizing recovery on those that can.

3. We Don’t Charge a “Turnpike Toll”

Why give up 50% of your money? Our Step 1 & 2 fixed-fee options (starting at $15) allow you to keep 100% of the recovered funds. We only move to contingency (40%) if the low-cost steps don’t work.

Understanding New Jersey Collection Laws

We help you navigate the Garden State’s specific regulations.

  • Statute of Limitations: In NJ, the window to sue for debt is generally 6 years for contracts and 4 years for the sale of goods (UCC). If you wait too long, the debt becomes legally uncollectible.

  • Bonding: New Jersey requires collection agencies to file a $5,000 surety bond with the state. Working with an unbonded agency is a risk you shouldn’t take. We are fully bonded and compliant.

  • Medical Debt: As of July 2025, strict new rules apply to medical collections, including income-based garnishment bans. We manage these complexities so you don’t have to.

Frequently Asked Questions

Do you handle medical collections given the new NJ laws?

Yes. We are experts in the Louisa Carman Medical Debt Relief Act. We know exactly when and how to communicate with patients to secure payment without violating the new 120-day waiting periods or reporting bans.

Can you collect from Rutgers students who moved away?

Absolutely. Piscataway is transient. If a debtor moves back to New York, Pennsylvania, or California, we can pursue them. Nexa’s partner agencies are licensed in all 50 states. We follow the debtor, not just the address.

What industries do you serve in Piscataway?

We work with a diverse range of local sectors, including biotech/pharma, logistics and warehousing, property management (student and corporate housing), and medical practices.

Why shouldn’t I just use a lawyer?

Lawyers bill by the hour; we bill by results. Unless the debt is significantly large (over $5,000), a lawyer’s retainer often eats up the recovery. Our model gives you the leverage of a third party without the upfront legal fees.

Ready to Unblock Your Cash Flow?

Stop letting unpaid invoices pile up. Let’s build a reliable, compliant revenue cycle for your business.

Get Your Free Consultation Today

  • « Go to Previous Page
  • Page 1
  • Interim pages omitted …
  • Page 21
  • Page 22
  • Page 23
  • Page 24
  • Page 25
  • Interim pages omitted …
  • Page 27
  • Go to Next Page »

Primary Sidebar


accounts receivable

Need a Collection Agency?
Kindly fill this form.
We’ll get in touch with you

    Please prove you are human by selecting the tree.

    Compliance & Security

    • SOC 2 Type II Certified: Third-party audited data security and strict privacy controls.

    • HIPAA Compliant: Secure, legal processing of medical and municipal EMS accounts.

    • PCI-DSS Level 1: Highest tier of data encryption for secure payment processing.

    • FDCPA & FCRA Aligned: Full legal adherence to federal consumer protection laws.

    Recent Posts

    • Why Dental Patients Dispute Bills: The Nexa Collections Dental Account Dispute Index
    • 2027 Commercial Collections Benchmark: U.S. Late Payments, AR Risk and B2B Collection Trends
    • Bulk Account Placement: What a Collection Agency Actually Needs From You
    • Nationwide Debt Collection Agency Serving U.S. Cities
    • Chula Vista Collection Agency for Medical, B2B, Schools & Business Debt
    • Corpus Christi Collection Agency: Itemized Bill Rules for Practices
    • Riverside Collection Agency | For Logistics, Medical, Schools & Business Recovery
    • Collection Agency for Large Balances: High-Value B2B Debt Recovery

    Featured Posts

    • 10 Ways To Handle Angry Patients
    • Riverside Collection Agency | For Logistics, Medical, Schools & Business Recovery
    • 6 Steps to Creating Accurate Cash Flow Forecast for Your Business

    Copyright © 2026 NEXACOLLECT.COM | This content is provided for general informational purposes only and should not be considered legal advice. Collection laws and requirements may vary by state, account type, documentation, debtor status, and specific facts. Please consult qualified legal counsel for guidance regarding your particular situation. Nexa and its authorized collection partners service accounts in accordance with applicable federal and state collection requirements. Visit our home page to know more about us.

    X
    Need a Collection Agency?
    Contact Us