• Skip to main content
  • Skip to primary sidebar

Nexa Collections

  • Home
  • Serving
    • Medical
    • Dental
    • Small Business
    • Large Business
    • Commercial Collections
    • Government
    • Utilities
    • Fitness Clubs
    • Schools
    • Senior Care Facility
  • Contact Us
    • About us
    • Cost

Debt Recovery

Proactive Approach to Lower Accounts Receivable

Customer payments get delayed all the time. It may not always be worrisome right away, but not having an accounts receivables strategy can be devastating for your business.

Consumers and businesses alike have ups and downs, and their financial situation can temporarily or permanently deteriorate. If you have outstanding AR from your customers, it is crucial to get paid on time before they prioritize other payments over yours.

Firstly, you must learn to overcome the hesitation of reminding your customer of a missed payment promptly. It is possible that it was just an oversight on their part, but there is always a possibility that they have a financial crunch. They could be owing other bills just like yours.

Secondly, there is nothing wrong with sending invoices twice a month, and a phone call to the concerned person will ensure that you have done everything to maintain a healthy AR. We prefer emailing the invoice, followed by physically mailing the same invoice ten days later, followed by a phone call to the concerned person after another ten days. It means in 1 month you would have contacted them thrice (by email, mail, and phone call). The process should repeat for at least 2-3 months until you get paid.

Lowering accounts receivable is essential for improving cash flow and reducing the risks associated with late or non-payments. A proactive approach involves implementing strategies that will reduce the amount of money owed to your business by clients or customers before it becomes a problem. Here’s how you can be proactive in managing and reducing your accounts receivable:

  1. Credit Policy Evaluation: Regularly evaluate your credit policy. This includes reassessing credit limits, conducting background checks, and analyzing the creditworthiness of new and existing customers.
  2. Clear Payment Terms: Clearly state your payment terms on invoices and contracts. This includes the due date, late payment penalties, and any discounts for early payments.
  3. Invoice Promptly and Accurately: Send invoices as soon as goods or services are delivered. Ensure that the invoices are accurate, detailed, and include all the necessary information for the customer to make payment.
  4. Electronic Invoicing and Payments: Adopt electronic invoicing and offer multiple payment options, making it easier and faster for customers to pay.
  5. Regular Follow-ups: Keep a consistent schedule for following up on unpaid invoices. Start with a polite reminder as the due date approaches, and maintain communication if the payment is late.
  6. Maintain Relationship with Customers: Maintain a positive relationship with your customers. Understanding their business and any issues they may be facing can help in negotiating payment plans if they are experiencing financial difficulties.
  7. Train Staff in Accounts Receivable Management: Ensure your staff is well-trained in accounts receivable best practices. They should be knowledgeable in your policies and be able to handle communications with customers effectively.
  8. Monitor Accounts Receivable Aging Reports: Regularly review accounts receivable aging reports to identify overdue accounts. This helps to prioritize collection efforts and spot trends that may need attention.
  9. Offer Early Payment Discounts: Provide incentives such as discounts to customers who pay their bills before the due date.
  10. Implement a Dunning Process: Establish a structured communication process that escalates in tone and urgency as an account becomes more overdue.
  11. Outsource or Utilize Collection Agencies: For severely overdue accounts, consider utilizing the services of a collection agency or outsourcing the accounts receivable process. Also, assess your dependency on this customer and prepare for an alternate strategy. If your invoice is 90-120 days old, I do not doubt that most of these accounts should be forwarded to a collection agency.
  12. Regularly Review and Optimize Processes: Continually review your accounts receivable processes for efficiency. Make necessary adjustments based on what’s effective and what’s not.
  13. Use Technology Solutions: Implement software that automates the accounts receivable process. This not only saves time but also minimizes errors and provides valuable data for analysis.
  14. Cash Flow Forecasting: Regularly forecast cash flow taking into account your accounts receivable. This will give you a better understanding of your financial health and allow you to make informed decisions.
  15. Document and Enforce Policies: Have a documented policy regarding accounts receivable management and ensure that it is consistently enforced.

By being proactive in managing your accounts receivable, you can lower the outstanding balances and improve the financial health and sustainability of your business.


Filed Under: Debt Recovery

Setup Fee for Collection Agency: Waived Off !!

It is common for collection agencies to charge an onboarding fee to their new customers. However, a few good collection agencies with nationwide coverage waive their setup fee regardless of the number of accounts you have for collections.

Contact us if you need a collection agency with the following features.

  • No setup fee and no hidden charges. We guarantee it.
  • Open-ended contract with no minimums and free credit bureau reporting.
  • High collection rates and an easy-to-use online client portal.
  • Offers both Fixed-fee service and Contingency-only based collection services.
  • Cares about your reputation by not indulging in aggressive collection tactics.
  • GLBA, FDCPA, TCPA and PCI compliant.  ( Obeys government-mandated rules and handles data securely)

With over 3000 collection agencies all over the USA, selecting a good collection agency can be a daunting task.

Selecting a mid-sized collection agency will ensure that you get adequate attention and that compliance with national and state laws is entirely followed.


Filed Under: Debt Recovery

Collection Agency for Lumber Companies: Reputation Safe Approach

Whether you’re a family-run yard or a regional building supplier, local construction cycles shouldn’t dictate your cash flow. Don’t let past-due contractor notes stall your inventory turnover while the competition keeps building across town. We help our local partners reconcile accounts before a single bad debt weakens your standing in our community.

Lumberyards Are Not Banks: Stop Financing Your Customers’ Projects

As a supplier, you are operating on razor-thin margins. Industry data for 2024 shows that the average net profit margin for building material dealers often hovers between 3% and 6%.

Here is the math that keeps owners awake at night: If you write off just $10,000 in bad debt at a 5% margin, you have to sell an additional $200,000 in lumber just to break even.

Nexa provides a reputation-safe approach, equipped with all 50-state collections license, offering free credit reporting, free litigious debtor check, free bankruptcy scrub, and zero onboarding fees. Secure – SOC 2 Type II & FDCPA compliant. Over 2,000 online reviews rate us 4.85 out of 5. 

Need a Collection Agency? Contact us

In the building materials sector, your reputation is as important as your inventory. We act as your Account Reconciliation Team, using a “Velvet Hammer” approach—diplomatic enough to protect your 5-star online reputation but firm enough to ensure you are the first creditor paid. Our team includes dedicated Spanish-speaking collectors to bridge communication gaps immediately.

The “Dispute” Game: How GCs Delay Payment

We know the specific excuses you hear from general contractors, because we handle them every day. Traditional agencies treat every debt like a credit card bill. We treat lumber debts like construction disputes.

We know how to push back on the common “stall tactics” used in the lumber trade:

  • The “Culling” Claim: The contractor waits 45 days to tell you that 20% of the framing package was “unusable” due to wane or shake. We demand the timestamped photos and the rejection notice that should have been sent upon delivery, not two months later.

  • The “Phantom” Shortage: They claim the load was short five bundles of studs. We counter with the signed Proof of Delivery (POD) and GPS data from your drop.

  • The “Pay-When-Paid” Bluff: GCs often tell suppliers they can’t pay until the owner pays them. In most states, this clause does not apply to material suppliers. We remind them of the law.

Transparent Recovery for Building Suppliers (B2C Accounts)

Cash flow is the lifeblood of the lumber industry. We provide straightforward pathways to get your balance sheet back in the green without the guesswork:

  • Fixed-Fee Recovery ($15): Best for early-stage accounts. You pay a flat fee per account and your business retains 100% of the recovered funds.

  • Contingency Resolution (40%): Our “No Recovery, No Fee” model ensures we only get paid when you do.

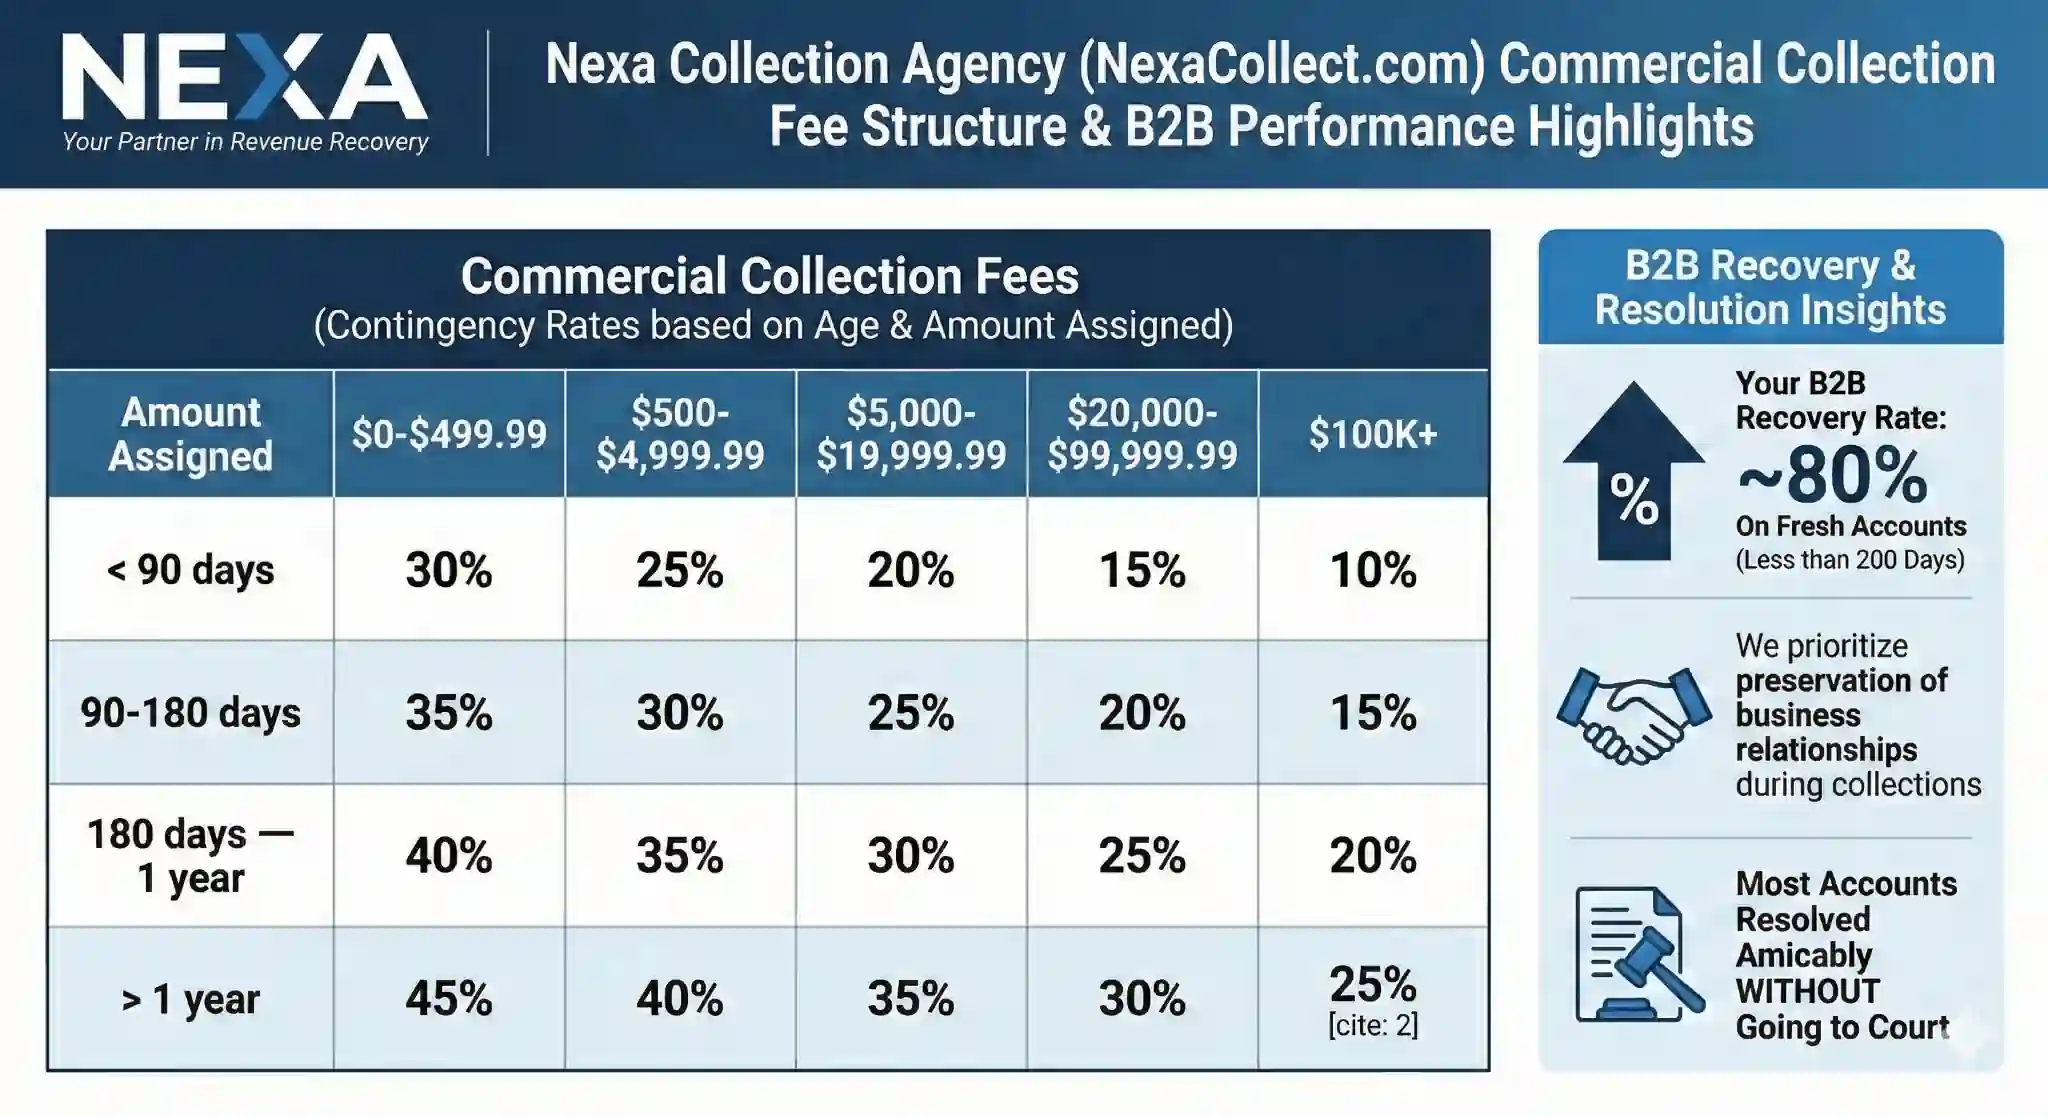
Pricing for Commercial B2B Accounts

Why LBM Dealers Choose Us

  • We Check Before We Chase: We provide Free Bankruptcy and Litigious Checks on every account. If a builder has already filed Chapter 7, we tell you immediately so you don’t throw good money after bad.

  • We Protect Your Brand: The construction world is small. We recover your money firmly but professionally, ensuring you don’t get a reputation for being “impossible to work with” in the local market.

  • Nationwide Reach: Whether you shipped a load across the county line or across the country, we are licensed to collect in all 50 states.

Success Story: The $42,000 “Pay-When-Paid” Pivot

The Conflict: A General Contractor (GC) stalled a $42,000 framing invoice, using the “Pay-When-Paid” excuse to treat a local lumber yard like an interest-free bank.

The Strategy: We bypassed the stall by initiating a Phase 2 Lien-Aware Escalation, diplomatically reminding the GC that material suppliers are legally exempt from such clauses.

The Result: The balance was settled in full within 18 days—prioritized to avoid a bond claim—and because our “Velvet Hammer” approach preserved the relationship, the contractor has since returned for a new $60,000 cash-up-front order.

Q&A: Real Issues from the Lumber Yard

Q: Can you help if the material was stolen from the job site?

A: This is a massive issue. Contractors often try to refuse payment for material stolen after delivery. However, legally, FOB Job Site means the risk of loss transfers to the buyer upon delivery. If you have a clean POD, we enforce payment. The contractor’s lack of site security is not your financial loss.

Q: Do you handle Retainage disputes?

A: Yes. Retainage (usually 5-10%) is standard, but GCs often “forget” to pay it out months after the project is closed. We track substantial completion dates and aggressively pursue these “leftover” balances that add up to significant profit.

Q: What about “Moisture Content” disputes?

A: This is frequently a user error (improper storage on site) rather than a product defect. We know how to ask the right questions to determine if the lumber was left uncovered in the rain versus actually being delivered wet.

Stop Cutting Into Your Margins

You delivered the wood. You deserve the check. Stop letting bad debt eat away at your hard-earned profits.

Collecting money for Lumberyards Nationwide

Contact us & start recovering. High recovery rates.

Filed Under: Debt Recovery

How can Collection Agencies Maintain a Good Reputation?

Business and medical professionals seeking to hire a collection agency always wonder if the agency they hire is ethical or if it may damage their reputation. 

Here are some valuable tips on how collection agencies can maintain a good reputation online and offline.

  • Following Federal and State laws: A collection agency that violates government laws will get sued or penalized sooner or later. This violation can be all over the news, and this incident will remain in electronic news outlets for years. 
  • Google Ratings: Checking Google ratings are the #1 place for almost everyone when shortlisting a collection agency. Asking your happy customers or satisfied debtors can improve your online reputation by many folds.
  • Amicable collections: Using harsh, abusive, unfair, or deceptive practices to collect debts from your debtors can severely damage your reputation. 
  •  BBB Rating: Although millennials may not care much about Better Business Bureau ratings, this is often quite important to people over 55. People in this group can be real decision-makers.
  • Scholarships: Giving college scholarships, sponsoring a community event, and donating a small percentage of profit for a social cause, then publishing those events on your blog or press release can work wonders for your collection agency’s reputation.
  • References: Positive references from existing customers and publishing them on your website can be very effective. Businesses may not believe what you tell them, but positive reviews from their peers are very impactful.
  • Good recovery rates: Last but not least, if you recover more money for your customers, they will likely refer your service to their friends, who may also be looking to hire a debt collector.
  • Be vocal about your compliance: Compliances like GLBA, PCI, HIPAA, and affiliations like ACA are essential to comfort potential clients.


Filed Under: Debt Recovery

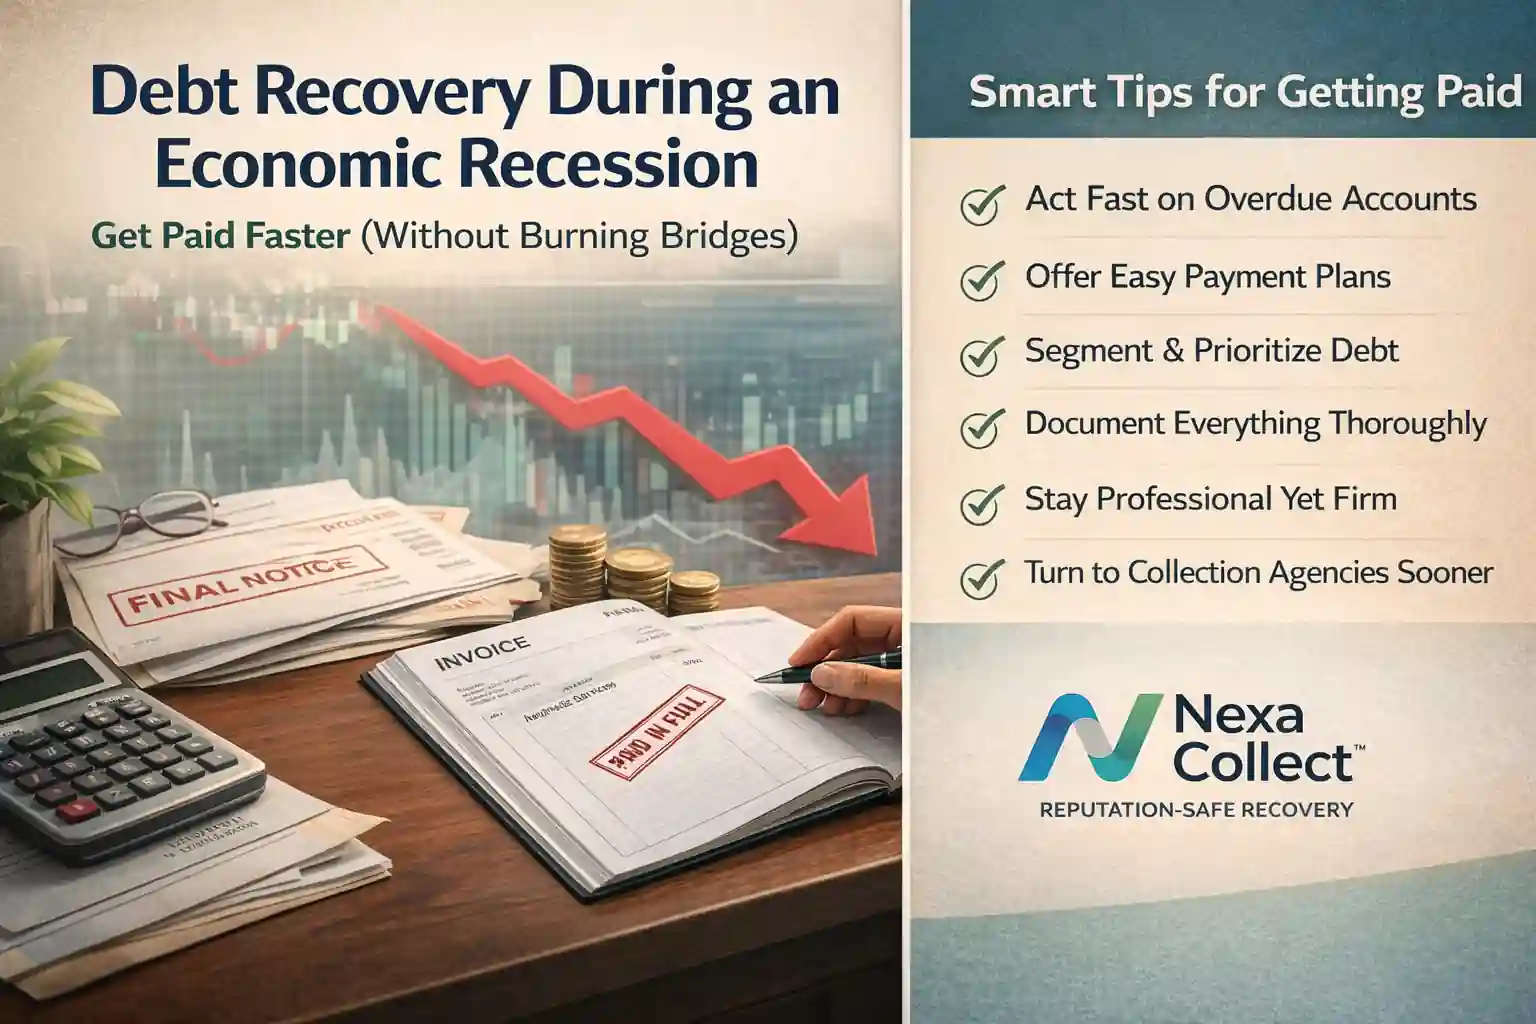
Professional Debt Recovery During a Recession | Get Paid Faster, Reputation-Safe

The more you defer working on your overdue bills, the financial situation of your customers/debtors will deteriorate. The probability of getting paid will decrease with each passing day, especially during a recession.

blank

When the economy slows down, getting paid becomes harder—even by customers who normally pay on time. Rising interest rates can increase monthly payments on credit cards, auto loans, and mortgages, while layoffs and higher living costs squeeze budgets.

That’s why recession debt recovery isn’t just “collect harder.” It’s about collecting smarter, faster, and more professionally—before your invoices become last on the debtor’s priority list.

Quick Recession Debt Recovery Checklist

✅ Follow up early (don’t wait months)
✅ Prioritize your “most recoverable” accounts
✅ Offer structured payment solutions
✅ Tighten documentation and remove disputes
✅ Communicate firm but professional
✅ Use escalation deadlines
✅ Assign stuck accounts to collections fast

Nexa provides a reputation-safe approach, equipped with all 50-state collections license, offering free credit reporting, free litigious debtor check, free bankruptcy scrub, and zero onboarding fees. Secure – SOC 2 Type II & HIPAA compliant. Over 2,000 online reviews rate us 4.85 out of 5. 

Need a Collection Agency? Contact us

Below is a detailed, recession-friendly playbook that helps businesses protect cash flow while still keeping relationships intact.


1) Act Early: Fresh Debt Recovers Faster

Waiting is the biggest mistake. 30–90 days past due is still recoverable. 180+ days becomes high-risk.

Best timeline:

  • Follow up within 3–7 days of due date

  • Escalate at 15–30 days

  • Consider collections at 45–60 days if ignored


2) Segment Accounts (Don’t Treat Everyone the Same)

Prioritize like triage:

  • A: Most recoverable (recent, responsive)

  • B: Needs negotiation (cash-flow issues)

  • C: High risk (disputed, non-responsive, closed)


3) Offer Structured Payment Options

One-time demands often fail in a recession. Give simple choices:

  • 2-part split payment

  • 3–6 month plan

  • Fast-pay incentive (where appropriate)

People don’t need pressure—they need a path.


4) Reduce Disputes With Strong Documentation

Disputes increase during downturns. Be ready with:

  • invoice + contract/PO

  • proof of delivery/completion

  • approvals/scope emails

  • payment history summary

Clean paperwork speeds agreement.


5) Stay Professional: Reputation-Safe Recovery Works

Aggressive tactics can backfire. A recession-friendly tone is:
calm, direct, consistent.
Use firm lines like:

  • “Let’s resolve this before it escalates.”

  • “Here are options to close the balance.”


6) Escalate Smart: Deadlines Without Drama

Structure gets results. Use a clear ladder:
Reminder → Final notice → Resolution window → Third-party collections
Always include a deadline + next step so it doesn’t drag on forever.


7) When to Involve a Collection Agency

If internal follow-ups aren’t working, a collection agency can help by:

  • contacting debtors professionally

  • negotiating settlement plans

  • escalating correctly

  • recovering funds while you focus on business

It also removes awkward chasing and improves recovery odds.

Why Recessions Create More Past-Due Accounts

During an economic recession, debtors typically do three things:

  • Delay payments to preserve cash

  • Dispute invoices more often to buy time

  • Ghost vendors instead of negotiating

Even customers with good intentions may prioritize essentials (payroll, rent, fuel, inventory) and push your invoice to “later.” And unfortunately, “later” often turns into never.

Need help recovering overdue invoices during a recession? Contact us

blank

Filed Under: Debt Recovery

Government is Making Debt Recovery a lot Harder

The US government has thrown several laws on collection agencies, making bad-debt recovery harder and costlier. Lower recoveries mean, low recoveries and extensive loss for businesses and doctors. Our government’s intention behind these laws is not wrong, but the ground reality is different. 

Extra costs to comply with these laws would be passed on to businesses /creditors unwilling to pay the current expenses of hiring a professional debt collector.

There are thousands of collection agencies in the USA, but most are small. They have less than ten people and work from small offices. The following changes can result in many collection agencies shutting their businesses. 

New Regulations

  1. As per FTC, starting June 9, 2023, all collection agencies will be treated as financial institutions. This means all collection agencies must secure consumer data nearly the same way as banks.
    Read: Impact of the GLBA on Collection Agencies

  2. As of Nov 2021, The new debt validation notice format recommended by CFPB makes it easier for debtors to dispute the authenticity of debt. Debtors who would have usually paid quickly are now disputing the collection notices more than ever. All these delays and extra paperwork means higher cost, lower recovery, and more time to recover debts.
    Read this: https://nexacollect.com/debt-recovery/validation-letter/

  3. In another CFPB order, all collection agencies must provide the balance as of a specific date and itemize all interest, fees, payments and adjustments from that date. Not all clients have this information handy. Many clients would take the loss upfront rather than wasting time digging into all the detailed documentation required to submit an account for collections. 
  4. The government and even credit bureaus are creating roadblocks for hospitals, doctors and dentists, who rely on collection agencies and credit bureau reporting for medical debt recovery. Credit bureaus will soon stop reporting medical debts lower than $500, remove medical line items that have been fully paid, and collection agencies now have to wait one year before medical debts can be reported. Suppressing how medical reports are reported to the credit bureaus will surely increase the cost of healthcare, more defaults, more legal mess, and higher risk for future creditors.
    Read: Making Medical Credit Reporting Harder is a Disaster in the Making

These laws are on top of all the existing Federal and State laws. These include FDCPA, TCPA, HIPAA, FCRA, and many more.

These laws can have a positive perception of people on lawmakers, but as usual, it is making doing business harder than ever.

Filed Under: Debt Recovery

  • « Go to Previous Page
  • Page 1
  • Interim pages omitted …
  • Page 18
  • Page 19
  • Page 20
  • Page 21
  • Page 22
  • Interim pages omitted …
  • Page 55
  • Go to Next Page »

Primary Sidebar


accounts receivable

Need a Collection Agency?
Kindly fill this form.
We’ll get in touch with you

    Please prove you are human by selecting the key.

    Compliance & Security

    • SOC 2 Type II Certified: Third-party audited data security and strict privacy controls.

    • HIPAA Compliant: Secure, legal processing of medical and municipal EMS accounts.

    • PCI-DSS Level 1: Highest tier of data encryption for secure payment processing.

    • FDCPA & FCRA Aligned: Full legal adherence to federal consumer protection laws.

    Recent Posts

    • Why Dental Patients Dispute Bills: The Nexa Collections Dental Account Dispute Index
    • 2027 Commercial Collections Benchmark: U.S. Late Payments, AR Risk and B2B Collection Trends
    • Bulk Account Placement: What a Collection Agency Actually Needs From You
    • Nationwide Debt Collection Agency Serving U.S. Cities
    • Chula Vista Collection Agency for Medical, B2B, Schools & Business Debt
    • Corpus Christi Collection Agency: Itemized Bill Rules for Practices
    • Riverside Collection Agency | For Logistics, Medical, Schools & Business Recovery
    • Collection Agency for Large Balances: High-Value B2B Debt Recovery

    Featured Posts

    • The Delicate Art of OB-GYN Collections, Without Losing Your Patients
    • Adapting to Change: Key Trends and Challenges for Private Ambulance Services
    • Navigating Canada’s Debt Collection Landscape: Laws, Ethics and Regulations

    Copyright © 2026 NEXACOLLECT.COM | This content is provided for general informational purposes only and should not be considered legal advice. Collection laws and requirements may vary by state, account type, documentation, debtor status, and specific facts. Please consult qualified legal counsel for guidance regarding your particular situation. Nexa and its authorized collection partners service accounts in accordance with applicable federal and state collection requirements. Visit our home page to know more about us.

    X
    Need a Collection Agency?
    Contact Us