• Skip to main content
  • Skip to primary sidebar

Nexa Collections

  • Home
  • Serving
    • Medical
    • Dental
    • Small Business
    • Large Business
    • Commercial Collections
    • Government
    • Utilities
    • Fitness Clubs
    • Schools
    • Senior Care Facility
  • Contact Us
    • About us
    • Cost

Debt Recovery

Data Security Rules that Collection Agencies Must Follow

Debt collection agencies are subject to various data security rules and regulations to protect consumer information. I will outline some general principles and specific regulations in the United States. Remember that there might be additional state or local regulations, and laws can change over time.

  1. Fair Debt Collection Practices Act (FDCPA): While primarily focused on the practices and behaviors of debt collectors, the FDCPA also contains provisions that protect consumers’ personal information.
  2. Gramm-Leach-Bliley Act (GLBA): This act requires financial institutions, including debt collection agencies, to explain their information-sharing practices to their customers and to safeguard sensitive data. The Safeguards Rule under GLBA mandates that financial institutions must have measures in place to keep customer information secure.
  3. Federal Trade Commission Act (FTC Act): Under Section 5 of the FTC Act, debt collection agencies are required to employ fair and equitable practices. This includes protecting consumer data from unauthorized access or data breaches.
  4. Health Insurance Portability and Accountability Act (HIPAA): If the collection agency is dealing with medical debts, they must also comply with HIPAA, which sets rules for the protection of health information.
  5. State Laws: States might have their own set of laws regarding data security and privacy. For example, the California Consumer Privacy Act (CCPA) has stringent rules for businesses that handle the personal information of California residents.
  6. Payment Card Industry Data Security Standard (PCI DSS): If the institution processes /stores credit card transactions, it must comply with PCI DSS, which outlines requirements for enhancing payment account data security.

Regardless of the jurisdiction, it is generally expected that debt collection agencies must:

  • Protect sensitive consumer information by using secure systems.
  • Limit the amount of personal information they collect to what is necessary.
  • Not disclose information to third parties without a valid reason.
  • Provide individuals with the ability to access, correct, or erase their personal information in certain circumstances.
  • Have a data breach response plan in place.

If you are dealing with a debt collection agency and have concerns about data security or privacy, consider consulting with a legal professional to understand the specific regulations that apply to your situation.
 

Filed Under: Debt Recovery

Consequences of Ignoring Debt Collection

The “Ostrich Effect”: Why Your Customers Are Ghosting You (And How to Break the Silence)

If you are reading this, you are likely staring at an unpaid invoice and wondering, “Why won’t they just call me back?”

You have sent the polite reminders. You have left voicemails. You have tried to be understanding. In return, you get silence. This isn’t just bad manners; it is a psychological phenomenon known as the Ostrich Effect. When faced with financial stress, debtors bury their heads in the sand, hoping that if they ignore your emails long enough, you will simply give up.

And usually, they are right. Most internal accounting teams do give up after 90 days.

But when you partner with NexaCollect, the dynamic shifts instantly. We don’t let them hide. We turn the “silence” into a calculated escalation that forces a decision: Pay now, or face the consequences.


3 Reasons Why They Ignore You (But Won’t Ignore Us)

Internal billing departments lack leverage. Third-party agencies command attention. Here is the psychology behind the switch.

1. The “Vendor vs. Authority” Shift

To a debtor, you are a vendor. A relationship. Someone they can negotiate with or stall. When they receive a letter from NexaCollect, the relationship ends. We are a regulated third-party entity. Our presence signals that the debt has moved from “accounting issue” to “legal liability.”

  • The Stat: Industry data shows that a formal third-party demand is 3x to 5x more effective at eliciting a response than an internal invoice reminder.

2. The Threat of Credit Damage (The 100-Point Drop)

Your internal emails might be annoying, but they don’t threaten their financial future. Our demands do.

  • The Reality: A collection account reporting to Equifax, Experian, or TransUnion can drop a credit score by 100+ points overnight. For a business owner trying to secure a line of credit or a consumer trying to rent an apartment, this is a non-negotiable risk. They pay us to protect their score.

3. The “Litigation Certainty”

Debtors ignore you because they think you won’t sue over $2,000. They might be right. But they don’t know our capabilities.

  • The Data: In 2024, consumer debt lawsuits surged to pre-pandemic levels. More importantly, over 70% of debt lawsuits result in a Default Judgment because the debtor fails to show up.

  • The Leverage: We make them understand that ignoring the debt doesn’t stop the lawsuit; it guarantees they will lose it.


The Escalation Timeline: What Happens When They Ignore Us?

We use a tiered pressure system designed to break the silence.

  • Day 1-30 (The Wake-Up Call): We deploy Step 2 (Flat-Fee Demands). These are official, Regulation F compliant notices. They strip away the “I didn’t see the invoice” excuse.

  • Day 31-60 (The Pressure Cooker): If they continue to ghost, we move to Step 3 (Contingency). Our team begins skip-tracing to find new numbers and employers. We apply intensive phone pressure.

  • Day 90+ (The Nuclear Option): If they still refuse to pay, we review the file for Step 4 (Legal). If the debtor has assets (wages, property, bank accounts), our attorney network files suit. A judgment leads to wage garnishment and bank levies.


Strategic Insight: The Risk of B2B Defaults

If you are a B2B business, ignoring a slow-paying client is dangerous.

  • The Stat: Research indicates that one payment default creates a 20% probability that your client will fail within 12 months. If they default on three obligations, that probability jumps to 62%.

  • The Takeaway: If they are ignoring you, they are likely ignoring others. You need to be the “squeaky wheel” that gets paid before they file for bankruptcy.


FAQ: The Mechanics of “Ignoring It”

Q: Can a debtor simply block your calls?

A: They can block a number, but they cannot block the United States Postal Service or a Process Server. Regulation F (the modern FDCPA) also allows us to use email and text messaging (with proper opt-outs) to ensure our message lands. They can hide, but they cannot claim ignorance.

Q: Does the “Statute of Limitations” mean the debt disappears?

A: No. This is a common myth. The Statute of Limitations (SOL) only limits the time we have to sue them (typically 3-6 years depending on the state). It does not erase the debt. We can still collect, call, and report the debt to credit bureaus (for up to 7 years) long after the SOL has passed.

Q: What if they ignore the court summons?

A: That is actually the best-case scenario for you. If they ignore the summons, the court issues a Default Judgment. This gives us the legal power to garnish wages or freeze bank accounts without a trial.

Break the Silence. Secure Your Revenue.

Stop letting debtors control your cash flow with their silence. Use a system designed to get a response.

Click here to Contact Us and start your recovery campaign.

Filed Under: Debt Recovery

Impact on Credit Score due to a Medical Debt Default

Debt recovery
Medical debt default can significantly impact an individual’s credit score. Here are some points to consider regarding the impact of medical debt default on the patient’s credit scores:

  1. Reporting to Credit Bureaus: When a medical debt goes unpaid for an extended period, the healthcare provider may send the account to a collection agency. The collection agency may then report the debt to the credit bureaus. Once it is reported, it is listed on your credit report as a collection account for up to 7 years.
  2. Drop in Credit Score: Having a collection account on your credit report, especially for an unpaid debt, is considered a negative mark and can cause your credit score to drop significantly. The exact impact varies depending on various factors, including the credit scoring model being used, the individual’s existing credit history, and the amount of the debt.
  3. Duration of Impact: A collection account due to medical debt default can remain on your credit report for up to seven years from the date of the original delinquency. This means that even if you pay off the debt, the negative mark can still remain on your report and potentially affect your credit score for several years.
  4. Newer Scoring Models: Some newer credit scoring models, like FICO Score 9 and VantageScore 4.0, treat medical collection accounts differently than non-medical ones. They often weigh medical collections less heavily than non-medical collections, acknowledging that medical debt can sometimes be incurred through no fault of the consumer.
  5. Credit Utilization Not Affected: Medical debts do not affect your credit utilization ratio since they are not tied to revolving credit accounts like credit cards. Credit utilization is a significant factor in credit scores, but medical debt impacts scores through its presence as a collection account.
  6. Negotiating with the Collection Agency: Sometimes, you may be able to negotiate with the collection agency to have the account removed from your credit report once it’s paid. This is known as “pay for delete”. However, not all collection agencies will agree to this.
  7. 180-Day Waiting Period: As per the changes made by the three major credit bureaus (Experian, TransUnion, and Equifax) some time ago, medical debts won’t be reported until after a 180-day waiting period to give individuals enough time to resolve the debts with insurance and healthcare providers.

If you encounter medical debt issues, it’s important to communicate openly with your healthcare provider and insurance company, and if necessary, seek advice from a consumer credit counselor or attorney.

Filed Under: Debt Recovery

Why Medical Debt Recovery Requires a Specialized Approach


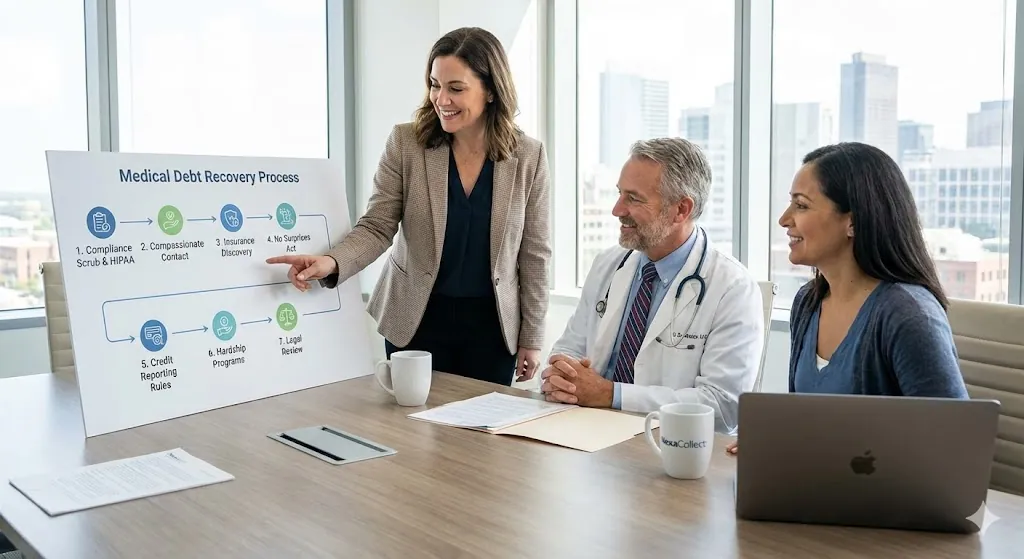
The Specialized Blueprint: How a Medical Collection Agency Works

Recovering medical debt is a high-stakes balancing act between financial recovery and strict federal compliance. Unlike standard B2B or retail collections, medical recovery is governed by a complex web of privacy laws and patient protection acts. A specialized medical collection agency doesn’t just ask for money; it manages a patient-provider relationship with extreme care.

Nexa provides a reputation-safe approach, equipped with all 50-state collections license, offering free credit reporting, free litigious debtor check, free bankruptcy scrub, and zero onboarding fees. Secure – SOC 2 Type II & HIPAA compliant. Over 2,000 online reviews rate us 4.85 out of 5. 

Need a Medical Collection Agency? Contact us

Phase 1: Compliance Scrub & HIPAA Verification

The process begins with a rigorous data audit. Before any contact occurs, we ensure that all transmitted data is encrypted and HIPAA-compliant. We verify that only the “Minimum Necessary” information is shared to avoid privacy violations, ensuring that a patient’s sensitive medical history is never compromised during the recovery process.

Phase 2: The Compassionate Contact Model

Medical debt is often unexpected and stressful. Our approach differs from standard recovery by using a “Human-First” communication style. We focus on empathy and education, helping patients understand their statements and insurance EOBs (Explanation of Benefits). This firm yet respectful approach reduces friction and prevents patient complaints against the provider.

Phase 3: Insurance Discovery & Billing Correction

A significant portion of medical “debt” is actually a billing error or an unsubmitted insurance claim. A specialized agency performs Insurance Discovery—checking for active coverage that the patient may have forgotten to provide. We often resolve the “debt” by simply getting the right information to the payer, rather than the patient’s pocket.

Phase 4: Adhering to the No Surprises Act & 501(r)

Medical collections are bound by specific laws that don’t apply to general debt:

  • The No Surprises Act: We ensure that “surprise” out-of-network bills are handled according to federal dispute resolutions.

  • Section 501(r) Compliance: For non-profit hospitals, we ensure that “Extraordinary Collection Actions” (ECAs) are only taken after the required 120-day notification period and after checking for financial assistance eligibility.

Phase 5: The Medical Credit Reporting “Lockout”

Credit reporting in medical collections is no longer a grey area; it is heavily restricted. Also in many states its prohibited all together.

  • Threshold Rules: Medical debts under $500 are generally prohibited from appearing on credit reports.

  • The Waiting Period: Agencies must wait one year before reporting a medical debt to allow time for insurance processing.

  • Removal Mandate: Once a medical debt is paid, it must be removed from the credit report entirely, unlike other debts that stay for seven years.

Phase 6: Professional Mediation and Hardship Programs

If a patient is genuinely unable to pay, we facilitate Hardship Applications. By identifying patients who qualify for charity care or sliding scale fees, we help the provider clear the balance through appropriate channels, maintaining the provider’s community standing while resolving the account.

Phase 7: Advanced Skip Tracing & Legal Review

If a patient has moved without notice, we use specialized skip tracing to find updated contact details. If a balance is significant and the patient has the means to pay but refuses, we conduct a “suit-suitability” review, ensuring any legal recommendation follows the specific medical litigation laws of your state.


How Medical Recovery Differs from Standard Debt

Feature Standard Collections Medical Collections
Primary Law FDCPA FDCPA + HIPAA + No Surprises Act
Data Privacy Standard encryption Strict PHI (Protected Health Information) protocols
Credit Reporting Reported after 30 days 365-day wait; $500 minimum threshold
Paid Debt Remains on report as “Paid” Must be deleted from report immediately
Goal Fastest recovery of funds Recovery + Protection of Patient Relationship

Secure Your Revenue – Contact Nexa Today

Filed Under: Debt Recovery

The AI Revolution in Debt Recovery: Efficiency, Compliance, and ROI

The debt collection industry is undergoing a seismic shift. As debt portfolios grow and consumer behaviors change, traditional “dial-and-hope” strategies are becoming obsolete. Artificial Intelligence (AI) is no longer a futuristic concept—it is the current standard for high-performing agencies.

Here is how AI is transforming debt recovery, boosting liquidation rates, and ensuring compliance.

1. Automated Communication & 24/7 Availability

AI-powered chatbots and virtual assistants never sleep. They can handle up to 80% of initial debtor interactions, resolving routine queries instantly without human intervention. Unlike human agents, AI maintains a consistent, professional tone regardless of the time of day. This consistency has been shown to improve customer engagement rates by approximately 35%, as debtors can get answers immediately rather than waiting on hold.

2. Omnichannel Orchestration

Modern debtors ignore unknown calls but often respond to texts or emails. AI doesn’t just call; it coordinates a “surround sound” approach. If a debtor ignores an email, the AI can automatically schedule an SMS 48 hours later, followed by a WhatsApp message. This coordinated effort ensures you meet the debtor where they are, increasing contact rates by up to 27%.

3. Advanced Data Analysis & Predictive Profiling

AI moves beyond basic spreadsheets to analyze unstructured data—including call logs, email sentiment, and payment history—to build 360-degree debtor profiles. By processing this data, AI can predict the probability of repayment with 90%+ accuracy. This allows agencies to prioritize efforts on high-value accounts rather than wasting hours on uncollectible debt.

4. Drastic Reduction in Operational Costs

While implementing AI requires an initial investment, the long-term savings are massive. By automating manual dialing, data entry, and skip tracing, agencies report operational cost reductions ranging from 40% to 70%. This efficiency protects margins in an industry where commission rates are often squeezed.

5. Instant Scalability (Elastic Capacity)

One of the biggest challenges in collections is staffing for volume spikes. AI solves this with “elastic capacity.” Whether you receive a new portfolio of 1,000 or 100,000 accounts, the system scales instantly. You avoid the 3-to-6-month lag time typically required to hire, train, and license new human agents.

6. Hyper-Personalized Debt Management

One-size-fits-all demand letters rarely work. AI analyzes a debtor’s income stability and spending habits to generate personalized repayment plans. By offering a plan that fits the debtor’s specific financial reality, agencies are seeing acceptance rates increase by 3x compared to generic demands.

7. Self-Service Empowerment

74% of consumers prefer to resolve financial matters digitally without speaking to a human. AI-driven portals allow debtors to negotiate terms and set up payments at 2 AM on a Sunday. This captures revenue that traditional 9-to-5 agencies would simply miss.

8. Early Risk Assessment & Skip Tracing

Time is the enemy of recovery. AI uses “propensity-to-pay” scoring to identify high-risk accounts immediately—such as those likely to file for bankruptcy or skip town. This allows agencies to intervene weeks earlier than manual review processes would allow, securing assets before they disappear.

9. Real-Time Compliance & Legal Support

In a litigious environment, AI is your best defense. It acts as a 24/7 compliance officer, capable of auditing 100% of calls in real-time (compared to the industry standard of 1-3%). It can flag potential FDCPA violations or missing “Mini-Miranda” warnings instantly, stopping a lawsuit before it happens.

10. Speech & Sentiment Analysis (The Empathy Engine)

AI can now “listen” for emotions. Real-time sentiment analysis warns agents if a debtor is becoming hostile or distressed. This prompts the agent to change tactics or de-escalate, reducing complaint volumes by up to 50% and preserving the agency’s reputation.

11. Predictive Modeling for Timing

AI eliminates the guesswork of when to call. Machine learning models analyze historical data to determine that Debtor A is most likely to answer on Tuesdays at 6 PM, while Debtor B responds to emails on Saturday mornings. This precision timing drives a 20-25% increase in liquidation rates.


The Guardrails: Where Compliance Limits AI

While AI is powerful, it is not a “wild west” tool. Government regulations (such as the FDCPA, Reg F, and ECOA) impose strict limits to prevent abuse.

  • Frequency Limits (Reg F): AI auto-dialers must adhere to the “7-in-7” rule. Calling a debtor more than 7 times in 7 days is considered harassment. AI systems must be calibrated to hard-stop dialing once this limit is reached to avoid hefty fines.

  • The “Black Box” Problem (ECOA): Agencies must be able to explain why an adverse decision was made (e.g., rejecting a settlement offer). If an AI makes a decision based on opaque algorithms (“The computer said no”), it may violate the Equal Credit Opportunity Act. Human oversight is required to explain decisions.

  • Consent & TCPA: AI cannot send automated texts or prerecorded voicemails to mobile phones without express prior consent. “Blast” campaigns without verified consent are the fastest route to a class-action lawsuit.

  • Disclosure of Identity: An AI chatbot must disclose that it is an automated system. Attempting to pass an AI off as a human lawyer or officer to intimidate a debtor is a deceptive practice under the FDCPA.

  • Contextual Blindness (Safety & Legal Stops): AI lacks “environmental awareness.” A human agent can hear traffic noise and ask, “Are you driving?”—immediately terminating the call to prevent liability. AI might plow through a script while a debtor is behind the wheel. Similarly, humans can better detect critical stops, such as a debtor being hospitalized or mentioning attorney representation, where continuing the conversation is not just unethical, but legally dangerous.

Conclusion

AI in debt recovery is not about replacing humans; it is about freeing them to do what they do best—negotiate complex accounts—while the machines handle the routine volume. Agencies that adopt these tools today will define the market of tomorrow.

Filed Under: Debt Recovery

Optimum Speed to Assign Debts to a Collection Agency

Large clients often assign hundreds ( even thousands) of accounts to a collection agency in one go. This large batch is usually their past-due inventory accumulated over the years. 

Suppose a client submits a batch of 1000 accounts to the collection agency. These accounts are assigned to multiple debt collectors who will start sending collection demands or making phone calls to your debtors. All your 1000 accounts are acted upon in a matter of days. What happens next catches most clients by surprise.

Roughly one hundred concerned debtors will begin calling the client directly ( to pay, dispute the debt, complain, or other reasons). Although (in most cases) the debtor is directed to call the collection agency and not the client, a small percentage of debtors still call the client ( say 10% of the total assignments).

The front-line person in the client’s office receiving these debtor calls quickly gets overwhelmed (at least temporarily. say for a week). This high inbound call volume catches the client by surprise.

Although the client will collect a lot of money quickly, they will surely need additional hands to cope with these debtor calls and inform the collection agency about the payments they received for these accounts. You must also post an update in your internal accounting software (like Quickbooks).

There are two ways to handle this situation:

  1. Before a client submits a large batch of accounts, they should dedicate more resources for inbound calls for at least a few weeks till the inbound call volume tapers down to a nominal level. This is the preferred approach.
  2. Assign only 200 accounts to start with. This will keep your inbound call volume low, then increase/decrease the submission size the following week.

Filed Under: Debt Recovery

  • « Go to Previous Page
  • Page 1
  • Interim pages omitted …
  • Page 17
  • Page 18
  • Page 19
  • Page 20
  • Page 21
  • Interim pages omitted …
  • Page 55
  • Go to Next Page »

Primary Sidebar


accounts receivable

Need a Collection Agency?
Kindly fill this form.
We’ll get in touch with you

    Please prove you are human by selecting the key.

    Compliance & Security

    • SOC 2 Type II Certified: Third-party audited data security and strict privacy controls.

    • HIPAA Compliant: Secure, legal processing of medical and municipal EMS accounts.

    • PCI-DSS Level 1: Highest tier of data encryption for secure payment processing.

    • FDCPA & FCRA Aligned: Full legal adherence to federal consumer protection laws.

    Recent Posts

    • Why Dental Patients Dispute Bills: The Nexa Collections Dental Account Dispute Index
    • 2027 Commercial Collections Benchmark: U.S. Late Payments, AR Risk and B2B Collection Trends
    • Bulk Account Placement: What a Collection Agency Actually Needs From You
    • Nationwide Debt Collection Agency Serving U.S. Cities
    • Chula Vista Collection Agency for Medical, B2B, Schools & Business Debt
    • Corpus Christi Collection Agency: Itemized Bill Rules for Practices
    • Riverside Collection Agency | For Logistics, Medical, Schools & Business Recovery
    • Collection Agency for Large Balances: High-Value B2B Debt Recovery

    Featured Posts

    • The Auction-Trap: Why Selling Their Stuff is Costing You Thousands
    • Managing Stress when Running a Small Business
    • Negative Impact of Buy Now Pay Later Schemes

    Copyright © 2026 NEXACOLLECT.COM | This content is provided for general informational purposes only and should not be considered legal advice. Collection laws and requirements may vary by state, account type, documentation, debtor status, and specific facts. Please consult qualified legal counsel for guidance regarding your particular situation. Nexa and its authorized collection partners service accounts in accordance with applicable federal and state collection requirements. Visit our home page to know more about us.

    X
    Need a Collection Agency?
    Contact Us