• Skip to main content
  • Skip to primary sidebar

Nexa Collections

  • Home
  • Serving
    • Medical
    • Dental
    • Small Business
    • Large Business
    • Commercial Collections
    • Government
    • Utilities
    • Fitness Clubs
    • Schools
    • Senior Care Facility
  • Contact Us
    • About us
    • Cost

Debt Recovery

Pay in Installments or Full: Which is Better?

A debt collector lets you make payments in installments or a one-time total amount. Which one should the borrower go for?

Benefits of Paying in Full (in one lump sum payment)

  • You can almost always strike a deal to settle the debt for a lower amount (keep insisting). Installments result in more work for collection agencies. They would rather accept a lower amount ( like a 10% or a 20% lower settlement and waive off all interest and extra charges) than work on your debt for months. Moreover, if a borrower skips an installment in the future, it results in even more work for them.
  • Peace of mind. The matter is closed, and those pestering collection calls end.
  • If you have cash available or can arrange it, then closing the matter in one lump sum payment is best rather than dragging the case. Debt collectors are persistent callers. They get paid a commission on whatever you pay and will keep bugging you until the payment is made. 

Benefits of paying in installments

  • The borrower who pays in installments has effectively communicated to the debt collector that he does not have much money in the bank. He is genuinely tight on cash. He can usually settle the deal on the principal amount only and avoid paying any additional interest and fees.
  • It gives more time to pay and avoids immediate cash flow problems. 

Benefits of Both (Installments and Full Payment):

  • You avoid damaging your credit report.
  • No more harassment from collection agencies or their lawyers.
Filed Under: Debt Recovery

Impact of Russia-Ukraine war on Accounts Receivables

The Russia-Ukraine war will undoubtedly translate to higher consumer and commercial delinquencies. 

Here are several reasons for it:

  • Due to higher gas prices, everything has become expensive. Consumers need to shell out money on essential goods (like food, gas, clothes, expenses related to kids, etc.), and debt is something most people tend to put on the back burner. 
  • For the majority of the American population, salary increase has failed to keep up with rising inflation. 
  •  Commercial businesses have also been struggling with supply chain issues due to the covid restrictions in China; further increase in input costs due to the Russia-Ukraine war has resulted in severe financial stress. They are either not able to produce goods in required quantities or not able to always pass the increased costs to their customers.
  • Many analysts predict that we are on the verge of an economic recession, the job market that has been very healthy so far can very well break the trend as corporations and small businesses may try to cut costs by laying off employees.
  • Many people are saving money in cash, citing uncertainty.

The urgency for medical practices and small businesses to protect themself against unpaid bills is crucial. Before the financial situation of your debtor becomes worse, it is highly advisable to hire a collection agency and attempt to recover your money. The probability of recovering receivables goes down drastically each month, therefore prompt and intensive steps are sometimes necessary.


Filed Under: Debt Recovery

Making Medical Credit Reporting Harder is a Disaster in the Making

We all agree that healthcare costs in the USA are incredibly high.

Most doctors (and dentists) who do private practice struggle to cope with never-ending government regulations and mandates, a constant fear of frivolous lawsuits, dealing with insurance companies, and loss due to unpaid patient bills. The medical profession is among the most stressful careers out there.

Back to our core topic of medical debts and credit reporting of medical bills, here are our thoughts on this matter.

Regardless of the balance, reporting all unpaid bills to credit bureaus as the final step does two main things.

1. Inform future creditors about bills on which a person has defaulted so they can assess their own risk to lend money to that person.
2. It gives a chance to the borrowers to pay off their bills so that the concerned credit report entry can be marked as “Paid in full.” Paying off reported bills helps borrowers to improve their credit scores instead of leaving them unpaid.

But all this is changing, “only” for medical debts.

Credit bureaus have implemented these new rules:

a) Stop reporting medical debts lower than $500
b) Remove medical line items that have been fully paid
c) Collection agencies must wait one year before medical debts can be reported.

In the last few years, there has been a pushback on how medical bills are reported. These include government rules, credit scoring models, and even credit bureaus have made their own rules.

All these create roadblocks for medical credit reporting, encouraging patients to avoid paying their bills.

Debt is a debt … Shouldn’t all unpaid defaults ( medical or otherwise) be reported to credit reports in the same way?

Then let the lenders decide which one they want to consider or ignore.

Forcefully suppressing unpaid medical debts from credit bureau reporting will undoubtedly result in many unintended consequences.

  •  Fewer patients would be willing to pay their medical bills. Even those who can pay may decide not to pay in the future.
  •  The cost of unpaid bills will be passed to patients who can pay.
  • Won’t hospitals be encouraged to push patients for procedures with a higher chance of getting paid?
  •  This also means that the cost of medical treatments will increase gradually.
  •  Some medical practices may try to intentionally inflate the cost of specific treatments so that accounts receivable from patients is over $500 so that they can be reported to the credit bureaus.
  • On the other side, even patients may very well pay a portion of their medical bills, so the outstanding amount is less than $500. Now default on the remaining amount since there is no risk of credit reporting for amounts lower than $500.
  • How is medical debt different from any other bill? Why does defaulting on one type of bill differ less from other kinds of bills? Isn’t this increasing the risk for future creditors who will lend money to the patient without knowing that the patient had past unpaid (medical) bills?

For example: What if a patient who owes $10,000 in medical bills wants to take a $500,000 home loan? Now he purposefully pays his old $10,000 medical bill to remove it from his credit report. Then he can qualify for a $500,000 loan. Wouldn’t this increase the risk of the bank/credit union with whom he takes that mortgage?

Suppressing how medical reports are reported to the credit bureaus will surely increase the cost of healthcare, more defaults, more legal mess, and higher risk for future creditors.

Filed Under: Debt Recovery

Standard RFP Requirements for Hiring a Collection Agency

Are you a large or even a mid-sized company, college, hospital, or government entity? In that case, you should always ask all collection agencies seeking your business to fill out Request-For-Proposal (RFP) document provided by you. 

Benefits of asking to fill out your RFP

  • It helps select a collection agency that takes your client’s data seriously and commits to keeping it secure.
  • Follows all federal and local laws when working on your accounts.
  • It gives you a clear picture of whether they utilize other entities with whom your data will be shared during the collection process.
  • It protects you from any legal issues that may arise in the future.
  • Other benefits include competitive pricing, quality assessment, defining your needs and objectives, legal compliance, and risk assessment.

Here are essential points to include in your RFP questionnaire.

  1. Is their collection agency nationally licensed or not? (If not, which all states are you licensed in?)
  2. What services do they offer? Check all those which apply (Collection Letters, Collection Calls, and Legal).
  3. What are the fees for each of the above services and payment methods?
  4. Ask if they have the resources to handle the volume of data you would be submitting.
  5. How long have they been in business?
  6. Do they have a secure portal for submitting accounts?
  7. List all security certifications they have (Like SSAE / SOC / HIPAA etc.?)
  8. Are they GLBA compliant? (Important),
  9. Provide a workflow/chart of their collection process and if there are any other entities with whom your data will be shared.
  10. Can the accounts be uploaded in a batch using an Excel spreadsheet?
  11. Can they provide references (or names) of clients similar to our company? What is your average collection rate for our industry?
  12. Are their debt collectors regularly trained for debt collection laws like FDCPA/TCPA/HIPAA/State Legislation?
  13. What if the remittance frequency (for the amount collected by the collection agency)?
  14. Do they provide monthly collection status reports for all accounts?
  15. Which subcontractors/vendors are involved in performing your services? Do they also handle the debtor data securely as well?
  16. Are your company operations located overseas, or are you a 100% USA-based company?
  17. In case of a debtor dispute or litigation, what is your procedure? Do you have liability insurance against such disputes? Attach the proof. 
  18. In case of service issues, who will be our point of contact from the senior management?
  19. In case of disagreement, can we withdraw all our accounts from you? Are there any exceptions?
  20. Do you offer both B2B and B2C collections?


Filed Under: Debt Recovery

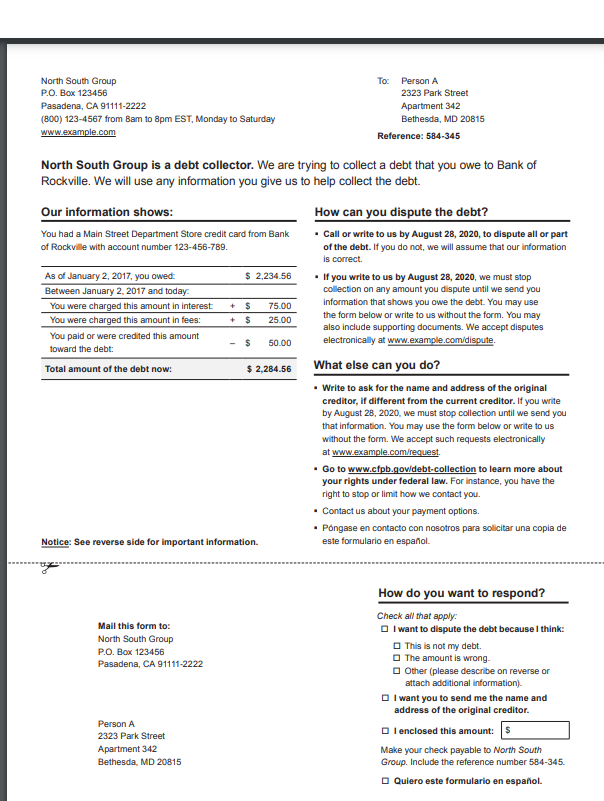
Debt Validation Notice Format Recommended by CFPB

By law, all debt collectors are required to provide at least 30 days to the debtor/consumer to dispute the debt, after the consumer receives (or is assumed to receive) the validation information. Most collection agencies will add about additional 2 weeks to account for mailing delays and holidays.

This format is located here:
CFPB Debt Collection Validation Notice R19  ( as of Nov 2021)
https://files.consumerfinance.gov/f/documents/cfpb_model-validation-notice_2020-12.pdf

Debt Validation Notice

These are the standard options available to dispute the debt:

Check all that apply:
I want to dispute the debt because I think:
* This is not my debt.
* The amount is wrong.
* Other (please describe on reverse or attach additional information).
* I want you to send me the name and address of the original creditor.

Collection agencies not following this exact format risk safe harbor and may possibly get sued by attorneys.

They may additionally add page 2, which essentially says:

This notice is to inform you the consumer that this debt was assigned to ABC collection agency and they will not take any action from XX days from the date of this letter. 

( XX days can vary depending on the policy of the collection agency – Say 45 days or 60 days)


Filed Under: Debt Recovery

Effect of Inflation on Unpaid Bills and Debt Recovery Rate

Inflation translates to higher accounts receivable and unpaid bills. Wage growth does not keep up with rising prices for most consumers.

Whenever there is a spike in inflation, interest rates rise. This translates to higher delinquencies for credit card bills and more people unable to pay their mortgages. Consumers divert their finances towards more necessary expenses like food and rent over other bills obligated to pay but feel they can be deferred.

Doctors suddenly see more patients defaulting on their payment plans. More people are unable to pay their car installments. A higher number of people are filing for bankruptcy. The list goes on.

Nearly 50% more people face financial problems whenever there is a significant rise in inflation. They are now paying more for food, fuel, and almost all essential things people need daily.

It is vital to recover your share before your debtor’s financial condition deteriorates further to improve your chances of getting paid during inflation. So whenever your AR is over 60-90 days past due, hire experts – Hire a collection agency.

Effect of Inflation on Unpaid Bills

  1. Eroding Real Value: If there is inflation, the real value of the money owed decreases over time. This means that when a debtor pays back a bill after a period of inflation, the creditor receives money that has less purchasing power than it did at the time the debt was incurred.
  2. Interest Rates: Inflation often leads to higher interest rates. If the unpaid bills carry a variable interest rate, the amount owed might increase faster due to inflation, making the debt more expensive to repay.
  3. Cost of Living: For individuals, inflation increases the cost of living, as the prices for goods and services rise. This might make it more difficult for people to pay off their bills, as a larger portion of their income might be required for everyday expenses.
  4. Business Costs: For businesses, inflation can increase the cost of materials, labor, and other expenses. If a business has unpaid bills, the rising costs might make it more difficult to allocate funds for paying off these debts.
  5. Credit Score Impact: If individuals or businesses cannot keep up with their bills due to inflation eroding their real income or increasing their expenses, this can lead to late payments or defaults, negatively affecting their credit scores.
  6. Debt Reassessment: In a high-inflation environment, creditors might be more cautious about extending credit, and may reassess the creditworthiness of their debtors. This can lead to reduced credit limits or tighter lending standards, which can affect the ability to pay bills.
  7. Payment Prioritization: When prices rise rapidly, individuals and businesses might prioritize which bills to pay and may postpone or neglect payments that are not considered critical.

Filed Under: Debt Recovery

  • « Go to Previous Page
  • Page 1
  • Interim pages omitted …
  • Page 20
  • Page 21
  • Page 22
  • Page 23
  • Page 24
  • Interim pages omitted …
  • Page 55
  • Go to Next Page »

Primary Sidebar


accounts receivable

Need a Collection Agency?
Kindly fill this form.
We’ll get in touch with you

    Please prove you are human by selecting the car.

    Compliance & Security

    • SOC 2 Type II Certified: Third-party audited data security and strict privacy controls.

    • HIPAA Compliant: Secure, legal processing of medical and municipal EMS accounts.

    • PCI-DSS Level 1: Highest tier of data encryption for secure payment processing.

    • FDCPA & FCRA Aligned: Full legal adherence to federal consumer protection laws.

    Recent Posts

    • Why Dental Patients Dispute Bills: The Nexa Collections Dental Account Dispute Index
    • 2027 Commercial Collections Benchmark: U.S. Late Payments, AR Risk and B2B Collection Trends
    • Bulk Account Placement: What a Collection Agency Actually Needs From You
    • Nationwide Debt Collection Agency Serving U.S. Cities
    • Chula Vista Collection Agency for Medical, B2B, Schools & Business Debt
    • Corpus Christi Collection Agency: Itemized Bill Rules for Practices
    • Riverside Collection Agency | For Logistics, Medical, Schools & Business Recovery
    • Collection Agency for Large Balances: High-Value B2B Debt Recovery

    Featured Posts

    • Customer Relationship Management for Small Business
    • Debt Collection Laws and Agencies in Germany
    • Wellness Industry Collections: Protecting Your Revenue and Your Reputation

    Copyright © 2026 NEXACOLLECT.COM | This content is provided for general informational purposes only and should not be considered legal advice. Collection laws and requirements may vary by state, account type, documentation, debtor status, and specific facts. Please consult qualified legal counsel for guidance regarding your particular situation. Nexa and its authorized collection partners service accounts in accordance with applicable federal and state collection requirements. Visit our home page to know more about us.

    X
    Need a Collection Agency?
    Contact Us