• Skip to main content
  • Skip to primary sidebar

Nexa Collections

  • Home
  • Serving
    • Medical
    • Dental
    • Small Business
    • Large Business
    • Commercial Collections
    • Government
    • Utilities
    • Fitness Clubs
    • Schools
    • Senior Care Facility
  • Contact Us
    • About us
    • Cost

Debt Recovery

Ex-Employee Debt Recovery: How to Get Back Equipment, Overpaid Wages & Perks

Ex-employee debt recovery is the process of recovering money or company property that a former employee owes an employer, including unreturned equipment, overpaid wages, unearned advances, unreconciled expenses and other documented balances, through itemized written demands, skip tracing, negotiation and, where warranted, legal escalation.

Quick answer: Yes, a collection agency can pursue most of what a former employee owes you, as long as it’s documented and not genuinely disputed: unreturned laptops and phones (or their value), overpaid wages, unearned advances, company-card balances and agreed repayments. The catch is payroll. Many states sharply limit what an employer can take from a final paycheck, so recovery often has to happen outside payroll, through a return-first, itemized demand. Polite, documented and fast beats aggressive every time.
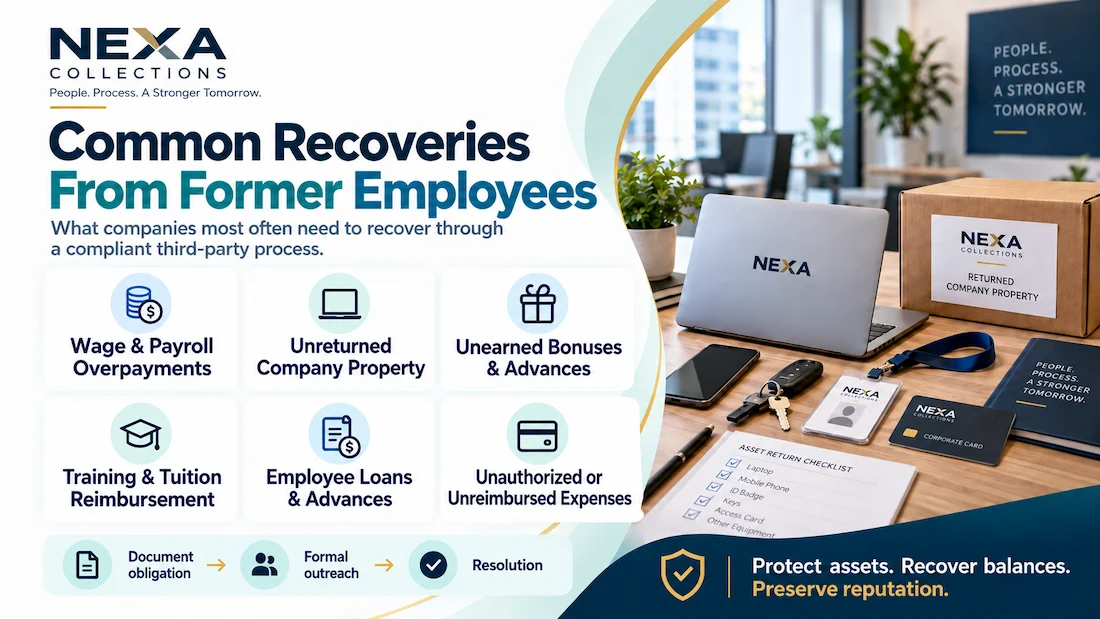
Infographic showing common recoveries from former employees, including payroll overpayments, unreturned company property, bonuses, tuition reimbursement, employee loans, and unauthorized expenses.

The laptop is in a closet in Tucson. The overpayment is sitting in a checking account in Ohio. And the person who has both stopped answering email. Now what?

If you run payroll, IT or a growing team, you know this account. It’s too small to justify a lawsuit and too big to write off quietly. And it isn’t rare. U.S. employers recorded about 5.1 million separations in July 2026 alone, roughly 3.1 million of them quits (BLS). Capterra’s offboarding survey of nearly 300 HR professionals found that 71% had seen at least one departing employee fail to return company equipment, that hybrid and remote workers were 17% more likely to keep it, and that the average haul was worth $1,963. (The survey dates from 2022, so treat it as a directional benchmark, not a 2026 measurement.)
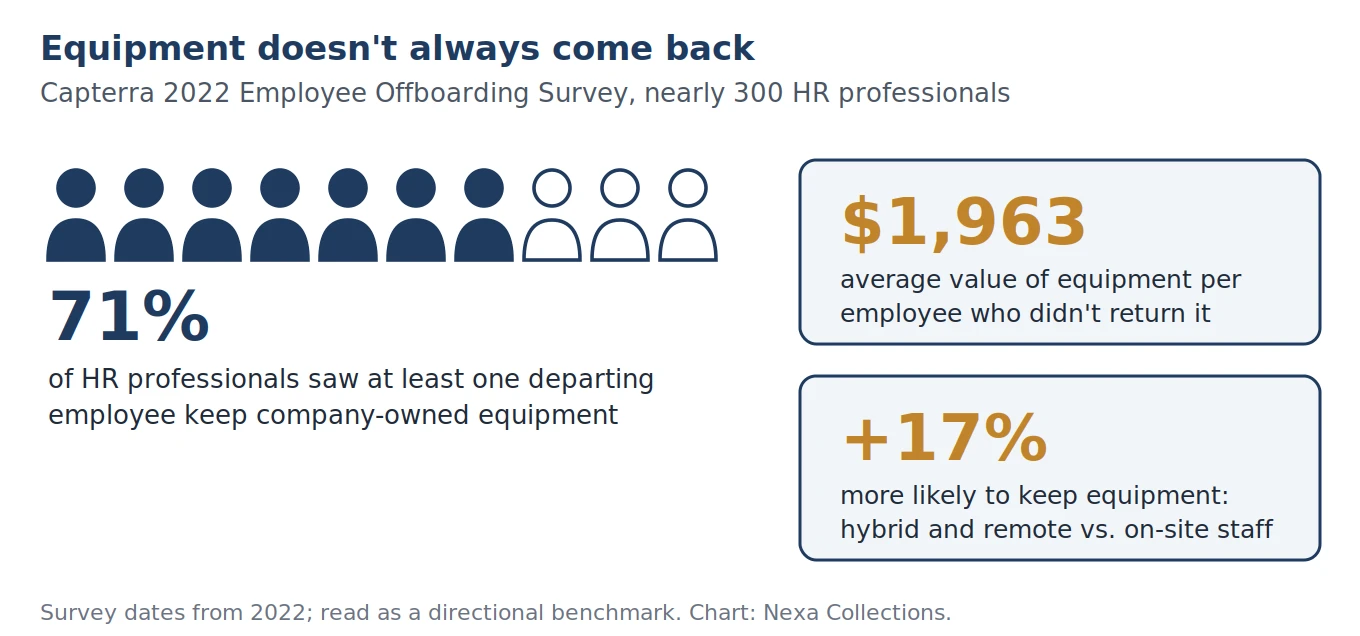
71% of HR professionals saw at least one departing employee keep company-owned equipment

Most departures end cleanly. The ones that don’t share a pattern: nobody asked in writing, nobody itemized the balance, and by the time someone noticed, the trail was cold. This guide fixes that.

Need a Collection Agency? Contact us


What a Collection Agency Can Recover From a Former Employee

If the obligation is documented and the employee hasn’t raised a genuine dispute, most of the following can be pursued:

What’s owed Typical examples Have this in hand Watch out for
Company equipment Laptops, phones, tablets, monitors, tools, badges, keys, fuel cards Asset log with serial numbers, signed receipt, written return requests Ask for the item back first. If you bill for it, use a defensible value, such as depreciated ledger value, not a new-for-old price tag
Overpaid wages and payroll errors Duplicate pay, wrong rate, pay after separation, miscalculated PTO payout Pay records, a plain-language correction notice, the math Deduction rules for final pay vary by state. Overpayments that cross a tax year add payroll-tax steps, so loop in payroll first
Unearned advances and draws Pay advances, commission draws, negative commission balances A signed advance or draw agreement and the ledger Commission clawback rules are state-specific
Bonus, relocation, training or tuition repayment Sign-on bonus, relocation package, certification costs A signed repayment agreement with clear terms Newer “stay-or-pay” laws restrict many of these. See below
Company-card and expense balances Personal charges, unreconciled advances, missing receipts Card statements, the expense policy, signed acknowledgment Give a reasonable chance to reconcile before treating it as a debt
Perks and stipends paid but not earned Fitness or wellness stipends, phone, internet and home-office allowances, certification fees A written policy that clearly ties the perk to continued employment A vague perk isn’t a debt. The policy has to say so
Employee loans and purchase balances Payroll loans, employee purchase plans, installment arrangements A signed note or installment agreement Written terms matter, and the balance should match them exactly
Benefit premiums advanced during leave The employee’s share of premiums the employer fronted Leave records and a written agreement Only where the law and the agreement allow recovery

What Isn’t a Collection Matter

An agency recovers money and property. It doesn’t replace employment counsel when the problem is something else:

  • Trade secrets, confidential files or customer lists. Time-sensitive and legal. Call counsel the same day.
  • Non-compete, non-solicit or confidentiality breaches. Contract enforcement, not debt.
  • Damage claims that depend on proving fault or misconduct. A court or counsel decides those.
  • Theft or criminal reports. That’s a decision for you and counsel, not an agency.
  • Anything you owe them. Earned wages, required PTO payouts and expense reimbursements get paid. Netting them against a debt is the shortcut that costs the most.

The Final Paycheck Trap

Here’s what catches most employers: the instinct is to recover the money from the last paycheck. In many states, that’s exactly what you can’t do.

Federal law doesn’t require final pay to be handed over immediately (the Department of Labor says so plainly), but states can, and many set tighter deadlines. Federal rules also generally let employers deduct for lost or unreturned items from non-exempt employees only if the deduction doesn’t push pay below minimum wage or eat into overtime. State rules then layer on top:

Jurisdiction General position on deducting debts or equipment from final pay
Federal (FLSA) No immediate-payment requirement. For non-exempt employees, deductions can’t cut pay below minimum wage or into overtime
California Among the strictest. The Labor Commissioner’s long-standing position is that debts can’t be offset against final wages, and equipment-loss deductions are tightly limited. Withheld or late final pay can trigger waiting-time penalties
New York Deductions are limited to specific categories, with notice, timing and cap rules for recovering overpayments. Unreturned equipment isn’t a typical permitted category
Illinois Generally requires the employee’s express written consent given freely at the time of the deduction. Hiring paperwork alone typically isn’t enough
Other states Anywhere from an outright prohibition to a written-authorization requirement to little beyond the federal baseline

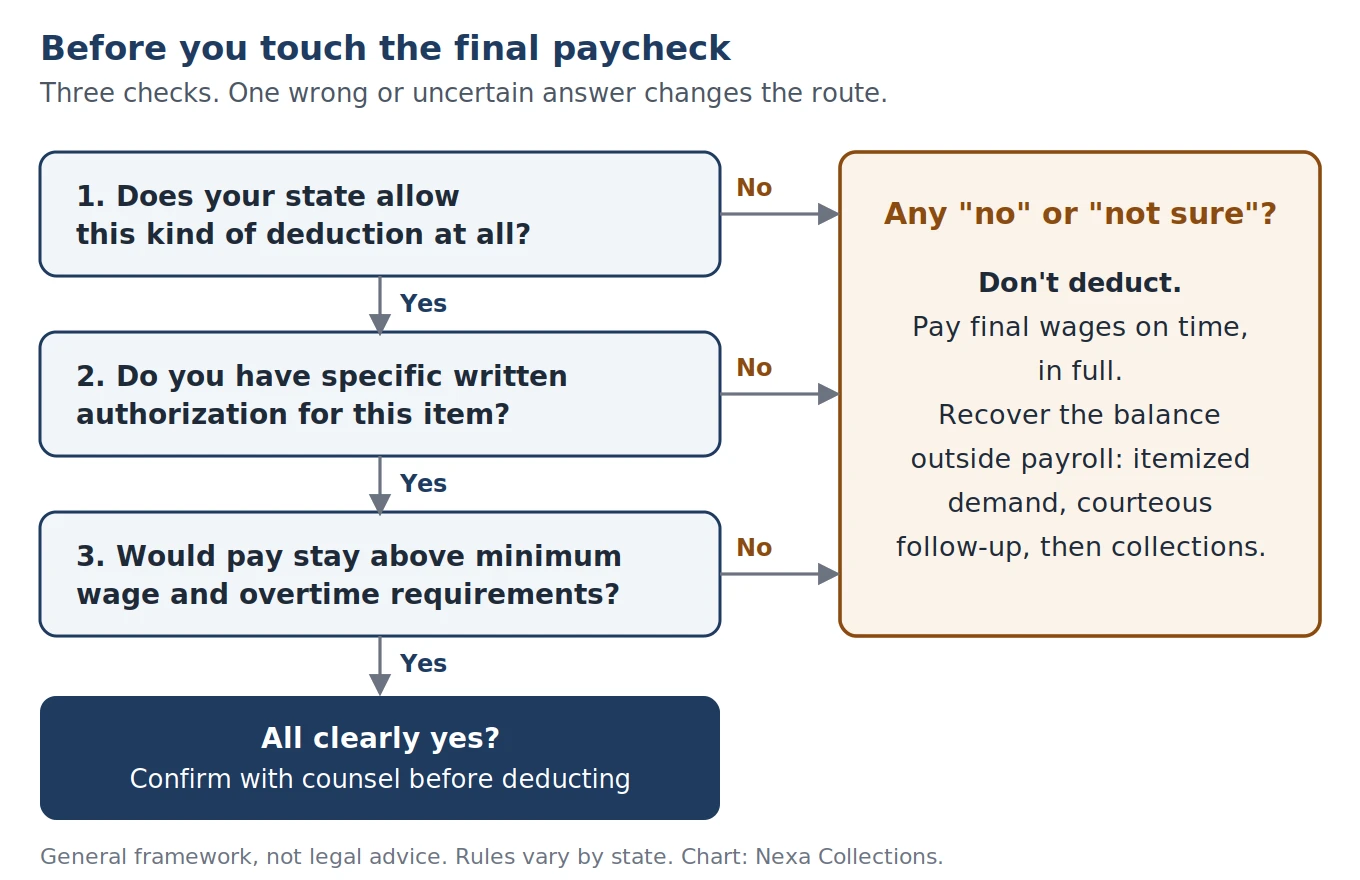
Before you touch the final paycheck - Three checks. One wrong or uncertain answer changes the route.

If any answer is no or unsure, don’t deduct: pay final wages on time and recover the balance outside payroll.

The fix is simple, even if it’s counterintuitive: pay final wages on time and in full, then recover the balance outside payroll. The debt doesn’t disappear because you can’t deduct it. It just needs a different route: an itemized written demand, a courteous follow-up and, when needed, a professional collection effort. Withholding or deducting wrongly can cost far more than the laptop.


Return First, Then Pay

When the debt is equipment, the goal isn’t a payment. It’s the device. A refund of its value is plan B.

  1. Make returning it easy. A prepaid label, a box, a deadline and a single contact person. Many unreturned laptops are just unreturned because shipping one is a hassle.
  2. Cut access on day one, separately from recovery. Revoke accounts, VPN and device management the day the person leaves. Don’t wait for the hardware. In the Capterra survey, only 55% of the HR professionals who reported unreturned equipment containing sensitive information said they could completely lock the employee out. Our guide to data privacy and security for collection agencies covers what to expect from a partner that handles personnel and device records.
  3. Offer both doors. Return the device by a date, or pay its documented value by a later one. People who won’t write a check will often ship a box.
  4. Put the escalation in writing. Each request should restate what’s owed, how it was calculated and what happens next.
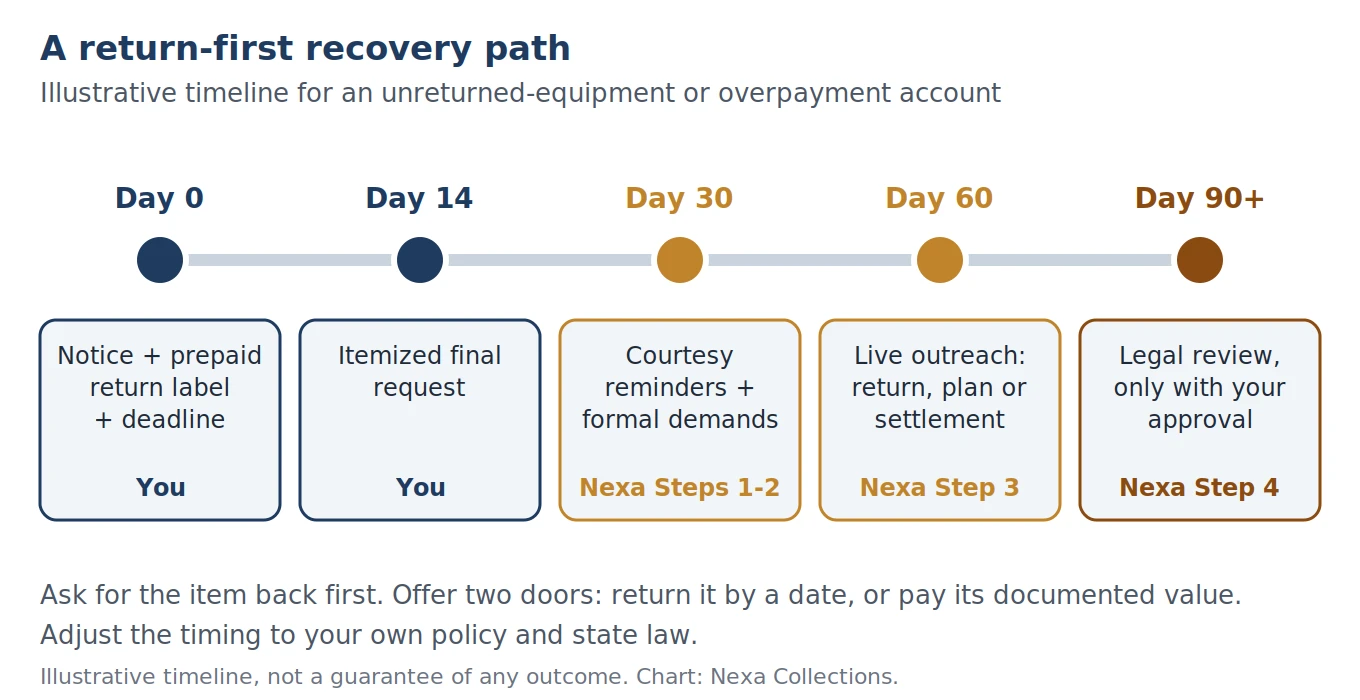
timeline for an unreturned-equipment or overpayment account

A return-first path: ask in writing, itemize, then add professional follow-up in steps. Timing is illustrative.

Not sure when an account is ready to leave your desk? These usually mean it is:

  • Two written requests have gone unanswered.
  • The balance is itemized and the documents are in one place.
  • The employee hasn’t raised a specific dispute.
  • Chasing it is costing your team more than it’s worth. (Our comparison of in-house collections vs. an agency walks through that math.)

If the person has simply gone quiet, see how skip tracing finds a current address and phone number and what changes when a debtor stops responding.


How Nexa Collections Recovers Ex-Employee Accounts

Nexa runs ex-employee accounts as a four-step ladder. The early steps are inexpensive and look like your own front desk. The later ones add persistence and, only with your approval, legal pressure.

Step What happens Typical fee
1. Courtesy reminders Five soft reminders for fresher balances, sent as if they’re coming from you. Return the equipment or settle the balance $15 per account
2. Formal written demands Five professional, itemized letters on Nexa letterhead $15 per account
3. Full collection Persistent, polite phone and digital outreach. Negotiated returns, payment plans and settlements 40% of amounts recovered. No recovery, no fee
4. Legal collections For large, unresponsive accounts, escalation to an attorney after review and only with your explicit approval Up to 50% of amounts recovered. No recovery, no fee

collection agency fee

On every account Nexa also runs a free bankruptcy screening, a litigious-debtor check and address verification, so you aren’t chasing a person who’s protected by a bankruptcy stay or who has moved. For the full pricing picture, see our collection agency fees page, and for what happens after you upload an account, see what happens when a debt is assigned to a collection agency.

Need a Collection Agency? Contact us


One Departed Employee, One Itemized Demand

An illustrative composite, not a client result.

A remote operations coordinator leaves on short notice. Payroll processed two more days of pay after her last day. Her laptop and company phone never came back, and her company-card charges are still unreconciled after two reminders. The itemized demand looks like this:

Item Basis Amount
Pay issued after separation Payroll record, corrected calculation $1,240.00
Laptop (3 years old) Asset log, depreciated ledger value $640.00
Company phone Asset log, depreciated ledger value $210.00
Personal card charges Card statements, signed card policy $385.50
Total $2,475.50

The letter’s first ask isn’t the total. It’s the devices. Return both within 14 days and the balance drops by $850 to $1,625.50. That’s the return-first idea working: a smaller number, a faster yes, and no argument about valuation. And because the error was caught within the same tax year, the payroll correction is generally simpler. (If it had crossed into a prior year, ask your payroll provider whether the demand should be stated gross or net of withheld taxes before the invoice goes out.)


Bonus, Relocation and Training Repayments: Read the Clause First

This is the category where the rules are moving fastest.

  • California’s AB 692, effective January 1, 2026, restricts “stay-or-pay” terms that require a worker to repay a debt to the employer, a training provider or a debt collector when the work relationship ends. It applies to agreements entered into, amended or renewed on or after that date and carves out narrow exceptions, such as signing bonuses that meet specific conditions.
  • New York’s Trapped at Work Act was signed in December 2025 and amended in February 2026, delaying its effective date by one year. It takes a similar approach, with its own exceptions, and is enforced by the state labor department.

Returning employer-owned equipment raises different questions from repaying a bonus, but contracts sometimes bundle both, so the wording matters. Because these laws name debt collectors specifically, a responsible agency will ask to see the agreement before pursuing a bonus, relocation or training repayment. Have employment counsel confirm the clause is enforceable first.


Pursue It Cleanly: An Ex-Employee Compliance Checklist

A recovery that creates a wage claim, a privacy complaint or a hostile Glassdoor review isn’t a recovery. Keep it clean:

  • Pay final wages on time and in full. Never hold the check hostage for the laptop.
  • Itemize everything: what it is, when it was issued or paid, and exactly how the amount was calculated.
  • Don’t contact their new employer, coworkers or family about the balance.
  • Don’t threaten police or criminal charges unless counsel advises it.
  • Treat a specific dispute as a reason to verify, not to push harder. “I shipped it in March” gets checked against your records.
  • Check for bankruptcy before any contact.
  • Share only the minimum personnel and device data a partner needs.

One more point worth knowing: whether federal consumer-collection law (the FDCPA) applies to a particular employer claim depends on how the underlying obligation arose, and state licensing and unfair-practices rules can apply either way. Nexa handles ex-employee accounts with the same FDCPA-aligned communication standards it uses elsewhere.


Who Sends Us Ex-Employee Accounts

  • Remote-first and tech companies: laptops, monitors and security tokens scattered across states.
  • Healthcare and dental practices: tablets, devices and payroll corrections after fast staff turnover.
  • Schools and colleges: staff laptops, tablets and stipends when faculty and staff leave mid-year.
  • Construction and trades: tools, vehicle fobs and fuel cards.
  • Staffing agencies and franchises: high turnover and a long tail of small balances. See bulk account placement if you’re sitting on a backlog.
  • Large balances: executive-level repayments and sizable overpayments often fit our large-balance collections process.

Make the Next Offboarding Boring

The cheapest recovery is the one you never need:

  • Get a signed equipment acknowledgment at issue, with serial numbers, and keep an asset log.
  • Put perk and stipend conditions in writing. If a stipend must be earned, say so.
  • Send the return kit when someone gives notice, not on their last day.
  • Document every advance, draw and repayment in a separate, plainly worded agreement.
  • Send a final written statement of anything you believe is still owed.
  • Review repayment clauses with counsel against current state law. Our small-business risk management strategy guide is a good companion.

Frequently Asked Questions

Can a collection agency recover money or equipment from a former employee?

In most cases, yes, when the obligation is documented and not genuinely disputed. An agency can send itemized demands, locate the person, negotiate a return or payment and, with your approval, escalate to legal action. It can’t take wages or property without a court judgment, and state law and the specific agreement determine what’s collectible.

Can an employer deduct unreturned equipment or an overpayment from a final paycheck?

It depends on the state. Federal law generally doesn’t allow deductions for non-exempt employees that cut pay below minimum wage or into overtime, and many states add written-authorization, notice or cap requirements or restrict the practice entirely. California is among the strictest. Pay final wages on time, check your state’s rules and consult counsel before deducting.

What can an employer recover from an ex-employee?

Documented amounts such as unreturned company equipment (or its value), overpaid wages, unearned advances and draws, company-card balances, certain repayments under valid agreements and perks that a written policy clearly conditions on continued employment. Trade-secret, non-compete and misconduct claims are legal matters for counsel.

How should you value an unreturned laptop?

Ask for the device back first. If you bill for it, a defensible basis, such as the depreciated value on your asset log or the device’s fair market value, is safer than a full new-for-old replacement price, which invites disputes. Check your signed equipment agreement for any agreed valuation terms.

Can an employer make a former employee repay a signing bonus or training costs?

Sometimes, but the rules are tightening. It depends on a valid written agreement and state law. California’s AB 692 and New York’s Trapped at Work Act restrict many repayment terms with narrow exceptions, and AB 692 names debt collectors specifically. Have employment counsel review the clause before you pursue it.

How much does it cost to hire a collection agency for an ex-employee balance?

With Nexa Collections, typical fees are a $15 fixed fee per account for each of the first two steps, 40% of amounts recovered for full collection (no recovery, no fee), and up to 50% for client-approved legal collections. See the pricing page for details.


The Bottom Line

A former employee who keeps a laptop or an overpayment isn’t a payroll footnote. It’s a receivable with a name on it, and it ages like every other one. Don’t reach for the final paycheck, and don’t let it sit. Pay what’s owed, itemize what isn’t, ask for the equipment back first, and put the rest in professional hands before the trail goes cold.

Have ex-employee balances, unreturned devices or a backlog of small accounts? Call Nexa Collections at +1-844-639-2123, email support@nexacollect.com or contact us. Not sure whether a balance is collectible? Our collection agency overview explains how recovery works, and our commercial collections team handles employer and B2B accounts.


Sources

  • U.S. Bureau of Labor Statistics, Job Openings and Labor Turnover Survey news release (July 2026 data)
  • Capterra, 2022 Employee Offboarding Survey; HCA Magazine, coverage of the survey’s security findings
  • U.S. Department of Labor, Wage and Hour Division, “Last Paycheck” (dol.gov)
  • Littler, Our Wandering Workers Have Wandered Off With Our Equipment and I Want My Money Back: A Primer on Recovering Inadvertent Overpayments
  • California Department of Industrial Relations (DLSE), Opinion letter on final-wage deductions
  • Morrison Cohen, The End of “Stay-or-Pay” Provisions: How New Laws in California and New York Affect Your Business (March 2026)
  • IRS, Publication 15 (2026), Employer’s Tax Guide (wage repayments)

A general summary, not legal advice. State rules change and have exceptions.

Updated October 2026 | Nexa Collections Employer Recovery Guide

This article is for general information and isn’t legal or tax advice. Wage-deduction, final-pay, repayment-agreement and collection rules vary by state, agreement and individual facts. Consult qualified counsel before deducting from wages or enforcing a repayment clause.
Filed Under: Debt Recovery

Changing Medical Credit Reporting Laws: Urgently Hire a Collection Agency!

blank
One of the most effective tools in recovering unpaid medical bills has been credit bureau reporting. Patients fear that outstanding medical debts will tarnish their credit reports, reducing their chances of obtaining loans and potentially affecting employment opportunities. However, this window of opportunity is gradually closing as CFPB and states are gradually enact laws to stop or restrict credit bureau reporting of medical debts, making recovery efforts very challenging.

Act Now: Changing Laws Are Making Healthcare Debt Recovery More Challenging

Its all happening in front of us – Federal and state governments are rapidly eliminating the credit reporting of medical debts or imposing strict restrictions, making healthcare debt recovery increasingly difficult. The window to recover unpaid medical bills is closing fast.

What are you waiting for ?

  • If you have not collected your unpaid medical bills yet – Forward them to a medical collection agency fast!
  • Need a collection agency? Contact us 
  • Time is  running out !

Start the Collections Process Immediately

It’s imperative to initiate the collections process early, before patients begin to view their medical bills as a low priority, believing there will be no repercussions for not paying. Delaying action can result in missed opportunities to recover debts that are rightfully owed.

Credit Reporting Agencies Are Minimizing the Impact of Medical Debts

To make matters worse, credit reporting agencies like Equifax, TransUnion, and Experian, along with credit scoring models such as FICO and VantageScore, have already started to minimize the impact of medical bills on credit scores. This means unpaid medical debts may no longer significantly affect a patient’s creditworthiness, reducing their incentive to pay.

List of Laws Passed and Pending Approval 

  • Federal regulations like the “No Surprises Act” aim to protect consumers from unexpected medical bills, further complicating the debt recovery process for healthcare providers.
  • Jun, 2024 – CFPB Proposes to Ban Medical Bills from Credit Reports Entirely. ( All across USA)
  • Connecticut – May 9, 2024- Public Act No. 21-129 , Public Act No. 24-6
    Connecticut Governor Signs Bill Prohibiting Health Care Providers from Reporting Medical Debt to Credit Reporting Agencies.
  • Colorado – House Bill 21-1198, Colorado law prohibits credit bureaus from reporting medical debt or factoring medical debt into a credit score unless the consumer report is to be used in connection with a credit transaction that involves, or that may reasonably be expected to involve, a principal amount that exceeds the national conforming loan limit value for a one-unit property as determined by the federal housing finance authority.
  • New York – Senate Bill S4907A, SB 8373 , Fair Medical Debt Reporting Act, This law prohibits hospitals, health care professionals, and ambulance services from reporting medical debt to consumer reporting agencies.
  • Nevada – Senate Bill 248
  • Virginia – Bill, HB 1370 , HB 1265
  • California – Assembly Bill 1020 (AB 1020)
  • Maryland – Medical Debt Protection Act
  • Washington State – House Bill 1531 (HB 1531) , HB 2119
  • Minnesota – Minnesota Statutes Section 332.70
  • Illinois – House Bill 5482
  • Massachusetts – Senate Bill S.675
  • Oregon – House Bill 3076
  • Maine – Legislative Document 110 (LD 110) , SB 908
  • Texas – House Bill 1448
  • Florida – Florida reduces statute of limitations for medical debt to three years
  • New Jersey – AB 890
  • Virginia-  HB 1370
  • Wisconsin – AB 786
  • Rhode Island – HB 7103
  • Vermont – (SB 217)
  • Oklahoma – HB 3576, and HB 4148
  • Indiana – HB 1128
  • Equifax, Experian, and TransUnion:
    • Announced removal of paid medical collection debt from credit reports.
    • Extended the time before unpaid medical collection debt appears on credit reports from 6 months to 1 year.
    • Starting in 2023, medical collection debt under $500 is no longer included on credit reports.

Be First in Line Before Patient Finances Deteriorate

Medical collections should be a top priority because patients’ finances can deteriorate very quickly; they might accrue additional bills from other healthcare providers. You want to be first in line to secure payment before funds are depleted elsewhere. We strongly recommend sending accounts to a collection agency after 60 to 90 days of non-payment, even though medical credit reporting can now occur after one year due to stringent new laws.

Choose a Reputable Healthcare Collection Agency

When hiring a healthcare collection agency, you must select one that will not tarnish your reputation during collections. Ensure the agency:

  • Follows all federal and state laws
  • Is licensed to collect in all 50 states
  • Keeps patients’ data safe and is HIPAA compliant
  • Offers bilingual services
  • Serves hundreds of healthcare clients
  • Has a track record of delivering excellent recovery rates

Don’t Wait Until It’s Too Late

The landscape of medical debt recovery is changing rapidly. Act now to protect your revenue and maintain the financial health of your practice. Initiate the collections process promptly to navigate these challenges effectively.

Filed Under: Debt Recovery

Aggressive to Amicable: The Changing Face of Debt Collection

Collection agencies used to be known for being really aggressive, sometimes even harassing people to get them to pay. We have seen Hollywood movies like “Uncut Gems” and “Revolver”, which portray debt collectors as intimidating and dangerous figures. While these depictions are clearly overly exaggerated, it’s important to note that the reality has significantly changed, especially over the past decade.

amicable collections

Most reputable and sensible collection agencies are now adopting a much softer approach.

Here’s why: way things have changed.

1. Increased Awareness of Debtor Rights and FDCPA Laws: The widespread awareness about consumer rights, particularly through social media, blogs, and videos educate people on what they should and should not tolerate from debt collectors. . They are now more likely to recognize and challenge any violations of the Fair Debt Collection Practices Act (FDCPA), which prohibits aggressive and abusive collection tactics.

2. Impact of Online Reviews and Reputation Management: Both collection agencies and their clients (the original creditors) are aware of this risk, so there’s a strong incentive to avoid behaviors that could lead to public backlash. This has forced them to adopt more customer-friendly and compliant practices.

Google-rating-collection-agency

3. Rise of Consumer Protection Lawyers and Regulatory Action: The growing number of lawyers specializing in consumer protection law and experts in suing collection agencies, coupled with increased enforcement actions by the Federal Trade Commission (FTC), has further discouraged collection agencies from resorting to unlawful and aggressive tactics.

The Consumer Financial Protection Bureau (CFPB) and the FTC have shutdown several agencies that consistently violate the law.

4. Increased Debt Disputes and Requests for Validation: As debtors become more aware of their rights, they are more likely to challenge the validity of debts and demand proper documentation. This can lead to the removal of inaccurate or unsubstantiated debts from credit reports.

Other Contributing Factors:

  • Technological Advancements: Modern communication tools and data analytics have enabled collection agencies to adopt more targeted and efficient collection strategies, reducing the need for aggressive tactics.
  • Shift in Industry Culture: There is a growing recognition that a more collaborative and respectful approach can be more effective in securing debt repayment in the long run.
  • Economic Factors: In certain economic climates, collection agencies may prioritize maintaining a positive relationship with debtors who might become future customers.

While there are still some agencies that may use more aggressive methods, the industry as a whole is moving towards a more professional and respectful approach.

By focusing on compliance, transparency, and respectful communication, collection agencies can increase their chances of successful debt recovery while minimizing the potential for conflict and legal disputes.

Filed Under: Debt Recovery

Choosing Wisely: Client Selection Strategies for Successful Collection Agencies

Selecting Collection Agency Client

In the world of debt collection, success isn’t just about recovering outstanding balances. It’s about building lasting relationships, upholding ethical practices, and aligning with clients whose values mirror your own.

That’s why a collection agency should be highly selective when onboarding new clients. It’s not just about taking on any business that comes your way; it’s about finding the right fit.

Its OK to tell a potential client – Our collection agency is not the right fit for you.

It’s pointless to waste your client’s time or your debt collector’s time working on accounts that fall outside your area of expertise or where your collection methodology doesn’t align with the client’s expectations.

Philosophical Alignment

Every collection agency has a unique approach to its work. Some may prioritize aggressive tactics, while others emphasize amicable solutions. Similarly, clients have varying expectations for how their collections should be handled.

A mismatch in these philosophies can lead to dissatisfaction and even ethical concerns. It’s crucial to accept clients whose approach aligns with your agency’s core values.

  • For instance, if a client demands aggressive tactics but your agency prides itself on maintaining positive relationships with debtors, it’s likely not a good match.
  • Additionally, consider if the client’s industry or the nature of the debts aligns with your agency’s expertise and comfort level.
  • Your expertise may be consumer collections, while client may have commercial accounts, or, client is not willing to use your services in the way you have designed them, or, client just wants to dump accounts older than 2 years old and per your experience your recovery rate on accounts is nearly zero for such old accounts. Its OK to say “Sorry”.

Cost-Benefit Analysis

While it’s tempting to take on every client, sometimes the cost of onboarding and servicing an account outweighs the potential benefits.

  • For clients with just a few low-balance accounts, the administrative and operational costs can quickly exceed the commission earned. It’s essential to conduct a thorough cost-benefit analysis before accepting any new client.
  • Factor in the age and collectability of the debts, as well as any potential legal or compliance complexities.

Understanding Client Needs

Clients have different priorities when choosing a collection agency.

  • Some may prioritize high recovery rates and be willing to pay higher contingency fees for a full-service agency.
  • Others may prioritize lower fees and compliance but be less concerned about data security. It’s crucial to understand a client’s needs and expectations before entering into a partnership.
  • Ensure that you have the resources and capabilities to meet their specific requirements.

Additional Considerations

  • Client Reputation: Conduct due diligence on potential clients. Check their reputation, financial stability, and any history of legal or ethical issues.
  • Communication & Transparency: Establish clear communication channels and expectations from the outset. Transparency about fees, processes, and progress is essential for a successful partnership.
  • Scalability: Consider whether the client’s needs align with your agency’s growth plans and capacity.

Final Thoughts

Selectivity in client onboarding isn’t just a good practice; it’s a strategic imperative for collection agencies.

By choosing clients wisely, agencies can ensure philosophical alignment, maximize profitability, and build long-term relationships based on trust and mutual respect. Remember, in the collection industry, quality trumps quantity.

Filed Under: Debt Recovery

Tailored Debt Collection for Baby Boomers, Gen X, Millennials and Gen Z

blank
When it comes to collecting debt, one size doesn’t fit all. Different generations have unique financial habits and communication preferences, so understanding these differences can help debt collectors work more effectively. Here’s how to approach debt collection differently for Baby Boomers, Gen X, Millennials, and Gen Z.

1. Baby Boomers (Born 1946-1964)

Financial Habits:

  • Baby Boomers value financial stability and tend to stick to traditional financial habits. Many are retired or nearing retirement, so they’re often on a fixed income and careful about their savings.
  • They prioritize paying off debt because they associate it with financial security and maintaining a good credit score.

Communication Preferences:

  • Preferred Methods: They prefer direct, traditional communication, like phone calls or letters. They appreciate clear, respectful, and formal conversations.
  • Personal Touch: Baby Boomers like talking to a real person rather than dealing with automated systems.

Approach:

  • Be Respectful and Clear: Use polite, formal language when talking to them. Explain their debt situation clearly and outline what they can do to resolve it.
  • Offer Flexible Payment Plans: Since many are on a fixed income, offer payment options that fit their budget, like spreading out payments over time.
  • Follow Up with Written Confirmation: After a phone call, send a letter or email to summarize what was discussed and agreed upon.

2. Generation X (Born 1965-1980)

Financial Habits:

  • Gen Xers are generally financially responsible but often carry significant debt, like mortgages, credit card debt, or student loans for their kids.
  • They focus on saving for retirement and are cautious about taking on new debt.

Communication Preferences:

  • Preferred Methods: Gen X likes a mix of communication methods. They’re comfortable with emails and phone calls but also appreciate having online payment options.
  • Efficiency: They value straightforward and efficient communication.

Approach:

  • Offer Online Payment Solutions: Give them the ability to manage their debt online, like setting up payment plans or making payments through a website.
  • Be Direct and Efficient: When communicating, get straight to the point. Gen Xers appreciate clear, concise information and quick resolutions.
  • Highlight Long-Term Impact: Show them how resolving their debt can benefit their long-term financial goals, like retirement savings.

3. Millennials (Born 1981-1996)

Financial Habits:

  • Millennials often have student loan debt and prioritize experiences over material goods. They might delay big purchases like houses or cars and are open to non-traditional financial solutions.
  • They are very conscious of their finances but may struggle with managing debt due to lower wages or job instability.

Communication Preferences:

  • Preferred Methods: Millennials prefer digital communication, like emails, text messages, or app notifications. They want convenience and transparency.
  • Tech-Savvy: They expect to be able to manage their debt online or through apps, and they appreciate clear, accessible information.

Approach:

  • Leverage Technology: Use digital channels to communicate, offering them the ability to manage their debt through apps or online platforms. Send reminders via text or email.
  • Be Transparent: Be open about the debt collection process and provide educational resources on managing debt. Millennials appreciate clear info that helps them make informed decisions.
  • Offer Flexible Payment Options: Many Millennials like flexibility, so consider offering payment plans that can be adjusted based on their income or situation.

4. Generation Z (Born 1997-2012)

Financial Habits:

  • Gen Z is just starting to enter the workforce and tends to be cautious about debt, having seen the financial struggles of Millennials. They’re more likely to avoid debt and are focused on financial independence.
  • They value financial education and want to make informed decisions.

Communication Preferences:

  • Preferred Methods: Gen Z prefers mobile and digital communication, like texts, social media, and apps. They like short, direct messages and real-time communication.
  • Instant Responses: They expect quick replies and prefer chatting over the phone or messaging apps.

Approach:

  • Use Mobile and Social Media: Communicate through mobile apps, social media, or text messaging. Consider using chatbots for quick and easy communication.
  • Keep it Short: Keep messages brief and to the point. Gen Z doesn’t like long explanations and wants quick solutions.
  • Educate Digitally: Provide resources like short videos or infographics to help them understand debt management. Gen Z values learning and is likely to engage with content that helps them make smart financial choices.

Final Thoughts:

Each generation has its own way of handling money and communicating, so adapting your debt collection approach to these differences can lead to better results. By understanding what motivates each group and how they prefer to be contacted, debt collectors can build better relationships, improve recovery rates, and create a more positive experience for everyone involved.


Filed Under: Debt Recovery

Why Debt Collection Needs More Women in Leadership

blank

The debt collection industry has traditionally been dominated by men, but that’s gradually changing as more women take on leadership roles.

This shift isn’t just about diversity—it’s about the positive impact that women can have on the way debt collection works. Women bring empathy, emotional intelligence, strategic thinking, and collaboration skills that can enhance every aspect of debt collection, from improving debtor relations to driving business growth, making debt collection more effective, fair, and compassionate.

The Current Situation

For a long time, debt collection has been seen as a tough, even aggressive, field—qualities often linked to male leadership. But as the industry evolves, people are realizing that successful debt collection also needs empathy, good communication, and the ability to build relationships. These are areas where women often excel. Despite this, women have been underrepresented in leadership positions within debt collection.

Companies are starting to see the value of having diverse leadership teams because different perspectives can lead to better decisions and results.

Why Women Make Great Leaders in Debt Collection

  1. Empathy and Communication
    • Debt collection isn’t just about getting money back; it’s also about helping people who are struggling financially. Women leaders often bring a higher level of empathy, which makes it easier to communicate with people who owe money. For example, instead of just demanding payment, a woman leader might take the time to understand why someone is behind on their payments and work with them to find a solution.
    • Example: Imagine a debt collector who listens to a debtor explain that they lost their job. Instead of pushing hard for immediate payment, the collector might offer a revised payment plan that the debtor can afford, building trust and increasing the chance of repayment.
  2. Emotional Intelligence
    • Emotional intelligence (EI) is about understanding and managing emotions—both your own and others’. Women often score higher in EI, which is crucial in debt collection, where emotions can run high. Leaders with high EI can handle tough situations better, finding solutions that work for everyone involved.
    • Example: A good leader might notice that a team member is stressed out after a difficult call. Instead of ignoring it, she could offer support and suggest ways to handle similar situations in the future, improving both the team’s performance and morale.
  3. Strategic Thinking
    • Women leaders are often great at thinking long-term. In debt collection, this means not just focusing on getting money right now, but also on keeping good relationships with clients and debtors. This approach helps create strategies that are fair and sustainable.
    • Example: A thoughtful leader might decide to invest in better training for her team, knowing that while it might cost more upfront, it will lead to better results and happier clients in the long run.
  4. Collaboration and Team Building
    • Teamwork is essential in debt collection, where different departments need to work together. Women leaders are often natural collaborators, helping everyone work towards common goals.
    • Example: A woman leader might bring together team members from different areas—like customer service and collections—to come up with a plan that benefits both the company and the customers.

Why It’s Good for Business

Studies show that companies with diverse leadership teams do better financially. This is true in debt collection, too. When women are in leadership, they bring different perspectives that can lead to more creative solutions, better customer service, and higher recovery rates.

Having women in leadership can also improve how a company is seen by the public. In a world where people care more about working with companies that are ethical and responsible, having women in leadership roles can make a debt collection agency look fairer and more trustworthy.

Breaking Down Barriers

Even though the benefits are clear, there are still challenges. Gender bias, lack of mentorship, and the difficulty of balancing work and family can all hold women back. Companies need to address these issues by offering flexible work options, leadership training, and mentorship programs to support women’s advancement.

When companies support women in leadership, everyone wins. The debt collection industry becomes stronger, more innovative, and better at serving both clients and debtors. This isn’t just the right thing to do—it’s a smart move that can lead to success for everyone involved.

Filed Under: Debt Recovery

  • « Go to Previous Page
  • Page 1
  • Interim pages omitted …
  • Page 6
  • Page 7
  • Page 8
  • Page 9
  • Page 10
  • Interim pages omitted …
  • Page 55
  • Go to Next Page »

Primary Sidebar


accounts receivable

Need a Collection Agency?
Kindly fill this form.
We’ll get in touch with you

    Please prove you are human by selecting the plane.

    Compliance & Security

    • SOC 2 Type II Certified: Third-party audited data security and strict privacy controls.

    • HIPAA Compliant: Secure, legal processing of medical and municipal EMS accounts.

    • PCI-DSS Level 1: Highest tier of data encryption for secure payment processing.

    • FDCPA & FCRA Aligned: Full legal adherence to federal consumer protection laws.

    Recent Posts

    • Why Dental Patients Dispute Bills: The Nexa Collections Dental Account Dispute Index
    • 2027 Commercial Collections Benchmark: U.S. Late Payments, AR Risk and B2B Collection Trends
    • Bulk Account Placement: What a Collection Agency Actually Needs From You
    • Nationwide Debt Collection Agency Serving U.S. Cities
    • Chula Vista Collection Agency for Medical, B2B, Schools & Business Debt
    • Corpus Christi Collection Agency: Itemized Bill Rules for Practices
    • Riverside Collection Agency | For Logistics, Medical, Schools & Business Recovery
    • Collection Agency for Large Balances: High-Value B2B Debt Recovery

    Featured Posts

    • Commercial Debt Collection Agency: B2B Debt Recovery for Businesses
    • California Medical Collection Agency: Local Experience Matters!
    • How Outsourcing Debt Recovery Slashes Your Staffing and Overhead Costs

    Copyright © 2026 NEXACOLLECT.COM | This content is provided for general informational purposes only and should not be considered legal advice. Collection laws and requirements may vary by state, account type, documentation, debtor status, and specific facts. Please consult qualified legal counsel for guidance regarding your particular situation. Nexa and its authorized collection partners service accounts in accordance with applicable federal and state collection requirements. Visit our home page to know more about us.

    X
    Need a Collection Agency?
    Contact Us