• Skip to main content
  • Skip to primary sidebar

Nexa Collections

  • Home
  • Serving
    • Medical
    • Dental
    • Small Business
    • Large Business
    • Commercial Collections
    • Government
    • Utilities
    • Fitness Clubs
    • Schools
    • Senior Care Facility
  • Contact Us
    • About us
    • Cost

Debt Recovery

5 Things Collection Agencies Won’t Tell Clients

Businesses and medical practices can make a more informed decision when working with collection agencies to protect their financial interests and reputation.

Cherry-Picking Accounts

Many agencies prioritize easier-to-collect debts, neglecting more challenging ones like older debts or those with low balances. They might also focus more on high-value accounts, ones with better credit rating and commercial debts over consumer debts. This selective approach can reduce overall recovery.

Solution: Choose an agency that provides detailed action reports for each debtor, including call and demand letter histories. If online data is limited due to privacy concerns, the agency should offer a summary upon request.

Outsourcing to Other Agencies

Since most agencies aren’t licensed in all 50 states, they may outsource collections when debtors move to states where they lack a license. Clients are often not informed about these third-party handovers.

Solution: Opt for a collection agency with a national license to avoid complications from outsourcing.

Why Their Collection Fee is So Low

Lower fees often mean lower effort. Agencies charging lower contingency fees may cut corners on services or hire inferior quality debt collectors, resulting in poorer collection outcomes and inadequate data security. The risk of debtor data breaches is higher with such agencies.

Analogy: Think of a low-cost agency as a car without airbags, wipers, or seatbelts—it might move, but it lacks essential safety features. A higher-fee agency will provide better recovery rates and data security.

Impact on Client Reputation 

Aggressive collection tactics can damage a client’s reputation. Surprisingly, agencies that use respectful, diplomatic methods often achieve better results than those using harsh approaches.

Solution: Review Google ratings for the agency, selecting only those with a rating above 4.5 stars and at least 1,000 reviews.

Fees and Hidden Costs 

Collection agencies might not be transparent about all fees, including hidden charges, which can reduce the net amount recovered for the client.

Solution: Ensure clear communication and documentation of all fees before engaging a collection agency

Need a good collection agency? Contact us

Filed Under: Debt Recovery

Reducing Aging Receivables with Predictive Analytics Software

Utilizing predictive analytics to identify clients who are at risk of becoming delinquent. Lets understand this in simple terms how this concept works, taking example of a Credit Union.

How Predictive Analytics Can Help Credit Unions Collect Money

Lets say a credit union is like a big piggy bank where people keep their money and sometimes borrow money when they need it. When people borrow money, they promise to pay it back, but sometimes they have trouble doing that. Predictive analytics is like a smart helper that helps the credit union figure out who might have trouble paying back their money soon.

What is Predictive Analytics?

Predictive analytics is a way of looking at past behavior to guess what might happen in the future. It’s like using clues to solve a mystery before it happens.

For example:

  • If you see dark clouds, you might guess it’s going to rain.
  • Google Maps predict travel time based on current traffic conditions, historical traffic patterns, and other factors.
  • Wearable devices and health apps use predictive analytics to track your health metrics and identify potential health risks.
  • Email spam filters use predictive analysis to identify and block unwanted emails.
  • Streaming services like Netflix and Amazon Prime Video use your viewing history and ratings to recommend movies you might enjoy.

How Does It Help?

  1. Spotting Trouble Early:
    • The smart helper (Predictive Analytics) looks at clues like how people have paid their bills before. If someone starts paying late or has less money in their account, the helper guesses they might have trouble paying in the future.
    • If someone’s credit score goes down, the helper also knows they might be in trouble.
  2. Sending Helpful Reminders:
    • Once the helper spots someone who might struggle, the credit union can send them friendly reminders to pay their bills on time.
    • They might also offer help, like easier ways to pay or advice on managing money better.
  3. Using Resources Wisely:
    • The credit union can focus on helping the people who need it the most, instead of treating everyone the same. This makes their work more efficient.
    • They pay special attention to people whose credit scores have dropped because they might need extra help.
  4. Creating Easy Payment Plans:
    • The credit union can make special payment plans that fit each person’s needs, especially if they’re having a hard time. For example, they might let someone pay smaller amounts for a little while.
    • If a person’s credit score has gone down, the credit union might offer even more flexible plans to help them out.
  5. Building Good Relationships:
    • By helping people before they get into big trouble, the credit union shows that it cares. This makes people trust and like the credit union more.
    • Talking to people about their credit scores and helping them improve can make them feel supported and valued.

Example Story

Think of Jane, who usually pays her bills on time. But lately, Jane has been late with her payments, and her account has less money. Her credit score has also dropped. The smart helper notices this and tells the credit union.

Here’s what the credit union does:

  • Friendly Reminder: They send Jane a message reminding her to pay her bill soon.
  • Offer Help: They tell Jane about special plans to make paying easier or offer advice on managing her money.
  • Keep an Eye: They check back with Jane to make sure she’s doing okay and staying on track.

By doing this, the credit union helps Jane avoid big trouble, and Jane feels happy and supported.

Popular Predictive Analysis Software tools

Here are some tools that can help credit unions leverage predictive analytics to reduce aging receivables:

  1. SAS Analytics:
    • Offers advanced predictive analytics capabilities.
    • Provides robust data management, statistical analysis, and visualization tools.
  2. IBM SPSS:
    • Known for its powerful statistical analysis and predictive modeling features.
    • User-friendly interface suitable for complex data analysis.
  3. Microsoft Power BI:
    • Offers data visualization and business intelligence capabilities.
    • Integrates with various data sources and provides predictive analytics through its AI capabilities.
  4. Tableau:
    • Excellent for data visualization and real-time analytics.
    • Can be integrated with predictive analytics tools and platforms.
  5. RapidMiner:
    • Provides a comprehensive platform for data science and machine learning.
    • User-friendly and supports end-to-end analytics workflows.
  6. Alteryx:
    • Focuses on data preparation, blending, and advanced analytics.
    • Simplifies the process of predictive modeling with a drag-and-drop interface.
  7. Google Cloud AI and Machine Learning Tools:
    • Offers a suite of tools for predictive analytics and machine learning.
    • Scalable solutions that integrate with various data sources.
  8. R and Python:
    • Open-source programming languages with extensive libraries for statistical analysis and machine learning.
    • Suitable for custom predictive analytics solutions.
  9. Qlik Sense:
    • Data analytics platform that provides self-service visualization and discovery.
    • Integrates predictive analytics to enhance data insights.
  10. H2O.ai:
  • Open-source platform for AI and machine learning.
  • Provides tools for building predictive models and deploying them at scale.

Filed Under: Debt Recovery

Early Commercial Debt Collection: Why Waiting 90 Days Costs You 20% of Your Revenue

Early Commercial Recovery: The “Golden Window” for B2B Debt

In commercial lending and B2B sales, the clock ticks faster than in consumer debt. A business that owes you money today might be insolvent, acquired, or bankrupt tomorrow.

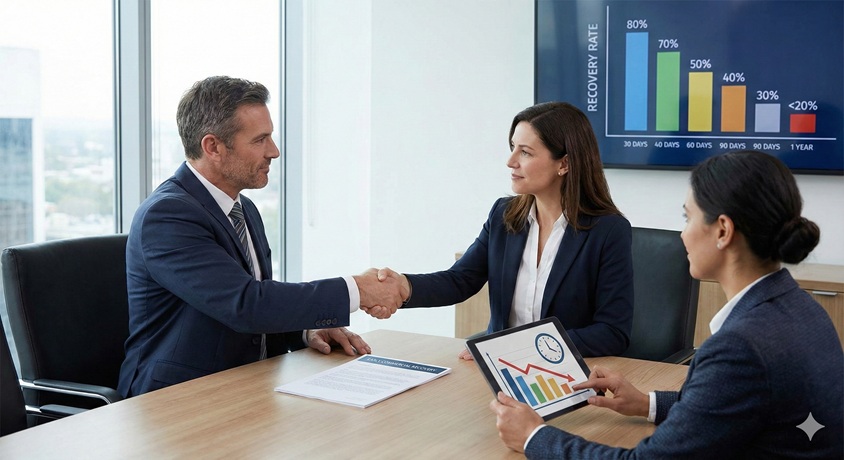
The 2026 Reality: The average B2B recovery rate for accounts under 90 days old is nearly 80%. Once that debt hits 6 months, the success rate plummets to roughly 50%. By one year, you are fighting for pennies.

Waiting for a “miracle payment” isn’t patience—it’s a liability. Here is why smart CFOs and Credit Managers assign accounts to third-party collections the moment internal efforts stall.

3 Numbers That Define B2B Collections

  • 11% Drop Per Month: Industry data shows that the collectability of a commercial invoice drops by approximately 11% for every 30 days it remains past due.

  • $25,000+: The average commercial collection claim is significantly higher than consumer debt. You cannot afford to treat a $25,000 invoice with the same passive strategy as a $100 utility bill.

  • 45% Higher Response: Modern agencies use SMS and digital demand signals, which see a 45% higher response rate from business owners than traditional mail.

The “Relationship Paradox”: Why Outsourcing Saves Clients

Business owners often fear that hiring a collection agency will “nuke” the relationship. The opposite is usually true.

  • The “Buffer” Effect: When you call for money, it gets personal. When we call, it’s business. We act as the “bad cop,” allowing your sales team to remain the “good cop.”

    Use a collection agency that starts contacting with a gentle reminder, and then gradually shifts to a more diplomatic/pressurizing approach.

  • The Excuse Remover: Delinquent clients often dodge your sales reps because they are embarrassed. Once an agency steps in, the awkwardness is removed from your direct relationship. We settle the debt so they can buy from you again.

Step-by-Step: How We Recover Commercial Debt

We don’t just “dial for dollars.” Commercial recovery is a forensic process.

1. The “Deep Scrub” (Investigation)
Before we make a call, we investigate. Is the debtor still in business? Have they filed for bankruptcy? Are they paying other vendors but stiffing you? We use skip tracing and commercial credit data to see their financial health.

2. The Demand & Dispute Resolution
B2B debts are rarely about “I don’t have money.” They are usually about disputes (e.g., “The shipment was late,” “We didn’t authorize that charge”). Our collectors are trained to cut through these stalls. We demand proof of the dispute or payment in full.

3. The Leverage (Credit Reporting)
For a business, credit is oxygen. We report delinquent commercial accounts to major business credit bureaus. The threat of losing their ability to get a line of credit or a supplier loan is often the only motivation they need to pay.

4. The Settlement Negotiation
If a debtor is truly cash-strapped, we negotiate a Consent Judgment or a structured payment plan that ensures you get paid first, before their other creditors.

Specific Issues We Solve for B2B Creditors

  • “The Check is in the Mail” Stall: We hold them accountable to specific dates and tracking numbers.

  • Unauthorized “Net-Terms” Extensions: Clients who unilaterally decide to pay in 60 days when your terms are Net-30.

  • Supply Chain Excuses: We separate legitimate logistics issues from cash-flow stalls.

  • Ghosting: When the Accounts Payable manager suddenly stops replying to emails.

When to Assign? (The Red Flags)

Do not wait for 120 days. Assign the account immediately if:

  • The debtor has broken two promises to pay.

  • The phone line is disconnected or the website is down.

  • They suddenly switch to a new bank or ask for unusual payment changes.

  • A competitor tells you they haven’t been paid either.

Stop financing your customers’ businesses interest-free.

Get a Free Quote for Early-Out Commercial Collections

Filed Under: Debt Recovery

Debt Collection Agency Guide: Handling Disputes & Regulations

How to Handle Debtor Disputes & Complaints

Managing disputes professionally is a hallmark of a compliant collection agency. Following federal regulations ensures that the rights of both the creditor and the debtor are protected.

blank

Mandatory Compliance & Procedures

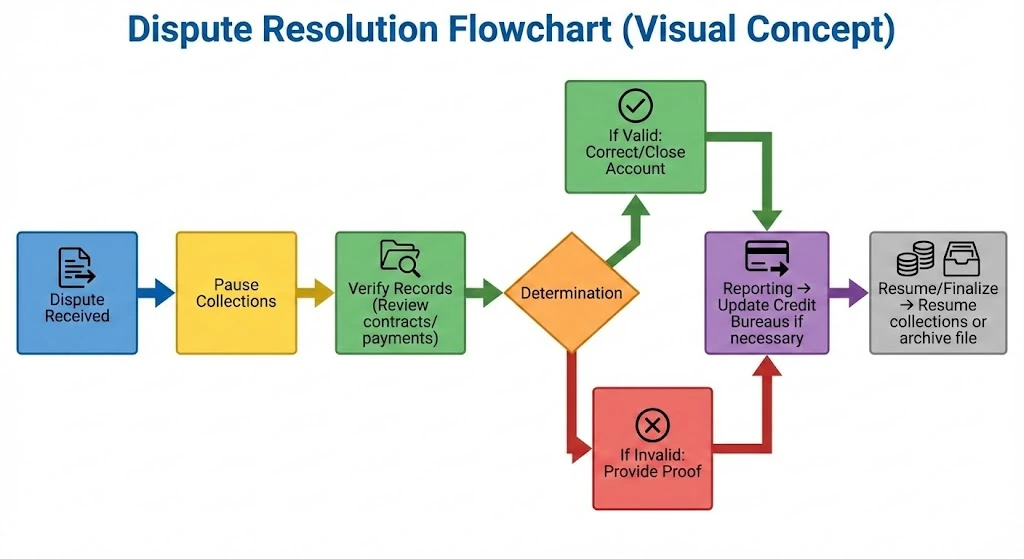
  • Immediate Cease of Activity: When a debtor disputes a debt, the collection agency must immediately halt all collection efforts until the dispute is verified.

  • Regulatory Adherence: All processes must align with the Fair Debt Collection Practices Act (FDCPA) and the Fair Credit Reporting Act (FCRA) nationwide.

  • Evidence Gathering: Collect and review all account statements, original contracts, and payment history to verify the debt’s accuracy.

  • The 30-Day Rule: By law, if a dispute is raised during the validation period, the collection agency has 30 days to provide backup documentation. If the creditor cannot provide this, the account may need to be closed.

Valid vs. Invalid Disputes

  • Valid Disputes: Occur if the debt was already paid, is a result of identity theft, or contains accounting errors. The collection agency must correct these records and update credit bureaus immediately.

  • Invalid Disputes: Occur when the debtor acknowledges the debt but is attempting to delay payment. In these cases, provide clear, written evidence of the debt to the debtor to resume collection activities.

Escalation and Legal Review

  • Attorney Involvement: If a debtor is represented by counsel, the account is classified as “litigious.” The collection agency should consult with the client to determine if the account should move to legal action or be closed.

  • Staff Training: Ensure all personnel are trained on dispute resolution to maintain high standards of effectiveness and legal compliance.

Frequently Asked Questions (FAQ)

  • Can a collection agency contact me during a dispute?

    No. Once a written dispute is received, the agency must stop contact until they provide verification of the debt.

  • What happens if the original creditor doesn’t have the paperwork?

    If documentation cannot be produced within the legal timeframe, the collection agency must generally cease collection efforts on that specific debt.

  • Does a dispute automatically remove the item from my credit report?

    Only if the dispute is found to be valid and the information is proven inaccurate. If the debt is verified, it remains on the report.

Filed Under: Debt Recovery

The Compliance Firewall: Protecting Your Reputation and Revenue

blank

In the modern regulatory environment, a collection agency is either a financial asset or a legal liability. From the strictures of the No Surprises Act to the nuances of state-level consumer protections, “good intentions” are not enough. At Nexa Collections, we believe that compliance is the foundation of recovery. We don’t just “debt collect”; our Account Reconciliation Team operates under a “Firm on Results, Fair on People” mandate that shields your practice from litigation and protects your brand from public “review-bombing”.

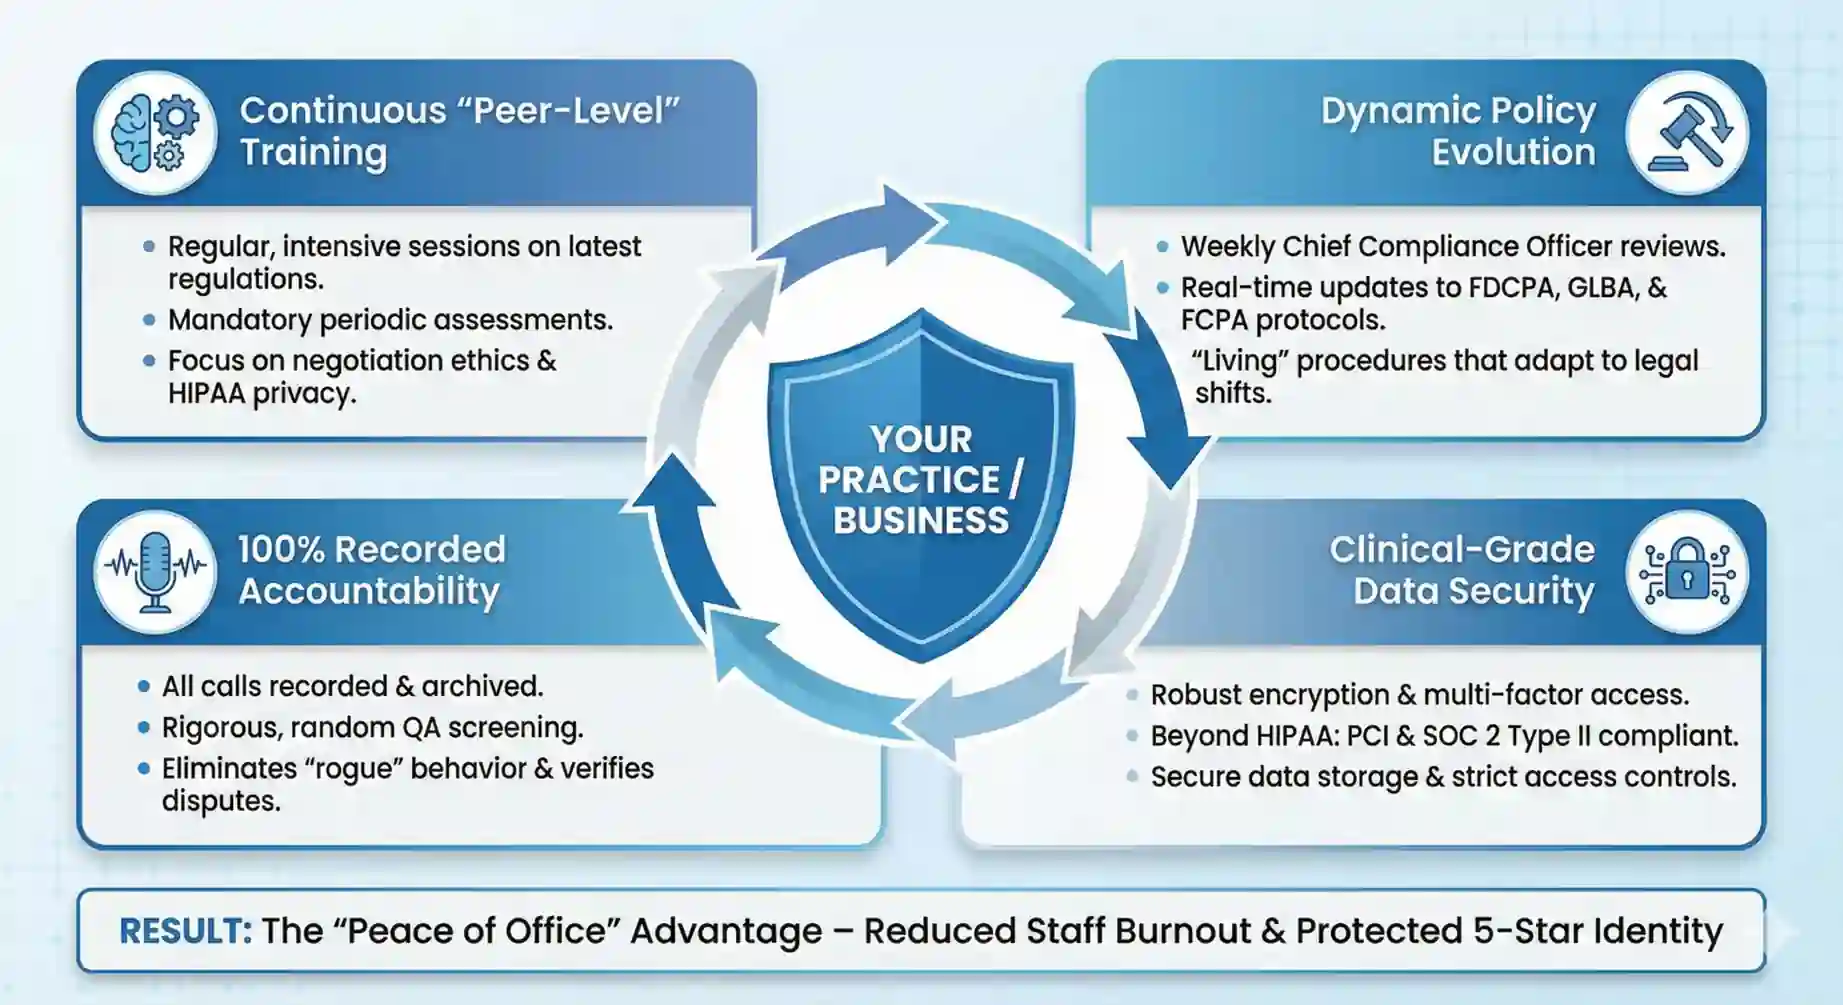
Our Four Pillars of Regulatory Excellence

1. Continuous “Peer-Level” Training

We don’t settle for annual checklists. Our specialists undergo regular, intensive training sessions focused on the latest federal and state-specific regulations. To maintain active status on our team, collectors must pass periodic assessments on negotiation ethics, HIPAA privacy standards, and the FDCPA. This ensures that every conversation reflects the same professionalism found in your own office.

2. Dynamic Policy Evolution

Laws change; so do we. Our Chief Compliance Officer conducts weekly strategy meetings to audit our internal policies against the latest shifts in the FDCPA, HIPAA, GLBA, and FCPA. By maintaining a “living” set of procedures, we ensure your accounts are always managed within the safest legal boundaries.

3. 100% Recorded Accountability

Trust is built on verification. We record and archive 100% of our outreach calls. These recordings are subject to random, rigorous screening by our quality assurance team to identify and correct even the smallest deviation from our “Respectful Friction” model. This process eliminates “rogue collectors” and provides a documented defense against unfounded patient disputes.

4. Clinical-Grade Data Security

We treat patient and business data with the highest level of technical scrutiny. Our systems are fortified with robust encryption, secure data storage, and strict multi-factor access controls. Beyond HIPAA, we maintain rigorous PCI and SOC 2 Type II compliance standards to ensure that your sensitive financial information is never compromised.


The “Peace of Office” Advantage

Compliance is more than just avoiding fines; it’s about preventing friction. When a recovery partner operates with clinical professionalism, patients and customers don’t call your front desk to complain. By outsourcing to our compliant team, you:

  • Reduce Staff Burnout: Your team stops absorbing the emotional stress of financial disputes.

  • Protect Your 5-Star Identity: Respectful outreach prevents the retaliatory “review-bombing” on Healthgrades or Google that can devastate a local business.

  • Ensure “Net-Zero” Cost: Professionalism leads to higher recovery rates, often making the service a self-funding investment in your practice’s health.


Compliance & Security FAQs

How do you stay updated on state-specific collection laws?

Our legal network monitors legislative updates in all 50 states. Whether it’s the Texas Debt Collection Act or the California Medical Debt Protection Act, our workflows are automatically adjusted to match current local requirements.

What happens if a patient disputes an account?

We move from “recovery” to “reconciliation.” We review the recorded call, verify the documentation (invoices, POs, or EOBs), and diplomatically clarify the balance with the patient. This documentation-first approach resolves disputes without losing the patient’s loyalty.

Filed Under: Debt Recovery

Process to Send Someone to Collections

In the digital age, hiring a collection agency has never been easier. There’s no need for in-person meetings, physical paperwork, or tedious calls to customer service for updates.

Contact us : We can make this process extremely smooth for you.

Tip: Never hire a very small collection agency as they would not have enough resources, security implementations to keep your data safe, or a national license. Ability to collect money in all 50 states is important as people move from one state to another especially when they have defaulted.

Most reputable collection agencies provide a convenient online client portal, allowing you to effortlessly sign up for their services from the comfort of your own home. Before making your final decision, request detailed information from the agency’s sales representative and schedule a consultation call to discuss their services and address any concerns you may have. This ensures a transparent and informed decision-making process, saving you valuable time and effort.

Steps before sending someone to collections

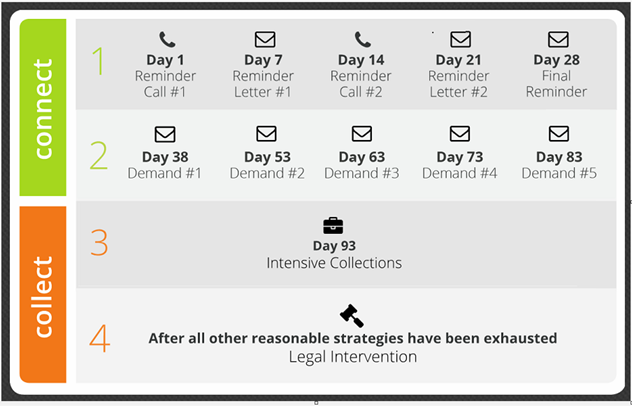
  • Wait 90+ days: It’s generally recommended to wait at least 90 days after the invoice due date before considering collections.
  • Resend invoices: Send the invoices again, ensuring they haven’t been lost or overlooked.
  • Send reminders: Send polite reminders to the debtor, either through email or phone calls.
  • Make phone calls: If reminders don’t work, try contacting the debtor directly to discuss the payment.
  • Send a demand letter: A demand letter is a formal notice informing the debtor of the consequences of non-payment, including your intention to forward their account to a collection agency.

Ready to send account to a Collection Agency

collection services

  • Verify the debt: Ensure the debt is valid and all necessary steps have been taken to collect it.
  • Choose a collection agency: Research and select a reputable collection agency.
  • Provide documentation: Provide the agency with all relevant documentation, including invoices, contracts, and communication records.
  • Monitor progress: Track the progress of the collection efforts on their online client portal.
  • Consider fixed fee service:  Although most people tend to go with contingency-only collections (No Recovery – No Fee), however it almost always better and cheaper to go for fixed-fee service that averages $20 per account.

Filed Under: Debt Recovery

  • « Go to Previous Page
  • Page 1
  • Interim pages omitted …
  • Page 7
  • Page 8
  • Page 9
  • Page 10
  • Page 11
  • Interim pages omitted …
  • Page 55
  • Go to Next Page »

Primary Sidebar


accounts receivable

Need a Collection Agency?
Kindly fill this form.
We’ll get in touch with you

    Please prove you are human by selecting the flag.

    Compliance & Security

    • SOC 2 Type II Certified: Third-party audited data security and strict privacy controls.

    • HIPAA Compliant: Secure, legal processing of medical and municipal EMS accounts.

    • PCI-DSS Level 1: Highest tier of data encryption for secure payment processing.

    • FDCPA & FCRA Aligned: Full legal adherence to federal consumer protection laws.

    Recent Posts

    • Why Dental Patients Dispute Bills: The Nexa Collections Dental Account Dispute Index
    • 2027 Commercial Collections Benchmark: U.S. Late Payments, AR Risk and B2B Collection Trends
    • Bulk Account Placement: What a Collection Agency Actually Needs From You
    • Nationwide Debt Collection Agency Serving U.S. Cities
    • Chula Vista Collection Agency for Medical, B2B, Schools & Business Debt
    • Corpus Christi Collection Agency: Itemized Bill Rules for Practices
    • Riverside Collection Agency | For Logistics, Medical, Schools & Business Recovery
    • Collection Agency for Large Balances: High-Value B2B Debt Recovery

    Featured Posts

    • Impact of Socio-Economic Condition on Health: 18 Facts
    • So many Indian Origin CEOs in Silicon Valley – Why?
    • 6 Steps to Creating Accurate Cash Flow Forecast for Your Business

    Copyright © 2026 NEXACOLLECT.COM | This content is provided for general informational purposes only and should not be considered legal advice. Collection laws and requirements may vary by state, account type, documentation, debtor status, and specific facts. Please consult qualified legal counsel for guidance regarding your particular situation. Nexa and its authorized collection partners service accounts in accordance with applicable federal and state collection requirements. Visit our home page to know more about us.

    X
    Need a Collection Agency?
    Contact Us