• Skip to main content
  • Skip to primary sidebar

Nexa Collections

  • Home
  • Serving
    • Medical
    • Dental
    • Small Business
    • Large Business
    • Commercial Collections
    • Government
    • Utilities
    • Fitness Clubs
    • Schools
    • Senior Care Facility
  • Contact Us
    • About us
    • Cost

Debt Recovery

2025-2026 ROI & Opportunity Matrix for Collection Agencies

collection agency outlook 2026

Debt collection in 2025–26 is shifting fast. Delinquencies are climbing across multiple industries, regulations are getting tougher, and clients want recovery solutions that protect their brand image as much as their bottom line.

Agencies that move early, stay compliant, and communicate respectfully are in the best position to win. Let’s break down where the real opportunities lie.


The Big Picture

Businesses everywhere — from trade schools to telecom companies — are under pressure to collect faster and more transparently. Regulation F, state-level laws, and new credit-reporting rules have made compliance more critical than ever.

The winning strategy?
Work early, use automation wisely, and combine fixed-fee programs with contingency collections. This dual approach keeps costs predictable for clients while boosting overall ROI.


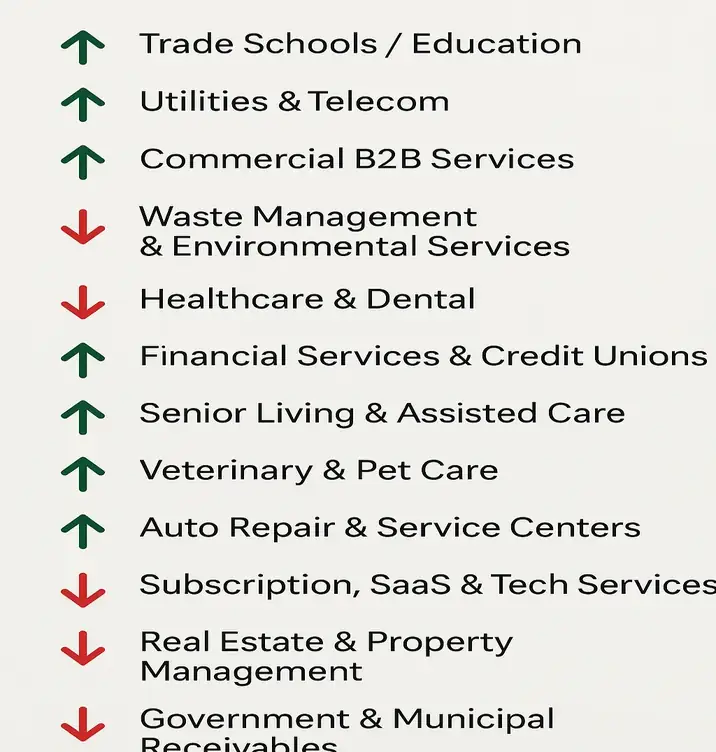
High-Potential Industries for 2025–26

Below are industries showing strong growth or stability for debt-collection services, grouped for readability instead of a wide table.

1. Education & Trade Schools

  • ROI: High

  • Risk: Low to Moderate

  • Volume: High
    Trade schools and vocational programs face steady delinquencies from tuition and course fees. They appreciate fixed-fee bulk recovery that preserves goodwill with students.


2. Utilities & Telecom

  • ROI: High

  • Risk: Low

  • Volume: Very High
    Recurring billing, high turnover, and cost-of-living pressures are creating record volumes. Automated reminders and self-service payment links work best here.


3. Commercial B2B Services

  • ROI: High

  • Risk: Moderate

  • Volume: High
    Staffing, leasing, and engineering firms struggle with client delays and contract disputes. These are ideal for contingency-based recovery, often with solid returns.


4. Waste Management & Environmental Services

  • ROI: High

  • Risk: Low

  • Volume: Moderate
    Regional haulers and recyclers see steady volumes of unpaid invoices. Early outreach preserves customer relationships while keeping internal AR lean.


5. Healthcare & Dental

  • ROI: Moderate

  • Risk: High

  • Volume: High
    Credit-reporting limits and medical-billing reforms mean compliance is everything. Focus on early patient engagement and compassionate communication.


6. Financial Services & Credit Unions

  • ROI: Moderate to High

  • Risk: High

  • Volume: Medium
    Rising defaults and tighter lending rules are bringing more accounts to agencies — but only those that meet strict data-security and member-sensitivity standards.


7. Senior Living & Assisted Care

  • ROI: High

  • Risk: High

  • Volume: Medium
    An aging population means more billing disputes over care balances. Sensitivity and empathy are critical, but ROI potential is strong with respectful handling.


8. Veterinary & Pet Care

  • ROI: High

  • Risk: Low

  • Volume: High
    Pet-care costs are climbing, and practices often face delayed self-pay balances. Friendly outreach yields surprisingly high recovery rates.


9. Auto Repair & Service Centers

  • ROI: High

  • Risk: Low

  • Volume: High
    Frequent small-ticket accounts make this perfect for fixed-fee placements. Low compliance exposure and strong repeat volume.


10. Subscription, SaaS & Tech Services

  • ROI: High

  • Risk: Low

  • Volume: Very High
    Cancellations and card-failures are driving spikes in receivables. Automated, digital-first recovery workflows perform best here.


11. Real Estate & Property Management

  • ROI: Moderate

  • Risk: Low to Moderate

  • Volume: Moderate
    HOA dues, tenant charges, and commercial rent balances are steady business. Legal awareness of landlord-tenant rules is key.


12. Government & Municipal Receivables

  • ROI: Moderate

  • Risk: High

  • Volume: Medium
    Permits, citations, and local fines require licensed, transparent processes. Bureaucratic but reliable for established agencies.


What’s Driving These Shifts

  1. Regulation Tightening:
    The CFPB’s proposed expansion of “larger participant” definitions could bring more agencies under direct oversight.

  2. Digital Outreach Rules:
    Email, SMS, and AI-based contact methods are now allowed — but closely watched.

  3. Medical-Debt Reforms:
    Accounts under $500 and surprise billing restrictions have reduced leverage for healthcare providers.

  4. Economic Strain:
    Interest rates and inflation are squeezing both consumers and businesses, increasing delinquency rates but also opportunity.


Smart Playbook for 2025–26

  • Go early. The younger the account, the higher the recovery and lower the risk.

  • Automate where it counts. Use tech for reminders, not for tone.

  • Show compliance. Transparency wins contracts and renewals.

  • Focus by region. States like Texas, Florida, Georgia, and North Carolina combine volume with manageable regulation.

  • Lead with empathy. Consumers and businesses respond to clarity and respect — not pressure.


The Bottom Line

The next 18 months belong to agencies that act like partners, not enforcers.
By combining compliance, technology, and timing, collection firms can scale responsibly and profitably.

Early, ethical, efficient — that’s the formula for growth in 2025 and beyond.
Filed Under: Debt Recovery

Timeshare Debt Recovery | Maintenance Fee Collections

Timeshare Debt Recovery: Protecting Resort Stability & Homeowner Equity

For a resort manager or HOA board, unpaid maintenance fees aren’t just a line item—they are a threat to the property’s physical integrity. When delinquency rises, the burden shifts to the paying owners, creating a “death spiral” of rising fees and further defaults.

Nexa provides a specialized, non-alienating recovery solution. We understand that timeshare owners are members of a community, not just “debtors.” Our approach focuses on resolving the underlying frustration that causes non-payment, ensuring your resort remains funded and your community remains intact.

Nexa provides 100% reputation-safe, equipped with all 50-state collections license, offering free credit reporting, free litigious debtor check, free bankruptcy scrub, and zero onboarding fees. Secure – SOC 2 Type II & HIPAA compliant. Over 2,000 online reviews rate us 4.85 out of 5. 

Need a Collection Agency? Contact us


The Timeshare Reality: By the Numbers

  • $2.4 Billion: The estimated annual loss in the industry due to unpaid maintenance fees and assessment defaults.

  • 18%: The average delinquency rate for resorts without an active, third-party recovery partner.

  • 85%: The success rate of our Step 1 Soft-Touch notice in “re-engaging” owners before they fall into the hands of predatory “Timeshare Exit” scams.

  • Zero-Touch Compliance: Full adherence to FDCPA and TCPA, assuming 100% of the regulatory risk for your HOA or management company.


The Nexa 4-Step “Community-Safe” Ladder

  1. Step 1: The Account Re-Engagement (Fixed Fee). Best for accounts 30–90 days past due. We send professional, white-labeled demands that frame the payment as a “contribution to the resort’s future.” You keep 100% of the funds recovered.

  2. Steps 2-4: Specialized Mediation (Contingency). For aged or high-dispute accounts. Our mediators are trained to handle “exit-scam” rhetoric and complex deed-back negotiations. No Recovery = No Fee.


Why Resort Managers Choose Nexa

  • Counter-Exit Strategy: We educate owners on the dangers of “Timeshare Exit” scams. By providing an official channel for resolution, we stop them from paying thousands to scammers instead of their maintenance fees.

  • Deed-in-Lieu Mediation: Sometimes the best recovery is an “amicable exit.” We facilitate deed-backs and title transfers to return units to the “paying inventory” faster.

  • 50-State & International Reach: Timeshare owners live everywhere. We have the licensing to follow the debt wherever the owner resides.


Recent Timeshare Recoveries

  • Legacy Resort (Florida): Recovered $412,000 in back-due maintenance fees across 150 units in 90 days.

  • HOA Managed Property (Nevada): Reduced the “Bad Debt” write-off by 35% in one year by implementing our Step 1 notice at the 45-day mark.

  • Fractional Ownership Group: Secured $88,000 from international owners who had “ghosted” the property for two years.


Frequently Asked Questions (FAQ)

1. How do you handle owners who are working with “Exit Companies”?
We are aggressive in educating owners that paying a third party to “cancel” a contract rarely works and ruins their credit. We offer them a direct path to resolution with the resort.

2. Can you help with “Deed-backs”?
Yes. If an owner truly cannot pay, our mediators can facilitate an amicable surrender of the unit, allowing you to resell or re-rent the inventory rather than letting it sit in a 2-year foreclosure process.

3. Is this safe for our resort’s reputation?
Yes. We maintain a 4.85 Google Rating. We treat your owners with the same hospitality they expect at the front desk, while firmly reminding them of their financial obligations.


👉 At the end of the day, timeshare AR challenges aren’t just about money—they’re about protecting relationships, reputations, and the long-term health of your business. That’s why so many resorts and HOAs trust NexaCollect. With a proven track record, a near-perfect Google rating, and services designed to recover more while costing you less, we turn AR nightmares into solvable problems.

Contact Nexa Today

Filed Under: Debt Recovery

When Should I Send Dental Accounts to Collections? A Guide for a Healthy Practice

blank

Introduction: The Knot in Your Stomach

You know that feeling. The stack of unpaid invoices that feels less like paper and more like a pile of unanswered questions. How long should you wait? Should you send another reminder? What if you lose a patient you’ve cared for?

As a dental professional, you didn’t choose this field to become a bill collector. Your heart is in patient care. But at the same time, your practice is a business. Without steady cash flow, even the best care becomes hard to sustain.

This guide is here to help you remove the guesswork. I’ll walk you through the clear signals that it’s time to involve a collections partner—not as a last resort, but as a smart step to protect your practice’s health and restore your peace of mind.


Before You Pick Up the Phone: The Internal Collections Checklist

Before reaching out to an agency, it’s important to make sure your in-house process has been solid. That way, when you do send accounts to collections, you know you’ve done everything you reasonably could. Think of this as your pre-checklist:

  • Crystal-Clear Financial Policy
    Did the patient know from the start what their insurance covered, what they were responsible for, and when payment was due? Transparency sets the tone.

  • Consistent In-House Efforts
    Best practices often look like this:

    • Statement at 30 days

    • Friendly reminder call at 45 days

    • Direct letter at 60 days

    • Final notice around 75–90 days

  • Multiple Contact Attempts
    Not everyone responds to a mailed statement. Try a mix: phone call, email, even a portal message.

  • Offer of a Payment Plan
    Flexibility matters. Sometimes, the willingness to break a balance into smaller payments is all it takes.

If you’ve checked all these boxes and the balance is still unpaid, it’s time to look for the red flags.


The Tipping Point: 5 Undeniable Signs It’s Time to Call a Partner

1. The 90/120-Day Wall

Here’s the truth: the longer a balance lingers, the less likely it is to be collected. After 90 days, the chances of recovery drop steeply. At 120 days, they plummet. Waiting longer doesn’t help—it only costs your practice more.

2. The Sound of Silence (Ghosting)

You’ve called. You’ve emailed. You’ve mailed. And still—nothing. No callbacks, no replies, no engagement. At this point, it’s not just forgetfulness; it’s avoidance.

3. A Pattern of Broken Promises

The patient agreed to a payment plan, but payments are missed again and again with no explanation. This isn’t a temporary hiccup—it’s a sign the intent to pay may not be there.

4. Invalid Disputes

You’ve provided proof. You’ve shown documentation. Yet the patient continues to dispute the bill with excuses you know don’t hold water. These stall tactics are a sign it’s time to escalate.

5. The Cost-Benefit Imbalance

Your staff is spending more time chasing an old $400 balance than supporting today’s patients. When the cost of effort outweighs the potential recovery, that’s a clear sign it’s time for help.


Why Waiting Too Long Hurts More Than It Helps

Let’s address the hesitation head-on.

  • The Fear: “If I send this account to collections, I’ll lose the patient or get a bad review.”

  • The Reality: By waiting too long, you risk something bigger—your practice’s financial stability, your staff’s morale, and your ability to focus on patients who are paying and present.

The Hidden Costs of Delay

  • Cash flow slows down

  • Staff frustration increases (“I didn’t go to dental school to be a collector”)

  • The debt itself loses value

The Right Agency Protects Your Reputation

Not all agencies are the same. A professional, HIPAA-compliant partner acts as an extension of your office. The right team uses respectful, compassionate communication that helps patients take responsibility—without tarnishing your reputation.


It’s Not Giving Up, It’s Taking Control

Sending an account to collections isn’t about failure. It’s about protecting your practice, your team, and your ability to serve patients for years to come.

If these signs feel all too familiar, maybe it’s time to have a conversation. Let’s talk about how a compassionate, professional partner can help you recover what you’re owed—while keeping your patient relationships and your peace of mind intact

Filed Under: Debt Recovery

Debt Collection for Telehealth Providers: Proven Strategies & Best Practices

Telehealth and virtual care have dramatically reshaped healthcare delivery, providing accessible, efficient, and patient-friendly alternatives to traditional in-person visits. Yet, telemedicine brings unique billing and debt collection challenges, requiring tailored strategies distinct from conventional medical billing.

Telehealth providers should partner with a collection agency that is HIPAA-compliant, highly rated, licensed in all 50 states, and experienced in medical collections. Just as importantly, the agency must prioritize data security and protect your reputation through respectful, patient-friendly practices.

blank

Why Telehealth Debt Collections are Different

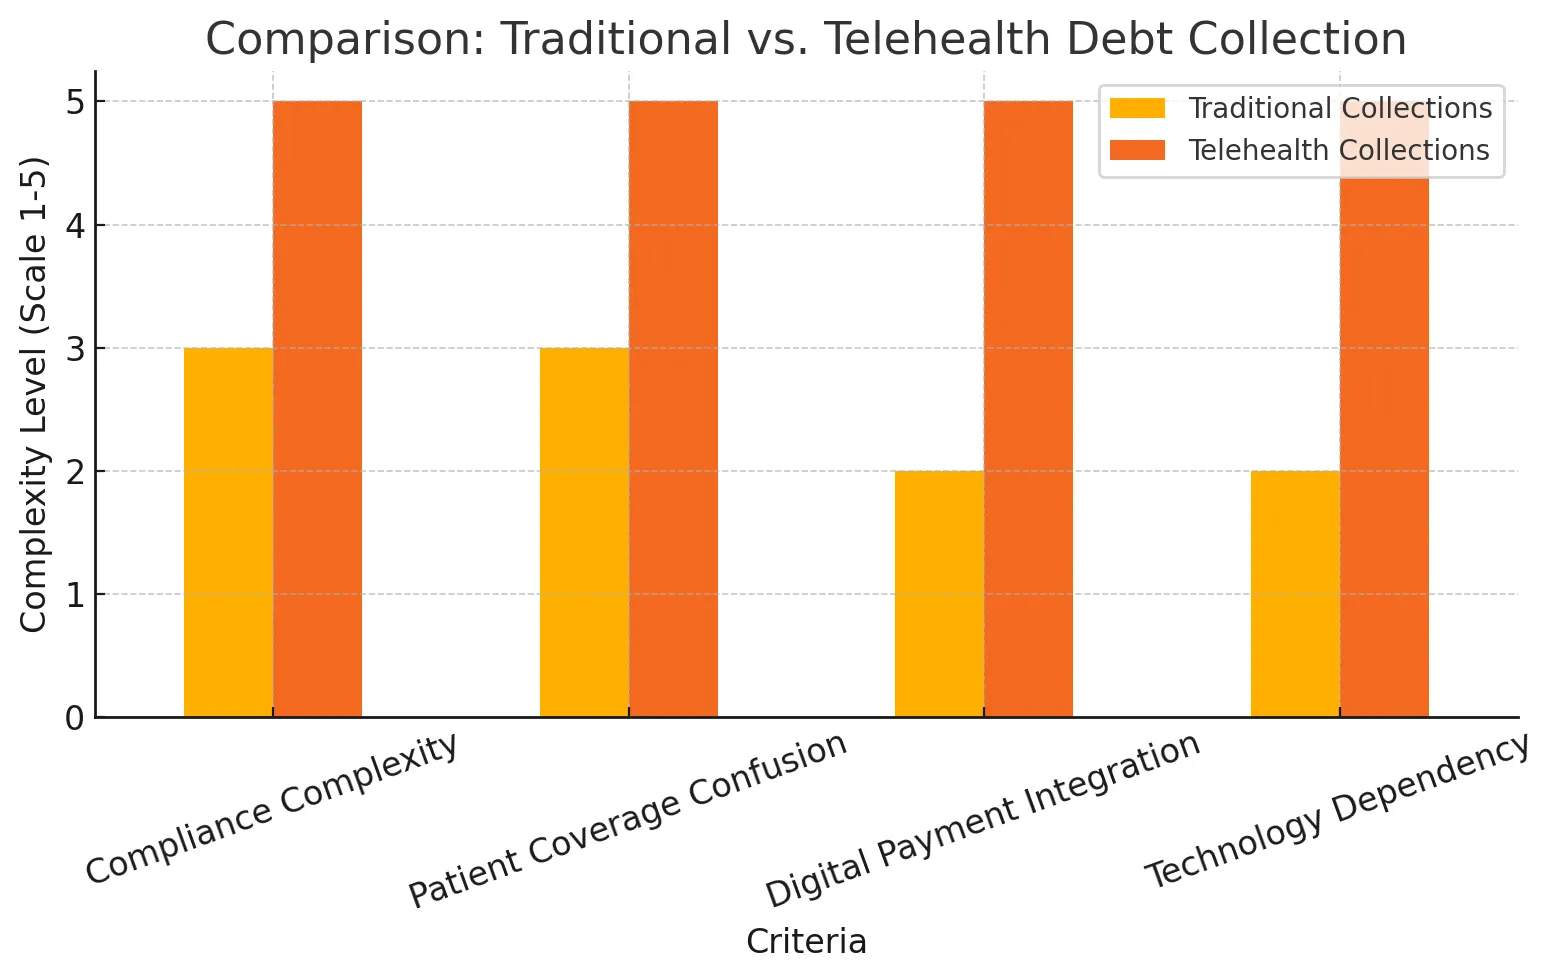
Telehealth collections differ significantly from traditional medical billing due to:

  • Geographic complexity: Telehealth providers often treat patients across state lines, introducing varied billing regulations and compliance requirements.
  • Technology-driven workflows: Virtual care relies heavily on digital payments and patient portals, necessitating robust online billing systems.
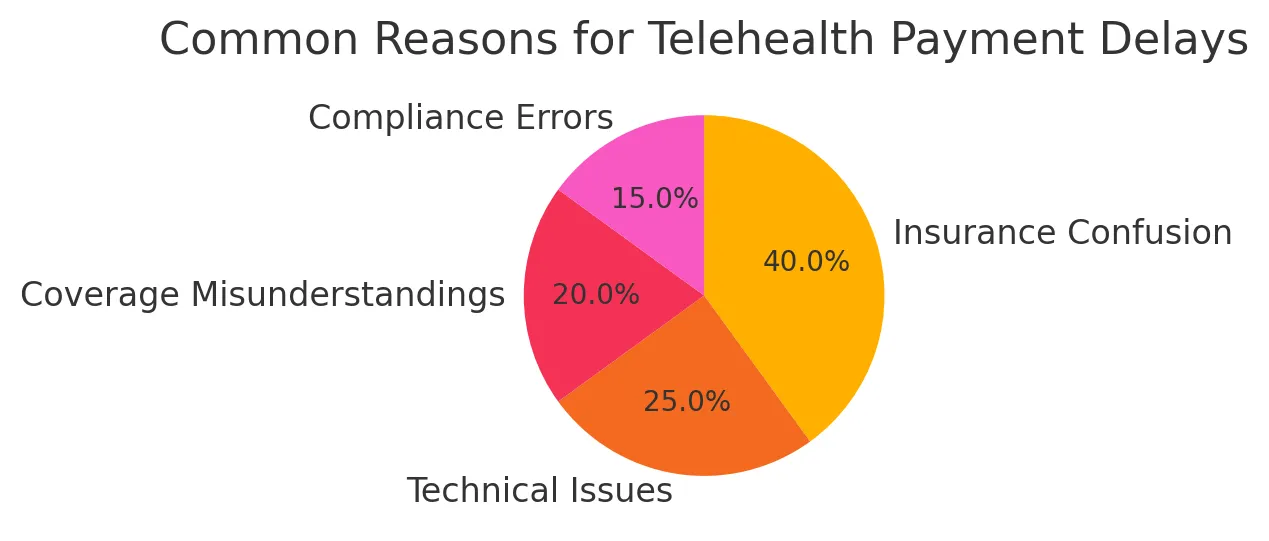
  • Insurance variability: Telehealth insurance coverage can differ greatly depending on the patient’s policy, state, and the nature of virtual visits, often resulting in unexpected denials.

Unique Challenges in Telehealth Debt Collection

  1. Compliance Across Jurisdictions: Telehealth providers must comply with differing state laws, licensing requirements, and telehealth-specific billing regulations. Failure can lead to denied claims and collection complexities.

    Example: A virtual mental health provider treating patients in multiple states must adhere to each state’s telehealth reimbursement rules to avoid insurance rejections.

  2. Patient Confusion Regarding Coverage: Patients often misunderstand the scope of their telehealth coverage, resulting in higher rates of non-payment or delayed payments.

    Example: Patients might assume all virtual visits are fully covered, only discovering afterward that certain visits, such as teletherapy sessions, have limited coverage.

  3. Integration with Digital Payment Platforms: Effective collections require seamless integration with user-friendly online payment systems. Telehealth providers who lack intuitive payment portals see higher delinquency rates.

    Example: Practices using platforms like Healow or MyChart for seamless bill payments see increased promptness and satisfaction compared to those using disconnected systems.

Effective Debt Collection Strategies for Telehealth

  • Clear Communication of Coverage: Ensure patients clearly understand their financial obligations before appointments, reducing disputes and confusion.
  • Omnichannel Billing Solutions: Provide multiple digital payment options, such as mobile payments, online portals, or SMS-based systems, enhancing convenience.
  • Real-Time Eligibility Verification: Adopt technology that checks insurance eligibility instantly, reducing claim denials and associated collections.
  • Compassionate Virtual Collection Practices: Telehealth is rooted in convenience and care—collection practices should reflect this ethos, employing empathy-driven scripts and digital reminders.

Selecting the Right Collection Agency for Telehealth

When outsourcing collections, telehealth providers must look specifically for agencies that:

  • Have Multi-State Compliance Expertise: Ensure the agency is adept at managing collections under varying state telehealth regulations and laws.
  • Leverage Technology for Efficiency: Agencies should integrate seamlessly with telehealth providers’ existing billing and patient portal systems, providing frictionless payment experiences.
  • Offer Clear, Empathetic Communication: Prioritize agencies with a proven record of compassionate collection practices that align with telehealth’s patient-first model.
  • Demonstrate Proven Telehealth Experience: Select agencies familiar with telehealth nuances, insurance complexities, and virtual care billing dynamics.

blank

Real-World Success Story

 A national telehealth provider partnered with a tech-forward collection agency, integrating their patient portal with the agency’s collection software. Within six months, patient satisfaction improved, and collections increased by 25%.

Conclusion

Debt collection for telehealth and virtual care is complex but manageable with strategic approaches that prioritize compliance, technology integration, and patient-focused communication. By thoughtfully selecting partners and investing in efficient digital systems, telehealth providers can significantly improve revenue cycles while enhancing patient satisfaction.

Filed Under: Debt Recovery

The Rise of Mobile Payment Solutions in Debt Collection

blank

Debt collection has traditionally been viewed as a slow, paper-heavy process. However, the smartphone has revolutionized the industry. Today, if a debtor cannot pay with two taps on their screen, they likely won’t pay at all.

Mobile payment solutions offer both debtors and creditors a seamless, efficient method to manage debt repayment—removing the “friction” that causes most unpaid bills.

Why Mobile Payments Are Changing Debt Collection

In recent years, consumer behavior has shifted entirely to mobile. Speed is the new currency. For debt collection specifically, mobile platforms significantly enhance repayment rates by meeting the debtor where they are: on their phone. Traditional methods—like mailing a check or reading a 16-digit credit card number over the phone—create barriers. Mobile payments remove them.

Benefits of Mobile Payments in Debt Collection

1. Increased Convenience (The “Frictionless” Experience)

Mobile payments eliminate the need for physical checks, stamps, or even logging into a desktop computer. Debtors can settle debts instantly via a secure link sent to their phone.

  • Stat: Payment portals optimized for mobile see a 30% higher conversion rate than desktop-only sites.

2. Faster Collection Rates

Immediate payment options shorten the collection cycle. Instead of waiting 5–7 days for a check to arrive, funds are verified and deposited instantly. This dramatically improves cash flow for businesses.

3. Enhanced Security & Compliance

Modern mobile payments use tokenization and biometrics (Face ID/Touch ID). This is far more secure than writing credit card numbers on paper forms.

  • Note: Professional mobile gateways are PCI-DSS compliant, protecting you from data breach liability.

4. Reduced Operational Costs

Digital payments lower administrative overhead. There is no envelope to stuff, no postage to buy, and less staff time spent on manual data entry.

Real-World Mobile Solutions (And What to Avoid)

1. Text-to-Pay (SMS Links)

This is the gold standard for 2025. The agency sends a secure, encrypted link via SMS. The debtor clicks, verifies their identity (DOB or Zip), and pays.

  • Why it works: Open rates for SMS are 98%, compared to just 20% for email.

2. Digital Wallets (Apple Pay & Google Pay)

Integrating Apple Pay and Google Pay is crucial. It allows debtors to pay using the card already stored in their phone.

  • The Benefit: It eliminates the excuse “I don’t have my wallet on me right now.”

3. A Warning on Consumer Apps (Venmo/Zelle)

  • Caution: While apps like Venmo and Zelle are popular for friends, businesses should be very careful.

  • The Risk: Using personal Venmo accounts for business debt collection can violate Terms of Service and lead to account bans.

  • The Compliance Trap: Publicly visible transactions on Venmo can violate HIPAA (for medical debt) and FDCPA privacy laws. Always use a professional merchant processor, not a peer-to-peer app.

Overcoming Resistance & Ensuring Compliance

The Challenge: TCPA Laws

The biggest hurdle to mobile collections is not technology—it is the law. The Telephone Consumer Protection Act (TCPA) restricts how businesses can text consumers.

  • The Solution: Professional agencies use “Safe Harbor” software that manages consent. We never text a debtor without verifying the number and ensuring we have the right to contact them.

The Challenge: Security Concerns

Debtors are wary of clicking links.

  • The Solution: Build trust by using branded URLs (e.g., pay.yourbusiness.com) rather than generic link shorteners, and always require a verification step (like entering a Zip Code) before displaying the balance.

The Future of Mobile Payments in Debt Collection

As digital transformation accelerates, “paper billing” will become obsolete. Innovations such as AI-driven payment reminders (which send texts at the exact time a person is most likely to look at their phone) and QR Codes on letters are already becoming standard.

Conclusion

Debt collection agencies that proactively adopt Text-to-Pay and Mobile Wallets will not only improve their recovery rates but also significantly enhance debtor satisfaction. In the modern economy, the easier you make it to pay, the faster you get your money.

Filed Under: Debt Recovery

Credit Bureau Reporting Forbidden on Several Types of Debts

We have been made aware of a growing concern that collection agencies are increasingly not reporting debts to credit bureaus. Believe us when we say that creditors across various industries are voicing their complaints. Obviously, this has a negative impact on the recovery rate.

If collection agencies had the ability to report every legitimate debt, they certainly would when all other collection efforts fail. However, the reality is that Credit Reporting Agencies (CRAs) — TransUnion, Experian, and Equifax — do not permit it in all cases.

Here is an excerpt from the credit reporting manual of one of the major CRAs:

We does not accept the following types of data from our furnishers, either directly or as collection accounts that have been assigned to third parties.

  •  Fines and Fees – Examples include but are not limited to:
    –  Towing Charges
    – Vehicle Storage Fees
    – Parking and Traffic Tickets/Fines
    – Toll Road Fines/Fees
    – Ordinance Violations
    – Library Fines
    – Video Rental Fees
    – Prequalification Fees
    – Brokerage Fees
    – Eviction Fees
  • Continuity Clubs – Examples include but are not limited to:
    – Health Club Dues
    – Karate Club/Martial Arts Dues
    – Magazine Subscriptions
    – DVD/Book Club Fees
  •  Pre-Paid Debit/Gift Cards
  •  Checking/Savings Account Activity/Balances
  •  Home Owners’ Association (HOA) Dues
  • Child Support Enforcement Data from Non-Government Entities
  • Tribal loans not compliant with federal and state lending laws
  •  Unpaid Taxes*
  • Unacceptable Data by Industry Type – Bail Bonds Companies – Check Cashing Companies – Pay Day Loan Companies

The banking industry has been hit with what the CFPB called “Junk fees” and there is a full assault on collection agencies attempting to collect medical debt – not only from the CFPB on the federal side, but from the state side too.

Already a dozen states made it illegal to credit report on medical debts. Even a state like Indiana (a traditional red state) is not only attempting to block credit reporting but also stating that collection agencies would not be able to get judgments if they file suit.  This is problematic.

If the balance merits it ($2K+) and the debtor has a decent credit score, job and maybe some assets like a home, Collection Agencies could file suit.

( Article written on 02/20/2025)

Filed Under: Debt Recovery

  • « Go to Previous Page
  • Page 1
  • Interim pages omitted …
  • Page 5
  • Page 6
  • Page 7
  • Page 8
  • Page 9
  • Interim pages omitted …
  • Page 55
  • Go to Next Page »

Primary Sidebar


accounts receivable

Need a Collection Agency?
Kindly fill this form.
We’ll get in touch with you

    Please prove you are human by selecting the plane.

    Compliance & Security

    • SOC 2 Type II Certified: Third-party audited data security and strict privacy controls.

    • HIPAA Compliant: Secure, legal processing of medical and municipal EMS accounts.

    • PCI-DSS Level 1: Highest tier of data encryption for secure payment processing.

    • FDCPA & FCRA Aligned: Full legal adherence to federal consumer protection laws.

    Recent Posts

    • Why Dental Patients Dispute Bills: The Nexa Collections Dental Account Dispute Index
    • 2027 Commercial Collections Benchmark: U.S. Late Payments, AR Risk and B2B Collection Trends
    • Bulk Account Placement: What a Collection Agency Actually Needs From You
    • Nationwide Debt Collection Agency Serving U.S. Cities
    • Chula Vista Collection Agency for Medical, B2B, Schools & Business Debt
    • Corpus Christi Collection Agency: Itemized Bill Rules for Practices
    • Riverside Collection Agency | For Logistics, Medical, Schools & Business Recovery
    • Collection Agency for Large Balances: High-Value B2B Debt Recovery

    Featured Posts

    • Printing & Mailing Collections: Protecting Your Margins Without Burning Bridges
    • Improve Efficiency of Remote Employees
    • How to Negotiate Payment for Your Overdue Bill

    Copyright © 2026 NEXACOLLECT.COM | This content is provided for general informational purposes only and should not be considered legal advice. Collection laws and requirements may vary by state, account type, documentation, debtor status, and specific facts. Please consult qualified legal counsel for guidance regarding your particular situation. Nexa and its authorized collection partners service accounts in accordance with applicable federal and state collection requirements. Visit our home page to know more about us.

    X
    Need a Collection Agency?
    Contact Us