• Skip to main content
  • Skip to primary sidebar

Nexa Collections

  • Home
  • Serving
    • Medical
    • Dental
    • Small Business
    • Large Business
    • Commercial Collections
    • Government
    • Utilities
    • Fitness Clubs
    • Schools
    • Senior Care Facility
  • Contact Us
    • About us
    • Cost

Debt Recovery

Collection Agency in Stamford, CT | Compliant & Effective

Stamford’s Capital Recovery: High-Impact Results Without the Friction

Stamford isn’t just a stop on the Metro-North; it’s the financial engine of Fairfield County. From the corporate towers of Harbor Point to the bustling medical offices along Summer Street, your business moves at a relentless pace. Don’t let uncollected invoices stall your momentum on the I-95 corridor—let our team recover what’s yours while you focus on scaling.

Nexa provides a reputation-safe approach, equipped with all 50-state collections license, offering free credit reporting, free litigious debtor check, free bankruptcy scrub, and zero onboarding fees. Secure – SOC 2 Type II & HIPAA compliant. Over 2,000 online reviews rate us 4.85 out of 5. 

Need a Collection Agency? Contact us


Transparent Pricing for Local Growth

We believe in straightforward numbers that protect your bottom line. Whether you are a boutique firm in the South End or a large-scale contractor near the Port of Stamford, our rates are fixed and fair:

  • Flat-Fee Recovery: $15 per account. You retain 100% of the recovered funds.

  • Performance-Based: 40% contingency. If we don’t recover your money, you don’t pay a dime.

Pro-Tip for Local Business Owners: Most of our clients effectively neutralize the cost of our $15 service. By consulting with your CPA, you can often categorize these fees as a deductible Business Expense, essentially making the service free.


The “Velvet Hammer” Philosophy

The Account Reconciliation Team operates on a simple truth: you get more with a handshake than a closed fist. We use a diplomatic style—firm enough to secure immediate payment, but respectful enough to safeguard your 5-star reputation. In a high-density hub like Stamford, news travels fast; we ensure your brand remains “reputation-safe.”

We prioritize working with the debtor to find a path to “Current” status. When a person feels respected, they are statistically more likely to pay you before they pay a more aggressive, abrasive creditor.


A Note From Our Reconciliation Team

“We see ourselves as an extension of your front office. When you assign an account to us early, the recovery rate skyrockets. We handle the difficult conversations and the Spanish-language outreach so your employees can stick to the work they actually enjoy. We don’t just ‘collect’; we resolve.”


Success Stories: Recent Recovery Results

Medical Practice Resolution (Stamford)

A specialized surgical center near Stamford Hospital had a high-balance debt from an out-of-network procedure.

  • Phase 1: We initiated a bankruptcy and litigation scrub to ensure the patient was solvent.

  • Phase 2: Our bilingual team contacted the debtor, discovering a simple insurance coding misunderstanding.

  • Result: We mediated the balance, securing full payment within 14 days without a single negative review for the clinic.

B2B Commercial Recovery (Norwalk)

A restoration company working on a multi-family project near the Merritt Parkway was ignored for sixty days by a subcontractor.

  • Phase 1: We utilized skip-tracing and USPS address verification to locate the principal owner who had moved offices.

  • Phase 2: We presented a “Cooperative Mediation” plan, emphasizing the protection of their own credit rating.

  • Result: The subcontractor paid the full balance via an expedited electronic transfer.


Sector-Specific Solutions

  • Healthcare & Medical: 100% HIPAA-compliant recovery for the regional medical hubs and private clinics.

  • Colleges & Universities: Balancing tuition and housing recovery with the delicate student-institution relationship.

  • Construction & Trades: Aggressive revenue recovery for HVAC, electrical, and general contractors working the Gold Coast.

  • Dental: Specialized focus on orthodontics and family dentistry patient balances.

  • K-12 Private & Charter Schools: Diplomatic handling of unpaid enrollment and textbook fees for the city’s premier educational centers.

  • Accountants & CPA Firms: Respectful professional service fee recovery that mirrors your own high standards.

  • Banks & Credit Unions: Expert management of delinquent consumer loans and overdrawn accounts using high-level skip tracing.

  • B2B & Industrial: Recovery for waste management, restoration, and heavy equipment sectors.


Protecting Your Interests: The Red Flag Box

Three pitfalls Stamford businesses often face when chasing debt alone:

  1. The “Ghost” Debtor: Failing to verify current addresses via USPS before sending notices.

  2. Reputation Damage: Engaging in heated arguments that lead to “review-bombing.”

  3. Legal Exposure: Ignoring the nuances of the FDCPA or state-specific communication limits.


Standards and Compliance

We utilize a multi-layered verification process including USPS address checks, skip tracing, and bankruptcy scrubs. If permitted and requested, we can also facilitate credit reporting. To ensure every interaction is “Velvet Hammer” quality, all calls are recorded and randomly reviewed. This prevents “rogue” behavior and protects you from legal or social media blowback.

Practical Framework: Our process aligns with the Federal Fair Debt Collection Practices Act (FDCPA) and Connecticut’s specific debt collection regulations, focusing on ethical contact frequencies and clear disclosure.


Frequently Asked Questions

Is your team equipped for Stamford’s diverse population?

Absolutely. We have Spanish-speaking collectors on board to ensure clear, bilingual communication, which is essential for the diverse workforce in Fairfield County.

Why should I hire you instead of using my own staff?

Your team was hired for their expertise in medicine, law, or trade—not for the stress of collections. Our involvement signals to the debtor that the matter has escalated, which significantly improves the recovery rate.

What happens if the debtor has moved?

We use advanced skip tracing and USPS data to find their “Current” location. We don’t just mail letters to old addresses; we find where the money is.
Contact Nexa Today

Filed Under: Debt Recovery

Arizona Medical & Dental Collection Agency | HIPAA-Compliant Recovery

Arizona medical collections work best when patient balances are addressed early, clearly, and respectfully.

From medical offices and dental practices in Phoenix and Scottsdale to hospitals, urgent care centers, ophthalmologists, surgery centers, imaging facilities, and senior living providers across Mesa, Tucson, Peoria, and communities statewide, unpaid self-pay and post-insurance balances can quickly become difficult receivables.

Nexa brings Arizona-focused healthcare collection experience to these accounts, combining HIPAA-compliant communication, payment resolution, persistent follow-up, bilingual outreach when needed, and appropriate escalation. Arizona’s Proposition 209 has also tightened the rules around medical-debt interest and wage garnishment, making thoughtful patient engagement even more important. The goal is straightforward: recover more patient revenue while reducing staff workload and protecting the reputation of your healthcare organization.

Arizona medical collection agency helping healthcare providers recover overdue patient balances

Nexa provides  reputation-safe, equipped with all 50-state collections license, offering free credit reporting, free litigious debtor check, free bankruptcy scrub, and zero onboarding fees. Secure – SOC 2 Type II & HIPAA compliant. Over 2,000 online reviews rate us 4.85 out of 5. 

Need an Arizona Medical Collection Agency? Contact us


The Nexa Efficiency: The $15 Fixed-Fee Utility

Arizona providers require a financial model that is predictable, compliant, and high-velocity. Our pricing is designed to keep your clinical mission liquid and your overhead low:

  • Fixed-Fee Reconciliation: A flat $15 per account. Your practice retains 100% of the recovered balance.

  • Contingency Strategy: A 40% fee strictly for legacy or high-complexity accounts where no recovery means no fee.

  • The CPA Advantage: Nexa’s $15 fee is specifically structured to be neutralized as a tax-deductible business expense, effectively turning our services into a cost-neutral utility for your back office.

Get a Free Arizona Accounts Receivable Audit


Clinical Philosophy: Respectful Friction in the Prop 209 Era

We act as “Clinical Authority” mediators who clear “billing static” while remaining HIPAA compliant and fully aligned with Arizona’s Predatory Debt Collection Protection Act.

  • Peace of Office: We eliminate the burnout associated with financial friction, allowing your staff to focus on patient outcomes rather than balance discussions.

  • Respectful Friction: We don’t use aggressive tactics. Instead, we use a mediation-first model that assists patients in understanding their obligations, which is critical given Arizona’s strict 10% wage garnishment caps.

  • Bilingual Outreach: Our specialized Spanish-speaking experts ensure faster resolution and inclusivity for the state’s diverse patient populations.


Localized Recovery Results: Arizona Case Files

Medical Specialist (Senior Living) | Peoria:

The Case: A facility near Plaza del Rio struggled with $92k in accounts due to complex out-of-pocket coordination.

The Intervention: Our Account Reconciliation TEAM implemented localized, respectful outreach cycles.

The Financial Result: $68,000 recovered in 90 days with zero reputational impact.

Orthodontic Practice | Scottsdale:

The Case: A high-volume practice near the Shea Medical Center was buried under hundreds of small-balance accounts.

The Intervention: Applied our $15 fixed-fee model to automate patient engagement through our Arizona-compliant platform.

The Financial Result: 81% recovery rate on targeted accounts, significantly stabilizing monthly cash flow.


The Security & Integrity Suite

Nexa protects your clinical reputation through a technology-driven data standard that is fully compliant with Arizona local laws:

  • The Patient Scrub: Every account undergoes a Litigation Check, Bankruptcy verification, and USPS scrubbing. We specifically screen for litigious history to protect your practice from aggressive lawsuits.

  • Reputation Preservation: 100% of calls are recorded and reviewed. This protects you from “review-bombing” and ensures every interaction matches your professional standards.

  • Modern HIPAA Channels: We utilize secure, encrypted email and text messaging to meet patients where they are most comfortable—on their devices.


Areas of Clinical Expertise

  • Healthcare & Medical: Regional systems, hospitals, and multi-specialty clinics.
  • Dental: General dentistry, orthodontics, and maxillofacial surgery.
  • Senior Living: Assisted living and skilled nursing facilities.
  • Specialized Centers: Fertility and cosmetic surgery suites.

For general medical collections methodology beyond Arizona specifics, see Nexa’s medical debt recovery services. See full pricing details for how the fixed-fee and contingency tiers compare.


Arizona Regulatory & Compliance FAQ

Does Arizona’s 3% interest cap apply to medical debt from before Prop 209 took effect?

No. Arizona’s Court of Appeals confirmed in 2024 that Proposition 209’s protections, including the 3% interest cap and 10% garnishment limit, apply only to medical debt incurred after the law’s effective date of December 5, 2022. Older balances may still be governed by the prior rules, up to 10% annual interest and 25% wage garnishment, so account age determines which framework actually applies.

What is Arizona’s wage garnishment limit for medical debt, and can it go lower than that?

Arizona generally caps wage garnishment at 10% of a debtor’s disposable earnings under Proposition 209, down from the prior 25% limit. Courts can reduce that further to 5% if the debtor demonstrates genuine economic hardship, so a judgment doesn’t guarantee the full 10% will actually be collected in every case.

What is the statute of limitations for medical debt in Arizona?

Arizona generally allows six years to pursue legal action on medical debt and most written contracts, measured from the date the debt became due. Recovery odds decline well before that legal deadline, which is why our model focuses on the first 120 days of delinquency rather than waiting until an account nears the statutory limit.

Does Prop 209 protect a patient’s bank account or other assets, not just wages?

Yes. Alongside the interest and garnishment limits, Proposition 209 raised Arizona’s bank account exemption to $5,000, up from $300, and increased the homestead exemption to roughly $437,000, adjusted annually for inflation. These asset protections apply to debt collection generally, not only medical debt, so a judgment against a patient may recover less than expected if their assets fall within these shielded amounts.

Do Prop 209’s protections apply only to medical debt, or to all consumer debt in Arizona?

It depends on which protection. The 3% interest cap and 10% wage garnishment limit apply specifically to medical debt, while non-medical debt remains subject to the prior 10% annual interest rate and higher garnishment exposure. The asset exemptions, including the bank account and homestead protections, apply to debt collection broadly, not just medical accounts.

How does Nexa determine whether a specific patient balance qualifies for the 3% cap?

The determining factor is the date the debt was incurred, not the date it’s being collected, since only medical debt from December 5, 2022 onward qualifies for the reduced interest rate and garnishment exposure. Our intake process reviews account origination dates before applying interest or pursuing enforcement, which avoids miscalculating what’s actually owed or collectable on older balances.


Are you ready? Contact us

Filed Under: Debt Recovery

Collection Agency in Fullerton, CA | Compliant & Effective

The Fullerton Bottom Line: Protecting Your Reputation While Securing Your Cash

Business in the “Education City” moves fast, from the bustling commerce near Cal State Fullerton to the industrial corridors along the 91 Freeway. If your accounts receivable are lagging, you don’t need a shouting match; you need the Account Reconciliation Team to apply the “Velvet Hammer”—a firm, reputation-safe approach that gets you paid without the public relations nightmare. We understand that in a community this tight-knit, your brand is as valuable as your bank balance.

Nexa provides a reputation-safe approach, equipped with all 50-state collections license, offering free credit reporting, free litigious debtor check, free bankruptcy scrub, and zero onboarding fees. Secure – SOC 2 Type II & HIPAA compliant. Over 2,000 online reviews rate us 4.85 out of 5. 

Need a Collection Agency? Contact us


Transparent Recovery Pricing

We believe in straightforward math, tailored to your risk comfort:

  • The Flat-Fee Edge: Only $15 per account. You retain 100% of the recovered funds.

  • The Performance Model: A 40% contingency fee. If we don’t recover a dime, you don’t owe us a cent.

blank

Money Saver Tip: Most of our Fullerton partners effectively eliminate our fixed-fee cost by classifying it as a Business Expense on their tax filings after a quick chat with their CPA.


Why Cooperative Mediation Outperforms Confrontation

In the current economic climate, aggressive arguing builds walls; diplomatic mediation builds bridges to your money. We prioritize making your invoice the one the debtor wants to pay first. By treating people with respect and utilizing bilingual Spanish-speaking collectors, we navigate the diverse demographic landscape of Orange County with ease.

Our “Velvet Hammer” methodology ensures we are firm enough to secure a commitment but soft enough to protect your 5-star online rating. Before we even dial a number, we perform a litigation scrub and bankruptcy check to ensure we aren’t chasing ghosts or legal traps. This data-driven precision is why our recovery rates consistently tower over the industry average.


Recent Recovery Results

Medical Specialty – Fullerton
A private surgical clinic near the St. Jude Medical Center hub had a high-balance debt lingering for months.

  • Step 1: We performed a skip trace and address check via USPS to locate the patient who had moved.

  • Step 2: Our team initiated a series of empathetic, recorded calls to establish a voluntary repayment schedule.

  • Step 3: Total balance was recovered in 45 days without a single negative review for the clinic.

B2B Construction – Placentia
An HVAC contractor servicing residential developments near Kraemer Blvd was owed for a large-scale installation.

  • Step 1: We identified a breakdown in communication regarding the final inspection.

  • Step 2: Our Account Reconciliation Team acted as a neutral third party to verify the debt’s validity.

  • Step 3: Secured a wire transfer for the full amount within 14 days by focusing on the debtor’s professional reputation.


Localized Industry Expertise

  • Healthcare & Medical: HIPAA-compliant recovery focused on the specialty clinics and wellness centers surrounding Fullerton’s major medical corridors.

  • Colleges & Universities: Managing tuition and housing balances for the student-heavy population near Nutwood Avenue. We balance firm tactics with the need to preserve institutional standing.

  • Dental: Specialized focus on orthodontics and family practices requiring a gentle touch for long-term patient retention.

  • Construction & Trades: Swift revenue recovery for the HVAC, electrical, and plumbing contractors that keep Orange County running.

  • K-12 Private & Charter Schools: Sensitive handling of unpaid enrollment fees, tailored for the local “school choice” environment.

  • Accountants & CPA Firms: We understand “Net-30” culture and ensure professional service fees are paid without damaging your client rapport.

  • Banks & Credit Unions: Handling delinquent loans and overdrawn accounts with a focus on high-risk portfolios.

  • Restoration, Pool & Contractors: Recovering funds for home improvement professionals who often face seasonal payment delays.

  • B2B Commercial, Waste Management & Restoration: Large-scale recovery for the industrial sectors near the Fullerton Municipal Airport.


The Red Flag Box: 3 Local Pitfalls

  1. DIY Burnout: Assigning collections to your staff. They weren’t hired for this, they hate doing it, and it pulls them away from core revenue-generating work.

  2. Delayed Action: The longer you wait, the lower the recovery rate. Early assignment to the Account Reconciliation Team is the single best predictor of success.

  3. Communication Gaps: Not utilizing modern tools. When permitted, we use email and text to meet debtors where they are, significantly speeding up the “will to pay.”


A Note from the Reconciliation Team

We view ourselves as an extension of your office. Because we record and randomly review all calls, we eliminate the risk of “rogue collectors” who might trigger a “review-bomb” on your social media. Our goal isn’t just to get the money; it’s to provide a seamless, professional experience that reflects your high standards.


Essential Compliance & Law Summary

We operate under the current Fair Debt Collection Practices Act (FDCPA) and California’s Rosenthal Act. These laws govern how and when we contact debtors, ensuring consumer protection while allowing us to pursue your funds vigorously. Our process includes:

  • Address Validation: Using USPS data to ensure notices reach the right hands.

  • Financial Scrubbing: Checking for active bankruptcies before proceeding.

  • Credit Reporting: Available upon request and where legally permitted to provide extra leverage.


Local FAQs

How does Fullerton’s specific economy affect my recovery?
Fullerton is a hub for education and medical services. These sectors rely heavily on reputation. Our “Velvet Hammer” style is designed specifically for these high-visibility industries where a single public complaint can cost more than the debt itself.

What if the debtor speaks Spanish?
We have on-board bilingual collectors ready to assist. In a diverse city like ours, being able to communicate clearly in a debtor’s primary language removes barriers to payment.

Can you handle debts from companies outside of North Orange County?
Yes. While we are local experts, our tools—like skip tracing and credit reporting—allow us to track and recover funds across state lines if necessary.

Secure Your Revenue – Contact Nexa Today

Filed Under: Debt Recovery

Collection Agency in Palm Bay, FL | Compliant & Effective

Palm Bay, FL Past-Due Accounts: Keep It Calm. Get It Closed.

Palm Bay runs on precision—Space Coast engineers, skilled trades, and service businesses moving fast between Malabar Road and I-95.

With Melbourne’s medical hub next door and Port Canaveral driving constant commerce, your invoices shouldn’t be the slowest thing in your operation. When accounts drag out, the real damage isn’t just money—it’s momentum, morale, and the awkward tension your staff carries home.

Nexa provides a reputation-safe approach, equipped with all 50-state collections license, offering free credit reporting, free litigious debtor check, free bankruptcy scrub, and zero onboarding fees. Secure – SOC 2 Type II & HIPAA compliant. Over 2,000 online reviews rate us 4.85 out of 5. 

Need a Collection Agency? Contact us

Straight Pricing (Pick Your Lane, Stay in Control)

You’ve got two clean options with our Account Reconciliation Team:

  • Fixed-fee: $15 (you keep 100% of what’s recovered)

  • Contingency: 40% (no recovery, no fee)

Early assignment changes everything. The sooner you hand off an account, the more likely it resolves with our most amicable strategies—before frustration hardens into refusal.

Money saver tip: Many clients effectively get the fixed-fee service “free” by treating it as a business expense at tax time after consulting their CPA.

Why Palm Bay Businesses Collect More by Staying Human

If you’ve ever watched a rocket countdown on the Space Coast, you know the truth: pressure without control creates a mess.

That’s the problem with arguing. It lights up the room, but it doesn’t always land the payment.

We recover more by working with the account holder—not against them—because people pay the party that makes payment feel doable.
Our style is diplomatic. Firm enough to secure action. Soft enough to protect your reputation.

That’s the Velvet Hammer: strong results, reputation-safe tone, and a clear path to closure.

We also run a Litigation Scrub early. It helps filter riskier situations so your business doesn’t waste time chasing accounts that are more likely to explode into conflict. This is one reason our recovery rates stay higher than industry average.

Fast Resolution Tools: Email, Text, and Bilingual Outreach

A lot of Palm Bay accounts don’t go “bad.” They go quiet.

So we use modern outreach when appropriate and permitted—email and text—because it reduces phone-tag and speeds up decisions.
We also have Spanish-speaking collectors on board, which matters across Brevard County. When language is clear, excuses fade faster.

Most importantly: your employees go back to what they were hired to do—run schedules, manage crews, care for patients, handle vendors.
Not chase payments. Not absorb uncomfortable conversations. Not become the unofficial collections department.

Recent Recovery Results

1) Medical Balance — Palm Bay

The situation: A medical office in Palm Bay had patient-balance accounts piling up after insurance processing. Some patients genuinely misunderstood their responsibility. Others just stopped responding. Front desk staff was stuck re-explaining the same thing repeatedly—while phones kept ringing.
What we did (2–3 steps):

  1. Completed account verification with USPS address checks and a bankruptcy screen before contact intensified.

  2. Delivered respectful outreach using approved channels, keeping the tone calm and the message consistent.

  3. Offered two resolution lanes: a short structured plan or a single payment option, with clear documentation so nobody felt cornered.
    Outcome: Accounts started closing without escalation. The office reclaimed time, reduced stress, and avoided reputation fallout.

2) Commercial Invoice — Melbourne

The situation: A B2B service provider in nearby Melbourne had an outstanding invoice that kept bouncing between “AP review,” “waiting approval,” and “next week.” The work was completed. The relationship mattered. But the balance was turning into an internal distraction.
What we did (2–3 steps):

  1. Consolidated proof and issued a formal notice through multiple channels to reach the actual decision-maker—not just the gatekeeper.

  2. Negotiated human-to-human with a calm, professional stance: confirm the timeline, remove the stall tactics, set a real deadline.

  3. Where permitted and if the client chose it, introduced credit reporting as a non-legal lever to encourage closure without court drama.
    Outcome: Payment resolved with reputational control intact. No public conflict. No burned relationship. Just a finished account.

Red Flag Box: 3 Palm Bay Collection Mistakes That Quietly Bleed Cash

  1. Waiting because “they’re local” — relationships don’t pay bills unless you guide them to action.

  2. Letting emotion into the script — one harsh call can trigger review-bombing or a public complaint that costs far more than the balance.

  3. Chasing the wrong person — if you never reach the actual decision-maker, you’re collecting “updates,” not money.

A Note from the Account Reconciliation Team

We don’t show up loud. We show up effective.
We verify first, communicate professionally, and keep the temperature low. When someone can pay, we make it easy to do the right thing. When someone is stalling, we tighten the structure until the account closes. That’s the Velvet Hammer: calm pressure, clean documentation, and outcomes you can count.

What We Handle Around Palm Bay (Tailored to Local Reality)

  • Healthcare & Medical: Recovery support for hospitals, clinics, and specialty practices with a reputation-safe approach

  • Colleges & Universities: Tuition balances, housing accounts, and administrative fees handled diplomatically

  • Dental: Dental practices and orthodontics—protect patient trust while resolving balances

  • Restoration / Pool / Contractors: Job invoices, change orders, and service agreements without referral-damage

  • K-12 Private & Charter Schools: Enrollment fees, textbooks, and family balances handled with sensitivity

  • Accountants & CPA Firms: Professional fee recovery that respects long-term client relationships

  • Banks & Credit Unions: Delinquent consumer accounts and deficiency balances handled with structured escalation

  • Construction & Trades: HVAC, electrical, and general contractors who can’t afford cash flow disruption

  • B2B Commercial: Vendor invoices, service contracts, and recurring billing across the Space Coast

  • Waste Management: Commercial service billing and route-based balances resolved with consistency

Rules That Matter (Practical, Not Legal Advice)

Florida has state rules for consumer collections and federal standards apply in many situations as well. We stay disciplined: no harassment, no threats, no sloppy third-party talk.

Our process includes USPS address verification, skip tracing, and bankruptcy checks to reduce wrong-party contact and wasted effort.
If you choose and it’s permitted, credit reporting can be used as a non-legal lever.
And for quality protection: calls are recorded and randomly reviewed to prevent rogue behavior and reduce “review-bomb” risk.

FAQs

Palm Bay question: People move often along the Space Coast—what if contact info is outdated?
That’s common here. We run USPS checks and skip tracing so your team isn’t stuck calling dead numbers and leaving voicemails into the void.

What if the account holder says they dispute the balance?
We don’t argue. We isolate the reason, validate the documentation, and offer a structured resolution path that keeps the relationship intact.

Will this damage our reputation online?
Not with Velvet Hammer discipline. Calm language, consistent process, and recorded quality reviews dramatically reduce the blowback that comes from emotional collection attempts.

Contact Nexa Today

Filed Under: Debt Recovery

Texas Medical Collection Agency | Local & HIPAA-Compliant Recovery

Texas healthcare moves fast—unpaid patient balances shouldn’t be allowed to slow it down. From major hospital systems and specialty practices in Houston and Dallas–Fort Worth to medical offices in Austin, dentists and orthodontists in San Antonio, and urgent care centers, ophthalmologists, surgery centers, imaging facilities, and senior living providers across the state, aging receivables can quietly turn into significant write-offs when follow-up comes too late.

Nexa brings Texas-specific medical collection experience to every account. We help healthcare providers recover self-pay balances, high-deductible patient responsibility, post-insurance balances, and older receivables through HIPAA-compliant communication, payment resolution, persistent follow-up, and appropriate escalation. Our approach is built around a simple goal: recover the revenue your organization earned while protecting the patient experience, your staff’s time, and the reputation you built in your community.

HIPAA-compliant medical debt recovery for Texas hospitals, doctors, dentists, urgent care and senior living providers

Not just Texas, Nexa provides a reputation-safe approach, equipped with all 50-state collections license, offering free credit reporting, free litigious debtor check, free bankruptcy scrub, and zero onboarding fees. Secure – SOC 2 Type II & HIPAA compliant. Over 2,000 online reviews rate us 4.85 out of 5. 

Need a TX Medical Collection Agency? Contact us


Precision Recovery: Our Simple Pricing

In the Current healthcare landscape, financial transparency is as vital as clinical precision. We’ve removed the complexity from our pricing, offering a performance-driven model tailored for high-volume Texas practices:

  • The $15 Fixed-Fee Acceleration: Perfect for early-stage accounts. Pay a one-time fee of fifteen dollars, we handle the professional mediation, and you keep 100% of the recovered funds.

  • The Contingency Resolution: For older or complex balances, our rate is fixed at 40%. Our rule is absolute: No recovery, no fee.

Involving a professional agency significantly improves your recovery rate; data confirms that the earlier you assign a file, the better the recovery results delivered. We utilize Current communication streams, including email and SMS text where possible, to engage patients with speed. This partnership allows your medical staff to focus on the core clinical work they were hired for, rather than making them do collections—a task that kills staff morale and pulls them away from patient care.

Get Started with $15 Fixed-Fee


Truly Medical Healthcare Experts

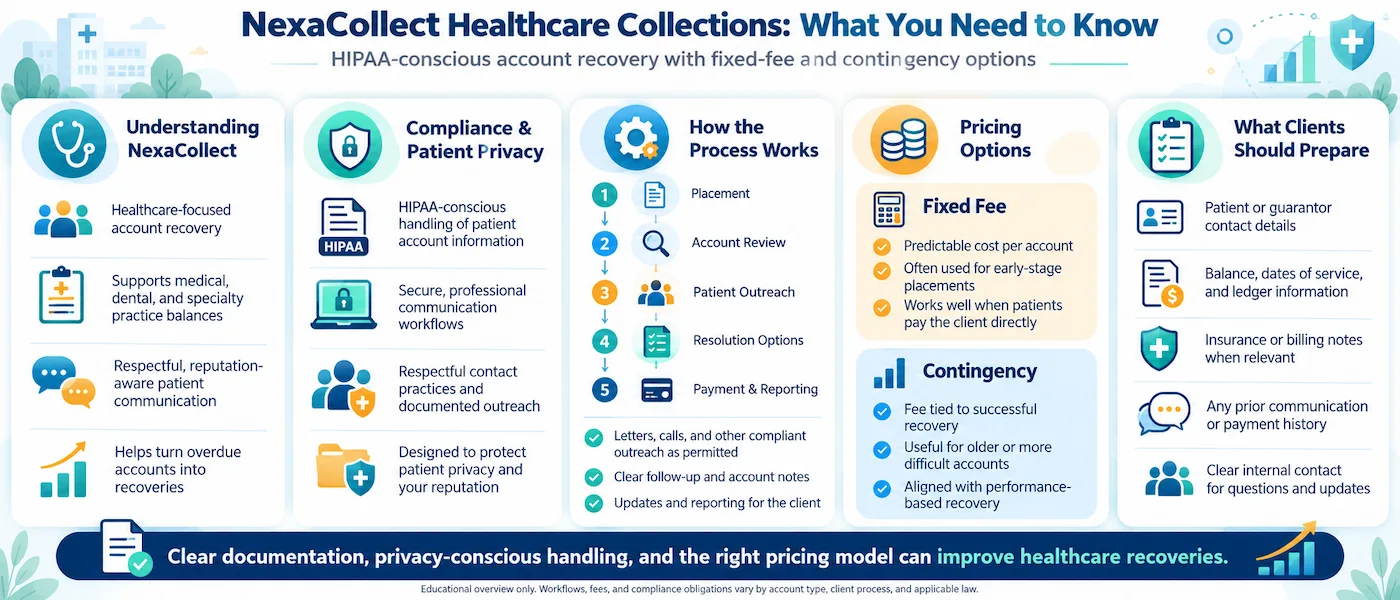
HIPAA-conscious patient account recovery, the collection process, fixed-fee and contingency pricing options, and information healthcare providers should prepare.

We aren’t a generalist agency; we are specialized practitioners in healthcare revenue restoration.

  • Dedicated Focus: Over 50% of our portfolio is comprised exclusively of medical, dental, senior living, and hospital clients.

  • Proven Scale: This specialization represents over a thousand satisfied medical clients nationwide.

  • Unmatched Reputation: Our approach has earned us a 4.85 Google rating from over 2,000 reviews, proving that you can be firm about your money without being a villain to your patients.

Why Cooperative Mediation Recovers More

We recover more by working with the debtor, rather than arguing against them. In the Texas medical community, your reputation is your most valuable asset. Conflict triggers avoidance; diplomacy triggers resolution. Our “Velvet Hammer” approach is firm enough to secure payment but respectful and soft enough to protect your 5-star online reputation. By resolving the friction, we ensure the patient has the will to pay you first than others.

To protect you from unnecessary risk, every file undergoes a rigorous litigation scrub. This identifies “professional plaintiffs” who intentionally bait businesses into technical errors to trigger lawsuits. Combined with USPS address checks, skip tracing, and bankruptcy scrubs, we ensure you aren’t attempting to collect from riskier people who could put your business at legal or reputational peril.


Texas Medical Debt Laws: A Practitioner’s Guide

Navigating the legal landscape in Texas requires a deep understanding of state-specific mandates:

  • The Itemized Bill Mandate (Texas Health & Safety Code Chapter 185): Healthcare providers must provide an itemized bill in plain language before pursuing debt collection. We ensure all pre-collection requirements are met.

  • Timely Billing Law (Texas Civil Practice & Remedies Code Chapter 146): Providers must bill patients by the first day of the 11th month after services are provided, or they may lose the right to collect.

  • The 4-Year Statute of Limitations: In Texas, the legal window to file a lawsuit for a medical debt is generally four years from the date the cause of action accrues.

  • Credit Reporting Update: As of July 2025, a Texas federal court vacated the CFPB’s rule that would have banned medical debt from credit reports. This means credit reporting remains a Current and effective leverage tool for Texas providers.


Recent Recovery Results: Lone Star Cases

Case 1: Specialized Surgical Center Reconciliation (DFW)

A surgical facility near the North Dallas Parkway was carrying $18,200 in aging patient responsibilities.

  1. Skip-Trace: We located several patients who had relocated within the DFW Metroplex following their procedures.

  2. Mediation: Our concierges reached out with a “billing audit” tone, identifying insurance gaps patients didn’t know how to resolve.

  3. Result: Recovered $14,500 in 38 days without a single negative review.

Case 2: Commercial Medical Logistics Dispute (Austin)

A medical device distributor was owed $22,400 by a laboratory facility near the Austin Biotech corridor.

  1. Litigation Scrub: Confirmed the lab was solvent but prioritizing national vendors over local support.

  2. Pressure: Used the “Velvet Hammer” to reach the ownership group directly to discuss professional reconciliation.

  3. Result: Full wire transfer received within 14 days of our initial intervention.

Recovery Snapshots

  • The “Slow-Pay” Dentist: A family practice in San Antonio recovered $7,200 in overdue orthodontics payments after we established a 3-part payment plan that the patient fulfilled Current.

  • The Facility Restoration Dispute: A contractor serving a clinic in Sugar Land recovered $9,800 after we mediated a “quality of service” stall that was actually a simple cash-flow delay.


A Note from the Reconciliation Team

“We view ourselves as the ‘Reputation Guards’ for your accounting department. In Texas, where today’s delinquent debtor might be tomorrow’s fellow patron at a local restaurant or a neighbor you see in the Hill Country, a heavy-handed collector is a strategic liability. We act as a firm but empathetic extension of your office. We handle the friction of the ‘past due’ notice so you can maintain the friendship of the long-term patient.”

Frequently Asked Questions

What Texas laws must a medical collection agency follow?

A Texas medical collection agency must comply with applicable federal requirements, including the FDCPA and HIPAA, as well as the Texas Debt Collection Act under Chapter 392 of the Texas Finance Code. Texas also requires third-party debt collectors to maintain a $10,000 surety bond filed with the Secretary of State before engaging in debt collection.

Can a Texas healthcare provider send a patient to collections without providing an itemized bill?

Generally, no. Texas Health and Safety Code Chapter 185 requires healthcare providers requesting payment from patients to provide an itemized bill, and a provider may not pursue debt collection against the patient unless it has complied with the itemized-billing requirements.

How long does a healthcare provider have to bill a patient in Texas?

Texas has a timely-billing requirement under Chapter 146 of the Civil Practice and Remedies Code. In many cases, a healthcare provider must bill the patient or other responsible party no later than the first day of the 11th month after the date the healthcare service was provided, subject to the statute’s specific rules and exceptions.

Is it HIPAA-compliant for a Texas medical practice to use a collection agency?

Yes. HIPAA permits healthcare providers to use collection agencies because collecting payment is considered a permitted payment activity. When protected health information is involved, the collection agency generally operates as a business associate and must comply with applicable HIPAA safeguards and minimum-necessary requirements.

When should a Texas medical practice send unpaid patient balances to a collection agency?

Providers generally achieve better results when delinquent accounts are addressed before they become severely aged. Before placement, the practice should verify the balance, insurance adjudication, patient responsibility, required billing notices and Texas itemized-bill requirements. Nexa offers both a $15 fixed-fee early-stage collection option and a 40% contingency service for older or more difficult accounts.

Can a Texas medical collection agency recover high-deductible and post-insurance patient balances?

Yes. Once insurance has processed the claim and the remaining patient responsibility is properly documented, eligible deductibles, coinsurance, copays and other patient-responsibility balances may be placed for collection. The provider should first ensure that applicable Texas billing requirements, itemized-bill requirements, contractual obligations and federal protections have been satisfied.

Specialized Support for Texas Medical Entities

Our outreach is specifically calibrated for the unique regulatory and cultural landscape of Texas healthcare:

  • Hospital Systems & LTACHs: Managing complex uncompensated care and high-balance accounts for tax-exempt and for-profit systems near the Dallas Medical District.
  • Senior Living & Post-Acute Care: Specialized recovery for Skilled Nursing Facilities (SNFs), Assisted Living (ALFs), and CCRCs. We navigate the sensitivities of family-responsible billing with the “Velvet Hammer” touch.
  • Physician Groups & Specialists: 100% HIPAA-compliant recovery for orthopedic, OBGYN, and internal medicine groups operating in high-growth corridors like Austin’s biotech belt.
  • Ambulatory Surgery Centers (ASCs) & Urgent Care: Revenue restoration for fast-paced outpatient centers where patient churn is high and rapid follow-up is essential.
  • Dental & Orthodontics: Maintaining the long-term patient-provider bond while resolving balances for multi-phase treatment plans and elective procedures.
  • Ancillary Services (Labs & Pharmacies): Professional mediation for clinical laboratories and specialty pharmacies fueling the San Antonio healthcare hub.
  • Chiropractic & Physical Therapy: Ensuring your practice gets paid for high-touch, recurring wellness services without bruising local rapport.

Need a Medical Collection Agency? Contact us

Filed Under: Debt Recovery

Federal Government Shutdown: Impact on Collections

A U.S. federal shutdown doesn’t hit every portfolio the same way. The impact depends on who owes the money, who your clients are, and how much your recovery model relies on courts or government-run services. Below is a comprehensive view of likely scenarios—beyond what was shown in the slides—plus sector examples.

1) Consumer ability to pay

  • Furlough ripple: Federal employees, contractors, and vendors face delayed income → more accounts roll from 30→60→90 DPD, but with lower near-term liquidation.

  • Household triage: Debtors prioritize essentials (rent, utilities, groceries) over elective medical, tuition balances, memberships, etc. Promise-to-pay breakage rises.

  • Hardship/forbearance requests: Expect more requests for payment plans, lower down payments, and settlements.

  • Tax-refund timing risk: If IRS operations slow, refund-funded lump-sum settlements may slip.

2) Litigation and judgment recovery

  • Federal courts: Civil matters can slow or be de-prioritized (criminal takes precedence). New filings, hearings, and garnishment orders tied to federal debts can be delayed.

  • State courts: Usually open, but some dockets move slower if they rely on federal interfaces (e.g., service members’ status checks, certain bankruptcy interactions).

  • Post-judgment remedies: Garnishments of federal wages/benefits are more complex; any agency processing step that needs federal staff may lag.

3) Identity, employment, and data verification

  • E-Verify/contractor status checks: Often limited or paused, making employer verification harder for skip-tracing and right-party contact strategies on employment-based repayment plans.

  • Public records access: Some federal data portals slow; state/county records mostly normal.

  • Credit reporting: Bureaus operate normally; however, consumer disputes may spike as people manage credit during income gaps.

4) Payment rails and mail

  • ACH/credit card networks: Operate as normal (they’re private), but debtor funding is constrained.

  • USPS: Stays operational; mail turn-times remain, but volume changes can affect response windows.

5) Client operations and cash flow

  • Federal-funded clients: Hospitals, universities, labs, housing authorities, defense vendors may delay outsourcing or pause placements; some slow remittances.

  • Private-sector clients in federal towns: Local businesses around bases, parks, or federal campuses see sales drops → more delinquencies.

  • Contingency-fee agencies: Liquidation rates dip near term; placement volumes may rise. Lag effect hits commission revenue 30–90+ days out.

  • Fixed-fee/early-stage services: Demand can increase as creditors try low-cost steps before escalation.

6) Regulatory and compliance posture

  • CFPB/FTC oversight: Typically continues (not appropriated through annual budget the same way), so FDCPA/Reg F compliance remains critical—no “free passes.”

  • Servicemembers & protected classes: Heightened sensitivity; ensure SCRA checks, hardship scripting, and no UDAAP risk in messaging.

7) Bankruptcy dynamics

  • Consumer Chapter 7/13 filings: Can tick up if shutdown is prolonged; trustee operations may be slower in some districts.

  • Adversary proceedings/timelines: Calendars may move, impacting claim resolution timing.

8) Portfolio valuation & strategy

  • Vintage performance: Federal-exposed zip codes or SIC/NIC clusters may underperform; re-underwrite models, adjust forward flow pricing, and suit-rate assumptions.

  • Scoring/segmentation: Add a “shutdown sensitivity” flag (federal employee density, contractor NAICS, proximity to federal facilities).


Sectors where shutdowns hit collections (with examples)

  1. Healthcare (outpatient, labs, imaging, elective care)

    • Exposure: Patients who are federal employees/contractors delay co-pays and deductibles; Medicare/Medicaid claim timing risk if prolonged.

    • Impact: Slower self-pay; higher payment-plan demand.

  2. Higher Education & Training

    • Exposure: Federal aid/grant timing; students from furloughed households.

    • Impact: Tuition/fee delinquencies rise; payment plan extensions; slower placements from bursar offices.

  3. Defense & Federal Contractors (manufacturing, IT, staffing)

    • Exposure: Paused contracts, delayed invoices, stop-work orders.

    • Impact: B2B receivables stretch, disputes over milestone acceptances; placements increase but recovery depends on contract restarts.

  4. Housing & Property Management (incl. Section 8/affordable)

    • Exposure: HAP/assistance timing risk, tenants with furloughed income.

    • Impact: Rent arrears increase; evictions tied to federal programs may be slower; need careful compliance.

  5. Utilities & Telecom

    • Exposure: Federal communities manage cash by paying minimums or skipping cycles.

    • Impact: DPD buckets swell; more high-risk promises; stricter—but compliant—outreach cadence pays off.

  6. Transportation & Travel (airports, TSA/FAA-adjacent), Hospitality near parks/bases

    • Exposure: Demand shock from travel constraints and park closures.

    • Impact: Merchant chargebacks, unpaid invoices for group bookings; local SMBs’ B2B delinquencies rise.

  7. Childcare, Fitness, and Membership-based Services

    • Exposure: Families trim “discretionary” spend first.

    • Impact: Membership dues lapse, PT packages/unutilized services go unpaid; early-stage reminders work best.

  8. Public-sector Adjacent Nonprofits & Research Labs (grant-funded)

    • Exposure: NIH/NSF grant timing, drawdowns delayed.

    • Impact: AP crunch → vendor bills slow; contingent recoveries depend on grant resumption.

  9. Mortgage/Auto Finance & Servicing

    • Exposure: FHA/VA pipeline disruptions; income verification delays for loss-mit options.

    • Impact: More extensions/forbearance; repos/judicial timelines may stretch in some venues.


What collections teams should do now

  • Segmentation: Flag accounts by federal exposure (ZIPs, NAICS, employer keywords); route to hardship-savvy reps.

  • Messaging & offers: Deploy temporary, compliant hardship language, smaller down payments, and graduated payment plans; keep settlement authority tight but flexible.

  • Cadence tuning: Shift effort from suit-driven to phone/letter/SMS-driven strategies where courts slow.

  • Right-party contact (RPC): Verify contact points; when employment verification is constrained, lean on consented digital channels and alternate references (compliantly).

  • Client comms: Send a one-pager explaining likely timelines, performance expectations, and what documentation you need to move quickly when government reopens.

  • Cash-flow planning: For contingency shops, reforecast liquidation curves and tighten remittance cycles; for fixed-fee programs, consider volume-tier pricing to help clients start earlier.

  • Compliance refresh: Re-train on Reg F call attempts/7-in-7, model scripts for hardship, SCRA checks, and UDAAP risk—regulators still watch.

Filed Under: Debt Recovery

  • « Go to Previous Page
  • Page 1
  • Interim pages omitted …
  • Page 4
  • Page 5
  • Page 6
  • Page 7
  • Page 8
  • Interim pages omitted …
  • Page 55
  • Go to Next Page »

Primary Sidebar


accounts receivable

Need a Collection Agency?
Kindly fill this form.
We’ll get in touch with you

    Please prove you are human by selecting the truck.

    Compliance & Security

    • SOC 2 Type II Certified: Third-party audited data security and strict privacy controls.

    • HIPAA Compliant: Secure, legal processing of medical and municipal EMS accounts.

    • PCI-DSS Level 1: Highest tier of data encryption for secure payment processing.

    • FDCPA & FCRA Aligned: Full legal adherence to federal consumer protection laws.

    Recent Posts

    • Why Dental Patients Dispute Bills: The Nexa Collections Dental Account Dispute Index
    • 2027 Commercial Collections Benchmark: U.S. Late Payments, AR Risk and B2B Collection Trends
    • Bulk Account Placement: What a Collection Agency Actually Needs From You
    • Nationwide Debt Collection Agency Serving U.S. Cities
    • Chula Vista Collection Agency for Medical, B2B, Schools & Business Debt
    • Corpus Christi Collection Agency: Itemized Bill Rules for Practices
    • Riverside Collection Agency | For Logistics, Medical, Schools & Business Recovery
    • Collection Agency for Large Balances: High-Value B2B Debt Recovery

    Featured Posts

    • Short-Staffed and Drowning in AR? Here’s the Real Problem
    • Closing the Final Ledger: An Explainer on Compassionate Deceased Debt Recovery
    • Riverside Collection Agency | For Logistics, Medical, Schools & Business Recovery

    Copyright © 2026 NEXACOLLECT.COM | This content is provided for general informational purposes only and should not be considered legal advice. Collection laws and requirements may vary by state, account type, documentation, debtor status, and specific facts. Please consult qualified legal counsel for guidance regarding your particular situation. Nexa and its authorized collection partners service accounts in accordance with applicable federal and state collection requirements. Visit our home page to know more about us.

    X
    Need a Collection Agency?
    Contact Us