• Skip to main content
  • Skip to primary sidebar

Nexa Collections

  • Home
  • Serving
    • Medical
    • Dental
    • Small Business
    • Large Business
    • Commercial Collections
    • Government
    • Utilities
    • Fitness Clubs
    • Schools
    • Senior Care Facility
  • Contact Us
    • About us
    • Cost

Debt Recovery

Data Privacy and Data Security for Collection Agencies

Data Privacy in Collections
Collection Agencies often deal with sensitive personal and financial information, understanding and implementing Data Privacy and Data Security is crucial. Here’s how these concepts are perceived and managed in a collection agency context:

  1. Data Privacy in a Collection Agency:
    • Definition and Focus: Data Privacy for a collection agency involves handling personal information of debtors in a manner that respects their privacy rights. This includes information like names, contact details, financial data, and debt-related information.
    • Regulatory Compliance: Collection agencies must comply with specific laws like the Fair Debt Collection Practices Act (FDCPA) in the U.S., which sets standards for the collection of debts and provides guidelines on how debtor information can be used and disclosed.
    • Examples:
      • Ensuring that debtor information is not disclosed to unauthorized third parties, like friends or family, without the debtor’s consent.
      • Obtaining consent from debtors before using their personal information for purposes other than debt collection, such as for marketing other services.
      • Providing debtors with the option to opt out of certain forms of communication or data usage.
      •  Sharing only the minimum necessary health information for a specific purpose. Not disclosing actual treatments received by patients, they should only be referred as procedures or doctor visits.
  2. Data Security in a Collection Agency:
    • Definition and Focus: Data Security in a collection agency involves protecting debtor data from unauthorized access, cyber-attacks, and data breaches. This is essential not only for protecting the privacy of debtors but also for maintaining the trustworthiness and integrity of the agency.
    • Technical Measures: Implementing robust cybersecurity measures such as encryption of data, secure data storage solutions, strong access controls, and regular security audits.
    • Examples:
      • Using encrypted communication channels when discussing debt information with debtors or reporting to credit bureaus.
      • Regularly updating IT systems and training staff to recognize and prevent potential cyber threats like phishing attacks.
      • Implementing strict access controls so that only authorized personnel can access sensitive debtor information.

For a collection agency, maintaining high standards of Data Privacy and Data Security is not just about legal compliance, but also about building trust with clients and debtors. Mishandling of data can lead to legal repercussions and damage to reputation, while strong privacy and security practices can enhance reliability and professionalism in the eyes of both clients and debtors.

Most common Data Compliance,  Data Security Laws and Ethical laws that Collection Agencies must follow

Here is a list of some of the key federal laws they are typically required to follow:

  1. Fair Debt Collection Practices Act (FDCPA): This is the primary federal law that governs debt collection practices in the U.S. It prohibits debt collectors from using abusive, unfair, or deceptive practices to collect debts and sets guidelines on how and when they can contact debtors.
  2. Telephone Consumer Protection Act (TCPA): This act restricts telemarketing calls and the use of automated telephone equipment. It also limits the use of pre-recorded voice messages, SMS text messages, and faxes.
  3. Fair Credit Reporting Act (FCRA): FCRA regulates the collection, dissemination, and use of consumer information, including credit information. Collection agencies must ensure that the information they report to credit bureaus is accurate and must follow certain procedures when consumers dispute that information.
  4. Gramm-Leach-Bliley Act (GLBA): Also known as the Financial Services Modernization Act, GLBA requires financial institutions, which can include debt collectors, to explain their information-sharing practices to their customers and to safeguard sensitive data.
  5. Health Insurance Portability and Accountability Act (HIPAA): When collection agencies deal with medical debts, they must comply with HIPAA, which includes provisions for protecting the privacy and security of health information.
  6. Bankruptcy Code: The U.S. Bankruptcy Code impacts debt collection, as it may restrict collection efforts against consumers who have filed for bankruptcy protection.
  7. Uniform Commercial Code (UCC): The UCC, particularly Article 9, deals with secured transactions and can impact the collection of secured debts.
  8. Consumer Financial Protection Act (CFPA): Under the Dodd-Frank Wall Street Reform and Consumer Protection Act, the CFPA established the Consumer Financial Protection Bureau (CFPB), which can regulate debt collectors and enforce certain consumer protection laws.

Additionally, collection agencies must be aware of and comply with state-specific laws and regulations, which can vary significantly and may impose additional requirements or restrictions on their operations. These laws can include licensing requirements, statutes of limitations on debts, and additional consumer protections.
Filed Under: Debt Recovery

Identifying and Mitigating B2B Client Default Risks

Client Default management

In the B2B world, client defaults on accounts receivable can create significant financial disturbances. Recognizing early warning signs and taking proactive steps to mitigate these risks can help maintain your business’s financial health. Let’s delve deeper into each sign, provide examples, and explore effective preemptive measures.

1. Delayed Payments

A pattern of late payments or increasingly delayed responses to payment reminders can be a red flag.

  • Examples:
    1. A client who used to pay within 30 days now regularly takes 60 days or more.
    2. Sudden requests for extended payment terms without a prior history of such requests.
  • Preemptive Measures: Implement more stringent payment terms, consider incentives for early payments, and enforce late payment penalties.

2. Poor Communication

  • Examples:
    1. A previously responsive client ignores payment reminders or invoices.
    2. Abrupt stop in regular communication or updates regarding business activities.
  • Preemptive Measures: Enhance your follow-up process with scheduled calls. Establish alternative communication channels, like direct meetings, to discuss payment matters.

3. Financial Hardship

Be aware of any public information or rumors about the customer’s financial struggles, such as layoffs, legal issues, or a drop in business.

  • Examples:
    1. Public announcements of the client’s budget cuts or significant financial losses.
    2. News reports of the client’s major clients or partners going bankrupt.
  • Preemptive Measures: Regularly review clients’ financial statements and public information. Adjust your exposure to clients based on their financial stability.

4. Partial Payments

  • Examples:
    1. A client starts consistently paying only a fraction of the invoice amount.
    2. Regular requests to pay in installments for previously full-paid invoices.
  • Preemptive Measures: Discuss and agree on a structured payment plan. Consider reducing future credit limits or requiring advance payments.

5. Changes in Order Patterns

  • Examples:
    1. A noticeable reduction in the volume or frequency of orders without a seasonal trend.
    2. Shifts in ordering patterns, like opting for cheaper alternatives or smaller quantities.
  • Preemptive Measures: Conduct regular reviews and discussions with the client about their changing needs. Adjust your offerings to better align with their current situation.

6. Excuses and Deflections

  • Examples:
    1. Consistent excuses related to internal approval processes or accounting issues.
    2. Blaming external factors like market conditions or vendor issues for delayed payments.
  • Preemptive Measures: Establish clear, firm, and non-negotiable payment terms. Communicate the consequences of late payments.

7. Disputed Invoices

  • Examples:
    1. Sudden disputes over previously agreed prices or services.
    2. Frequent, unjustified complaints about the quality of goods or services to delay payments.
  • Preemptive Measures: Ensure clarity and precision in your invoicing process. Consider implementing digital invoicing systems to reduce errors.

8. Negative Credit Reports

  • Examples:
    1. Credit reports showing an increase in the client’s debt levels or defaults.
    2. Deterioration in the client’s credit score over consecutive reports.
  • Preemptive Measures: Conduct periodic credit checks. Adjust your business dealings based on the client’s current creditworthiness.

9. Changes in Banking Relationships

  • Examples:
    1. Frequent changes in the client’s bank accounts or reported issues with their banking partners.
    2. Unexplained delays related to changing banking details.
  • Preemptive Measures: Maintain a close watch on such changes. Offer a variety of secure payment methods while being alert for possible fraud.

10. Industry Downturn

  • Examples:
    1. General decline in the client’s industry, leading to widespread business closures or cutbacks.
    2. Reports of major players in the client’s industry facing financial difficulties.
  • Preemptive Measures: Stay informed about industry trends and adjust your exposure accordingly. Diversify your client base to mitigate industry-specific risks.

11. Frequent Management Changes

  • Examples:
    1. Rapid turnover in the client’s executive team or financial department.
    2. Sudden departure of long-term key personnel without clear reasons.
  • Preemptive Measures: Regularly update your contacts and relationships within the client company. Stay informed about strategic changes that may affect their payment behavior.

12. Overreliance on a Few Clients

  • Examples:
    1. More than 40% of your revenue comes from a single client or a small group.
    2. A significant portion of your business is tied to clients in the same industry.
  • Preemptive Measures: Actively seek to diversify your client portfolio. Develop strategies to attract clients from various industries and regions.

13. Unusual Requests

  • Examples:
    1. Requests for significantly altered product or service specifications without clear justification.
    2. Sudden demands for unusual or risky payment terms, like extended credit periods.
  • Preemptive Measures: Thoroughly assess and discuss any atypical requests. Ensure they are in line with your business’s risk tolerance and capabilities.

When to Send an Account to a Collection Agency

Deciding when to send an account to a collection agency depends on several factors:

  1. Age of the Debt: Typically, the older a debt, the harder it is to collect. Many businesses turn to collection agencies when an account is 90-120 days past due.
  2. Internal Efforts and Results: If your internal efforts to collect the debt (such as reminders, follow-ups, and negotiations) have been unsuccessful over a reasonable period, it might be time to involve a collection agency.
  3. Size of the Debt: Consider the size of the debt. If the amount is substantial enough to impact your cash flow or financial stability, it may warrant quicker action.

Ask Tactful Questions

When dealing with a client who may be experiencing financial difficulties but is reluctant to disclose them, it’s important to ask questions that are tactful, understanding, and insightful.

  • “How can we work together to navigate any challenges that may arise?”
  • “How have recent industry trends impacted your business?”
  • “Are there any budgetary constraints we should be aware of to serve you better?”
  • “Do you find our current payment terms comfortable, or is there a different schedule that would work better for you?”
  • “What are your business’s priorities and plans for the upcoming months?”
  • “Are there any upcoming projects or changes that might affect our ongoing partnership?”
  • “How satisfied are you with the value and results our services/products have brought to your business?”
  • “What can we do to strengthen our partnership and ensure mutual success?”

Remember, the key is to approach the conversation with empathy and a genuine willingness to understand and accommodate your client’s needs. This approach not only helps in gathering valuable information but also strengthens the client relationship.

Conclusion

Vigilance and proactive management are key to navigating the complexities of B2B relationships. By recognizing these warning signs and implementing effective preemptive strategies, you can protect your business from the impact of client defaults on accounts receivable. Regular client reviews, open communication, and flexible yet firm policies are essential in maintaining a healthy and stable financial environment.

Filed Under: Debt Recovery

How the Legal Collection Process Actually Works, Step by Step

Most creditors picture legal escalation as a single event, “we sued them.” In practice it’s a multi-stage process with several off-ramps along the way, most accounts that enter legal review still resolve without ever reaching a courtroom. Knowing where those off-ramps are changes what a creditor should actually expect once an account moves past standard collections. 

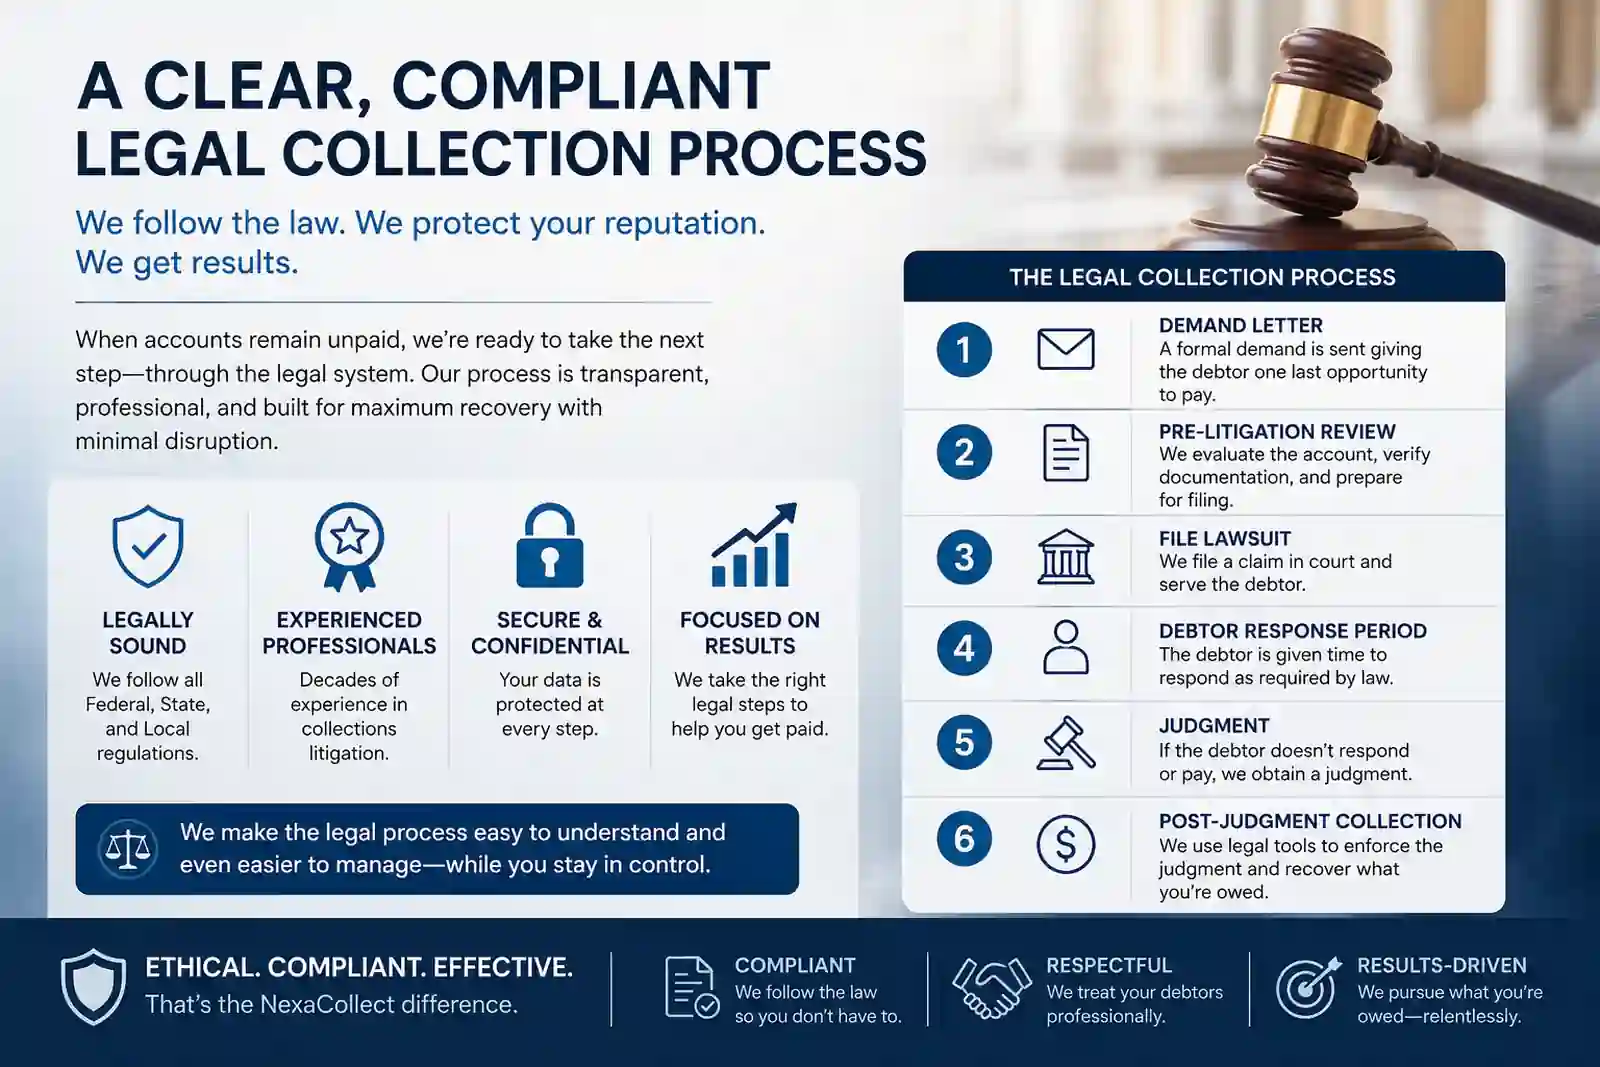
Quick answer: Legal collections operate on a contingency basis with the fee disclosed upfront, and an account only enters this track after standard collection efforts fail and the client gives written consent. The process runs through a Pre-Litigation demand, documentation verification, attorney assignment in the correct jurisdiction, and, only with further client consent, an actual lawsuit. Most cases resolve through settlement before trial; where a lawsuit does proceed, outcomes are typically a default judgment (debtor doesn’t respond) or a standard judgment, followed by enforcement tools like wage garnishment or asset liens, both of which vary significantly by state.


Legal collections process — how a collection agency escalates an unpaid account to an attorney network for lawsuit and judgment

Nexa provides a reputation-safe approach, equipped with all 50-state collections license, offering free credit reporting, free litigious debtor check, free bankruptcy scrub, and zero onboarding fees. Secure – SOC 2 Type II & HIPAA compliant. Over 2,000 online reviews rate us 4.85 out of 5. 

Need help with an account that needs legal escalation? Contact us


Before Anything Legal Happens: Three Ground Rules

  • Legal collections run on contingency, and the fee is disclosed before anything starts. There’s no separate legal add-on fee sprung on a client mid-process.
  • Legal escalation only happens after standard collection has failed. An account doesn’t skip straight to attorneys, it moves there only once internal collection efforts have been exhausted.
  • Written client consent is required before proceeding. Nothing legal happens on an account without the client’s explicit, documented go-ahead, and some clients choose to prohibit legal escalation entirely, that choice is respected.

Stage 1: Pre-Litigation Review

When an account transfers to the legal collections track, it first enters what’s called the Pre-Litigation phase. The agency’s in-house legal team reviews the account and issues a firm demand notifying the debtor that the account is now under legal review. This is genuinely the debtor’s last opportunity to resolve the balance before formal legal steps begin, and a meaningful share of accounts do settle right here, once a debtor sees “legal review” in writing, it changes the calculation.

Stage 2: Documentation Verification

If the debtor doesn’t resolve the account during Pre-Litigation, the next step is verifying that backup documentation actually supports the balance being claimed. This typically involves several rounds of communication with the client, updates on the account’s status, and requests for any additional supporting documents (the original contract, invoices, correspondence) that will matter if the case proceeds to a courtroom. A case is only as strong as its paper trail, this stage exists to make sure that trail is solid before anyone spends money filing suit.

Stage 3: Attorney Assignment

Once documentation is in order, the account is assigned to an attorney. Collection agencies typically maintain networks of hundreds of affiliated attorneys nationwide, and the case goes specifically to one licensed in the jurisdiction where it needs to be handled, jurisdiction matters here, an attorney licensed in the wrong state can’t file the case.

Stage 4: Attorney Contact and the Pre-Suit Window

What happens next depends on whether the attorney can negotiate a settlement or determines a lawsuit is the better path. Reaching the debtor remains the hardest part of this stage, and there’s no fixed universal timeline. Attorneys generally extend the debtor a courtesy window to respond following initial contact, this is a professional practice, not a court-imposed deadline, and it’s separate entirely from the formal answer period a debtor gets after a lawsuit is actually filed (which is set by state law, commonly somewhere in the 14-to-30-day range depending on jurisdiction, not a fixed number across every state).

Stage 5: Assessing Whether a Lawsuit Is Actually Worth Filing

If the attorney determines the case is viable for a lawsuit, based on the likelihood of winning a judgment and whether the debtor actually has assets or income worth pursuing, they’ll consult the client before proceeding. The client is typically asked to cover the court’s filing fee, which is reimbursed from the first funds recovered. This viability check matters: a technically winnable case against a debtor with nothing to collect from isn’t worth filing, and a good attorney network says so before spending the client’s money.

Stage 6: The Lawsuit Itself

Moving to an actual lawsuit requires the client’s consent. The process involves serving the debtor, preparing an affidavit, and waiting for a court date, and it can run long, court processing times have been notably slower since the pandemic in many jurisdictions. Two typical outcomes: a default judgment if the debtor doesn’t show up to respond, or a standard judgment if they do appear and the case is heard on its merits. With solid documentation in hand (which is exactly what Stage 2 was for), the odds of a favorable outcome are generally strong.

Stage 7: Judgment, Settlement, or Enforcement

Even after judgment, the story isn’t always over. Depending on whether the debtor is willing to settle, there may be an additional court hearing. If the debtor agrees to payment terms, the case moves to monitoring for payment. If they refuse to pay voluntarily, the attorney may pursue wage garnishment or asset liens, though which of these tools is actually available depends heavily on the state; several states restrict or outright prohibit wage garnishment for ordinary consumer debt. See our guide to collecting on a judgment for a full breakdown of enforcement options, judgment expiration and renewal, and what “judgment-proof” actually means for a debtor with no currently collectable assets.

Once funds are recovered, the amount is remitted to the client after deducting the agreed legal-contingency fee, disclosed to the client from the very start of the process, per the ground rules above. See the full pricing structure for how legal-contingency rates compare to standard collection fees.


Frequently Asked Questions

Does transferring an account to legal collections mean it will definitely go to court?

No. Legal escalation opens the door to a lawsuit, it doesn’t guarantee one. A meaningful share of accounts resolve during the Pre-Litigation demand stage alone, once a debtor receives formal notice that legal review has begun, and among cases that do proceed further, many settle through attorney negotiation before ever reaching a courtroom.

How long does a debtor actually have to respond once contacted by the attorney?

There are two different timeframes here, worth not confusing. Before any lawsuit is filed, the attorney generally extends a courtesy response window as a matter of professional practice, not a fixed legal deadline. Once a lawsuit is actually filed and the debtor is formally served, a separate, state-mandated answer deadline applies, typically somewhere between 14 and 30 days depending on the jurisdiction, and missing it can result in a default judgment.

Who pays the court filing fee, and is it refundable?

The client is typically asked to cover the court’s filing fee before a lawsuit proceeds. That fee is reimbursed from the first funds recovered on the account, so it isn’t a permanent out-of-pocket cost if the case succeeds, though it is a real upfront expense the client should budget for regardless of outcome.

Can a client stop an account from going to legal collections at all?

Yes. Written client consent is required before an account moves into the legal track in the first place, and some clients choose to prohibit legal escalation entirely as a matter of policy. Nothing legal happens on an account without that explicit, documented authorization.

What’s the difference between a default judgment and a standard judgment?

A default judgment is entered when the debtor fails to respond or appear after being properly served, the court rules in the creditor’s favor without the case being contested on its merits. A standard judgment results when the debtor does appear and the case proceeds to be heard, evaluated on the evidence and arguments both sides present. Both are enforceable judgments, but a default judgment can sometimes be reopened if the debtor later shows a valid reason for not responding, which a contested standard judgment generally cannot.

Once a judgment is obtained, is collecting on it automatic?

No, and this is one of the most commonly misunderstood parts of the process. A judgment is a legal ruling establishing the debt is owed, it doesn’t compel immediate payment on its own. Enforcement tools like wage garnishment and asset liens still have to be pursued separately, and their availability varies significantly by state, some states broadly restrict wage garnishment for consumer debt, for instance. Our guide to judgment collection covers this stage in full detail.

When should a creditor transition an account from standard collections to legal action?

Transitioning an account to legal action is typically recommended when a debtor has demonstrated the capacity to pay but refuses to cooperate, when standard agency skip-tracing and commercial mediation have stalled, or when the debt is approaching the state statute of limitations. Legal forwarding should be weighed against the size of the balance and the likelihood of asset recovery post-judgment.

Who covers court costs and legal fees when filing a debt collection lawsuit?

Upfront court costs (such as filing fees, process server costs, and local attorney court appearances) are typically coordinated with the creditor prior to filing, or handled through specialized legal forwarding arrangements. In many commercial contracts containing attorney-fee provisions, or depending on state statutes, legal fees and court costs can be formally added to the total judgment amount demanded from the debtor.

Does winning a debt collection lawsuit guarantee immediate payment?

Not automatically. Securing a legal judgment establishes a formal court-ordered debt, but enforcement steps are often required to collect funds. Depending on state laws, post-judgment enforcement remedies include bank-account attachments, corporate or personal asset liens, debtor examinations, and wage garnishments (where legally permitted for commercial guarantees or applicable consumer debts).

How long does the legal debt collection process take?

The timeline varies significantly based on court dockets, whether the debtor contests the suit, and state jurisdiction. A straightforward suit where the debtor fails to respond may result in a default judgment within 30 to 90 days, whereas contested litigation involving formal discovery and defense motions can extend across several months.


Talk to Us About Legal Collection Options for Your Account

Filed Under: Debt Recovery

Collecting Credit Card Debt: Challenges and Resolutions

credit card debt

Collecting credit card debt is a multifaceted challenge that involves legal, financial, and ethical considerations. It is a critical aspect of the financial services industry. However, the process is fraught with challenges that range from regulatory compliance to ethical concerns. Understanding these challenges is essential for both creditors and debt collection agencies.

Challenges Collecting Credit Card Debt

1. Regulatory Compliance

  • Strict Regulations: Debt collectors must adhere to a myriad of laws and regulations, such as the Fair Debt Collection Practices Act (FDCPA) in the United States. These laws are designed to protect consumers from abusive, deceptive, and unfair debt collection practices.
  • Varying State Laws: In addition to federal laws, collectors must navigate varying state laws and regulations, which can differ significantly in terms of restrictions and requirements.

2. Consumer Protection and Ethics

  • Consumer Rights: Consumers are increasingly aware of their rights, and any misstep by collectors can lead to complaints and legal actions.
  • Ethical Practices: Maintaining ethical practices while aggressively pursuing debts is a delicate balance. Harassing or threatening consumers is not only unethical but also illegal.

3. Financial Viability

  • Cost-Effectiveness: Collecting small or old debts might not be financially viable due to the costs involved in the collection process.
  • Debt Valuation: Accurately valuing debt portfolios is complex, and overvaluing them can lead to financial losses.

4. Technological Challenges

  • Data Management: Efficient management of large volumes of debtor data is crucial. Poor data management can lead to targeting the wrong individuals or outdated information.
  • Technology Integration: Implementing and integrating new technologies for better efficiency while ensuring compliance with data protection laws is a significant challenge.

5. Reputation Management

  • Public Perception: Debt collection agencies often struggle with negative public perception, which can impact their business relationships and overall success.
  • Brand Protection: Creditors must balance effective debt recovery with the need to protect their brand image, as aggressive collection tactics can lead to customer dissatisfaction and harm the brand.

6. Legal Challenges

  • Litigation Risks: The risk of legal action by consumers, either as individual lawsuits or class actions, is a constant concern.
  • Compliance Monitoring: Continuously monitoring and updating practices to remain compliant with ever-changing laws and court rulings is both challenging and essential.

7. Economic Factors

  • Economic Downturns: During economic downturns, the ability of consumers to pay back debts decreases, making debt collection more challenging.
  • Changing Consumer Behavior: Understanding and adapting to changing consumer spending and borrowing habits is crucial for effective debt recovery strategies.

Resolutions with Examples

1. Regulatory Compliance

  • Example: A debt collection agency might use automated calls to contact debtors, but if these calls violate the FDCPA’s restrictions on contact times or frequency, it could lead to legal issues.
  • Resolution: Regular training programs for collection staff on legal compliance, and implementing automated compliance checks in communication systems can help in adhering to regulations.

2. Consumer Protection and Ethics

  • Example: An agency that uses intimidating language or false statements to coerce payment can face lawsuits and heavy fines.
  • Resolution: Establishing strict ethical guidelines and monitoring communication for compliance can help maintain ethical standards and protect consumer rights.

3. Financial Viability

  • Example: Pursuing a debt that is small or several years old may cost more in resources than the debt is worth.
  • Resolution: Agencies can use analytics to assess the viability of collecting specific debts and focus resources on those with a higher likelihood of recovery.

4. Technological Challenges

  • Example: Outdated data may lead to contacting the wrong individuals, causing reputational damage and potential legal issues.
  • Resolution: Investing in advanced data management and analytics tools can ensure up-to-date and accurate information, enhancing the efficiency of collection efforts.

5. Reputation Management

  • Example: Aggressive tactics by a collection agency can lead to negative reviews and social media backlash, affecting both the agency and the creditor’s reputation.
  • Resolution: Adopting a customer-centric approach, focusing on helping debtors find feasible payment solutions, can improve public perception and protect the brand.

6. Legal Challenges

  • Example: A class action lawsuit can be filed against a collector for widespread non-compliance with collection laws.
  • Resolution: Legal risk assessments and regular audits of collection practices can help in identifying potential legal issues and rectifying them proactively.

7. Economic Factors

  • Example: During a recession, an increase in unemployment can lead to a higher rate of default on credit card debts.
  • Resolution: Implementing flexible payment plans and hardship programs during economic downturns can help in recovering debts while accommodating the debtor’s financial situation.

8. Communication and Negotiation

  • Example: Miscommunication or a lack of negotiation skills can lead to unresolved disputes and failed collection attempts.
  • Resolution: Training collectors in effective communication and negotiation techniques can lead to more successful resolutions.

9. Dealing with Bankruptcy

  • Example: A debtor filing for bankruptcy can halt all collection efforts, leading to potential losses.
  • Resolution: Monitoring bankruptcy filings and understanding the legal proceedings can help in strategizing the collection efforts accordingly.

10. Cross-border Debt Collection

  • Example: Collecting debts from consumers in different countries involves navigating different legal systems and cultural differences.
  • Resolution: Working with local collection agencies or legal experts in different countries can aid in understanding and complying with international collection practices.

Conclusion

Collecting credit card debt is a complex task that requires a careful balance between aggressive recovery efforts and adherence to legal and ethical standards. Successful debt collection involves navigating a challenging landscape of regulations, technological advancements, and changing consumer behaviors, all while maintaining a positive public image and ensuring financial viability.

Filed Under: Debt Recovery

GLBA Compliance: The Crisis for Small Collection Agencies

GLBA Law

Collection agencies are required to follow GLBA (Gramm-Leach-Bliley Act) compliance. The GLBA, primarily targeted at financial institutions, has a broad definition that can encompass debt collection agencies. This is because these agencies often handle consumer financial information, which falls under the purview of GLBA.

Hiring a non-GLBA compliant collection agency puts creditors at a high legal risk.

Problems and Financial Burden for Collection Agencies

  1. Increased Operational Costs: Implementing robust cybersecurity measures like advanced encryption and secure data storage systems is very expensive. For instance, smaller agencies may struggle to afford high-end security software that large corporations use.
  2. Training and Personnel: Agencies must regularly train their employees on handling sensitive information compliantly. This could mean hiring external trainers or dedicated compliance officers, which smaller agencies might find financially burdensome.
  3. Regular Audits and Updates: Continuous monitoring and updating of security practices to stay compliant can be costly. For example, an agency might need to hire external auditors to ensure their systems meet GLBA standards, which can be a significant expense.
  4. Legal and Consultation Fees: Understanding GLBA’s complexities often requires legal expertise. Smaller agencies may not have the budget to regularly consult with legal professionals, making compliance more challenging.
  5. Potential Penalties for Non-Compliance: Fines for non-compliance can be substantial. A small agency might face crippling penalties if found non-compliant, significantly impacting its financial stability.

Risks of Hiring a Non-GLBA Compliant Collection Agency

  1. Data Breaches and Loss of Sensitive Information: A non-compliant agency may lack secure data handling, leading to breaches. For example, inadequate data encryption could result in unauthorized access to student financial data.
  2. Legal and Financial Repercussions: Institutions face legal risks if their hired agency violates GLBA. This could lead to lawsuits and fines, as well as a loss of federal funding or accreditation in severe cases.
  3. Loss of Trust: If a student’s sensitive information is mishandled, it can lead to distrust towards the institution. This could result in decreased enrollment or donations.
  4. Operational Disruptions: Legal issues or breaches might force institutions to terminate contracts with non-compliant agencies, disrupting debt collection processes and affecting cash flow.
  5. Liability Issues: If a breach occurs due to the agency’s non-compliance, the institution may be held liable, resulting in legal and reputational damage.

Impact on Smaller Collection Agencies

GLBA compliance requires significant investment in technology, training, and legal counsel. Smaller collection agencies often operate with limited budgets and may find these requirements overwhelming. The cost of maintaining up-to-date security systems and regularly training staff can consume a substantial portion of their resources. Additionally, the risk of hefty fines for non-compliance adds to the financial strain.

As a result, many smaller agencies are facing closure. They struggle to compete with larger agencies that have the resources to invest in compliance measures. This trend not only affects the diversity of the collection agency market but also limits options for institutions looking to hire these services. The closure of smaller agencies can lead to less competition, potentially increasing costs and reducing innovation in the sector.

In summary, while GLBA compliance is crucial for protecting sensitive information, its stringent requirements and associated costs pose significant challenges, especially for smaller collection agencies. This has led to a consolidation in the industry, with smaller players either shutting down or being absorbed by larger firms.

Filed Under: Debt Recovery

University Debt Recovery | R2T4 & Tuition Collection Service

Universities AR

The “Enrollment Cliff” is no longer a forecast—it is your current fiscal reality. With the demographic decline in high school graduates hitting its peak and nearly half of all higher education institutions facing deficits in the upcoming academic year, the margin for error in your Accounts Receivable (AR) department has vanished.

In previous decades, a 2% write-off rate on tuition and fees was acceptable. Today, with 22.3% of first-time freshmen dropping out and the cost of acquiring a new student skyrocketing, every uncollected dollar represents a direct threat to your institution’s sustainability.

You are being asked to do the impossible: close the budget gap, remain compliant with increasingly complex Title IV (R2T4) regulations, and treat students with the “white glove” service required to boost retention.

NexaCollect is the partner that bridges the gap between the Bursar’s office and the bottom line. We don’t just “collect debt”; we execute a Tuition Revenue Preservation Strategy designed for the specific pressures of the current academic landscape.

The “Hidden Deficit”: Where Universities Are Bleeding Cash

While most universities focus on recruitment, the real financial leakage is happening in the back office. The traditional “wait and see” approach to AR is costing you millions.

1. The R2T4 Clawback Trap: When a student withdraws before the 60% completion mark, federal law mandates you return a portion of their Title IV aid.

  • The Statistic: Low-income students who owe R2T4 balances are 11% less likely to re-enroll.

  • The Problem: You are forced to return cash to the government immediately, leaving an instant deficit on the student’s ledger. Internal attempts to collect this “clawback” often fail because the student has already disengaged.

2. The “Murky Middle” Attrition: New data shows a spike in dropouts among students with 30–90 credits (sophomores and juniors). These students often leave with small unpaid balances—parking fines, lab fees, or partial tuition.

  • The Cost: If you block their registration over a $300 balance, you lose $25,000+ in future tuition revenue. If you ignore it, your bad debt ratio balloons.

  • The Fix: You need a diplomatic intervention that resolves the $300 balance and gets them back in the classroom.

3. The Administrative Burden: Bursar teams are shrinking just as regulations are expanding.

  • The Reality: Your staff spends 40% of their week chasing “soft” receivables—calling parents, explaining EOBs, and navigating FERPA waivers—instead of focusing on strategic financial planning.

A Tiered Recovery Model: Precision Over Brute Force

We reject the “one-size-fits-all” agency model. We apply the right pressure at the right time to maximize recovery and retention.

Phase 1: The Retention-Focused Nudge (Active Students)

  • Best For: Current students with registration holds, small ancillary fees (Housing, Parking, Library).

  • The Strategy: We deploy our Step 2 Flat-Fee Service ($15/account). We send official, third-party notifications that serve as a “wake-up call” rather than a threat.

  • The Benefit: This prompts payment while keeping the student enrolled. You amplify your Bursar’s capacity without adding headcount, clearing hundreds of small accounts off your books for a nominal fee. You keep 100% of the revenue.

Phase 2: The Post-Separation Recovery (Inactive Students)

  • Best For: R2T4 balances, true dropouts, and aged receivables (120+ days).

  • The Strategy: We escalate to Step 3 (Contingency). We use advanced skip-tracing to locate former students who have moved off-campus. We report to credit bureaus (Equifax, Experian, TransUnion), which often motivates recent dropouts to pay so they can sign apartment leases or buy cars.

  • The Benefit: We handle the difficult conversations. We charge a 40% fee only if we succeed.

Recent Results: Securing Revenue in a Deficit Year

Scenario A: The “Sophomore Slump” Rescue

  • The Crisis: A mid-sized private college in Ohio identified 200 sophomores with “gap balances” averaging $800 after financial aid. The Bursar feared blocking their registration would worsen their enrollment crisis.

  • The Solution: We used our Step 2 Flat-Fee approach to send a supportive letter: “Resolve this balance to secure your Fall schedule.”

  • The Outcome: 65% of the students paid within 3 weeks. The college recovered $104,000 in immediate cash and, crucially, retained $3.8 million in future tuition revenue from those re-enrolling students.

Scenario B: The R2T4 Recovery

  • The Crisis: A state university had written off $450,000 in “Title IV Returns” over two years. The students had withdrawn, the school paid the government, and the students never paid the school back.

  • The Solution: We treated these as “Hard Debt.” We skip-traced the former students (many had moved back home) and reported the debts to credit bureaus.

  • The Outcome: Facing credit score drops, many former students (and their co-signing parents) settled. We recovered $180,000 (40%) of a debt pile the university deemed “uncollectible.”

Q&A: Navigating the Compliance Minefield

Q: With the “Enrollment Cliff” reducing our prospect pool, won’t collections hurt our brand?

A: Not if done correctly. “Junkyard” agencies hurt brands. Our diplomatic approach actually helps retention by clearing financial hurdles that keep students from registering. We allow you to safeguard your institution’s public standing while securing tuition revenue.

Q: How do you handle the “I withdrew, why do I owe this?” objection?

A: This is the #1 dispute in higher ed. Our agents are trained to explain the difference between academic withdrawal and financial liability. We walk the student through the R2T4 calculation so they understand that the debt is valid and federal in origin.

Q: Can you integrate with Banner, PeopleSoft, or Jenzabar?

A: We are software-agnostic. You can export your AR data to Excel or CSV and upload it to our secure, encrypted portal in seconds. You don’t need IT to build a complex API bridge.

Stabilize Your Institution’s Future

The deficit clock is ticking. You cannot afford to let 22% of your freshman class leave with unpaid bills. Switch to a recovery partner that understands the economics of modern higher education.

Click here to Contact Us for a confidential AR analysis.

Filed Under: Debt Recovery

  • « Go to Previous Page
  • Page 1
  • Interim pages omitted …
  • Page 9
  • Page 10
  • Page 11
  • Page 12
  • Page 13
  • Interim pages omitted …
  • Page 55
  • Go to Next Page »

Primary Sidebar


accounts receivable

Need a Collection Agency?
Kindly fill this form.
We’ll get in touch with you

    Please prove you are human by selecting the house.

    Compliance & Security

    • SOC 2 Type II Certified: Third-party audited data security and strict privacy controls.

    • HIPAA Compliant: Secure, legal processing of medical and municipal EMS accounts.

    • PCI-DSS Level 1: Highest tier of data encryption for secure payment processing.

    • FDCPA & FCRA Aligned: Full legal adherence to federal consumer protection laws.

    Recent Posts

    • Nationwide Debt Collection Agency Serving U.S. Cities
    • Chula Vista Collection Agency for Medical, B2B, Schools & Business Debt
    • Corpus Christi Collection Agency: Itemized Bill Rules for Practices
    • Riverside Collection Agency | For Logistics, Medical, Schools & Business Recovery
    • Collection Agency for Large Balances: High-Value B2B Debt Recovery
    • Baltimore Collection Agency | Medical, Commercial, Schools & More
    • Commercial and B2B Collection Agency in Detroit
    • Boston Medical Collection Agency | Serving Hospitals, Physicians & Dentists

    Featured Posts

    • Why is Data Security for Collection Agencies Important?
    • What are the Big Flaws of Body Mass Index (BMI)
    • How Automation Enhances the Human Experience

    Copyright © 2026 NEXACOLLECT.COM | This content is provided for general informational purposes only and should not be considered legal advice. Collection laws and requirements may vary by state, account type, documentation, debtor status, and specific facts. Please consult qualified legal counsel for guidance regarding your particular situation. Nexa and its authorized collection partners service accounts in accordance with applicable federal and state collection requirements. Visit our home page to know more about us.

    X
    Need a Collection Agency?
    Contact Us