• Skip to main content
  • Skip to primary sidebar

Nexa Collections

  • Home
  • Serving
    • Medical
    • Dental
    • Small Business
    • Large Business
    • Commercial Collections
    • Government
    • Utilities
    • Fitness Clubs
    • Schools
    • Senior Care Facility
  • Contact Us
    • About us
    • Cost

Debt Recovery

The Modern Accounts Receivable Specialist: Essential Skills & Strategic Mastery

In today’s high-velocity financial landscape, an Accounts Receivable (AR) Specialist is far more than a “bill collector.” They are the Architects of Cash Flow, responsible for the lifeblood of the organization. To excel in this role, one must blend clinical accounting precision with the psychological finesse of a master negotiator.
AR Professional Skills

Below is an in-depth guide to the core competencies required for a top-tier AR Specialist, complete with practical implementation strategies and industry benchmarks.


1. Advanced Financial Analysis & Technical Accounting

Technical proficiency is the “Hard Skill” foundation. A specialist must not only record data but interpret the “why” behind the numbers.

  • DSO (Days Sales Outstanding) Optimization: A elite specialist understands that if the industry average DSO is 45 days, and their company is at 52, there is a systemic leak.

    • Practical Implementation: Conduct monthly “Aging Audits.” Identify which 5% of clients are causing 80% of the delays (Pareto Principle) and adjust credit terms for those specific profiles.

  • The “3-Way Match” Accuracy: You must ensure the Purchase Order (PO), Invoice, and Receiving Report align perfectly. Even a 1% discrepancy in unit pricing can stall a $50,000 payment for months.

  • ERP Mastery (NetSuite, SAP, Oracle): Beyond clicking buttons, you should know how to build custom reports.

    • Example: Creating a “High-Risk” dashboard that flags any account that has missed two consecutive “promise-to-pay” dates.

2. Strategic Negotiation & Psychological Communication

The goal is to secure payment while retaining the customer. This requires a delicate balance of empathy and firmness.

  • The “Solution-Oriented” Scripting: Instead of asking “Why haven’t you paid?”, use “I see the invoice is 15 days past due; is there a specific documentation gap I can help resolve to get this cleared by Friday?”

  • Active Listening & De-escalation: If a client is angry about a product defect, an AR specialist must pivot.

    • Scenario: A client refuses to pay $10,000 because $500 worth of goods arrived damaged.

    • Practical Implementation: Negotiate a “Partial Payment” immediately. Secure the $9,500 undisputed amount while the $500 credit is being processed. This keeps the cash flow moving.

  • The Power of the Follow-Up: Research shows that 80% of collections require 5+ touchpoints. A specialist must be persistent without being perceived as a nuisance.

3. Data-Driven Decision Making

Modern AR is a game of predictive analytics. You are looking for patterns before they become problems.

  • Credit Risk Assessment: Before a sale is made, the AR specialist often vets the client.

    • Number to Watch: The “Collection Effectiveness Index” (CEI). A high-performing specialist maintains a CEI of 90% or higher.

  • Trend Analysis: If a long-term “Net-30” client suddenly starts paying on Day 45, it’s a red flag.

    • Practical Implementation: Reach out proactively. It may be a simple change in their accounting staff, or it could be a sign of insolvency. Catching this early prevents a total write-off.

4. Regulatory Compliance & Ethical Standards

A single compliance mistake can cost a company more in legal fees than the original debt was worth.

  • FDCPA & FCRA Mastery: In B2C environments, strictly adhering to the Fair Debt Collection Practices Act is vital. This includes knowing when you can call and what language constitutes harassment.

  • HIPAA & SOC2 (Data Privacy): If handling medical or high-security financial data, you must understand encryption and “need-to-know” access.

    • Example: Never leaving unredacted patient statements on a printer or in an unencrypted email.

  • Internal Controls (SOX Compliance): Ensuring a clear separation of duties to prevent internal fraud. For instance, the person who issues the credit memo should not be the same person who reconciles the bank statement.

5. Technology & Automation Integration

The “Modern Edge” is the ability to leverage FinTech to eliminate manual tasks.

  • Dunning Automation: Setting up tiered email sequences (e.g., Day 1: Friendly Reminder; Day 15: Firm Inquiry; Day 30: Formal Notice).

  • VLOOKUP & Pivot Table Proficiency: This is non-negotiable for large-scale reconciliation.

    • Scenario: You have a 1,000-line bank statement and a 1,000-line AR sub-ledger.

    • Practical Implementation: Use a VLOOKUP to match invoice numbers instantly, reducing a 4-hour manual task to 10 minutes.

  • Payment Portal Management: Encouraging clients to use ACH or Credit Card portals to reduce “Check in the mail” delays by an average of 5.5 days.

The Final Verdict

An AR Specialist with these skills transforms the department from a “cost center” into a revenue-protecting powerhouse. By mastering the numbers, the tech, and the talk, they ensure the company stays liquid and competitive in any economy.

A successful Accounts Receivable Specialist is detail-oriented, organized, an effective communicator, a problem solver, financially knowledgeable, customer-focused, adaptable, efficient in time management, skilled in data analysis, and ethical.
Filed Under: Debt Recovery

Stop Losing 40% of Your Revenue to Collection Fees (Do This Instead)

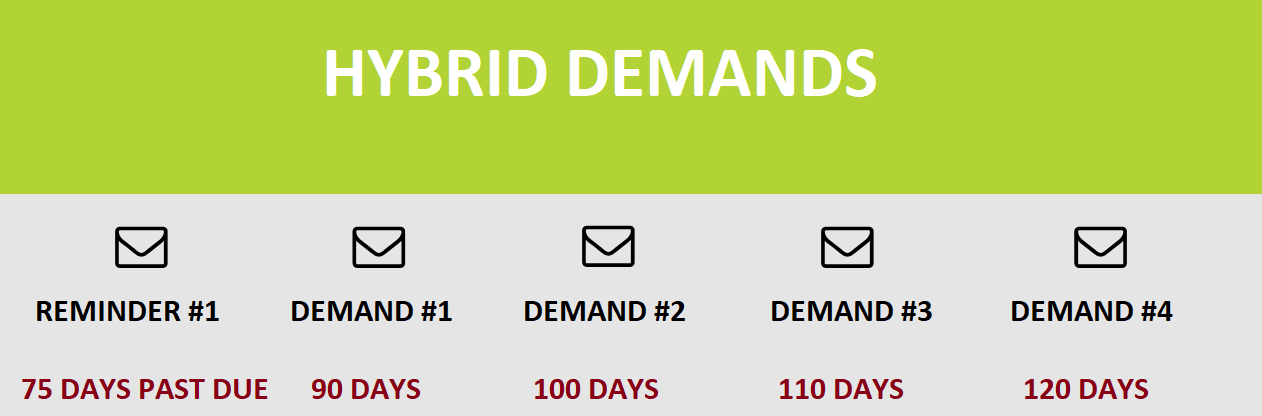
Use Fixed Fee Hybrid demands service for newer accounts !

Hybrid collections

You worked hard for that money. Why give half of it away?

If you run a medical practice, dental office, or small business, you know the pain: You have unpaid bills, but sending them to a traditional collection agency feels like a defeat. Why? Because most agencies take 33% to 50% of the money they collect as their commission.

That means on a $1,000 bill, you might only see $600. The rest vanishes.

But for debts that are less than a year old, there is a smarter way. It’s called Fixed-Fee Recovery, and it changes the math entirely.

The Problem: Traditional “Contingency” Collections

The traditional model works on a percentage. The agency says, “We don’t get paid unless you get paid.” That sounds great, but it’s expensive. It’s designed for old, difficult debt that requires hard labor to recover.

For newer accounts, you are overpaying. massively.

Fixed-fee collections use a diplomatic, professional approach that recovers your money while protecting your hard-earned reputation and preserving valuable client relationships. 

The Solution: The “Pre-Collect” Fixed Fee Model

Instead of giving up a percentage of your revenue, you pay a small, one-time flat fee per account (typically around $15) to purchase a “block” of accounts.

Here is the difference:

  • Contingency: You pay a huge commission on success.

  • Fixed Fee: You pay a tiny flat rate upfront. You keep 100% of the money recovered.

Let’s Look at the Math

Here is a real-world comparison on a single $2,000 unpaid balance.

Standard Agency (33%) Fixed-Fee Service
Debt Amount $2,000 $2,000
Cost to You $660 (Commission) ~$15 (Flat Rate)
Money You Keep $1,340 $1,985
PROFIT DIFFERENCE +$645

How It Works (The 3-Step Process)

When you use a Fixed-Fee service through our partners, you are automating the pressure on the debtor without losing your profit margin.

  1. You Upload the Accounts: You purchase a batch of accounts (credits) that never expire. You enter the debtor’s info into a secure portal.

  2. The System Goes to Work: The agency sends a series of 5 attorney-approved demand letters and makes automated calls in your name.

  3. You Get Paid Directly: The debtor is instructed to pay YOU. The money goes to your office or your bank account. The agency never touches it.

Is Fixed-Fee Right for You?

This model isn’t for everyone. It works best if you fit this profile:

  • Your debt is “fresh”: Accounts are between 60 days and 12 months past due.

  • You have smaller balances: If you have many accounts under $500, a contingency fee usually eats all the profit. Fixed-fee protects it.

  • You value customer relationships: Fixed-fee services are firm but professional. They are designed to get you paid without burning bridges or creating “bad blood.”

The “Smart Strategy” (Phase 1 vs. Phase 2)

We recommend a Two-Phase Approach to maximize your revenue:

  • Phase 1 (The Audit Phase): Send all accounts between 90–120 days past due to the Fixed-Fee service. This costs you pennies on the dollar and recovers the majority of solvable debt.

  • Phase 2 (The Cleanup Phase): Any accounts that still haven’t paid after the Fixed-Fee cycle can then be rolled over to a traditional contingency agency for harder collections.

Stop Bleeding Revenue

Don’t let unpaid invoices sit until they are worthless, and don’t pay 40% fees on easy-to-collect money.

Ready to try the low-cost approach?

Fill out the form below to get a quote for Fixed-Fee services tailored to your industry.

Filed Under: Debt Recovery

10 Ideas for Your Debt Collections Blog

Creating a blog focused on debt collections can offer valuable insights and guidance for both professionals in the field and individuals dealing with debt. Here are ten ideas for blog topics:

  1. Understanding Your Rights: A guide to what collectors can and cannot do legally, aimed at educating both debtors and new collectors about the legal landscape of debt collection.
  2. Negotiation Strategies for Collectors: Tips on how collectors can effectively negotiate payment plans with debtors, focusing on communication skills and understanding debtor’s circumstances.
  3. Impact of Debt on Credit Scores: An exploration of how different types of debt and their management affect credit scores, offering advice for debtors on how to minimize negative impacts.
  4. Technological Advances in Debt Collection: Discussing the latest technologies in debt collection, such as automated calling systems, AI, and how they’re changing the industry.
  5. Stories from the Field: Sharing real-life stories and case studies from experienced debt collectors, focusing on challenges, successes, and unique experiences.
  6. Dealing with Difficult Cases: Advice for collectors on how to handle particularly challenging or sensitive debt collection scenarios, including ethical considerations.
  7. Debt Collection Laws and Regulations Update: Regular updates on changes in laws and regulations affecting debt collection, both nationally and internationally.
  8. Personal Debt Management Tips: Offering practical advice for individuals on managing and paying off personal debts, including budgeting and prioritizing debts.
  9. Future of Debt Collection: Speculating on the future trends in the debt collection industry, including potential regulatory changes and emerging market needs.
  10. Interviews with Industry Experts: Featuring interviews with seasoned professionals in the debt collection industry, discussing their insights, experiences, and predictions for the future of the industry.

These topics cover a broad range of interests and perspectives within the field of debt collection, making the blog a valuable resource for a wide audience.

Filed Under: Debt Recovery

Empathetic Medical Debt Collection Agency Services

Doctors hesitate to send patients to collections mainly out of fear, not indifference: fear of a retaliatory online review, fear of a HIPAA misstep, and fear that demanding payment will end a patient relationship they worked hard to build. In practice, the opposite tends to happen. A patient-centered, compliant recovery process, one that explains charges clearly, offers real payment options, and never threatens or harasses, typically resolves the awkwardness faster than months of unpaid statements and avoided conversations, while keeping far more patients in the practice than an internal team that lets accounts quietly age instead.

Doctor reviewing patient accounts receivable, illustrating hesitation to send balances to collections

For a medical provider, the Hippocratic Oath, “first, do no harm,” often sits uneasily next to the reality of running a business. Most doctors trained to heal, not to chase invoices, and a quiet trend has followed: practice administrators let accounts receivable stack up because they fear a collection agency will damage their reputation, violate patient trust, or trigger a compliance misstep, and many simply don’t have the expertise to recover balances lawfully in the first place. With high-deductible health plans shifting more of the bill directly onto patients, standing still isn’t caution. It’s a slow financial leak.

The 3 major fears keeping practices in the red

The fear of the “one-star” review

In the digital age, reputation is a practice’s lifeline. Doctors worry that sending a patient to collections will trigger a retaliatory online review accusing the practice of being greedy. Aggressive, heavy-handed agencies genuinely do cause this. A diplomatic, patient-centered recovery service tends to have the opposite effect: clear communication and real solutions usually prevent the anger that leads to bad reviews in the first place.

The HIPAA and compliance minefield

Data privacy rules have never been stricter, and the fear of a breach or an accidental violation of the No Surprises Act keeps many office managers up at night. In practice, keeping collections entirely in-house is often the riskier path. Front-desk staff rarely track Regulation F’s call-frequency limits the way a dedicated collections process does; a professional partner acts as a compliance layer, not an added risk.

The “patient relationship” myth

Many providers assume that asking for payment ends the doctor-patient relationship. Financial ambiguity usually does more damage than a direct conversation. Patients often stop booking appointments simply because they’re embarrassed about an outstanding balance; resolving the debt clears the air and lets them come back.

The modern standard: what to look for in a collection partner

The goal isn’t a “bounty hunter.” It’s a revenue cycle partner. Five features are worth treating as non-negotiable when evaluating a firm to handle patient accounts.

A true patient-centric approach

Collecting on a medical bill isn’t the same as collecting on a credit card balance. The right approach explains insurance deductibles and EOBs rather than demanding payment outright, helping patients understand why a balance exists and how to resolve it, which preserves the relationship far better than a blunt collection notice.

Bank-level data security

A data breach can be a practice-ending event, and compliance isn’t optional. A signed Business Associate Agreement should be in place before any protected health information is shared, alongside 256-bit encryption for data transfers and adherence to SOC 2 Type II security standards, so patient health information stays protected and the practice stays out of liability’s way.

Frictionless payment options

If paying is hard, patients simply don’t do it. A secure, mobile-friendly payment portal lets patients pay by credit card, HSA or FSA card, or set up an automated plan whenever it’s convenient for them, not just during office hours. Removing friction meaningfully improves how much of a balance actually gets collected.

The “diplomacy first” financial model

Agencies that push high contingency fees on every account, often 33-50%, have a built-in incentive toward aggression. A flat-fee model flips that incentive: sending official, polite third-party demands for a low fixed cost per account resolves most medical debts without a single angry phone call.

Easy-to-use service for your staff

A front desk that’s already stretched thin doesn’t have time for complicated software. A simple, secure online dashboard should let staff upload accounts individually or in bulk, track status and payments, and stop collection activity instantly if a patient walks in and pays directly.

Real world scenarios: compassion in action

These examples show what patient-centered recovery looks like when the fear of collections gives way to an actual plan.

Pediatric group, New Jersey:
A busy pediatric practice had $58,000 in past-due copays and was worried about upsetting parents in a tight-knit community. A flat-fee letter series explained, plainly, that balances were tied to insurance gaps rather than treating families like delinquent debtors. Within six weeks, the practice recovered $41,500, no families left the practice, and the cost to the doctor was under $600. (Nexa internal data, 2025)

Ambulatory surgery center, Texas:
An ASC had several high-balance accounts, $2,000 and up, tied to out-of-network surgeries, and worried about No Surprises Act disputes. Files were audited for compliance before any patient contact, then payment plans were negotiated on the accounts that remained valid. Three of five major accounts settled, recovering $14,200 that had nearly been written off, with no legal disputes since debt validity was confirmed first. (Nexa internal data, 2025)

How patient data is protected throughout the process

A signed Business Associate Agreement is in place before any protected health information is shared, consistent with HIPAA requirements. Data moves through a secure, encrypted client portal, never unsecured email, and every call and letter follows FDCPA and Regulation F guidelines, including call-frequency limits. This isn’t a bolt-on feature; it’s the baseline a practice should expect before sharing a single account. Medical Collections and Dental Bill Collection requires an in-depth understanding of patient doctor relationship.

Nexa provides a reputation-safe approach, backed by a comprehensive 50-state collections licensing infrastructure, offering free credit reporting,  free litigation/bankruptcy scrubs, and zero onboarding fees. Secure – SOC 2 Type II & HIPAA compliant. 

Need a Collection Agency? Contact us


What this actually costs

Nexa Collections fixed-fee and contingency pricing for medical patient balance recovery

Fixed-Fee Recovery ($15/account): ideal for early-stage receivables. Patients pay 100% directly to you, with no commission taken out.

Contingency Service (20%-40%): performance-based recovery for older or harder accounts. No recovery, no fee.

Most practices start with the flat-fee tier for fresh balances and move only the accounts that don’t resolve into contingency. For more on how Nexa’s medical collections process works for patient balances, how this applies to dental practices facing the same hesitation, or what actually happens once an account is placed with a collection agency, and for exact rates, see the full breakdown of Nexa’s fixed-fee and contingency pricing. For a look at how cybersecurity and data handling work across every account type, that compliance layer applies here too.

FAQ

Can you collect from patients who have moved or changed jobs?

Yes. Skip-tracing technology helps locate patients who have relocated. Often patients simply forgot to update their address, and a letter to their new home is enough to secure payment.

What if the patient claims insurance should have paid?

This is the most common objection in medical collections. Collection activity pauses to validate the debt, and if it’s an insurance error, the patient is directed back to the practice’s billing team or their insurer, not harassed over a valid mistake.

Do you report medical debt to credit bureaus?

There is currently no federal rule banning medical debt from credit reports; a CFPB rule that would have imposed one was vacated by a federal court in July 2025. What does still apply, as of 2026, are voluntary policies the three major credit bureaus adopted in 2022-2023: paid medical collections are removed regardless of amount, and unpaid medical debt under $500 or less than a year old generally isn’t reported. Some states also restrict medical debt reporting independently, though that area is subject to ongoing legal challenges. Reporting is used sparingly, only where legally appropriate, and never as a first resort.

Will sending a patient to collections generate a bad online review?

Aggressive agencies can trigger this. A diplomatic, patient-centered process that communicates clearly and offers real solutions usually prevents the anger that leads to negative reviews in the first place.

Does sending a patient to collections end the doctor-patient relationship?

Often the opposite is true. Financial ambiguity and an unresolved balance are more likely to keep a patient away than a clear, respectful conversation that resolves the debt.

What’s the difference between fixed-fee and contingency medical collections?

Fixed-Fee Recovery, at $15 per account, suits early-stage receivables with no commission taken. Contingency Service, at 20-40%, is performance-based for older or harder accounts, with no recovery meaning no fee.

Heal your practice’s financial health

Excellent patient care deserves a partner that treats the business side with the same seriousness. Fear shouldn’t be the thing setting a practice’s financial strategy.

Filed Under: Debt Recovery

Addressing the Common AR Issues of Preschools

Preschools, like many educational institutions, face specific accounts receivable (AR) challenges. These issues can significantly impact their financial health if not managed properly. Some common AR issues for preschools include:

  1. Late or Unpredictable Payments: Parents or guardians may delay payments for tuition and other fees. This can create cash flow problems for the preschool. To address this, clear payment terms should be established, and regular reminders sent. Additionally, setting up automated payment systems can help ensure timely payments.
  2. Inaccurate Billing: Mistakes in billing can lead to disputes and delayed payments. It’s important for preschools to maintain accurate billing records. Using reliable billing software and regularly training staff in its use can reduce errors.
  3. Lack of Payment Plans: Some families may struggle with lump-sum payments. Offering flexible payment plans can help ensure consistent cash flow and reduce the burden on families. It’s important to clearly communicate the terms of these plans and monitor adherence.
  4. Inefficient Tracking of Receivables: Without a proper system to track accounts receivable, it’s easy to lose track of who owes what. Implementing a robust accounting system that can track receivables, send automatic reminders, and generate reports is critical.
  5. Difficulty in Handling Delinquent Accounts: Collecting overdue payments can be challenging. Establishing a clear policy for handling delinquent accounts, which may include late fees or suspension of services, is essential. For extreme cases, partnering with a collection agency can be considered, but it’s important to handle such situations sensitively due to the nature of the service provided.
  6. Varying Payment Methods and Currencies: With the increasing diversity in payment methods, including digital payments, managing multiple payment channels can become complicated. Pre-schools should ensure they have the capacity to handle various payment methods efficiently.
  7. Limited Understanding of Financial Policies by Parents: Sometimes, parents may not fully understand the payment policies. Clear communication and accessible documentation of all financial policies are important. Regular meetings or informational sessions can be helpful.
  8. Inadequate Financial Aid Management: If a pre-school offers scholarships or financial aid, managing these funds requires careful attention to ensure they are appropriately allocated and accounted for.

Addressing these issues

Addressing the common accounts receivable (AR) issues faced by pre-schools requires a combination of strategic planning, technology adoption, and clear communication. Here are solutions to the previously mentioned challenges:

  1. Late or Unpredictable Payments:
    • Automated Payment Systems: Implement automated payment solutions like direct debits to ensure timely payments.
    • Clear Payment Terms and Reminders: Set and communicate clear payment terms. Send regular reminders as due dates approach.
    • Incentives for Timely Payments: Offer discounts or other incentives for early or on-time payments.
  2. Inaccurate Billing:
    • Reliable Billing Software: Invest in efficient billing software that minimizes errors.
    • Regular Staff Training: Train staff regularly to ensure they are adept at using the billing system correctly.
    • Audit and Review: Conduct regular audits of billing records to catch and correct any errors.
  3. Lack of Payment Plans:
    • Flexible Payment Options: Offer various payment plans to accommodate different financial situations of families.
    • Clear Communication of Terms: Ensure parents understand the terms of payment plans, including any interest or fees for late payments.
  4. Inefficient Tracking of Receivables:
    • Robust Accounting System: Use an accounting system that can efficiently track receivables, send automated reminders, and produce detailed reports.
  5. Difficulty in Handling Delinquent Accounts:
    • Clear Delinquency Policy: Have a well-defined policy for handling late payments, including potential consequences.
    • Sensitive Approach: Approach delinquent accounts with understanding and offer to work out feasible payment solutions.
  6. Varying Payment Methods and Currencies:
    • Multiple Payment Channels: Accept various forms of payment, including online and mobile payment platforms, to accommodate different preferences.
    • Regular Reconciliation: Regularly reconcile payments received through different channels to ensure accurate accounting.
  7. Limited Understanding of Financial Policies by Parents:
    • Effective Communication: Use multiple channels to communicate financial policies clearly, such as meetings, emails, and handouts.
    • Accessibility of Information: Make financial policies easily accessible, possibly through a parent portal or a website.
  8. Inadequate Financial Aid Management:
    • Dedicated Tracking System: Have a system dedicated to tracking financial aid and scholarships, ensuring transparency and proper allocation.
    • Regular Reviews: Periodically review the financial aid process and amounts to ensure they are meeting the needs of both the pre-school and the recipients.

By implementing these solutions, pre-schools can significantly improve their AR processes, leading to better cash flow management, reduced financial risks, and stronger relationships with the families they serve.

Filed Under: Debt Recovery

The “Paper Judgment” Trap: Why Your Court Victory is Only Half the Battle

In the United States, winning a court case makes you a Judgment Creditor, but the court itself does not collect the money for you. A judgment is effectively a “legal license” to go after the debtor’s assets—it is not a guarantee of payment. If your debtor has gone silent despite a court order, you need to transition from “litigation” to “enforcement.”

blank

The Role of the Sheriff: Your Legal “Muscle”

Many people wonder: Can I just walk into the debtor’s bank with my judgment and withdraw the cash? The answer is no. Banks will not honor a judgment presented by a private citizen; they require a Writ of Execution served by a law enforcement officer.

Can a Sheriff Go to the Bank With You?

While a Sheriff is your primary tool for recovery, they do not act as a personal escort for withdrawals. You cannot simply walk into a branch with a Deputy and ask for a payout. Instead, the Sheriff acts as a Levying Officer.

  1. The Paper Trail: You provide the Sheriff with the Writ and a “Letter of Instruction” naming the bank and account.

  2. The Service: The Sheriff (or a registered process server) officially serves the bank.

  3. The Freeze: The bank immediately freezes the funds. They then send the money to the Sheriff’s Office, not to you directly.

  4. The Payout: The Sheriff holds the funds for a mandatory period (usually 15–30 days) to allow the debtor to claim exemptions. If no claim is made, the Sheriff issues a check to you, minus their service fees.

You can also contact a lawyer, who can handle the complex legal filings, help you coordinate with sheriff, conducts professional asset discovery to find hidden accounts, and initiates forced collection actions like bank levies and wage garnishments to turn your paper judgment into cash.


Step 1: Post-Judgment Discovery (Finding the Money)

A Sheriff cannot “hunt” for money; you must provide specific locations.

  • Information Subpoenas: Legal questionnaires requiring disclosure of assets under oath.

  • Debtor’s Examination: A court hearing where the debtor must testify about their finances.

  • Third-Party Discovery: Subpoenaing records from the debtor’s known clients or employers.


Step 2: State-Specific Enforcement & Exemption Guide (2026)

Rank State Judgment Duration Renewal Timeline 2026 Homestead Exemption (Equity)
1 California 10 Years Before Year 10 $371,547 – $743,459 (County Dependent)
2 Texas 10 Years Before Year 10 Unlimited (Up to 10 urban/200 rural acres)
3 Florida 20 Years Before Year 20 Unlimited (Up to 0.5 city/160 rural acres)
4 New York 20 Years Every 10 Years $99,225 – $198,450 (By County)
5 Pennsylvania 5 Years Every 5 Years None (Only Tenancy by the Entirety)
6 Illinois 7 Years Every 7 Years $50,000 (Individual) / $100,000 (Joint)
7 Ohio 5 Years Every 5 Years $125,000
8 Georgia 7 Years Before Year 7 $21,500 (Individual) / $43,000 (Joint)
9 N. Carolina 10 Years Before Year 10 $35,000 (Up to $60,000 for seniors)
10 Michigan 10 Years Before Year 10 $46,450 ($69,675 for seniors/disabled)
11 New Jersey 20 Years Before Year 20 None (Only Tenancy by the Entirety)
12 Virginia 20 Years Every 10 Years $25,000 (plus $5,000 per dependent)
13 Washington 10 Years Before Year 10 Greater of $125k or County Median Sale Price
14 Arizona 10 Years Before Year 10 $400,000
15 Tennessee 10 Years Before Year 10 $5,000 ($25,000 for seniors/joint)
16 Massachusetts 20 Years Before Year 20 $125,000 (Automatic) / $500,000 (Declared)
17 Indiana 20 Years Before Year 20 $22,750
18 Missouri 10 Years Every 10 Years $15,000
19 Maryland 12 Years Before Year 12 $25,100
20 Wisconsin 20 Years Every 10 Years $75,000

Step 3: Navigating 2026 Asset Protections

States adjust these limits for inflation. Notice these specific trends:

  • “Till Taps” and “Keepers”: If the debtor is a business, you can pay a fee for a Sheriff to physically stand at the business’s cash register and take every dollar that comes in until your judgment is paid.

  • Motor Vehicle Exemptions: If you seize a car, you must pay the debtor their exemption amount from the sale proceeds before you take your share.

  • Tools of the Trade: Professionals can often protect thousands of dollars in equipment, making it difficult to seize business assets for sole proprietors.

Conclusion: Persistence is Key

The Sheriff is a powerful ally, but they are a reactive force. You must provide the intelligence (where the assets are) and the paperwork (the Writ) to set them in motion. By monitoring renewal deadlines and understanding state exemptions, you can turn your paper judgment into a successful recovery.

Filed Under: Debt Recovery

  • « Go to Previous Page
  • Page 1
  • Interim pages omitted …
  • Page 11
  • Page 12
  • Page 13
  • Page 14
  • Page 15
  • Interim pages omitted …
  • Page 55
  • Go to Next Page »

Primary Sidebar


accounts receivable

Need a Collection Agency?
Kindly fill this form.
We’ll get in touch with you

    Please prove you are human by selecting the car.

    Compliance & Security

    • SOC 2 Type II Certified: Third-party audited data security and strict privacy controls.

    • HIPAA Compliant: Secure, legal processing of medical and municipal EMS accounts.

    • PCI-DSS Level 1: Highest tier of data encryption for secure payment processing.

    • FDCPA & FCRA Aligned: Full legal adherence to federal consumer protection laws.

    Recent Posts

    • Why Dental Patients Dispute Bills: The Nexa Collections Dental Account Dispute Index
    • 2027 Commercial Collections Benchmark: U.S. Late Payments, AR Risk and B2B Collection Trends
    • Bulk Account Placement: What a Collection Agency Actually Needs From You
    • Nationwide Debt Collection Agency Serving U.S. Cities
    • Chula Vista Collection Agency for Medical, B2B, Schools & Business Debt
    • Corpus Christi Collection Agency: Itemized Bill Rules for Practices
    • Riverside Collection Agency | For Logistics, Medical, Schools & Business Recovery
    • Collection Agency for Large Balances: High-Value B2B Debt Recovery

    Featured Posts

    • Collection Agency for Rehab Centers and Physiotherapists
    • Steps for Out-of-State Doctors to Practice in Texas
    • Texas Restoration Collections | $15 Fixed-Fee Debt Recovery

    Copyright © 2026 NEXACOLLECT.COM | This content is provided for general informational purposes only and should not be considered legal advice. Collection laws and requirements may vary by state, account type, documentation, debtor status, and specific facts. Please consult qualified legal counsel for guidance regarding your particular situation. Nexa and its authorized collection partners service accounts in accordance with applicable federal and state collection requirements. Visit our home page to know more about us.

    X
    Need a Collection Agency?
    Contact Us