• Skip to main content
  • Skip to primary sidebar

Nexa Collections

  • Home
  • Serving
    • Medical
    • Dental
    • Small Business
    • Large Business
    • Commercial Collections
    • Government
    • Utilities
    • Fitness Clubs
    • Schools
    • Senior Care Facility
  • Contact Us
    • About us
    • Cost

Debt Recovery

Farm Equipment Debt Recovery: Get Paid Without Losing the Community

Agricultural equipment dealers don’t just sell machinery; they power the American food supply. However, when a $250,000 tractor payment goes missing, it’s more than a late bill—it’s a direct hit to your dealership’s floor plan and interest-coverage ratio. In a community-based industry, a “bully” collection style can destroy your local standing, but silence on aged debt can destroy your business.

Nexa provides a specialized, Reputation-First recovery system designed for the unique cash-flow cycles of the agricultural world. We bridge the gap between being a “good neighbor” and ensuring your financial survival.

Secure Your Dealership’s Cash Flow Now

Nexa provides 100% reputation-safe, equipped with all 50-state collections license, offering free credit reporting, free litigious debtor check, free bankruptcy scrub, and zero onboarding fees. Secure – SOC 2 Type II & HIPAA compliant. Over 2,000 online reviews rate us 4.85 out of 5. 


The Ag-Equipment Reality: Why Timing is Everything

  • The Depreciation Danger Zone: In the ag world, a delinquent account is a depreciating asset. With tier-4 engine technology and high-hour depreciation, a combine sitting in a shed on day 120 of non-payment can lose 15% of its recovery value before the first mediation call is even made. We stop the clock and secure the value.

  • Statutory Lien Priority (The PMSI Advantage): Don’t let the local bank take your collateral. We specialize in enforcing Purchase Money Security Interests (PMSI). This gives you “super-priority” over a farmer’s existing blanket liens—but only if you act within strict UCC filing windows. Nexa ensures you stay first in line for the check, not last.

  • The “Elevator Check” Timing Strategy: Ag-debt isn’t about ability; it’s about liquidity. We synchronize our high-impact recovery triggers with USDA subsidy release dates and regional harvest payouts. By the time the “elevator check” clears, Nexa has already positioned your invoice at the top of the farmer’s payables list.


The Nexa 4-Step “Harvest” Recovery Ladder

  1. Step 1: The Account Reconciliation (Fixed Fee). Best for accounts 30–60 days past due. We send professional, white-labeled notices that act as a “soft reminder” under your brand. The farmer pays you directly. You keep 100% of the money.

  2. Steps 2–4: Specialized Mediation (Contingency). For high-value, aged debt. Our mediators understand UCC-1 filings and Agricultural Liens. We resolve the debt through negotiation, avoiding the cost and mess of repossession whenever possible. No Recovery = No Fee.


Why Agricultural Creditors Trust Nexa

  • UCC-1 & PMSI Expertise: We ensure your security interest is protected against other banks or creditors. We verify lien positions to ensure you have the maximum leverage during mediation.

  • Seasonality Awareness: We don’t call farmers during the peak of harvest. We time our outreach for when the farmer is actually at their desk, ensuring a higher response rate and less community friction.

  • 50-State Licensing: Whether your customer is a local family farm or a multi-state corporate grower, we have the legal authority to recover your funds across state lines.


Recent Industry Recovery Results

  • Multi-County Implement Dealer: Recovered $160,000 in delinquent lease payments on high-horsepower tractors within 45 days.

  • Specialty Irrigation Dealer: A dealer was owed $65,000 for a custom pivot system. Nexa’s Step 1 service triggered payment in full within 42 days.

  • Short-Line Dealer: Reduced 90-day delinquency by 42% in one quarter, restoring $120,000 to the dealership’s operating budget.


Frequently Asked Questions (FAQ)

1. How do you handle “Pay-at-Harvest” terms?

We customize our recovery triggers to match your specific contract terms, ensuring we aren’t creating friction during the farmer’s busiest months while still securing your priority status.

2. Can you handle UCC-1 disputes with local banks?

Yes. Our mediators are trained in the Uniform Commercial Code and can effectively communicate your “super-priority” status to other creditors, often resulting in a faster settlement.

3. Will this damage my dealership’s local reputation?

No. We maintain a 4.85 Google Rating because we focus on professional mediation. We act as an extension of your office, resolving disputes rather than escalating them.

Need a Collection Agency? Contact us
Filed Under: Debt Recovery

Debt Collection Laws and Agencies in Germany

Several laws and guidelines regulate debt collection in Germany.

  1. Civil Code (BGB): This is the main body of private law in Germany. Debt collection falls under contract law, which is a part of the Civil Code. The code outlines the rights and obligations of creditors and debtors.
  2. Insolvency Law: If a debtor is unable to pay their debts, insolvency proceedings may be initiated. This is regulated by the Insolvency Code (InsO).
  3. Legal Services Act (RDG): This law regulates who can provide debt collection services. Debt collectors must be registered and approved under this act.
  4. Federal Data Protection Act (BDSG): This law restricts the way debt collectors can use personal data of debtors.
  5. Unfair Competition Law (UWG): This law protects consumers from unfair business practices, including in debt collection.

Debt collectors in Germany are required to follow these laws, which provide certain protections to debtors. For example, debt collectors cannot harass debtors, they must provide clear information about the debt, and they must respect privacy and confidentiality laws. Penalties for non-compliance can include fines and restrictions on operating.

In case of international debt collection cases, EU regulations may also apply, like the European Payment Order procedure, which simplifies the process of cross-border monetary claims. It’s recommended to consult with legal experts for detailed and updated understanding.

Top Collection Agencies in Germany

There are several debt collection agencies in Germany, each with its unique services and customer base.

  1. Euler Hermes: A major global credit insurance company that also offers collection services.
  2. Tesch Inkasso Forderungsmanagement GmbH: They provide full-service receivables management from one source, from credit checks to the judicial dunning process and even the monitoring of titles.
  3. Arvato Financial Solutions: A subsidiary of Bertelsmann, Arvato Financial Solutions offers services that include debt purchase, debt collection, and business information.
  4. EOS Group: A multinational company offering debt collection among other services.
  5. Creditreform: A collection agency with a strong presence in Germany that offers a range of services from credit rating to marketing and debt collection services.
  6. Bisnode Deutschland: A part of Dun & Bradstreet, Bisnode is a leading European Data & Analytics company that offers debt collection services.
  7. Klarna: While primarily a financial technology company, Klarna provides collection services for debts arising from its payment solutions.
  8. Intrum Justitia: A Sweden-based collections company with a strong presence across Europe, including Germany.
  9. LOWELL Group: Offering services across debt management and collections, data analytics and insight, and more.

Things to ask before you hire one:

Always conduct a thorough due diligence process before finalizing your choice to ensure the agency aligns with your business needs and ethical standards. Also ask for their policy on Legal Compliance, Reputation, References and Experience, Fee Structure, Customer Service and Reporting, Technology and Data Security and Client Reviews and Testimonials.

What can debt collectors do in Germany?

Debt collectors have a range of strategies to retrieve owed money, but their actions must comply with German law.

  1. Contact the Debtor: The debt collection agency will first attempt to contact the debtor, typically by sending a written notice. This letter will outline the debt, including its origin, the total amount owed, any late fees or interest, and a deadline for payment.
  2. Negotiation: Debt collectors may negotiate with the debtor, possibly offering payment plans or settlements.
  3. Legal Action: If the debtor doesn’t respond or refuses to pay, the debt collector can initiate legal proceedings. This generally starts with a “Mahnbescheid” (order for payment), which is an official request for payment. If the debtor still does not pay, the creditor may seek a “Vollstreckungsbescheid” (enforcement order), which allows for the seizure of assets or income.
  4. Seizure of Assets: If the debt is legally confirmed and the debtor still refuses to pay, the debt collector can request a bailiff to seize the debtor’s assets to satisfy the debt. Certain assets, like necessary household goods or a minimum level of income, are protected from seizure under German law.
  5. Credit Report: Unpaid debts can be reported to the SCHUFA (Germany’s main credit bureau), which can negatively impact the debtor’s credit rating and make it harder to get loans or credit in the future.
  6. Insolvency Proceedings: In extreme cases, if the debtor is unable to pay the debt, insolvency proceedings may be initiated. This can lead to a variety of outcomes, including debt relief, payment plans, or the liquidation of assets.

Throughout this process, debt collectors must respect the rights and privacy of the debtor. They are not allowed to use threatening or abusive language, disclose the debtor’s situation to third parties without consent, or contact the debtor during unreasonable hours. Penalties for violations of these protections can include fines and restrictions on operating.

Filed Under: Debt Recovery

What Can Debt Collectors Legally Do in the UK? (2025 Business Guide)

Last Updated: November 2025

For business owners and credit managers, the “debt collection” landscape in the UK is often misunderstood. There is a vast difference between a professional, FCA-compliant agency and the “heavies” of old.

With UK corporate insolvencies remaining near 30-year highs in 2025, waiting for payment is a risk you cannot afford. However, fearing that an agency might damage your reputation is a valid concern.

This guide provides a definitive, in-depth look at the legal powers of debt collectors in the UK, separating fact from fiction so you can recover your revenue with confidence.

1. Debt Collectors vs. Bailiffs: The Critical Distinction

Most confusion stems from mixing up these two distinct roles.

Debt Collectors (Pre-Legal)

  • Role: Hired by a creditor (or owning the debt) to recover money before court action.

  • Powers: Same legal standing as the original creditor. They rely on negotiation, persistence, and the threat of credit damage or legal escalation.

  • Right of Entry: None. They cannot force entry into a home or business.

Bailiffs (Enforcement Agents)

  • Role: Appointed after a court order (CCJ) has been granted and not paid.

  • Powers: Can remove goods (vehicles, stock, electronics) to sell at auction.

  • Right of Entry: Limited powers to use “reasonable force” (usually for criminal fines or tax), but for standard commercial debt, they can enter peacefully through unlocked doors.


2. What a Debt Collector Can Legally Do

Professional agencies operate under strict license, but they are effective because they are consistent and process-driven.

Contact You (Within Reason)

They can contact debtors via:

  • Telephone

  • Letter / Email

  • SMS / Text Message

  • The Rule: Contact must be at “reasonable times” and intervals. The FCA Handbook (CONC 7) generally defines “reasonable” as between 8:00 am and 9:00 pm.

Send “Field Agents” to a Property

A collector can send a representative to a debtor’s home or business to negotiate payment face-to-face.

  • The Limitation: This is a “doorstep collection” visit. The agent must leave if asked. They cannot put a foot in the door or push past a person.

Trace a Debtor

If a debtor has “done a runner” (skipped town), agencies use sophisticated credit bureau data, voter rolls, and employment tracing to locate them.

Add Interest and Charges

  • Commercial Debt: Under the Late Payment of Commercial Debts (Interest) Act 1998, they can legally add interest (base rate + 8%) and compensation fees (£40–£100 per invoice) to B2B debts.

  • Consumer Debt: They can only add charges if the original contract allowed for “collection costs.”

Issue a Default Notice

For regulated debts, they can issue a formal Default Notice. This stays on the debtor’s credit file for 6 years, severely damaging their ability to get a mortgage, car finance, or mobile contract.

Start Legal Proceedings

If negotiation fails, the agency can prepare the file for the County Court. A CCJ (County Court Judgment) is the ultimate leverage, as it legally validates the debt and opens the door to bailiff enforcement.


3. What They Strictly Cannot Do (The “Harassment” Line)

Crossing these lines is not just bad practice; it is often a criminal offense under the Administration of Justice Act 1970 (Section 40) and the Protection from Harassment Act 1997.

  • Force Entry: They cannot break windows, pick locks, or push past you.

  • Take Goods: They cannot clamp cars or seize laptops. Only a bailiff with a warrant can do this.

  • Contact Third Parties: They cannot tell a neighbour, family member, or partner about the debt (Privacy/GDPR breach).

  • Misrepresent Authority: They cannot use documents that look like court summonses if they are not. They cannot claim to be bailiffs.

  • Harass at Work: They can call a workplace to speak to the debtor, but they cannot reveal the debt to a receptionist or boss, and they must stop calling work if explicitly told it is not permitted by the employer.

  • Demand Payment After “Statute Barred”: If a debt is over 6 years old (5 in Scotland) and no contact/payment has been made, they cannot legally enforce it through the courts.


4. Key Regulations Governing the Industry (2025)

Citing these proves you are a compliant, modern agency.

The Debt Respite Scheme (Breathing Space)

This government scheme gives debtors legal protection for up to 60 days.

  • Standard Breathing Space: 60 days where creditors must pause all action and freeze interest/fees.

  • Mental Health Crisis Breathing Space: Lasts as long as the debtor is receiving crisis treatment, plus 30 days.

  • Agency Role: A professional agency monitors these periods and automatically reactivates collection the moment protection ends.

FCA Consumer Duty (2023/2024)

Firms must act to deliver “good outcomes” for retail customers. This means identifying vulnerable customers (e.g., those with dementia or severe financial distress) and treating them with forbearance rather than aggression.

Limitation Act 1980

Defines the time limits for debt (6 years for simple contracts). Professional agencies review portfolios to ensure they don’t waste time chasing unenforceable “statute barred” debts.


5. Common Debtor Questions (FAQ)

“Can a debt collector take my car?”

No. A debt collector cannot seize your vehicle. Only a bailiff (Enforcement Agent) can do this, and only after a court judgment (CCJ) has been issued and unpaid.

“Can they send me to prison?”

No. You cannot go to prison for not paying commercial invoices, credit cards, or loans in the UK. Prison is only a risk for non-payment of criminal fines or Council Tax (and even then, it is a last resort).

“Can they garnish my wages?”

Not directly. A debt collector cannot touch your wages. However, if they take you to court and get a CCJ, they can apply for an Attachment of Earnings Order, which instructs your employer to deduct money before it hits your bank account.


6. The 2025 Economic Landscape: Why Action Matters

The risk of bad debt is currently higher than it has been in decades.

  • Insolvency Rates: Corporate insolvencies in England and Wales are up ~17% year-on-year. When a company folds, unsecured creditors (like suppliers) usually get nothing.

  • The “Domino Effect”: The construction and retail sectors are seeing a wave of failures. If your client goes bust, you need to have already secured your cash.

  • Late Payments: The average B2B payment delay is now hovering around 38 days in the construction sector.

  • Inflationary Pressure: While inflation has cooled, the cost of doing business remains high. Debtors are holding onto cash to preserve their own liquidity—at your expense.


Conclusion: Protect Your Cash Flow Legally

Navigating the legal minefield of debt collection requires expertise. One wrong move—like calling too often or contacting a neighbour—can lead to heavy fines and reputation damage.

Our team specializes in high-compliance, high-recovery collections. We know exactly how far we can legally go to get you paid, ensuring your invoices move to the top of the pile without crossing the line.

Filed Under: Debt Recovery

Debt Collection in Australia

Debt collection in Australia is guided by a series of laws and practices designed to ensure that both parties involved in debt, the debtor and the creditor, are treated fairly.

  1. Australian Consumer Law: This law provides consumers with certain protections and rights. It includes provisions for misleading conduct, unfair practices, warranties, and guarantees. It also provides for dispute resolution.
  2. National Consumer Credit Protection Act 2009: This legislation is designed to protect consumers in relation to credit-related matters. Lenders and other credit providers must hold an Australian credit license and adhere to responsible lending conduct.
  3. The Privacy Act 1988: This Act provides guidelines on how personal information can be used by businesses and government agencies. This is particularly important in the context of debt collection, where personal information is often used.
  4. Debt Collection Guidelines: These guidelines, developed jointly by the Australian Securities and Investments Commission (ASIC) and the Australian Competition and Consumer Commission (ACCC), provide the debt collection industry with guidance on fair and appropriate behaviour when collecting debts. The guidelines cover the conduct of creditors and their agents and provide guidance on what constitutes harassment, the use of physical force, undue harassment or coercion for payment of debts.
  5. Bankruptcy Act 1966: This legislation governs the law of bankruptcy in Australia. It provides procedures for declaring bankruptcy and the consequences of bankruptcy.

These laws regulate how debts can be collected, who can collect them, and what methods they can use. Collection agencies are not allowed to harass or intimidate people who owe money and must respect privacy laws. If a person believes they are being treated unfairly by a debt collector, they can make a complaint to the ACCC or the ASIC.

What can Collection Agencies Do and Can’t Do

Debt collectors in Australia are regulated by both federal and state laws, and they have certain powers to collect unpaid debts. However, they must operate within the confines of the law. Here’s a general idea of what debt collectors can do in Australia:

  1. Contact You About the Debt: Debt collectors can contact you to request payment, explain the consequences of non-payment, offer to settle your account, or make alternative payment arrangements. They can contact you by phone, letter, email, social media, or face-to-face.
  2. Legal Action: If you refuse to pay a debt or can’t come to a repayment agreement, a debt collector can initiate legal action. This may include applying for a court order that demands payment of the debt.
  3. Bankruptcy Proceedings: If the debt is large enough, a debt collector can initiate bankruptcy proceedings against you.

However, the actions of debt collectors are also subject to restrictions under the law. For instance:

  • They should not contact you more than three times a week or ten times a month, and not outside of the hours of 7:30am to 9:00pm on weekdays and 9:00am to 9:00pm on weekends.
  • They should not contact you at your workplace if they know that your employer does not approve or if you ask them not to.
  • They must respect your wishes if you ask to be contacted in writing only (though in certain circumstances they may be able to contact you by phone).
  • They must not pursue you for a debt if you’ve requested evidence of the debt and they have not provided it.
  • They must not mislead you, harass you, or act unconscionably towards you.
  • They must not reveal information about your financial situation to others without your permission

Debtor’s Rights

  • Be treated respectfully and professionally.
  • Be informed about the details of the debt.
  • Have access to assistance if they are in financial hardship.
  • Make a complaint if they feel they are not being treated fairly.

Debt collection procedures often involve initially contacting the debtor to inform them of the debt and asking for payment. If the debtor is unable to pay, they may be able to negotiate a payment plan. If they still do not pay, the creditor may take legal action to recover the debt, which could result in the debtor’s property being seized, or in some cases, the debtor may be declared bankrupt.

In case your rights were violated then you may follow these steps.

Step 1: Contact the Creditor or Debt Collection Agency

Your first step should be to contact the creditor or the debt collection agency directly. It’s possible that the issue may be resolved through direct communication. Clearly explain your issue and provide any evidence you might have. Make sure to keep records of all communication.

Step 2: File a Complaint with AFCA

If your issue is not resolved satisfactorily through direct contact, you can file a complaint with the Australian Financial Complaints Authority (AFCA). AFCA provides fair and independent financial services complaint resolution that’s free to consumers.

You can submit your complaint online through the AFCA website or by calling them on 1800 931 678.

Remember to provide as much information as possible including details about your complaint, why you’re not satisfied with the outcome of your direct contact with the creditor or debt collection agency, and what outcome you’re seeking.

Step 3: Contact the ACCC

If the debt collector’s conduct has been particularly egregious, such as repeated harassment or intimidation, you can also report this conduct to the Australian Competition and Consumer Commission (ACCC). The ACCC regulates the conduct of debt collectors but note that they don’t resolve individual disputes.

You can contact the ACCC by calling their hotline at 1300 302 502 or filling out the complaint form on their website.

Step 4: Legal Action

If your issue still remains unresolved after these steps, you may need to consider legal action. This can be a complicated process, and it would be a good idea to consult with a legal professional or a financial counsellor before proceeding. Various community legal centres around Australia may be able to provide free or low-cost advice.

There may have been changes or developments in these laws It’s recommended to seek legal advice if you find yourself involved in a debt collection process.

Top Collection Agencies in Australia

  1. Milton Graham (formerly Dun & Bradstreet): Milton Graham has a long history of operations in Australia and offers a wide range of services including debt recovery and credit reporting.
  2. ARL Collect Pty Ltd (formerly known as Receivables Management Group): ARL Collect provides a full suite of receivable management solutions including debt purchasing, debt sale, and contingency collections.
  3. Collection House Limited: An Australian-based company offering debt collection services, receivables management, and debt purchasing.
  4. Lion Finance (part of the Collection House Limited group): Lion Finance is a large debt acquisition and collections company.
  5. Credit Corp Group: This is one of the largest debt collectors and buyers of debt in Australia.
  6. Baycorp: Baycorp is a leading player in the Australian and New Zealand debt collection industries.
  7. Probe Group: Probe Group provides a broad range of outsourcing services including debt collection.
  8. Prushka Fast Debt Recovery: An Australian-owned company that provides no recovery, no charge debt collection services.
  9. EC Credit Control: Offering debt recovery services, EC Credit Control also provides services around terms of trade and credit management.
  10. AMPAC Debt Recovery: AMPAC offers comprehensive commercial debt recovery services across Australia.

Each of these companies has a slightly different focus and different strengths, and they all operate within the legal frameworks provided by Australian law.

Remember to always do your own research when choosing a debt collection agency to work with, to ensure that the agency is reputable, treats debtors fairly, and complies with all applicable laws and regulations.

Filed Under: Debt Recovery

Navigating Canada’s Debt Collection Landscape: Laws, Ethics and Regulations

Managing accounts receivable in Canada requires more than a standard outreach strategy. The Canadian market is governed by a patchwork of federal and provincial regulations that prioritize consumer privacy and fair treatment. For businesses operating in Current, staying updated on shifting interest caps and new federal health benefits is essential to maintaining cash flow without risking legal penalties.

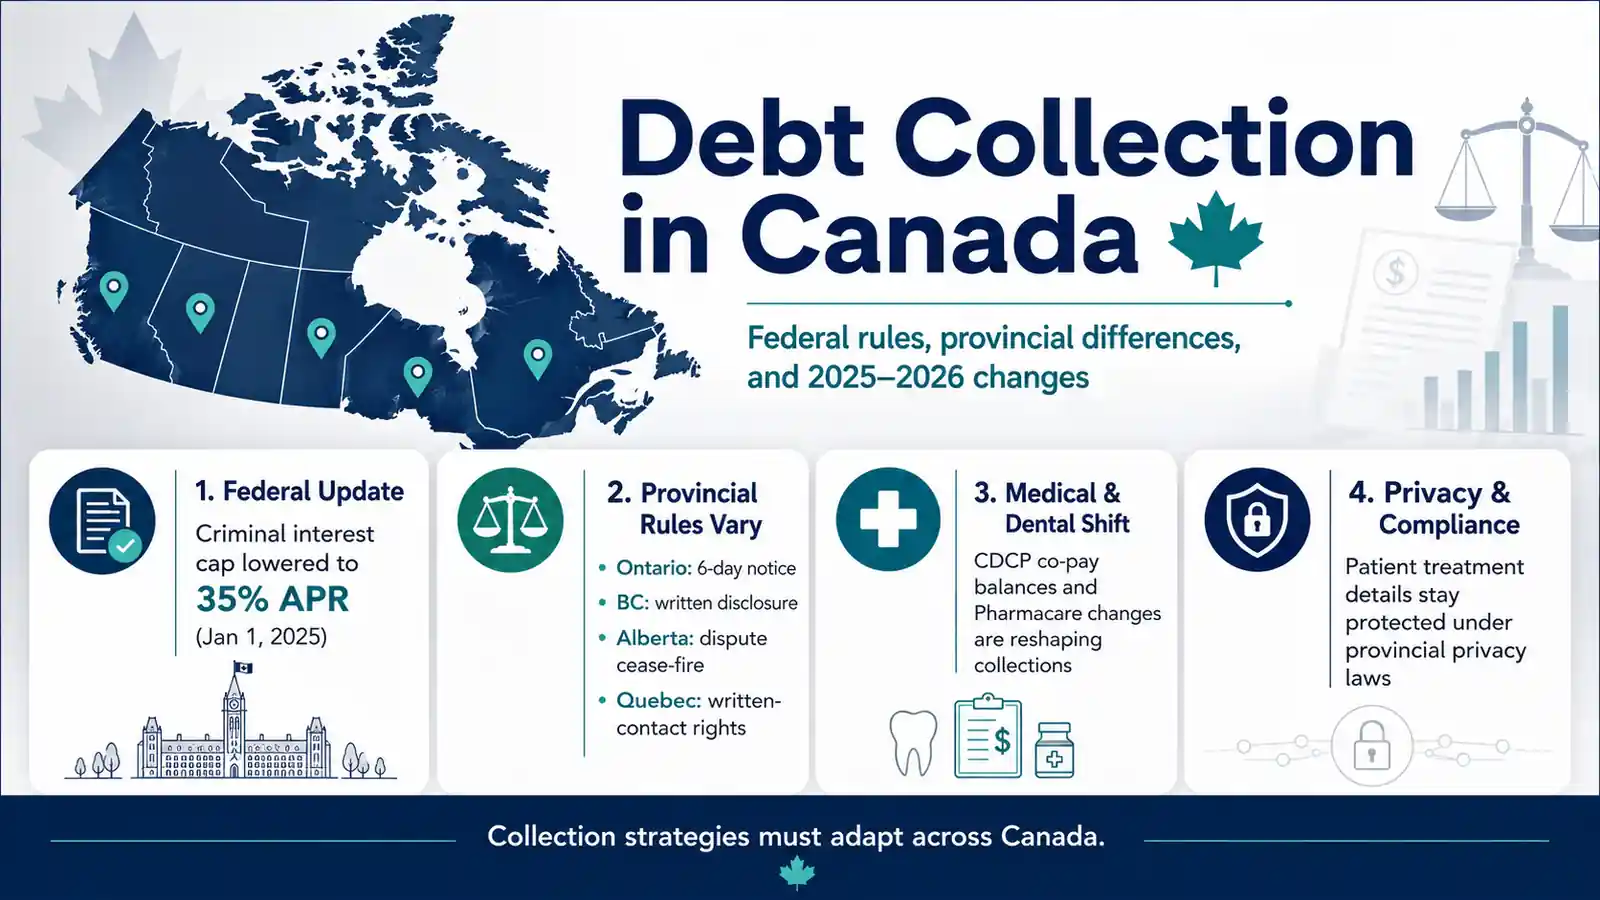
Debt collection in Canada infographic showing federal rules, provincial differences, medical debt changes, privacy requirements, and 2026 compliance updates.


The Federal Foundation: The Bank Act & Criminal Code

While most collection rules are provincial, federal law sets the absolute ceiling for what is legal across the country.

  • The Bank Act: This act governs all federally regulated banks. It mandates “Responsible Business Conduct,” meaning banks and their representatives cannot use threatening or coercive language. They are also strictly limited in contacting a debtor’s family or employer—usually only once to confirm location—unless explicit consent is given.

  • New 2025 Interest Rate Cap: As of January 1, 2025, Canada significantly lowered the “criminal interest rate.” The previous effective annual rate of 60% has been reduced to a 35% Annual Percentage Rate (APR). Offering or advertising credit above this rate is now a criminal offense, and collection efforts on debt with “usurious” interest can be legally challenged.

  • Payments Canada & The RPAA: New regulations under the Retail Payment Activities Act (RPAA) in late 2025 have increased oversight on payment service providers. This ensures that when debt is paid electronically, the funds are safeguarded and handled with higher transparency than in previous years.


Provincial Legislation: A Region-by-Region Breakdown

Because the day-to-day “rules of the road” are determined provincially, a recovery strategy must adapt as it crosses provincial borders.

Ontario: Collection and Debt Settlement Services Act

Ontario is a highly regulated environment requiring all agencies and individual collectors to be registered with the province.

  • The 6-Day Rule: Agencies must send a written notice and wait 6 days before the first phone call.

  • Contact Limits: Successful contact is limited to three times in a seven-day period.

  • New for 2026: Increased administrative penalties now allow the Registrar to levy significant fines against agencies that use “unregistered” collectors or misleading “legal-looking” documents.

British Columbia: Business Practices and Consumer Protection Act

BC law emphasizes transparency through the Debt Collection and Repayment Regulation.

  • Written Disclosure: Before any verbal contact, a collector must provide a written notice with a full breakdown of the amount owing.

  • No-Cost Contact: Collectors cannot contact a debtor in any way that costs the debtor money (such as collect calls or specific cellular data charges).

Alberta: Consumer Protection Act & Fair Trading Act

Alberta combines the Fair Trading Act with the Collection and Debt Repayment Practices Regulation.

  • Prohibited Hours: Contacts are restricted to 7:00 AM – 10:00 PM (Mon–Sat) and 1:00 PM – 5:00 PM on Sundays.

  • Dispute Cease-Fire: If a debtor notifies an agency in writing that the debt is in dispute and they wish to be taken to court, the agency must stop all collection activity immediately.

Quebec: An Act Respecting the Collection of Certain Debts

Quebec’s Civil Law system is unique.

  • Physical Presence: Agencies must have an office in Quebec to collect consumer debt.

  • Written-Only Request: A debtor can request in writing to be contacted only in writing. This must be honored for three months.

  • Bill 72 (2024/2025): New stricter consumer lending rules require more transparent disclosure of credit limits and prohibit certain “tipping” prompts or unsolicited credit offers during the debt reconciliation process.


Medical & Dental Debt: The 2026 Shift

The nature of medical debt in Canada has changed due to the rollout of the Canadian Dental Care Plan (CDCP) and the National Pharmacare Act.

  1. The “Co-Payment” Trap: While the CDCP covers millions of Canadians as of Current, it often only covers a portion of the fee grid. Patients with household incomes between $70k and $90k are responsible for 40% to 60% co-payments. This has created a surge in “micro-debts” for dental practices that were previously unaccustomed to collections.

  2. Pharmacare & Uninsured Services: With the expansion of free contraception and diabetes medications in many provinces, medical debt is shifting toward “ancillary” costs like delivery fees, prescribing fees, or non-covered specialized medications.

  3. Privacy Standards: Provincial acts like Ontario’s PHIPA or Alberta’s HIA remain the “gold standard.” A collector can see that a balance is owed to a clinic, but they are legally barred from knowing what the treatment was.


Statute of Limitations & The “Reset” Rule

In most provinces (ON, BC, AB), the window to sue for a debt is 2 years from the date of the last payment or written acknowledgement.

  • The “Reset”: If a debtor makes even a $1 payment or sends a text/email acknowledging the debt, the 2-year clock restarts.

  • Post-Statute Ethics: Even if the 2-year window has expired, the debt still exists. However, the Current 2026 guidelines emphasize that threatening legal action on an expired debt (time-barred debt) is a major regulatory violation.


Frequently Asked Questions

Can a collector call my mobile phone?
Yes, but if you inform them that you are being charged for the call or that it is a workplace-issued phone, they must offer an alternative method of communication in most provinces.

What happens if I live in a different province than the creditor?
The laws of the province where the debtor resides generally apply. If a BC company is collecting from an Ontario resident, they must follow Ontario’s 6-day notice rule and contact frequency caps.

Are robocalls legal for debt collection?
Under CRTC (Telecommunications Act) rules, automated “ADAD” calls for the purpose of solicitation are strictly regulated. While debt collection has some exemptions, many provinces require a “live” person to be available immediately upon the debtor answering.

Filed Under: Debt Recovery

Debt / Loan Collection Laws of India

Various laws and regulations govern debt collection (or loan recovery) in India. Always consult with a legal professional for the most accurate information. 

In India, debt collectors and financial institutions sometimes cross that legal line and tend to become over-aggressive. This is partly because the Indian legal system is a slow than its Western counterparts. For example, in USA, a lawyer can get a civil judgment from the court in a matter of months. However in India, we are talking years to get a case resolved. Lengers can therefore become restless and choose to take the aggressive (illegal) route.

  1. Insolvency and Bankruptcy Code, 2016 (IBC): The IBC provides a consolidated framework for the insolvency of companies, partnership firms, and individuals. It’s a unified law that replaces multiple existing laws. It aims to resolve insolvency in a time-bound manner.
  2. The Recovery of Debts Due to Banks and Financial Institutions Act, 1993 (RDDBFI Act): This law establishes tribunals for expeditious adjudication and recovery of debts due to banks and financial institutions.
  3. The Securitisation and Reconstruction of Financial Assets and Enforcement of Security Interest Act, 2002 (SARFAESI Act): This law allows banks and other financial institutions to auction residential or commercial properties to recover loans. The Act does not apply to unsecured loans, loans below ₹1,00,000, or where the remaining debt is below 20% of the original principal.
  4. The Companies Act, 2013: This law governs the functioning of companies in India and includes provisions for the recovery of debts by companies.
  5. Reserve Bank of India (RBI) Guidelines: The RBI, India’s central banking institution, has issued guidelines for the recovery of debts by banks and financial institutions, and these guidelines bind these institutions.
  6. Limitation Act, 1963: This law sets the limitation period for various types of lawsuits, including for recovering debts. If a debt is not recovered within the limitation period, it may become unenforceable.

These are some of the primary laws and regulations that govern the recovery of debts in India. They are designed to ensure that the process of debt recovery is fair, equitable, and conducted in a manner that respects the rights of all parties involved.

The actual process of debt collection can be complex and varies depending on the type of debt, the type of debtor (individual, partnership firm, company etc.), the amount of debt, the age of the debt, and other factors. It can involve going to court, negotiating settlements, or potentially even invoking insolvency or bankruptcy proceedings.

What Indian Loan Recovery Agents cannot do!

The Reserve Bank of India (RBI), has issued certain guidelines for debt collection that banks and other financial institutions are expected to adhere to.

  1. Harassment: Debt collectors should respect the privacy of debtors. Harassment, such as persistent phone calls, use of abusive language, or making false and misleading statements is prohibited.
  2. Undue Pressure: Debt collectors cannot use undue pressure or unfair practices to recover debts. This could include threatening legal action without proper grounds or authority.
  3. Contacting at Odd Hours: As per the guidelines issued by the RBI, debt collectors are typically prohibited from contacting debtors at odd hours. Contact with the debtor should usually be limited to a specified time slot agreed upon.
  4. Misrepresentation: Debt collectors cannot misrepresent or provide false information, either about their own identity, or about the debt, such as the amount owed, legal status of the debt, etc.
  5. Contacting Third Parties: Debt collectors are usually not allowed to disclose information about the debtor’s debt to third parties without the debtor’s consent.
  6. Invasion of Privacy: Violating the privacy of a debtor is not permitted. This includes practices like public shaming, publishing the debtor’s name in “defaulters’ lists” without legal authority, etc.
  7. Unfair Treatment: Debt collectors cannot treat a debtor unfairly on grounds of gender, caste, religion, or other protected characteristics.

These guidelines are intended to protect the rights of debtors and ensure ethical practices in debt collection. Failure to adhere to these guidelines could result in penalties for the financial institution employing the debt collector.

It’s important to note that specific circumstances might lead to different interpretations of what is permissible and what is not. Always refer to the most updated guidelines or legal consultation for precise information.

Filed Under: Debt Recovery

  • « Go to Previous Page
  • Page 1
  • Interim pages omitted …
  • Page 15
  • Page 16
  • Page 17
  • Page 18
  • Page 19
  • Interim pages omitted …
  • Page 55
  • Go to Next Page »

Primary Sidebar


accounts receivable

Need a Collection Agency?
Kindly fill this form.
We’ll get in touch with you

    Please prove you are human by selecting the truck.

    Compliance & Security

    • SOC 2 Type II Certified: Third-party audited data security and strict privacy controls.

    • HIPAA Compliant: Secure, legal processing of medical and municipal EMS accounts.

    • PCI-DSS Level 1: Highest tier of data encryption for secure payment processing.

    • FDCPA & FCRA Aligned: Full legal adherence to federal consumer protection laws.

    Recent Posts

    • Why Dental Patients Dispute Bills: The Nexa Collections Dental Account Dispute Index
    • 2027 Commercial Collections Benchmark: U.S. Late Payments, AR Risk and B2B Collection Trends
    • Bulk Account Placement: What a Collection Agency Actually Needs From You
    • Nationwide Debt Collection Agency Serving U.S. Cities
    • Chula Vista Collection Agency for Medical, B2B, Schools & Business Debt
    • Corpus Christi Collection Agency: Itemized Bill Rules for Practices
    • Riverside Collection Agency | For Logistics, Medical, Schools & Business Recovery
    • Collection Agency for Large Balances: High-Value B2B Debt Recovery

    Featured Posts

    • Impact on Power Grids due to El Nino
    • Addressing the Common AR Issues of Preschools
    • Negative Impact on U.S. Providers when Patients Go Abroad

    Copyright © 2026 NEXACOLLECT.COM | This content is provided for general informational purposes only and should not be considered legal advice. Collection laws and requirements may vary by state, account type, documentation, debtor status, and specific facts. Please consult qualified legal counsel for guidance regarding your particular situation. Nexa and its authorized collection partners service accounts in accordance with applicable federal and state collection requirements. Visit our home page to know more about us.

    X
    Need a Collection Agency?
    Contact Us