• Skip to main content
  • Skip to primary sidebar

Nexa Collections

  • Home
  • Serving
    • Medical
    • Dental
    • Small Business
    • Large Business
    • Commercial Collections
    • Government
    • Utilities
    • Fitness Clubs
    • Schools
    • Senior Care Facility
  • Contact Us
    • About us
    • Cost

Debt Recovery

Common Debt Collection Mistakes

Collecting unpaid bills is a crucial function for most businesses, especially for those in the credit, utilities, and medical sectors. However, there are common mistakes that employees make during the collection process which can impact the effectiveness of the recovery and even lead to legal issues. Here’s a list of such mistakes:

  1. Not Verifying Details: Before initiating any collection activity, it’s vital to ensure that the debt details are correct. Mistakes in the amount, identity of the debtor, or the details of the transaction can lead to disputes.
  2. Lack of Documentation: Not maintaining proper and detailed records of all communications with the debtor can be problematic, especially if there are disputes or if legal action becomes necessary.
  3. Harassment: Some collectors may become aggressive or overly persistent. This can not only damage the reputation of the company but also be illegal in many jurisdictions.
  4. Ignoring Disputes: Sometimes, the debtor may have genuine reasons to dispute the debt. Not addressing these disputes or not providing evidence can jeopardize the recovery process.
  5. Violating Laws: Different countries and states have specific laws related to debt collection. Examples include the Fair Debt Collection Practices Act (FDCPA) in the United States. Ignorance or violation of these laws can lead to penalties.
  6. Not Offering Payment Plans: Sometimes, debtors might be willing to pay but are unable to pay the full amount at once. Not offering flexible payment options can make collection more challenging.
  7. Poor Communication Skills: Being rude, confrontational, or not listening can make the debtor less cooperative.
  8. Not Keeping Updated on Account Status: Trying to collect on an account that has already been paid or settled due to an oversight can frustrate debtors and harm credibility.
  9. Neglecting to Follow Up: If a debtor promises to pay by a certain date or in a certain manner and then doesn’t, timely follow-up is essential.
  10. Using Unclear Language: When communicating, it’s crucial to be transparent and clear about what is owed, the consequences of non-payment, and any potential solutions.
  11. Not Protecting Personal Data: Confidentiality is crucial. Sharing or mishandling a debtor’s personal information can lead to breaches of privacy laws.
  12. Relying Solely on Phone Calls: In today’s digital age, there are multiple ways to reach out, including emails, texts, and more. Not diversifying the methods of communication might reduce the effectiveness of the collection efforts.
  13. Not Recognizing When to Write Off or Escalate: Sometimes, the cost of pursuing a debt may exceed the amount to be recovered. Recognizing when to write off a debt or escalate it to a collection agency or legal team is essential for effective debt management.
  1. Lack of Training: Collection is not just about demanding payment. Proper training on communication techniques, negotiation skills, and the legalities involved is crucial. Without this, employees might be ill-equipped to handle complex scenarios.
  2. Not Prioritizing Debts: Not all debts are of the same value or have the same likelihood of recovery. Not segmenting and prioritizing them can lead to misallocation of resources.
  3. Inflexibility: While it’s essential to be firm, there are situations where a bit of flexibility can lead to better outcomes. For instance, understanding a debtor’s genuine hardships and offering temporary leniencies can sometimes facilitate future payments.
  1. Ignoring the Root Cause: Instead of only focusing on the unpaid bills, it’s helpful to understand why the customer hasn’t paid. This can offer insights for the business on areas of improvement.
  2. Failure to Use Technology: Automated systems, reminder setups, CRM tools, and analytics can significantly aid the collection process. Not leveraging technology can make the process inefficient.
  3. Not Documenting Promises: When a debtor commits to a payment date or a plan, it’s crucial to document this. This not only acts as evidence but also as a reference for future communications.
  4. Neglecting to Build Relationships: While the primary goal is to collect unpaid bills, building a positive rapport with debtors can be beneficial. A good relationship can lead to easier negotiations and even future business opportunities.
  5. Using Misleading Tactics: Some collectors may use deceptive practices, like misrepresenting the amount owed or falsely claiming legal actions will be taken. Such tactics can backfire and lead to legal complications.
  6. Not Reviewing Feedback: Sometimes, debtors provide feedback on the billing system, communication clarity, or even product or service dissatisfaction. Ignoring this feedback can mean missed opportunities for improvement.
  7. Setting Unrealistic Targets: Setting overly aggressive collection targets can pressure employees to use shortcuts or unapproved tactics. It’s crucial to balance between recovery objectives and ethical practices.
  8. Lack of Regular Audits: Regular internal audits of the collection process can help identify weaknesses, potential violations, or areas of improvement. Skipping these can lead to persistent issues.
  9. Ignoring Soft Skills: Empathy, active listening, and patience are as important as knowing the collection procedures. Disregarding the significance of these soft skills can lead to strained debtor relationships.

By avoiding these mistakes and focusing on clear communication, empathy, and understanding, collectors can enhance their effectiveness and maintain a positive relationship with their customers.
Filed Under: Debt Recovery

Debt Recovery Strategies for Utility Companies

Biggest Recovery Challenges of Utility Companies

Utility companies face a myriad of challenges when trying to recover unpaid bills. Addressing these challenges requires strategic planning, understanding of customer behavior, and regulatory adherence. Here are some of the most prominent challenges:

  1. Economic and Financial Challenges:
    • Recessionary Periods: During economic downturns, many customers might face financial hardships, leading to a surge in unpaid bills.
    • Rising Costs: As operational and resource costs increase, utilities might need to increase their tariffs, leading to customer resistance and potential non-payment.
  2. Regulatory and Compliance Issues:
    • Legal Restrictions: There might be legal limits on actions utility companies can take, such as disconnection limitations.
    • Consumer Protection Laws: These can limit aggressive recovery tactics, ensuring that consumers are not unduly harassed or treated unfairly.
  3. Operational Constraints:
    • Inadequate Systems: Outdated billing and customer management systems might not be efficient in tracking unpaid bills or setting up timely alerts.
    • Limited Staffing: Recovery departments might be understaffed, affecting their efficiency.
  4. Customer Behavior and Perceptions:
    • Unintentional Oversights: Sometimes, customers might simply forget or overlook a bill.
    • Willful Defaults: Some customers intentionally avoid paying, either due to disagreements or hoping to exploit system inefficiencies.
    • Perceived Injustice: If customers feel that they’re being charged unfairly or erroneously, they might resist payment.
  5. Communication Barriers:
    • Ineffective Communication: Bills, reminders, or warnings that are not clearly communicated can result in non-payment.
    • Language and Cultural Differences: Especially in diverse regions, language or cultural barriers might hinder effective communication.
  6. Infrastructure Challenges:
    • Outdated Infrastructure: Aging infrastructure might lead to inaccuracies in meter readings or bill calculations.
    • Remote Areas: Inaccessible or remote locations might hinder meter reading or bill delivery, leading to delays or disputes.
  7. Fraud and Tampering:
    • Customers might tamper with meters or employ other fraudulent methods to reduce or eliminate their bills, leading to revenue losses.
  8. Alternative Energy Sources:
    • With the rise of decentralized and renewable energy sources like solar panels, some customers might rely less on the grid, complicating billing and recovery processes.
  9. Data Privacy and Security Concerns:
    • Utility companies need to ensure that customer data is protected, especially when engaging third-party collection agencies, to avoid potential breaches and legal consequences.
  10. Negative Publicity and Reputation Damage:
    • Aggressive recovery measures or perceived unfairness can lead to negative publicity, affecting a company’s reputation and customer trust.

Need a Collection Agency? Contact Us

Addressing these challenges requires a multi-faceted approach, including updating infrastructure, refining communication strategies, enhancing customer service, and ensuring compliance with all regulatory requirements.

Best Debt Recovery Strategies for Utility Companies

Ensuring effective debt recovery is crucial for utility companies to maintain a healthy cash flow and ensure continued provision of essential services. Achieving this requires striking a balance between firmness and understanding, and ensuring consistent compliance with regulatory requirements. Below are strategies that utility companies can implement to improve compliance and optimize recovery rates during the debt recovery process:

  1. Enhanced Data Management and Analytics:
    • Utilize sophisticated data management systems to maintain accurate records of customers’ payment histories.
    • Implement predictive analytics to identify potential defaulters in advance and customize recovery approaches accordingly.
  2. Transparent Communication:
    • Clearly communicate payment terms, due dates, and consequences of non-payment to customers from the outset.
    • Establish regular reminders through various communication channels, such as SMS, email, and phone calls, as due dates approach.
  3. Flexible Payment Options:
    • Offer various payment methods such as direct debits, online transfers, mobile payments, and payment plans to accommodate customers’ preferences and financial situations.
    • Consider implementing installment plans or deferred payment options for customers facing genuine financial difficulties.
  4. Empathy and Customer-Centricity:
    • Train recovery agents to approach customers with empathy, understanding that some may be facing genuine financial hardships.
    • Encourage agents to listen to customers’ concerns, offering solutions that can help them meet their obligations without further distress.
  5. Regular Training and Skill Enhancement:
    • Continually train recovery staff on best practices, regulatory compliance, and soft skills.
    • Ensure that staff understands the legal and regulatory frameworks governing debt recovery in the utility sector.
  6. Strengthening Feedback Mechanisms:
    • Create avenues for customers to provide feedback on the recovery process.
    • Use feedback to refine and improve recovery strategies and to ensure fair treatment of all customers.
  7. Collaboration with External Entities:
    • Partner with credit bureaus to get a comprehensive understanding of a customer’s creditworthiness.
    • Engage reputable third-party collection agencies when internal recovery efforts are unsuccessful. Ensure these agencies uphold the company’s values and adhere to regulatory standards.
  8. Regular Compliance Audits:
    • Periodically review and audit the recovery processes to ensure they are in line with industry regulations and best practices.
    • Address any identified gaps or shortcomings promptly to maintain the integrity of the recovery process.
  9. Utilizing Advanced Technologies:
    • Employ technologies like artificial intelligence and machine learning to refine customer segmentation, optimizing recovery strategies for different customer segments.
    • Use automation for repetitive tasks, allowing human agents to focus on complex cases and fostering customer relationships.
  10. Transparent Reporting:
    • Maintain a transparent reporting system where stakeholders can track recovery rates, compliance breaches, and other relevant metrics.
    • Use these insights to make informed decisions and strategy adjustments.

By implementing these strategies, utility companies can ensure that their debt recovery processes are efficient, compliant, and respectful of their customers’ circumstances.

Filed Under: Debt Recovery

Toledo Debt Collection for Manufacturing, Healthcare & Local Organizations

Toledo still earns the name “Glass City”—but today the invoices behind that economy can involve solar glass, auto parts, hospital care, freight, construction, and professional services.

A past-due account from a manufacturer near the I-75 corridor is not the same problem as a patient balance, a contractor invoice, or an unpaid municipal utility account. The paperwork, legal timing, and relationship risk can all be different.

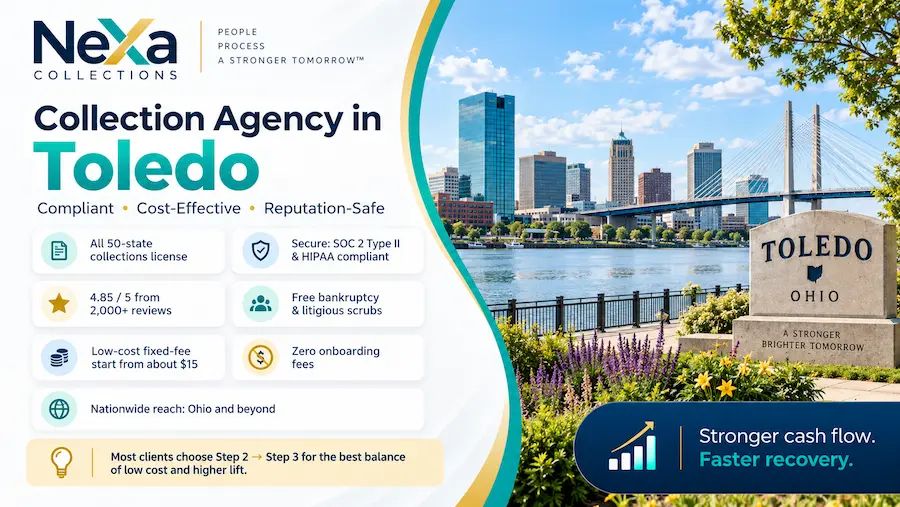
Nexa helps Toledo organizations recover those balances with a reputation-safe strategy matched to the account: $15 fixed-fee options for fresher receivables, 40% contingency recovery for tougher accounts, HIPAA-conscious healthcare workflows, and documentation-first B2B collections.

The idea is not to make collections louder. It is to make recovery smarter—before an unpaid invoice becomes a write-off.

Toledo is currently investing heavily in advanced glass, solar technology, EV-related manufacturing and industrial development, making that industrial positioning especially relevant rather than decorative.

Toledo Ohio skyline across the Maumee River and Glass City riverfront representing healthcare, manufacturing and B2B debt recovery

Nexa provides a reputation-safe approach, equipped with all 50-state collections license, offering free credit reporting, free litigious debtor check, free bankruptcy scrub, and zero onboarding fees. Secure – SOC 2 Type II & HIPAA compliant. Over 2,000 online reviews rate us 4.85 out of 5. 

Need a Collection Agency? Contact us


Our 4-Step Toledo Recovery System (Built to Protect Your Name)

We use a structured, compliant system that fits how Toledo businesses operate today—whether you’re near the University of Toledo, downtown offices by the Maumee River, or in the suburbs.

Step 1 – First-Party Reminder Service – $15 per account
We act as an extension of your team using your branding tone.

  • Gentle, professional reminders

  • Ideal for newer accounts before relationships sour

  • Helps your staff stretch further without hiring more people

Step 2 – Third-Party Demands – $15 per account
Now our name and process step in more visibly.

  • Firm, compliant letters and contacts

  • Often enough to move “stuck” accounts to resolution

  • Most clients start with Step 2, then move the remaining balance to Step 3

Step 3 – Contingency Recovery – 40% fee
You only pay when we collect.

  • No upfront cost on these accounts

  • Ideal for older, tougher balances

  • Designed to maximize recovery while respecting patients and customers

Step 4 – Legal Path – 50% fee
For select accounts where legal action makes sense.

  • Attorney review and, where appropriate, litigation

  • Used carefully and strategically, not by default

At every step, we run free bankruptcy and litigious checks so you don’t waste time throwing good money after bad.

We work across all 50 states, so if your Toledo customers move to Michigan, Florida, or anywhere else, your recovery strategy doesn’t fall apart.


Why This Model Works So Well in Toledo

Toledo’s mix of healthcare systems, industrial suppliers, small retailers, professional offices, and service businesses means you may be:

  • Dealing with high-volume, lower-balance invoices

  • Serving patients or customers who still leave reviews even when they’re past due

  • Working with people who often face real financial stress

Our approach helps you:

  • Keep legal and regulatory risk low while still pushing for payment

  • Protect your Google and online reputation by using respectful, compliant communication

  • Free up internal staff from repetitive chasing so they can focus on live patients, guests, or customers

  • Use fixed-fee Steps 1 & 2 for cost control, and contingency Steps 3 & 4 where risk is higher


Recent Recoveries

Dental Laboratory — Fixed-Fee | 94% Recovered

A Toledo-area dental lab placed $7,900 in fresher practice balances. Fixed-fee follow-up recovered $7,426 — 94%.

Dental Collection Services

Industrial Coatings Supplier — Contingency | 84% Recovered

A Northwest Ohio supplier assigned $36,500 in older manufacturing invoices involving delivery and approval disputes. Documentation-led recovery returned $30,660 — 84%.

Commercial B2B Collections

Fitness & Training Company — Contingency | 68% Recovered

A regional fitness provider placed $18,750 in documented membership and program balances. Structured recovery produced $12,750 — 68%.


Quick Snapshot: Ohio Debt-Collection Rules (Plain English)

We work within federal and Ohio rules so you don’t have to worry about hidden compliance landmines:

  • No harassment or deception – The federal Fair Debt Collection Practices Act (FDCPA) bans abusive, unfair, or misleading tactics.

  • Ohio Consumer Sales Practices Act (CSPA) – Adds state-level protections against unfair or unconscionable practices in consumer transactions, including certain collection behaviors.

  • Time limits to sue (statute of limitations) – For most consumer debts in Ohio, the window to file a lawsuit is about six years from when the debt became overdue or from the last payment, depending on the contract type.

  • Wage garnishment limits – In many cases, only up to 25% of disposable wages can be garnished, and only after a court judgment.

We keep your program aligned with these rules so you can recover more without stepping into regulatory trouble.


Who We Help in and Around Toledo

We support a wide range of organizations in Toledo, Lucas County, and nearby communities:

  • Healthcare & dental practices (including hospital-affiliated clinics and specialty groups)

  • Optometry, therapy, and allied health providers

  • Small and mid-sized manufacturers and distributors

  • Property managers & housing providers

  • Professional services – law, accounting, IT, marketing

  • Trade schools, private education, and training centers

Whether you’re near Franklin Park Mall, downtown, or on the edge of the metro, our process is built to fit both high-volume and boutique operations.


Frequently Asked Questions:

Should a Toledo hospital check HCAP eligibility before treating a low-income patient balance as collectible?

Yes. Ohio’s Hospital Care Assurance Program (HCAP) can make certain hospital balances noncollectible from qualifying patients.

Covered hospitals must provide basic, medically necessary hospital-level services without charge to Ohio residents who are not Medicaid recipients and whose income is at or below the federal poverty line. Ohio also requires hospitals that bill first to maintain procedures for determining eligibility and canceling charges when the patient qualifies.

That makes eligibility screening important before a patient account moves into outside recovery. Insurance, Medicaid eligibility, HCAP qualification, charity care, payment arrangements and genuine patient responsibility should be separated first.

See Nexa’s Hospital Collection Services.

A Toledo auto or glass supplier has a signed purchase order. Does that automatically give it six years to sue for an unpaid invoice?

Not necessarily.

Ohio generally provides six years for written contracts, but a contract involving the sale of goods can fall under Ohio’s UCC, which generally provides a four-year limitations period. The parties may even agree to shorten the UCC period to as little as one year, although they cannot extend it beyond four.

That distinction is particularly relevant to Toledo’s auto-parts, glass, solar, materials and manufacturing supply chains.

Before an aging B2B account is placed, preserve the purchase order, supply agreement, invoices, delivery documentation, warranties, receiving records and payment history rather than assuming “written contract = six years.”

See Commercial B2B Collection Services.

What should a Toledo manufacturer send when the buyer says parts failed inspection or did not meet specifications?

Start with the quality trail, not just the invoice.

Useful records can include the purchase order, engineering specifications, quote, certificate of analysis or conformity, inspection reports, receiving records, delivery confirmation, rejected-material reports, RMA documents, corrective-action correspondence, approved deviations, change orders and emails showing whether the customer accepted or used the goods.

This matters especially in Toledo’s manufacturing economy, where automotive, glass, advanced materials and industrial suppliers frequently work through detailed specifications and acceptance procedures.

The collection question becomes:

Was there a documented product-performance dispute—or did a quality complaint become an excuse to hold an otherwise valid invoice?

Commercial Collection Services

How quickly can a Toledo contractor lose Ohio mechanics-lien rights?

Faster than many contractors expect.

For a qualifying one- or two-family dwelling or residential condominium unit, Ohio generally requires the mechanics-lien affidavit within 60 days after the claimant’s last labor or materials.

For most other qualifying construction improvements, the deadline is generally 75 days. The separate 120-day period in Ohio law applies to specified oil-and-gas work rather than ordinary Toledo construction projects.

Sending an invoice to collections does not stop those deadlines. Contractors can pursue the receivable while separately preserving any lien rights that may still exist.

Contractor Collection Services

Can unpaid Toledo water, sewer, storm-water or refuse charges become a lien on the property?

Yes.

The City of Toledo states that delinquent water, sewer, storm-water and refuse charges may become a property lien and may be subject to collection activity. The City also applies a 5% late fee to past-due balances and provides an appeals process for disputed utility charges; customers generally have 30 days after the initial dispute to initiate that appeal.

For property transfers, the City specifically tells buyers to verify unpaid utility charges or liens before closing.

For any utility placement, keep the service address, account-holder record, meter dates, final bill, payments, dispute history and move-in/move-out information together.

Utility Collection Services

Toledo Public Schools already serves breakfast and lunch at no cost. What school balances can still become receivables?

For Toledo Public Schools, regular breakfast and lunch are currently no cost for elementary and high-school students. The district also says high-school à la carte purchases cannot be charged to an account.

So a Toledo education provider should not automatically treat “school debt” as cafeteria debt.

Depending on the institution and applicable policies, other receivables may include private-school tuition, extended-day programs, training-course fees, damaged or unreturned devices, transportation charges, housing, uniforms or other documented contractual obligations.

Separating those categories before placement produces a cleaner recovery file and reduces the chance of applying the wrong collection process.

School Collection Services


Ready to Stop Letting Past-Due Accounts Run Your Day?

If your receivables feel like they’re stuck on a permanent backup on I-475, it’s time to switch to a more efficient system.

Contact us today to review your Toledo A/R and design a Step 1–4 plan that fits your risk, your patients or customers, and your growth goals:

Filed Under: Debt Recovery

A Good Medical Collection Agency: Licensed in all 50 States

Are you trying to find a good medical collection agency that is fully licensed in your state with high recovery rates? A collection agency with a license to collect in all 50 states.

Choosing the right medical collection agency is crucial to ensure your accounts receivable are managed effectively and ethically.

Hire the best medical debt collection agency: Contact Us

Here are some steps and considerations to help you select the best medical collection agency for your needs:

1. Care for Your Reputation:

Medical debt is very sensitive and can easily ruin a doctor’s reputation if a debt collector is rude, deceptive, or uses intensive tactics to recover patient bills. A good debt collector will recover your medical bills diplomatically and amicably, preserving your reputation. How do you find out? ( check their online reviews).

2. Online reviews:

Check for their Google Reviews. These days, not just the client (creditors) but even debtors/patients leave online reviews about collection agencies.

This reflects how well or how badly they were treated during the collections call. Select a collection agency with an online rating of 4.5 or more, and check if some of the reviews were left by debtors too. Negative reviews are common for collection agencies due to the nature of work, but they should be no more than 10% of the total online reviews.

3. Adherence to laws:

If a Collection Agency HIPAA Compliant? Do they follow FDCPA and local state laws? Do they do credit reporting? Once the medical debt is paid off do they remove it from the patient’s credit history? One very important law that no one talks about is – GLBA law. GLBA law ensures that your data is kept secure and limits who can access patient’s data. Data theft is common in today’s digital age, and GLBA compliance ensures that your and your patient’s data is kept safe by following the highest security standards.

4. Type of Services:

Do they offer both Fixed Fee and Contingency services? This includes pre-collection, early-out services, insurance resolution, collection demands, collection calls, and even legal suits if needed. Carefully review the contract terms, including the length of the contract, the services provided, the fee structure, and any other obligations.

5. Licensed in your State and Other States too:

Collection agencies should be licensed and insured in your state. If they have a license to collect in all 50 states, then you don’t have to worry if your patients move to a different state after the treatment.

6. Multilingual:

A Collection agency’s ability to talk to patients in both English and Spanish is a huge advantage. Some collection agencies will also have individuals who can speak Mandarin, Tagalog, Hindi, and Punjabi.

7. References:

Select an agency with experience in medical collections, as they will better understand this sector’s unique regulations and challenges. They should be able to provide references of other medical practices they serve in your state,

8. Accreditation:

Look for agencies with memberships in reputable industry associations such as the American Collectors Association (ACA) or the Healthcare Financial Management Association (HFMA).

9. Online Portal:

Look for agencies that utilize modern technology for tracking and collecting debts and provide you with real-time access to account information. Discuss how performance metrics are tracked and reported.

10: Customer Service:

Ensure you feel comfortable with the level of communication and professionalism the agency demonstrates. The agency will be interacting with your patients, so they must provide respectful and professional customer service.


Filed Under: Debt Recovery

When “Please Pay” Becomes “See You in Court”: The Litigation Option

You have sent the invoices. You have made the polite phone calls. You have listened to the excuses about “checks in the mail” and “temporary cash flow issues.” Now, you are met with silence.

In the world of debt recovery, there comes a point where diplomacy fails and legal enforcement begins.

However, most business owners hesitate to pull the trigger on a lawsuit. They picture expensive hourly lawyers ($350/hour), massive retainers, and months of distraction. So, they write off $15,000 or $30,000 as “bad debt.”

This is a mistake. Modern debt litigation is efficient, data-driven, and—with NexaCollect—designed to minimize your financial risk.

We bridge the gap between standard collections and the courtroom. We provide access to a nationwide network of debt litigation attorneys who work on a Contingency Basis, meaning you don’t pay legal fees unless they collect.

The Strategic Advantage: Why “Agency First” Matters

Some businesses want to skip straight to a lawsuit. We advise against that. Utilizing our standard collection phase first is a crucial tactical move:

  • Kill the “Counter-Suit”: If you sue a customer out of the blue, they often panic and file a counter-lawsuit claiming they “never received the bill” or were “blindsided.” By letting us work the file first, we create a documented, compliant paper trail of communication. This destroys their defense in court.

  • The Credit Bureau Lever: Before a suit is even filed, we report the debt to major credit bureaus (Equifax, Experian, TransUnion). Often, the mere drop in their credit score—impacting their ability to buy a car or refinance a home—forces payment without a single court filing.

  • Filter Before You File (The “Asset Scrub”): The only thing worse than not getting paid is paying a lawyer to sue someone who is bankrupt. Before we recommend legal action, we conduct a deep investigation into the debtor’s assets (bank accounts, real property, W-2 employment). We only sue if the data shows they can pay.

No Retainers, No Hourly Billing

Traditional law firms require $3,000–$5,000 upfront just to open a file. That model is broken.

  • Our Model: Our network attorneys work on a 50% contingency fee. If the lawsuit yields zero dollars, you owe zero legal fees.

  • The Filing Fee Reality: You are responsible for the hard court filing costs (typically $250 to $600, depending on the state/county).

  • The Reimbursement: Here is the good news—these filing fees are added to the final Judgment amount. When the debtor starts paying, you get reimbursed for these costs first.

Recent Legal Victories: Enforcing Creditor Rights

We are actively securing judgments and settlements for clients who thought their money was gone.

The “Wholesale Inventory” Breach (Illinois)

  • The Scenario: An electronics distributor shipped $42,000 worth of components to a retailer. The retailer sold the goods but refused to pay the invoice, citing “cash flow tightness” before cutting off contact.

  • The Action: Our asset scrub revealed the retailer was still operating and had active merchant processing accounts. We filed suit.

  • The Result: Facing a bank levy that would freeze their operations, the retailer settled 3 days after being served. They paid $38,000 immediately to dismiss the case.

The “Architectural Service” Ghost (California)

  • The Scenario: An architecture firm completed final blueprints for a commercial renovation ($18,500 balance). The developer stalled payment for 8 months.

  • The Action: We reported the debt to credit bureaus first (Step 3), then moved to litigation (Step 4) when the developer ignored the hit. We obtained a Default Judgment.

  • The Result: The judgment lien prevented the developer from closing financing on a new project. They were forced to wire the full balance plus interest and court costs to clear the title.

Q&A: The Reality of Debt Lawsuits

Q: If I sue, do I have to go to court?

A: Rarely. Statistics show that 90-95% of debt collection lawsuits are resolved before trial. Most end in either a settlement (because the debtor doesn’t want to pay their own lawyer) or a Default Judgment (because they don’t show up). You would only need to appear if the debtor files a contest and it goes all the way to a trial.

Q: How long does a lawsuit take?

A: It varies by state court backlog, but generally:

  • 30-60 Days: To serve the debtor and wait for their answer window.

  • 3-6 Months: To obtain a Default Judgment.

  • 6-12 Months: If the debtor fights the case. Note: While slower than a phone call, a judgment is valid for 10-20 years and accrues statutory interest (often 5-10% per year).

Q: What is a “Default Judgment”?

A: This is the most common outcome (occurring in roughly 70% of cases). If the debtor fails to file a legal response to the lawsuit within the time limit (usually 20-30 days), the judge automatically rules in your favor. You win everything you asked for, without a trial.

Q: Can you sue a debtor in another state?

A: Yes. This is why you need us. If you are in Texas but your debtor is in New York, you generally need a lawyer licensed in New York. Our network covers all 50 states, ensuring jurisdiction is never an issue. This allows you to stretch your internal team further without hiring extra staff or searching for out-of-state counsel.

Stop Letting Debtors Bluff You

If they have the money but refuse to pay, they are betting on your inaction. Call their bluff. Using our legal network allows you to protect your name on Google while still getting paid, as the attorneys handle the hard conversations professionally.

Click here to Contact Us and review your legal options.

Filed Under: Debt Recovery

Hiring a Collection Agency with Good Reviews

Businesses and medical professionals with overdue invoices regularly hire collection agencies to recover money for which their own efforts have been exhausted.

Businesses must find a reputable agency with experience in their particular industry or sector. Before hiring a collection agency, it’s crucial for businesses to do thorough research, read reviews, and possibly even seek recommendations from peers in the industry to ensure they’re partnering with an agency that will handle their collections professionally and ethically.

Need a highly-rated collection agency? Contact Us

Good reviews

A collection agency with good online reviews or high recovery rate endorsements from other businesses can give tremendous confidence to anyone looking to recover overdue bills. Not just that, there are collection agencies who proudly showcase thousands of 5-star reviews left by debtors who were so satisfied with their collections approach. Sounds unbelievable?  It’s true, because debt collectors may request positive reviews from debtors who have been assisted amicably and become debt-free.

While online reviews can provide a glimpse into other businesses’ experiences with a particular agency, it’s crucial to approach this process with care and diligence. Here’s a step-by-step guide on how to hire a collection agency with good online reviews:

  1. Start with Research: Before you even look at reviews, make a list of agencies that specialize in your business niche or industry.
  2. Read Multiple Review Platforms: Don’t rely on just one review platform. Check out several, including Google, Yelp, BBB (Better Business Bureau), and industry-specific sites.
  3. Look Beyond the Star Rating: While a high star rating is encouraging, it’s important to read the content of the reviews. This will provide insight into common themes or issues.
  4. Check for Response to Negative Reviews: A collection agency’s response (or lack thereof) to negative feedback can be telling. An agency that professionally and constructively addresses criticism might be more trustworthy than one that ignores or responds aggressively to negative comments.
  5. Ask for References: Once you’ve shortlisted a few agencies based on online reviews, ask them for references. Directly talking to previous clients can provide deeper insights.
  6. Look into Their Practices: It’s essential that the collection agency uses ethical methods. The last thing you want is for your brand’s reputation to suffer because an agency uses aggressive or unlawful tactics.
  7. Check Licenses and Accreditations: Ensure the agency is licensed to operate in the state where your debtors are located. Membership in associations like ACA International can also be a positive sign.
  8. Consider Their Reporting Capabilities: It’s essential to be updated on the agency’s efforts and success rate. Ensure they can provide regular reports on their activities.
  9. Negotiate Fees and Contracts: There are different fee structures like fixed fees, contingency fees, etc. Ensure you understand and are comfortable with the terms before signing a contract.
  10. Pilot Test: If possible, start with a smaller batch of accounts to gauge the agency’s effectiveness before handing over your entire portfolio of delinquent accounts.

Filed Under: Debt Recovery

  • « Go to Previous Page
  • Page 1
  • Interim pages omitted …
  • Page 13
  • Page 14
  • Page 15
  • Page 16
  • Page 17
  • Interim pages omitted …
  • Page 55
  • Go to Next Page »

Primary Sidebar


accounts receivable

Need a Collection Agency?
Kindly fill this form.
We’ll get in touch with you

    Please prove you are human by selecting the heart.

    Compliance & Security

    • SOC 2 Type II Certified: Third-party audited data security and strict privacy controls.

    • HIPAA Compliant: Secure, legal processing of medical and municipal EMS accounts.

    • PCI-DSS Level 1: Highest tier of data encryption for secure payment processing.

    • FDCPA & FCRA Aligned: Full legal adherence to federal consumer protection laws.

    Recent Posts

    • Why Dental Patients Dispute Bills: The Nexa Collections Dental Account Dispute Index
    • 2027 Commercial Collections Benchmark: U.S. Late Payments, AR Risk and B2B Collection Trends
    • Bulk Account Placement: What a Collection Agency Actually Needs From You
    • Nationwide Debt Collection Agency Serving U.S. Cities
    • Chula Vista Collection Agency for Medical, B2B, Schools & Business Debt
    • Corpus Christi Collection Agency: Itemized Bill Rules for Practices
    • Riverside Collection Agency | For Logistics, Medical, Schools & Business Recovery
    • Collection Agency for Large Balances: High-Value B2B Debt Recovery

    Featured Posts

    • Hospital Revenue Cycle Management | Early-Out & Bad Debt Recovery
    • The Modern Accounts Receivable Specialist: Essential Skills & Strategic Mastery
    • LinkedIn for Marketing & Sales: Bye-Bye Cold Calling

    Copyright © 2026 NEXACOLLECT.COM | This content is provided for general informational purposes only and should not be considered legal advice. Collection laws and requirements may vary by state, account type, documentation, debtor status, and specific facts. Please consult qualified legal counsel for guidance regarding your particular situation. Nexa and its authorized collection partners service accounts in accordance with applicable federal and state collection requirements. Visit our home page to know more about us.

    X
    Need a Collection Agency?
    Contact Us