• Skip to main content
  • Skip to primary sidebar

Nexa Collections

  • Home
  • Serving
    • Medical
    • Dental
    • Small Business
    • Large Business
    • Commercial Collections
    • Government
    • Utilities
    • Fitness Clubs
    • Schools
    • Senior Care Facility
  • Contact Us
    • About us
    • Cost

Debt Recovery

Collection Agency to Recover Employee Overpayment or Company Laptop

Have you mistakenly overpaid your employee or a contractor who refuses to return that money? Did you sponsor higher education for your employee with a commitment to work with you for a few years, but he resigned right after completing the degree? Did they sign a contract stating they would pay back the training fees if they didn’t work for a specific duration? Other circumstances where an employee can owe money to his employer include overpaid salary, excessive travel expenses, misuse of company credit card,  or excessive reimbursement claimed. With more employees working remotely, unreturned company equipment—like laptops—has become a growing issue for businesses.

Need a Collection Agency? Contact us

While federal guidelines provide a baseline, specific legal rules and limitations for recovering employee overages vary significantly from state to state.


The Velvet Hammer: A Specialized Recovery Mandate

Recovering capital from former staff requires a specialized touch. Our Account Reconciliation Team utilizes the “Velvet Hammer” approach: a firm, results-oriented methodology that remains reputation-safe and empathetic. We move your bill to the top of their priority list by creating a genuine “will to pay” before other creditors.

Our current fee structure is built for performance:

  • Contingency Recovery: 40% fee—no recovery, no fee.

  • Equipment/Instrument Return: We understand that returned equipment is often depreciated. If a laptop or specialized tool is recovered in lieu of cash, our contingency fee drops to 25%.


Expert Recommendations for Internal Resolution

Before escalating to our team, we suggest following these best practices to strengthen your recovery position:

  • Document the Overpayment: Create a clear record of the overage, including the specific amount, the reason for the error, and any internal policies that were breached.

  • Listen to the Employee’s Perspective: Allow them to share their side. There may be extenuating circumstances or information you are missing that could lead to an amicable internal settlement.

  • Final Internal Communication: Send a formal, final notice outlining the outstanding debt and your intent to involve a third-party agency if not resolved by a specific date.

  • Provide Full Documentation to Us: Once you assign the account, supply our team with all relevant contracts, emails, and policy agreements to ensure a swift, legally-grounded recovery.


Why Working with Debtors Wins

Arguing often leads to defensive stalls. We work with the debtor to find a path to payment, using a diplomatic style that protects your 5-star online reputation. We also perform a rigorous litigation scrub to protect you from attempting collection on high-risk or litigious individuals. Involvement of an agency significantly improves recovery rates—the earlier you assign the debt, the better the results.


Recent Success Stories

Scenario A: The Relocation Refund

A mid-level manager received a $5,000 relocation stipend but resigned within four months, violating their one-year stay agreement.

  • Step 1: We utilized skip tracing to locate the former employee at their new firm.

  • Step 2: Our bilingual collectors mediated a settlement, identifying a payroll error at the new company that was stalling the refund.

  • Result: 100% of the principal was recovered via a structured two-payment plan.

Scenario B: The Unreturned Tech Suite

A remote contractor vanished with a company-issued high-end workstation and multiple peripherals.

  • Step 1: We performed a USPS address check to verify their current residence.

  • Step 2: We leveraged the 25% equipment return fee to incentivize the return of the hardware over a cash battle.

  • Result: All equipment was returned in working order within 72 hours.


Compliance and Modern Logistics

We navigate the complexities of current federal rules to keep your business safe. Our toolkit includes USPS address checks, skip tracing, and bankruptcy scrubs. We offer credit reporting where permitted and requested. All calls are recorded and reviewed to prevent rogue collector behavior and protect against review-bombing risks. When appropriate, we use email and text to speed up response times.


Frequently Asked Questions

Can we just take the money from their final paycheck?
Federal laws (FLSA) are very strict regarding final check deductions. If a deduction brings an employee below the minimum wage, you could face heavy penalties. Professional collection is often the safer legal route.

What if the former employee speaks Spanish?
We have professional Spanish-speaking collectors on board. This ensures clear, respectful communication and a higher likelihood of recovery without misunderstandings.

Does this service apply to contractors too?
Yes. Whether it’s a 1099 contractor or a W2 employee, our strategies for recovering overpayments and unreturned equipment remain highly effective.

Why should I use an agency instead of my HR team?
HR teams are built for culture and growth, not collections. Forcing them into an adversarial role can damage morale and distract them from their core functions.

How do you handle an unreturned company laptop from an ex-employee?
We’ll formally instruct the ex-employee to return the laptop immediately—or reimburse the full replacement cost if they don’t. Our preference is always to recover the actual device, since it may contain important business information. Other items for which you can put a claim include company provided Monitors, Docking station, Company phone, Printer, Hard drives, Ergonomic chair, etc.

Can an ex-employee be prosecuted or fined for misusing an unreturned laptop with company proprietary information?
Yes—misuse or theft of company proprietary data can expose an ex-employee to serious civil liability and even criminal charges in some cases, depending on what was accessed and how it was used. However, if you want to pursue legal action, you should consult an attorney—not a collection agency—to evaluate your options and next steps.

Recover Staff Overages – Contact us
Filed Under: Debt Recovery

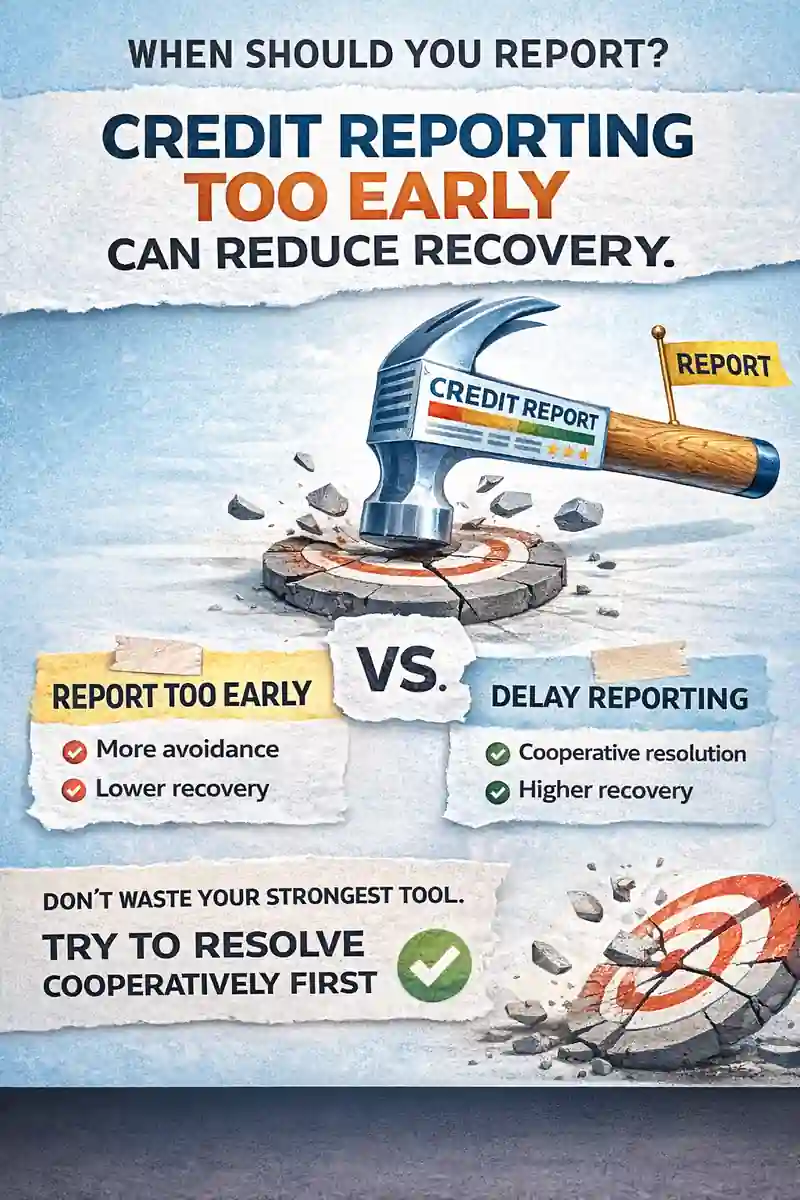
Credit Reporting Too Early Can Reduce Recovery

Credit reporting is powerful. That’s exactly why you shouldn’t waste it too soon.
If you report an unpaid balance immediately, you may accidentally kill the best reason the account holder had to resolve it quickly.

The Simple Truth

When an unpaid account hits a credit report, the situation “feels final” to the person on the other side.
And once something feels final, urgency drops.

Most people don’t think: “I should fix this right now.”
They think: “It already happened… so what’s the point?”

That’s why timing matters more than anger.


Why “Delayed Reporting” Often Collects More

Credit reporting is not just a punishment mechanism.
It’s a late-stage lever.

If you use it first, you have fewer tools left later.

Delayed reporting keeps pressure in reserve—while you attempt higher-yield recovery methods first:

  • professional outreach

  • structured negotiation

  • email + text follow-ups

  • settlement options

  • payment plans where appropriate

This approach protects your recovery rate and your reputation.


The Better Order of Operations (What Works in the Real World)

Here’s the sequence that typically produces the most money:

Step 1: Resolve with calm pressure
Reach out professionally. Create urgency without hostility.
Make it easy to say “yes” before people get defensive.

Step 2: Escalate structure, not emotion
More documentation. More firmness. Clear deadlines.
Still respectful. Still controlled.

Step 3: Credit reporting (only if needed)
When the account holder refuses to cooperate, reporting becomes the final non-legal lever.

That’s the win: you don’t spend your strongest tool on the weakest moment.


“But Isn’t Credit Reporting the Fastest Way?”

It’s fast.
But speed isn’t the same as recovery.

If your goal is to collect, reporting too early can backfire.

It turns a negotiation into a locked room.

And once the other side mentally checks out, you’re left with fewer options:

  • legal escalation (often not practical for smaller balances)

  • months of no response

  • “pay only if you delete it” behavior

You want the opposite:
A clear path to resolution that feels fair, doable, and final.


The One Thing You Should Never Do

Never use credit reporting like revenge.
It makes your process look emotional, not professional.

Credit reporting works best when it’s positioned as:
✅ a documented business step
✅ used after attempts to resolve
✅ based on verified account accuracy

That’s how you keep credibility—and keep recoveries high.


“Pay for Delete” Sounds Tempting (But It’s a Trap)

Some agencies push a “pay and we’ll remove it” style deal.
That strategy causes problems because it trains the account holder to think:

“I’ll pay only if I get something special.”

And it can create disputes, complaints, and reputation risk.

In many industries, credit bureaus expect accurate reporting to remain accurate—not used as a bargaining chip.

Better approach:
Delay reporting until reconciliation fails.

Then use reporting as the last lever—not the first threat.


The Exception: Medical Debt Rules Are Different

Medical debt is treated differently by the major credit reporting agencies in multiple ways, including timing and removal rules once paid.
That’s exactly why medical accounts require a more careful strategy from day one.

(If you’re collecting medical balances, you should be using a patient-friendly approach first anyway.)


What You Should Do Instead (If You Want Higher Recovery)

If the account is unpaid and you want maximum recovery:

✅ Start with structured outreach
Short messages. Clear amounts. Clear options.

✅ Use professional negotiation
Payment plan options can outperform pressure when the person is cooperative.

✅ Document everything
Bad documentation kills leverage. Clean documentation closes accounts.

✅ Hold credit reporting as the final lever
That’s where it does the most damage to avoidance—not to your recovery rate.


Quick Takeaway

Credit reporting works best when it’s delayed—not rushed.
Use professional reconciliation first.
Save reporting for the moment when the account holder is choosing avoidance over resolution.

Reconcile → Negotiate → Final Notice → Credit Reporting → Legal Review


FAQs

Should I report every unpaid balance to credit bureaus?
Not always. Many accounts resolve faster through structured outreach before reporting is used.

When does reporting make sense?
When the account holder stops cooperating, ignores notice, or repeatedly breaks resolution commitments.

Does reporting guarantee payment?
No. It increases leverage, but recovery is highest when you use it at the correct stage—not on day one.

Filed Under: Debt Recovery

Debt Collection Now and Post-Covid

The debt collection industry has been through one of its most difficult periods in modern history, and the recovery looks slow and prolonged. A national and, at the same time, a global recession has been caused, not by financial crises, but rather by an unexpectedly devastating health issue. This is a time to show resilience and learn what we can in order to protect ourselves in the future.

Performance of Collection Agencies during Covid-19 Pandemic

Economic downturns create a huge opportunity for the debt collection industry. A large number of creditors are stuck with unpaid invoices, and as their own efforts fail they tend to submit more accounts to collection agencies. However, during the recession, even the collection agencies find it hard to recover money as people have no funds to pay off their bills. However, as the economy starts to turn around, collection agencies are able to perfectly time their recovery efforts to maximize the chances of successful debt collection to ensure that their clients are the first ones to be paid.

During peak Covid-19 duration (May-Nov 2020) many states prohibited debt collection for several months. Recoveries dropped to a mere 50% of the normal levels. It was the worst time for collection agencies in decades. Many agencies had to shut down during this period.

The turnaround came the following year, during tax refund season as the debt recovery levels went up substantially ( March/April 2020). Additionally, the government-assisted stimulus packages resulted in recovery rates jumping by almost 1.5 times than normal, because people wanted to pay off their debts with this extra cash.

Collection levels will stabilize to normal levels only after the Covid-19 problem completely subsides.

Given its unprecedented scope, how can we access the resources at our disposal and organize our industry’s practices and decisions in a way that would enable us to survive and recover sooner rather than later? Looking at the two major crises in the last century, the Great Depression and the Great Recession, we can use the traditional route of analyzing both pre-and in-crisis data, to identify which receivables can be collected with a higher success rate and focus our efforts there.

Reporting information to build a reliable database

One of the difficulties in accessing that data is the reporting of consumer information by creditors and by debt collection agencies, themselves. The number of those actually furnishing payment information to the consumer reporting agencies has decreased in the last 10 years. A report released by the Consumer Financial Protection Bureau placed the number of reported payments on credit card accounts at 40% in 2020. In 2013, it was at 88%. The Bureau estimates that, as of 2020, ‘only about half of issuers with recent payments furnish these data’.

There may be several factors driving this decline, but what it boils down to for us is the unavailability of reliable information in terms of assessing the number of consumers that made payments, the number of accounts being paid and the speed at which their outstanding debts were being paid. Given this problem, we have to look elsewhere.

A boom in unchecked credit precedes economic crises

It’s generally accepted that ‘the more credit intense the expansion years preceding a crisis, the more severe the recession and the slower the recovery’ (Household Debt and Economic Recovery Evidence from the U.S. Great Depression, EHES Working Papers in Economic History | No. 36, p.4, March 2013). Now we know that before the Great Depression, there was a credit boom accompanying the economic expansion of the 1920s, where banks and financial intermediaries competed to extend credit for consumption and investments. As everyone tried to get a piece of the pie, investments became riskier and regulators turned more of a blind eye, caught in the euphoria of the boom, until the economic bubble began to contract due to non-viable financial choices that were economically unsupported long-term. The widespread, large volume of those financial decisions dragged down a vulnerable system, where consumer and commercial credit had been offered with no restraint.

The Great Recession of 2008 follows a similar pattern, where the domestic credit and subsequent debt in the financial and non-financial sectors increased significantly before and during the crisis. Financial institutions and regulators seem to have still a hard time establishing preemptive policies and controls to prevent recessions, from minor to devastating, from occurring.

What’s also interesting about financial and economic crises is which industries seem to recover time and again, where innovation is coupled with bold investment choices or sweeping reforms that draw from the strengths of previous solutions. The automotive industry is a fascinating example of stubborn efforts and reliable reinvention decade after decade.

US economy before and during Covid

Before the Covid epidemic, US credit levels had been increasing for several years, accompanied by an increase in delinquencies. Excessive borrowing and already vulnerable sectors of the economy might have led to another man-made financial crisis eventually, but the virus cut that transition short quite violently, sending shockwaves through the entire world. Even industries that were doing well, such as commercial construction, transportation, biopharmaceutical research and development, found themselves forced to overhaul their operations at an unprecedented cost. In November of 2020, some Harvard economists calculated that the pandemic would cost the US at least $16 trillion, provided it ended by the fall of 2021.

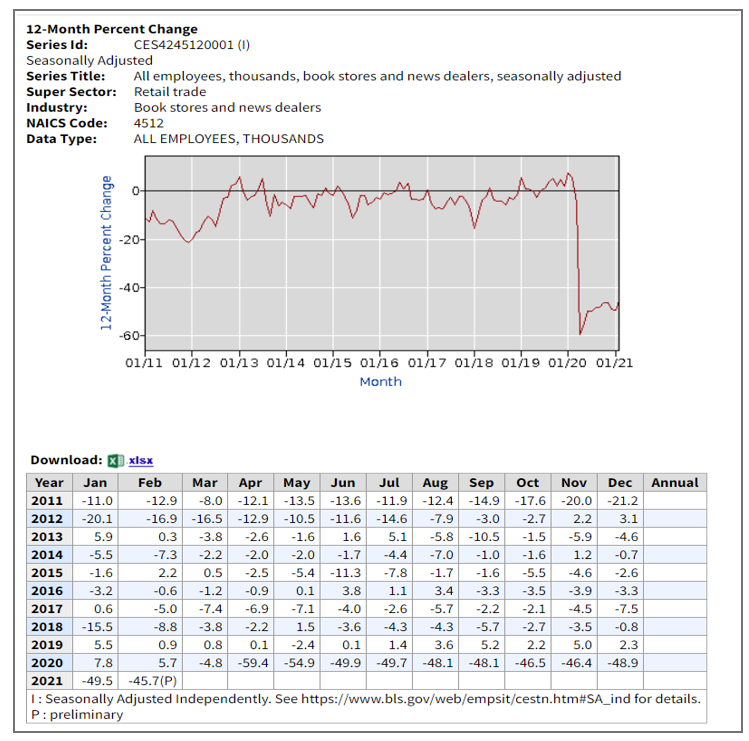
The levels of employment started spinning down at the beginning of 2020 with some industries hit so badly, it’s hard to believe they’ll take less than a few years to recover. For example, consider leisure and hospitality workers, whose employment fell by over 20% compared to 2019, or book retailers and news dealers, who recorded a 48.9% drop from 2019.

Covid Unemployment
Source: US Bureau of Labor Statistics

These are industries where debtors will be hard-pressed to find money to pay debts for no other reason than that they are unemployed. They are, by no means, exceptions. The reports of the US Bureau of Labor Statistics provide a discouraging image of the levels of employment in 2020. There are a few industries that recorded positive percentages when compared to 2019, but they are rare: warehousing and storage, gardening and residential construction, software publishers and credit card issuers, and a few others.

It’s worth noting that credit card issuers and real estate credit maintained or increased their employment levels, due to continued demand for credit, but commercial banking and consumer lending decreased their payrolls.

A focused approach to keep costs down and maximize receipts

The next 6 to 12 months are going to be an uphill battle for creditors. As the economy improves, following vaccinations and easing of restrictions, recoveries for creditors will start going up as well. Until then, the focus of collection efforts needs to be on those consumers who are in the least-impacted industries. The important factors to look at are: ratio of debt to income, a history of debt repayment, occupation, likelihood that they’ll file bankruptcy (see bankruptcy demographics), family size, and employment status.

It’s good to remember that these are not infallible guides, but they help make sorely-needed predictions. Income, for instance, is not a totally reliable indicator of a consumer’s willingness to pay debt. In some cases, consumers with higher expendable income may maintain debt for longer periods of time specifically because it takes up a smaller percentage of that income. Those whose monthly credit card payments are only 20% of their income might be more comfortable with that debt. On the other hand, consumers with lower income, whose monthly credit card payment bites painfully into their short-term individual or household income, at around 30%-40%, may feel more inclined to resolve their debt situation, even if it means taking out a loan, or making low, but consistent, payments every month. Obtaining current information about a given consumer will help a collector evaluate and compare them to other collection opportunities.

In addition, debt collection rates vary widely from state to state. The population of the Southern states seem to have the hardest time paying off their debt, according to this interactive map about debt in America, last updated in March of 2021.

With many debt collection agencies having shut down and others operating with fewer staff and less financial resources, wasting time and money on chasing random debtors may be the last nail in the coffin for some agencies’ profit margins. Breaking down your portfolio of delinquent debts into categories based on the information here may help optimize your collection efforts and accelerate cash inflow.

Filed Under: Debt Recovery

Agencia de Cobros en Puerto Rico | ¡Cobramos lo suyo, protegemos su marca!

En Puerto Rico—desde los hoteles de lujo en Isla Verde y Condado hasta las farmacéuticas de Barceloneta y los comercios de la Milla de Oro—sabemos lo que es “bregar” duro para echar hacia adelante. Pero en 2026, el que no se pone al día con el nuevo Código Civil, pierde. Con la fiscalización de DACO más fuerte que nunca y la prescripción de deudas a los 5 años, usted no puede darse el lujo de esperar. No deje que sus facturas se vuelvan sal y agua; en Nexa hablamos su idioma y sabemos cómo recuperar sus biles sin que usted pierda el sueño ni la reputación.

blank

Nexa ofrece servicios de cobro que protegen su reputación, con licencias de cobranza en los 50 estados y Puerto Rico. Incluye reportes de crédito sin costo, verificaciones gratuitas de litigios y bancarrota, y cero cargos de incorporación. Seguro y confiable: cumplimiento con SOC 2 Tipo II, DACO e HIPAA.

¿Necesita una agencia de cobro? Contáctenos


El Paisaje Legal en la Isla 

Puerto Rico se rige por el Derecho Civil, lo que significa que las reglas aquí son distintas a las del “Mainland”. Si usted piensa que tiene 10 años para cobrar, su deuda podría estar ya “muerta”.

Tipo de Deuda Tiempo para Cobrar (Prescripción) Base Legal
Acciones Personales (Deuda General) 5 Años Código Civil Art. 1201
Pagarés / Notas Promisorias 3 Años Código de Comercio Art. 946
Servicios Médicos / Salud 3 Años Código Civil Art. 1203
Embargo de Salario Solo el 25% (75% protegido) Regla 56.4 Proc. Civil
Sentencias Judiciales 15 Años (Renovable) Código Civil Art. 1201

Reglas Críticas para el 2026 en P.R.:

  • El “Barranco” de los 5 Años: Con el nuevo Código Civil, su tiempo se redujo drásticamente. Nexa audita sus cuentas para identificar cuáles están a punto de “vencerse” y las activa de inmediato.

  • Reglamento 9037 de DACO: El Departamento de Asuntos del Consumidor prohíbe el hostigamiento. Nexa utiliza mediación bilingüe profesional que cumple 100% con DACO para evitarle multas a su negocio.

  • Interrupción Extrajudicial: En P.R., una carta certificada bien redactada puede reiniciar el reloj de la prescripción. Nosotros nos encargamos de enviar estas reclamaciones para que su derecho al cobro no expire.

  • Protección Salarial: Aquí se protege el 75% del salario. Por eso, Nexa se enfoca en identificar activos, cuentas bancarias y otras propiedades para asegurar que el recobro sea real.


Costo-Efectividad: La Ventaja de Nexa

blank

  • Servicio de Tarifa Fija ($15 por cuenta): Ideal para cuentas nuevas. El deudor le paga el 100% directamente a usted. Sin comisiones de por medio.

  • Servicio de Contingencia (20%–40%): Cobro basado en resultados. Si no recobramos sus chavos, usted no paga ni un centavo.


Industrias que Servimos en Puerto Rico

  • Turismo y Hospitalidad: Atendiendo la “Economía del Visitante”. Recuperamos facturas de eventos, cancelaciones y deudas de huéspedes en hoteles y paradores de San Juan hasta Rincón. Sabemos cómo cobrarle al turista que ya se fue de la isla.

  • Farmacéuticas y Manufactura: Cobro B2B especializado para el sector industrial de Pharma-Coast. Manejamos disputas de logística y suplidores con precisión bilingüe.

  • Salud y Servicios Médicos: 100% cumplimiento con HIPAA. Navegamos la prescripción de 3 años en servicios médicos, usando una mediación empática para que su oficina médica no pierda pacientes ni dinero.

  • Universidades y Colegios: Manejamos el recobro de matrículas y cuotas de vivienda con un enfoque diplomático que respeta los ciclos de becas y el “Bono de Navidad” local.

  • Contadores y Firmas de CPA: Recobro de honorarios profesionales. Entendemos los ciclos de planillas de Hacienda y cobramos lo suyo sin dañar la confianza con sus clientes.

  • Bancos y Cooperativas de Ahorro y Crédito: Expertos en préstamos personales y comerciales atrasados, utilizando las leyes de hipotecas y sentencias de la isla.

  • Construcción y Contratistas: Recuperación de pagos para HVAC, eléctricos y contratistas generales. Expertos en gravámenes (Liens) bajo el Código Civil.

  • Comercio B2B, Restauración y Logística: Recuperación rápida para empresas que no pueden permitirse tener el dinero “estancao” mientras los costos de operación suben.


Resultados de Recobro Recientes en P.R.

Caso 1: Resort de Lujo en el Área Metro (Turismo)

  • El Problema: $95,000 en facturas de eventos corporativos de una empresa de EE.UU. que no quería pagar.

  • El Resultado: Nexa utilizó su red interestatal y mediación bilingüe para recuperar los $95,000 completos en 45 días, sin tener que pisar el tribunal.

Caso 2: Centro de Especialistas en Bayamón (Médico)

  • The Problem: $120,000 en deudas de pacientes que estaban a punto de cumplir los 3 años de prescripción.

  • El Resultado: Implementamos un plan de “Reclamación Extrajudicial” y recuperamos $82,000 en 70 días, salvando legalmente el resto de las cuentas.


Preguntas Frecuentes (FAQ)

1. ¿Cuánto tiempo tiene un negocio para cobrar una deuda en Puerto Rico?

En Puerto Rico, las acciones personales generalmente prescriben a los 4 años, salvo que una ley establezca un término diferente. El Código Civil de 2020 redujo el término general y también pueden aplicar reglas distintas según el tipo de obligación y la fecha en que nació la reclamación.

2. ¿Una carta de cobro puede interrumpir el término de prescripción en Puerto Rico?

Sí. Una reclamación extrajudicial válida del acreedor dirigida al deudor puede interrumpir la prescripción. El Artículo 1197 del Código Civil también reconoce la interrupción mediante una reclamación judicial, administrativa o arbitral, o cuando el deudor reconoce la obligación. Una vez interrumpido el término, comienza nuevamente su cómputo.

3. ¿Una agencia de cobros necesita licencia para cobrar deudas en Puerto Rico?

Sí. Las agencias de cobro que realizan actividades cubiertas en Puerto Rico están sujetas a los requisitos de licencia de DACO. Puerto Rico cuenta con un proceso específico de licencia para agencias de cobro, además de requisitos regulatorios aplicables a sus operaciones.

4. ¿Qué reglas debe seguir una agencia de cobros en Puerto Rico?

Las agencias de cobro en Puerto Rico deben cumplir con el Reglamento sobre Agencias de Cobro de DACO, además de las leyes federales que resulten aplicables. El Reglamento 6451 establece requisitos sobre procedimientos de cobro, comunicaciones con consumidores, licencias y prácticas prohibidas.

5. ¿Puede una empresa en Puerto Rico cobrar una deuda si el cliente se mudó a Estados Unidos?

Sí, en muchos casos una deuda puede continuar gestionándose aunque el deudor se haya mudado fuera de Puerto Rico. Sin embargo, las comunicaciones, licencias y cualquier acción legal deben cumplir con los requisitos aplicables en la jurisdicción donde se encuentra el deudor. Una agencia con capacidad de cobro a nivel nacional puede facilitar este proceso.

6. ¿Cuánto cuesta contratar una agencia de cobros en Puerto Rico?

NexaCollect ofrece una opción de tarifa fija de $15 por cuenta para cuentas elegibles, donde el cliente conserva el 100% de lo recuperado, y una opción de cobro por contingencia para cuentas que requieren esfuerzos más intensivos. El programa y la tarifa aplicable dependen del tipo, antigüedad y características de la cuenta.

Importante para esta página: yo corregiría antes de publicar el dato de “5 años” que aparece actualmente. El Código Civil de Puerto Rico de 2020 establece como regla general 4 años para las acciones personales, salvo que exista un término distinto fijado por ley.

Nosotros cobramos sus cuentas morosas

Need a Collection Agency (Agencia de cobros) in PR? Contact us


Filed Under: Debt Recovery

Collection Agency for Semen Distributors & Breeders

Livestock genetics don’t wait for a check to clear. A tank of unclaimed semen or embryos still needs liquid nitrogen and staff time whether or not the invoice ever gets paid, and the buyer knows that delay costs you more than it costs them. Nexa recovers past-due accounts for breeders, AI studs, and genetics distributors the same way we’d want a buyer treated in a small, reputation-driven industry: firmly, but without burning the relationship you’ll need again next breeding season.

A breeder handing carrying a container of semen

Unpaid invoices are common for animal breeders and semen distributors. Repeated follow-ups with a customer don’t always work, and past-due accounts receivable start eating into margins that were already thin. Breeders are often left with one real option: assign the account to a collection agency. The moment a customer realizes a professional agency is now involved, the tone of the conversation tends to change.

Why Genetics & Breeder Accounts Are Different From Ordinary B2B Debt

A Perishable Product on the Clock
This is especially concerning for distributors and breeders, since the product itself is perishable and carries ongoing maintenance costs — the liquid nitrogen, monitoring, and facility upkeep needed to keep frozen semen viable. Every day an account sits unpaid, the underlying product is still costing you money to preserve.

The Cost of Cold Storage
Proper cryopreservation requires tightly controlled storage conditions, and that isn’t free. When customer payments are delayed or never arrive, the ongoing cost of maintaining that inventory keeps accumulating on your side of the ledger, even while the product itself sits unused in a tank.

Breeding Season Drives Your Cash Flow
Demand for genetics is inherently seasonal, tied to breeding cycles for the species involved. That seasonality makes cash flow harder to predict, and it can turn a handful of slow-paying accounts from an annoyance into a real strain if the business hasn’t planned around the gaps between breeding windows.

Collection agencies know the laws and resources required to recover unpaid bills, and how to do it in an amicable, diplomatic manner that attempts to preserve the underlying business relationship.

Our specialized recovery strategy leverages key livestock industry legal mechanisms—including UCC-1 filings on agricultural assets, Packers & Stockyards Act (PSA) credit protections, and breed association pedigree release holds to enforce payment on high-value genetic accounts.”

Protecting Your Reputation in a Small, Word-of-Mouth Industry

Genetics and breeding is a smaller world than most industries you’ll sell into. Buyers talk to each other at sales, shows, and association meetings, and a distributor known for heavy-handed collections can lose future business well beyond the account in dispute. Our Velvet Hammer approach exists for exactly this reason: our Account Reconciliation Team handles every account diplomatically, aiming to collect what’s owed while giving the customers around a debtor no reason to think twice about buying from you again. We know how to press firmly on a stalled account without turning it into industry gossip.

Serving Breeders Nationwide

Nexa provides a reputation-safe approach, equipped with all 50-state collections license, offering free credit reporting, free litigious debtor check, free bankruptcy scrub, and zero onboarding fees. Secure – SOC 2 Type II & HIPAA compliant. Over 2,000 online reviews rate us 4.85 out of 5. 

Need a Collection Agency? Contact us

We Understand Every Corner of the Industry

It is crucial to select an agency with experience recovering specifically for breeders. It doesn’t matter which species you work with — we recover accounts for:

  • Cattle & Dairy Genetics — bull studs, embryo transfer programs
  • Equine Breeding — stallion services, shipped and frozen semen
  • Swine Genetics — boar studs, AI cooperatives
  • Poultry & Hatching Egg Producers
  • Small Ruminant & Specialty Livestock Breeders

Rather than writing off an unpaid invoice as bad debt, it’s worth handing it to an agency that already understands how your specific corner of the industry actually operates.

Recent Recovery:

A regional bull stud had roughly $18,000 tied up across a handful of accounts from repeat customers who had gone quiet after the spring breeding season. Rather than sending the same generic letter used for any other industry, the team referenced the actual straws and collection dates on file — a signal to the debtors that this wasn’t a form letter, but someone who understood the product. Most of the balance was recovered within the following breeding cycle, without losing any of the underlying customer relationships.

How Recovery Works

Most agencies — including Nexa — work on a contingency basis for breeder and genetics accounts: there’s no fee unless money is actually recovered. For freshly past-due accounts that haven’t reached the phone-call stage yet, a lighter-touch, fixed-fee letter series is also available.

Collectors like working with semen distributors, breeders, and the egg industry because of the high recovery rates these accounts achieve compared with many other business categories.

Cost of collections for breeders

Frequently Asked Questions

Can we place a lien on unclaimed frozen semen or embryos if a customer stops paying storage fees?

In many cases, yes, if the arrangement is documented properly. Under UCC Article 7 (adopted in some form in every state), a party storing goods for someone else can typically claim a possessory lien for unpaid storage charges once a proper storage agreement or receipt is in place — that lien lets you refuse to release the inventory until the balance is paid. The catch is that it’s a possessory lien: it disappears the moment you voluntarily hand over the semen or embryos, and its exact scope depends on the storage agreement’s wording. We factor this into strategy early, since holding the inventory is often more effective leverage than a phone call alone.

Our contract includes a conception guarantee, and the customer is refusing to pay because the animal didn’t get pregnant. Is this a real dispute or a delay tactic?

It can be either, so it’s worth separating the two quickly. A genuine conception guarantee dispute usually comes with some paper trail — breeding dates, a vet’s confirmation attempt, or a documented re-breed request. A stall tactic tends to be vague, arrives only after repeated payment reminders, and doesn’t reference the specific guarantee terms in the contract. We review what the agreement actually promised — a guaranteed conception versus a guaranteed service attempt — before pursuing the account, since collecting on a legitimate guarantee dispute can do more reputational damage than the balance is worth.

Can we withhold breed registration or pedigree papers until an account is paid?

Often, yes, as a matter of your own sale terms rather than a specific named legal lien. If your contract is clear that registration paperwork is delivered only after payment clears, that’s generally enforceable like any other deliverable you’re entitled to hold back. It works best as leverage early, before the buyer has bred, sold, or shown the animal without papers in hand; once they’ve already gotten value without them, it loses most of its pull. We help clients time this correctly rather than reaching for the phone before the contract’s built-in leverage has been used.

Our customer is an international buyer who imported semen or embryos. Does that change how collections work?

It adds a layer, but it doesn’t take the account off the table. Cross-border accounts take longer to resolve, and international litigation is rarely worth pursuing for a mid-sized balance, so the practical leverage shifts toward things that still cross the border: credit reporting that affects the buyer’s ability to finance future imports, and their own interest in staying eligible to purchase from other US suppliers. We flag international accounts early so the strategy accounts for the added distance from day one instead of defaulting to a domestic playbook that won’t apply.

We’re worried that being aggressive with a well-known breeder or stud farm could hurt our reputation in the industry. How do you handle that?

This is exactly the situation our Velvet Hammer approach is built around. Word travels fast between breeders, associations, and sale barns, so we treat every account as if the debtor might be a reference call away from your next ten customers. Our Account Reconciliation Team focuses on professional, documented communication rather than pressure tactics, and we coordinate with you before escalating on any account tied to a customer whose relationship matters beyond this one invoice.

Filed Under: Debt Recovery

Avoid Non-Payment of Bills for B2B Transactions

B2B bills
Staying in business can be as simple as pulling out the steamy croissants from the oven right when the timer rings just before your bakery opens or as complicated as the daily coordination of a supply chain that involves numerous moving pieces and partners.

Preventing non-payment of bills in a B2B (business-to-business) setting can be challenging, but there are several strategies you can use to minimize this risk:

  1. Credit Checks: Before offering credit to a new customer, conduct a credit check to evaluate their financial stability and payment history. This can help you identify high-risk clients.
  2. Clear Terms and Conditions: Clearly define your payment terms and conditions in the contract. Make sure that both parties understand and agree to the terms before conducting business.
  3. Upfront Payments: For large orders or high-risk customers, consider asking for upfront payments or deposits. This can reduce your exposure to credit risk.
  4. Payment Reminders: Regularly remind customers of upcoming or overdue payments. This can be done through various methods, including email, phone calls, or mailed statements.
  5. Strong Relationships: Maintain strong relationships with your customers. Open communication can encourage clients to pay on time and enable you to detect potential payment problems early.
  6. Flexible Payment Options: Offering multiple payment options can make it easier for clients to pay. This might include accepting payments by credit card, bank transfer, online payment platforms, or even offering installment plans for larger invoices.
  7. Escalation Procedures: Have a clearly defined process for managing late payments. This might include sending late payment notices, charging late fees or interest, or using a collections agency for persistently overdue accounts.
  8. Invoice Factoring: Invoice factoring or financing allows you to sell your invoices to a third party. This can be useful for managing cash flow and reducing risk, but it does involve fees.
  9. Trade Credit Insurance: This type of insurance protects your business from non-payment of commercial debt. It ensures that your invoices will be paid even if your customers default.
  10. Legal Assistance: In extreme cases, legal action might be necessary. Always consult with a legal professional to understand your options.

Remember, while you can’t eliminate non-payment risk entirely, you can take steps to manage it effectively and minimize its impact on your business.

We have mentioned the challenges faced by accounts receivable before, but one item stands out as a recurring and headache-causing problem: the predictability of timely receipts.

Delays or interruptions in customer payments can jeopardize all of your downstream activities, leading to potential losses, bad credit, and, eventually, more serious consequences for your business.

Here are several key paths and practical tips to use in order to avoid payment delays and prevent cash-flow issues.

1. Trust and communication

Business is about trust, and the key to trust is communication. Having open contact with both new and longtime customers and partners is vital to building an environment of efficient collaboration and honest mutual dependency. Good communication helps focus your common interests in order to keep them attainable and helps your business adjust to crises and instability without defections and bad surprises. Interaction can help to sense the intentions of new customers, and a good communication channel with longtime customers makes it more likely that they won’t hide their cash flow difficulties. That may give you an opportunity to prepare on your end and also to address such problems together, proposing payment plans that can prevent defaults and save the interests of both parties

2. Know your business partners

New commercial relationships are always risky and full of unknowns, and even the best long-running relationships are subject to conflict and deterioration. From the very beginning, setting up a channel or a system to identify, vet, and authenticate your partners can save money and headaches in the long run.

Sometimes, communication is just not enough, and trust can be lost along the way. Treat any disputes respectfully and promptly, and don’t let your emotions control your actions.

Monitoring your customers’ behavior is important for you to be able to anticipate and avoid uncomfortable positions and breaks in your cash flow. You don’t have to resort to any obsessive, intrusive surveillance systems to do that. Just staying informed about what’s going on in the industry and keeping in regular contact with your partners is enough.

Trusting means finding where your interests meet theirs, not neglecting them. Set up processes to collect up-to-date information about your customer’s financial health where the partner liaisons and account managers can access them, and modify your Policies and Procedures to include clear guidelines on payment practices befitting the customers’ situation. Depending on the case, you can require payment beforehand or establish credit limits.

3. Know your own business

Efficient and responsible choices in payment policies are possible only if you know your business’ own needs very well. How much total customer credit can you afford in terms of account receivables? What are your essential cash needs? What are the real risks you can take? Awareness about the limits of your business will help you enforce your payment policies in a non-aggressive, efficient way and avoid unnecessarily strict payment requirements when possible.

Learn to read a balance sheet, have monthly or quarterly meetings with your sales team and accounting department, and always ask for reports on unpaid invoices. Be prepared to stop services or the distribution of products to customers that have not paid, and establish a procedure for reinstatement of service.

We’ve talked about how a low rate of accounts receivable shows your business is on the right track.  A maximum of 20% is usually what a company can withstand, but conservative risk analyses show that the cash trapped in outstanding invoices should not be higher than 8%-10% of your total business income.

4. Fix your processes

A lot of payment delays can be easily avoided by designing efficient invoicing processes.

Ensure invoices are always correct, down to the last detail, so customers don’t reject them. Sometimes customers don’t even notify you that they haven’t accepted the invoice, and meanwhile, you’re still waiting for payment. Requiring them to validate the invoicing details can be an option.

Make sure that you always follow up on unpaid invoices. Streamline the payment process so your accounts receivable department can follow actionable, clear steps such as setting up automatic reminders and diversifying the notifications (phone calls, emails, or mailed statements).

In general, any possible source of misunderstanding and ambiguity in your process has to be identified and avoided in order to prevent both unintentional mistakes and deliberate strategies by customers to take advantage of the flaws that might be in your workflow. You can also include simple expedients to encourage quick invoice payment, such as offering prompt-payment discounts. Your company can offer a 1% to 3% discount if the invoice is paid within 15 days, ensuring you have healthy cash flows every month.

An alternative would be to allow a debtor to pay in interest-free and penalty-free installments. For those businesses facing hard times but struggling to get back on track, this method not only helps them maintain their relationships but also ensures they’ll have a lower balance to pay in the future.

5. Method of payment

Many companies have switched to digital payments, but some are still using paper, which means that a check might or might not be coming. Offer incentives to your established customers to switch to ACH, credit card payment, click-and-pay or even PayPal. With an app highly rated in terms of features and user-friendliness, PayPal also offers a business account that can be connected directly to your business checking account or credit card. If you have a website where you already accept credit cards, you can add PayPal as a secondary payment method. Once you give your customers several ways to pay that bill, they’ll have no good reason not to complete the transaction.

6. Platform of payment

You have to make sure that the digital platform you’re using, whether a website or specialized software, is fast and secure. Nearly 80% of online users who have a bad experience with pages loading slowly don’t return to those pages. The rule of thumb is that they expect no more than a 3-second lapse between the click and the moment a page fully loads. Imagine one of your partners trying to make a payment when your website doesn’t load the payment page. He might try one more time and then either forget or give up in frustration. Yours is just one of the bills he has to pay and his time is limited.

There are many ways to improve the loading speed of your website, and some are technically challenging. What you can do from the very beginning is to choose a competent web hosting service for your online business profile. That only requires a little bit of research.

7. How do others do it? What should you look out for?

Always be on the lookout for new solutions to problems. Innovative technology or methods of being paid are always emerging. Traditional solutions still work as well. If a customer is in trouble, you can help them by sending business their way or asking for free products/services in lieu of their debt.

Also, it’s good to be realistic about the type of service or product you’re offering. When a business starts going badly, companies tend to slash non-essential costs first. Do you service office water coolers or offer catering for company events? Are you a manufacturer of vintage toys with a very niche customer base and very few distribution centers? The type of business you have will determine how badly hit you’ll be during an economic crisis.

Cash flow is the lifeblood of every business. Regular and on-time customer payments are key to keeping the order-to-cash cycle healthy, which in turn enables you to make well-timed investments, pay your own bills, and ensure your business’ financial health. Anything you can do to secure your cash-flow will never be too much, as long as the steps you take are within practical, legal and ethical bounds. Prevention is always better than needing a cure, and that applies just as accurately to businesses working together.

Filed Under: Debt Recovery

  • « Go to Previous Page
  • Page 1
  • Interim pages omitted …
  • Page 23
  • Page 24
  • Page 25
  • Page 26
  • Page 27
  • Interim pages omitted …
  • Page 55
  • Go to Next Page »

Primary Sidebar


accounts receivable

Need a Collection Agency?
Kindly fill this form.
We’ll get in touch with you

    Please prove you are human by selecting the cup.

    Compliance & Security

    • SOC 2 Type II Certified: Third-party audited data security and strict privacy controls.

    • HIPAA Compliant: Secure, legal processing of medical and municipal EMS accounts.

    • PCI-DSS Level 1: Highest tier of data encryption for secure payment processing.

    • FDCPA & FCRA Aligned: Full legal adherence to federal consumer protection laws.

    Recent Posts

    • Why Dental Patients Dispute Bills: The Nexa Collections Dental Account Dispute Index
    • 2027 Commercial Collections Benchmark: U.S. Late Payments, AR Risk and B2B Collection Trends
    • Bulk Account Placement: What a Collection Agency Actually Needs From You
    • Nationwide Debt Collection Agency Serving U.S. Cities
    • Chula Vista Collection Agency for Medical, B2B, Schools & Business Debt
    • Corpus Christi Collection Agency: Itemized Bill Rules for Practices
    • Riverside Collection Agency | For Logistics, Medical, Schools & Business Recovery
    • Collection Agency for Large Balances: High-Value B2B Debt Recovery

    Featured Posts

    • Pros and Cons of Hiring a Debt Collection Agency
    • School District Accounting Trends After the ESSER Cliff
    • Common Debt Collection Mistakes

    Copyright © 2026 NEXACOLLECT.COM | This content is provided for general informational purposes only and should not be considered legal advice. Collection laws and requirements may vary by state, account type, documentation, debtor status, and specific facts. Please consult qualified legal counsel for guidance regarding your particular situation. Nexa and its authorized collection partners service accounts in accordance with applicable federal and state collection requirements. Visit our home page to know more about us.

    X
    Need a Collection Agency?
    Contact Us