• Skip to main content
  • Skip to primary sidebar

Nexa Collections

  • Home
  • Serving
    • Medical
    • Dental
    • Small Business
    • Large Business
    • Commercial Collections
    • Government
    • Utilities
    • Fitness Clubs
    • Schools
    • Senior Care Facility
  • Contact Us
    • About us
    • Cost

Debt Recovery

Short-Staffed and Drowning in AR? Here’s the Real Problem

When you’re short-staffed, unpaid invoices are the first thing to slip.

No one is hired just to chase money. The people you already have are busy keeping customers happy, answering phones, scheduling jobs, and putting out fires.

Meanwhile:

  • Most businesses are regularly paid after the due date

  • A big chunk of revenue often sits in the 60–90–120+ day bucket

  • Teams spend hours every week “circling back” on overdue invoices

If you’re short on people, you simply don’t have those hours. So AR becomes a someday project, and “someday” rarely comes.


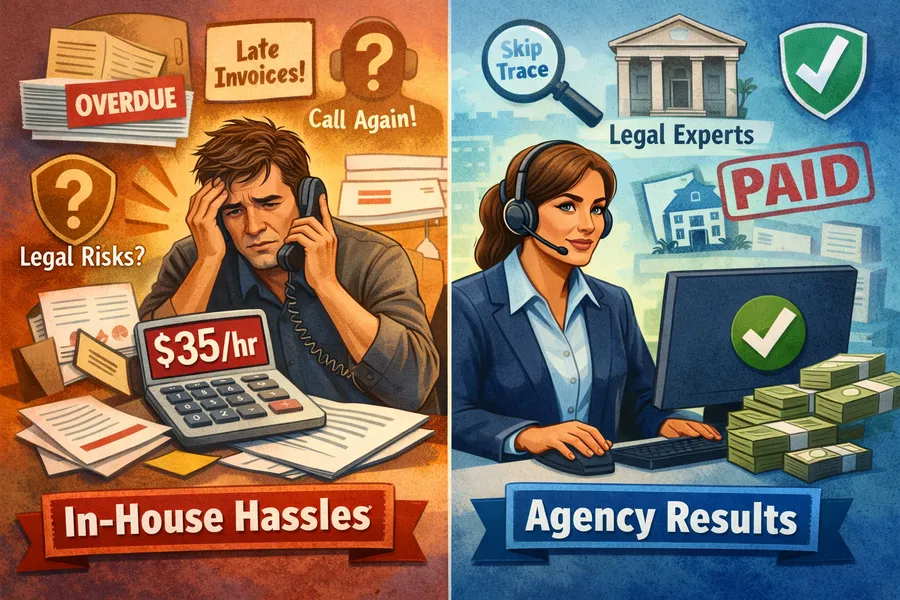
When you factor in salary, benefits, taxes and overhead, those “just 30 minutes a day” quickly add up to $30–$40+ per hour of fully loaded cost—hundreds of dollars a month—for an employee who lacks skip-tracing tools, bankruptcy screening, or knowledge of collection laws, and who usually has zero interest in acting as a part-time debt collector. In the end you’re paying a premium rate for slow, risky, and uncomfortable collections work that a specialized agency can do faster, safer, and purely on results.


The core issue: nobody truly “owns” collections

In a short-staffed operation, AR is treated like background noise:

  • “We’ll call them after this busy week.”

  • “Let’s get caught up on service first.”

  • “We’ll tackle aging invoices next month.”

That next month never arrives.

The real problem isn’t bad customers; it’s lack of ownership and consistency:

  • No one’s job is to be methodical about follow-up

  • Nobody has proper training in handling excuses and pushback

  • There’s no clear point where “late” becomes “collections”

So debts quietly age until they’re no longer worth the fight.


The hidden cost of “we’ll just hire someone”

On paper, hiring an in-house AR/collections person feels like the natural solution.

In reality, it’s expensive:

  • Salary (often tens of thousands a year)

  • Benefits, payroll taxes, software, workspace, training

  • Manager time to supervise, review, and replace if they leave

And collections work isn’t steady:

  • Some months they’re slammed

  • Other months there’s not enough work to justify the cost

  • If they’re mediocre, you pay a full salary for half the results

For a short-staffed business, that’s a heavy, permanent cost for a problem that’s irregular and spiky.


Why DIY collections rarely work well

Most businesses try to “share the load” internally:

  • The receptionist makes a few calls

  • The office manager sends some reminder emails

  • Someone in accounting tries to chase old invoices on Fridays

Common outcomes:

  • Awkward conversations – staff are afraid to be firm with customers they know

  • Inconsistent follow-up – two calls… then nothing for 6 weeks

  • No structure – every debtor is handled differently, depending on who picked up the file

  • Legal risk – nobody is trained on collection laws, call-time limits, or what you can and can’t say

On paper, DIY collections look cheap.
In practice, they’re slow, stressful, and lead to a lot of quiet write-offs.


Why outsourcing is often cheaper than “doing it ourselves”

A professional collection agency is usually contingency-based:

  • If they don’t recover, you don’t pay a fee

  • If they do recover, you share a percentage of the money collected

Compare that to a full-time salary, benefits, and overhead—paid every month, whether or not your AR actually improves.

For a short-staffed team, outsourcing means:

  • No fixed payroll cost for collections

  • No training, turnover, or management headaches

  • Staff stay focused on work that actually generates new revenue

You’re effectively trading “unpredictable write-offs and staff time” for “a predictable share of money you probably weren’t going to collect anyway.”


A four-step collection process that fits into your existing workflow

The fear with agencies is that they’ll be too harsh and damage relationships. A good one works in measured steps, not with a sledgehammer.

Think of it as a four-step ladder.

Step 1 – Gentle, branded reminders

This is the “soft touch” phase:

  • Professional letters or emails mentioning your company

  • Clear summaries of what’s owed and how to pay

  • A friendly, “we need to get this squared away” tone

This alone cleans up a surprising number of accounts—people who simply forgot or misplaced the invoice.

Step 2 – Polite, persistent live contact

For those who ignore written reminders, the agency begins live outreach:

  • Calls and, where allowed, text or email

  • Trained collectors who spend all day handling excuses and delays

  • Calm but persistent follow-up at different times of day

The tone is still respectful. The goal is to confirm the debt and get a realistic plan in place, not to threaten.

Step 3 – Deeper recovery tools

For tougher cases:

  • Skip tracing to find new addresses or phone numbers

  • Checking whether the debtor can realistically pay

  • Offering structured payment plans or, when appropriate, settlements

Here, experience matters. Collectors know when to push, when to listen, and when a partial recovery is better than adding another year to your aging report.

Step 4 – Legal and credit escalation (for the few that need it)

A small percentage of accounts are simply refusing to pay. For those:

  • Formal attorney letters or legal action may be considered (usually for larger balances)

  • Where allowed and appropriate, accounts may be reported to credit bureaus

By the time an account reaches this stage, every softer option has been tried. This step is for won’t-pay, not can’t-pay, situations.


How this helps a short-staffed team in real life

The real win isn’t just more recovered money—it’s clarity and relief.

You set simple rules, such as:

  • “Send accounts to Step 1 at 45 or 60 days past due.”

  • “Move to live contact at 90 days if there’s still no payment.”

  • “Only place accounts over $X, except for periodic cleanups of small, very old balances.”

After that:

  • Your team continues to serve customers and run the business

  • The agency handles the persistence, structure, and legal nuance

  • Money that used to quietly die in the 90–120+ day column starts coming back in


The bottom line

Being short-staffed isn’t just a staffing problem—it’s a cash problem when overdue invoices are allowed to pile up.

You can:

  • Ignore them and write off more every year

  • Keep trying to squeeze collections into already overloaded roles

  • Or plug in a four-step outsourced process that’s persistent, reputation-conscious, and paid for out of money you weren’t collecting anyway

If “we’re too short-staffed to chase AR” sounds familiar, that’s exactly why a structured, outsourced collections process isn’t an extra expense—it’s the missing piece in your revenue strategy.
Filed Under: Debt Recovery

Impact of the GLBA on Collection Agencies

As per FTC, starting June 9, 2023 all collection agencies will be treated as financial institutions. This means all collection agencies must secure consumer data nearly the same way as banks.

Failure to comply with GLBA can have severe consequences for the collection agency, especially the owners and the higher management. Each violation can result in fines up to $100,000 and may extend to criminal penalties, including jail time. We will try to cover only the important parts of GLBA per our understanding.

GLBA covers your employees and even your vendors that have access to your customer and debtor data. This includes your collection letter printing vendor, your software providers that access your data, and even your Sales Representatives.  Any data access outside your company network must be secured through the VPN and their laptops should be encrypted.

If your associates can access emails through their cell-phone, you must evaluate if their emails can potentially have sensitive data and take appropriate steps to secure their mailbox or completely disable mobile access to these emails.  The GLBA Privacy Rule only applies to nonpublic personal information (NPI), including (Debtor) Name, Address, Income, Social Security number. Transaction information such as account numbers, payment history, loan balances and information from court records or consumer reports.

After the recent changes done by CFPB and these upcoming GLBA laws will result in significant operational challenges and cost additions for all collection agencies in America.

When consumers turn to a financial institution for services, they want to know that their private information is being kept safe and sound. None of us want our information shared with companies we do not approve of. The Gramm-Leach-Bliley Act (GLBA) is a law that was enacted with this desire for security and privacy in mind. The act was passed in 1999 to protect consumers’ private information within financial institutions and give them the power to choose what happens with that personal information.

What Types of Businesses Are Impacted by the Gramm-Leach-Bliley Act?

The GLBA covers any institutions that provide financial services, including:

  • Handling loans
  • Handling savings
  • Exchanging or transferring funds
  • Providing financial advising
  • Investing for others
  • Career counseling (of those who are seeking employment with financial services)
  • Collecting debt
  • Banking
  • Insurance
  • Credit union

The law covers a wide variety of institutions that handle finances and can include institutions one may not expect, such as car dealerships that collect and distribute the personal information of their consumers or retailers that grant credit cards to their customers.

Protecting Your Customer’s Nonpublic Personal Information (NPI)

When a consumer decides to work with a specific financial institution, they must be able to trust that institution with their private information. Often, the information given to these institutions by their customers can be highly confidential and leave the customer vulnerable to a number of personal and legal issues should their information be shared or leaked to the wrong party.

Under the Gramm-Leach-Bliley Act, financial institutions are legally obligated to protect all of their private consumer’s nonpublic personal information (NPI). An NPI is defined as the individually identifiable financial information collected by a financial institution that cannot be found in the public domain. This can include information like:

  • Address
  • Income
  • Social security numbers
  • Payment history
  • Account information
  • Loan balances
  • Purchase history
  • Credit history
  • Consumer reports

Under the GLBA, a financial institution must uphold and ensure the safety, security, and confidentiality of any information their customers have trusted them with. A financial institution must always have security measures in place to prevent security breaches and data leaks. In order to ensure this, the Federal Trade Commission (FTC) has the power to audit any financial institution at any time. Should the financial institution have a need to share the customer’s information with an outside party, the customer must be made aware of the ways in which their information will be shared and given a choice in whether they would like to “opt-in” or “opt-out.”

The Gramm-Leach-Bliley Act and Privacy Notices

Whether you are opting in to sharing your customer’s NPI or not, the GLBA requires every financial institution to provide their customers with a privacy notice before a customer-business relationship has been established. Should this cause issues with the timeliness of completing the customer’s transactions with your business, there is an exception to this rule- as long as the client agrees, you may provide the notice within a reasonable time frame after the relationship has already been established.

Along with a privacy notice, customers must have an option to opt-out of sharing their NPI with outside parties. This opt-out notice must emphasize that the customer has a right to opt out, give a sensible method of opting out, and grant the customer a reasonable time frame to opt-out. The customer must also be given a copy of the privacy notice annually for the duration of the business-customer relationship.

The FTC’s Recent Amendments to the Gramm-Leach-Bliley Act

The FTC has recently made a few amendments to the GLBA. Due to this, multiple changes will become effective on June 9, 2023, including:

  • Risk assessments– financial institutions will now be required to maintain a formal risk management program that includes a written risk assessment
  • Designation of a single responsible and qualified individual– while it has already been required that the financial institution has designated employees overseeing the security program, financial institutions must now appoint a qualified individual to hold the ultimate responsibility of the program.
  • Employee training– this new requirement means financial institutions must ensure their staff have received proper security training from qualified personnel if they have access to private information like customer names, addresses, social security numbers, and date of birth. This training must be done regularly.
  • Monitor own providers to whom data is outsourced or serviced– financial institutions must monitor and complete risk assessments regarding the third-party service providers they are deciding to work and share information with. It is the financial institution’s responsibility to ensure the third-party vendors they share information with have the proper security measures to continue protecting their customer’s NPI.
  • Information Systems Monitoring & Penetration Testing– financial institutions must now regularly test and monitor their safeguards, systems, and procedures for any attempts at a security breach or weaknesses
  • Incident plan– a new requirement of the GLBA is that financial institutions will now be required to have a written incident response plan that addresses seven particular topics- the goal of the plan, internal processes for a response, external and internal communication, requirements for identified weaknesses, how the security event will be documented and reported, and the changes and evaluations needed to the incident plan after the occurrence of a security event
  • Specified security controls– There have now been security controls added as specific requirements to maintain GLBA compliance, including access controls, system inventory, encryption, secure software development, multi-factor authentication, data retention, change management, and system monitoring
  • Accountability of the responsible and qualified individual– the individual who has been designated the responsible party is now required to annually report their security program’s status to the executive leaders of the financial institution in order to maintain a sense of accountability and the motivation to uphold the highest security measures for customers.

In Conclusion

The GLBA has been put in place to protect consumers’ personal information from falling into the wrong hands. It is the responsibility of financial institutions to have security measures in place to protect their consumers and themselves. Staying up to date on the newest GLBA requirements can be crucial to ensuring your financial institution is doing everything you can to maintain compliance.

References:

https://www.fdic.gov/consumers/consumer/alerts/glba.html#:~:text=GLBA%20became%20law%20in%201999,insurance%20companies%20and%20securities%20firms.

https://www.ftc.gov/business-guidance/resources/how-comply-privacy-consumer-financial-information-rule-gramm-leach-bliley-act

https://globalcerts.com/wp-content/uploads/Whitepaper-2022-GLBA-Amendments.pdf

Filed Under: Debt Recovery

Industries with the Best and Worst Recovery Rates

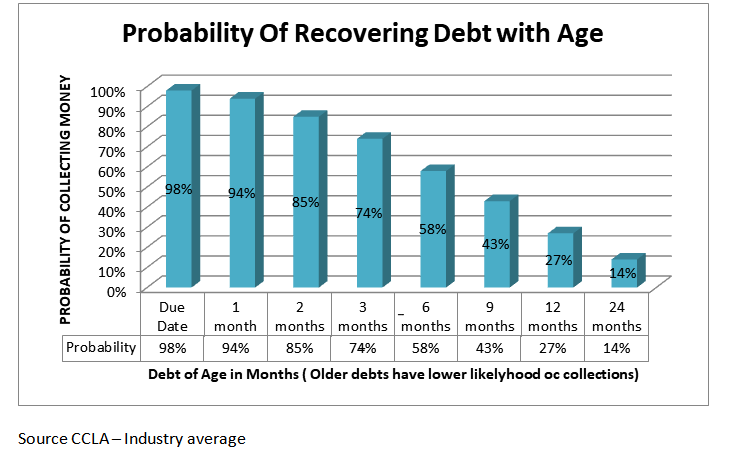
Assigning accounts for collections roughly 60-90 days past due for a maximum recovery rate is recommended.

The recovery rate dips as the account gets old. The following chart demonstrates the relationship between the Account-age and Recovery-Rate.

Debt Recovery Chances

Still, there are some industries where the average recovery rate is better than others.

Based on clients we came across last year (2021), here is the average recovery rate we have seen, along with our collection agency partner(s).

This is purely our own experience. No collection agency openly publishes the results they achieve by industry. But it should give an idea of what to expect.

Industry Recovery Rate
Transportation 84.33%
Pool Services 73.67%
Cooperative 70.39%
Propane 66.40%
Fuel/Oil 61.25%
Snow Removal 60.39%
Lawn & Garden 59.87%
Printing 58.19%
Plumbing, Heating, Air 53.30%
Engineering 52.95%
Interior Design 52.90%
Mortgage 48.11%
Travel Agent 44.18%
Distribution 43.30%
Medical / Athena 42.46%
Construction 41.49%
Publishing 40.78%
Credit Unions 40.27%
Retail/Consumer Misc. 39.72%
Pest Control 38.95%
Auto Supply & Repair 38.02%
Restoration Companies 37.73%
Commercial 36.95% – 85%
Contractors, Special Trade 36.76%
Industrial 36.38%
Optometrists 36.27%
Dental 33.29%
Repair Services 31.59%
Waste Management 31.40%
Funeral Services 31.09%
Day Care 29.55%
Business Services 29.43%
Government 28.38%
Utilities 28.36%
Farm Supply 27.52%
Auto Dealers 27.04%
Fire 26.65%
Telephone Communications 25.48%
Member Organizations 25.13%
Elementary/ High School 24.59%
Personal Services 22.83%
Schools Misc. 22.78%
CPA / Accounting 22.16%
Security 21.63%
Trucking, Nonlocal 21.34%
Clothing 20.86%
High Tech 19.87%
Veterinarian 19.25%
Advertising 19.17%
Drug Store 19.11%
Aviation 19.07%
Medical Supplies 18.03%
Rentals, Equip, etc. 17.71%
Newspaper 17.48%
Non Profit 17.28%
Hotel 17.21%
Manufacturing 17.08%
Pharmaceutical 17.00%
Wholesale, Durable 16.94%
Social Services Misc. 16.66%
Insurance 15.38%
Real Estate Management 15.34%
Media 15.22%
Bank 14.93%
Computer Services 14.90%
Bail Bonds 13.97%
Nursing Homes 13.87%
Medical Other 12.94%
College/Univ/ Prof. School 12.08%
Gym/Sports Org 11.41%
Electronics 10.25%
Legal Services / Lawyers 9.94%
Cleaning Service 9.06%
Accounting 8.40%
Moving / Storage 8.32%
Chiropractor 8.26%
House Rent Collection 6.96%

Commercial accounts (B2B) have a better recovery rate than (B2C) accounts.


Filed Under: Debt Recovery

Can I Hire Multiple Collection Agencies at One Time?

You can legally hire more than one collection agency at a time, provided you do not assign the same account to multiple collection agencies. If one debtor starts getting contacted by different agencies, you can be sued for harassment. 

However, hiring more than one collection agency will be very hard to manage. Keeping track of which accounts have been assigned to Collection Agency “A” and others to Collection Agency “B” is always confusing. Then each collection agency has its own way of recovering the debt. Two different client portals training will be required, and each agency will have separate ways and dates when they pay you or raise an invoice to bill you. Moreover, whenever a debtor calls you directly to make a payment or discuss something else about his debt, you will have to figure out which collection agency has the account of this debtor. It can be quite confusing. 

When does it make sense to hire two collection agencies?

  1. Transitioning from Agency A to Agency B: You want to fire your existing collection agency “A” ( say you are unsatisfied with their collection results). Meanwhile, you start assigning all new accounts to this collection agency “B”. Eventually, all your accounts to your old collection agency “A” complete their collection lifecycle, and you are left only with the new collection agency “B”.
  2. You are a large company with multiple offices across US. You also have hundreds or thousands of accounts that require collections every month. You decide to hire collection agency “A” for one set of offices and collection agency “B” for other offices. Both collection agencies will work hard to give you better results since you are such a large account for them. They will always have a fear of losing you.

Overall, we recommend that you hire only one collection agency that is licensed nationally. Do your due diligence to shortlist the best one.

Filed Under: Debt Recovery

Contingency Collections: Is it the best Debt Recovery Service?

Collection agencies typically offer two types of collection services to their clients. “Fixed Fee” and “Contingency Only” services.

In the Fixed fee service, a collection agency sends multiple written demands only.

In the Contingency service, one written debt validation notice is sent, followed by collection calls from an experienced debt collector.

Although the sales guy from the Collection Agency may attempt to sell you a “Fixed Fee” service that costs around $20 an account. Fixed fee may appear more beneficial after hearing all the sales pitch, however, it may not be the best service for you. The biggest advantage a collection agency gets is that the moment you buy their “Fixed Fee” service, they have made money from you even before a single account is placed for collections. 

Unless your accounts are less than 180 days past due, the “Fixed Fee” service may be of little help. After the collection agency fails to recover money for you in the “Fixed Fee” service, they will later insist that you should transfer accounts to the contingency service.

Why go for the “Contingency Only” service?

  • No upfront fee is involved.
  • A collection agency makes money only if they collect for you.
  • Credit Bureau reporting is done for free by most agencies.
  • Calls from a debt collector are more impactful than written demands. 
  • Most agencies do USPS change of address checks only in Fixed fee service. They do not perform skip-tracing, a more accurate tool for locating the debtor and his phone number. In Contingency service, almost all collection agencies rely on skip tracing.
  • A debt collector can negotiate payment terms even with those tricky debtors. For example, he may put the debtor in installments or settle the amount in one lump sum payment slightly lower than the original amount due.
  • A debt validation letter is sent out anyway, even during the Contingency only service; therefore your debtor knows the account is with a collection agency. So you do get a considerable benefit from this written demand as well.
  • A collection agency takes all the headaches involved in the negotiation and takes money from the debtor. In a fixed-fee service, you have to be the one to manage payment acceptance and negotiation. 
  • You just have to notify the collection agency of any payments received from the debtors directly to you. Other than that, sit back, and you will receive the monthly checks for the amount collected.

When is the Fixed Fee service beneficial?

In our experience, it is a better service only if your accounts are no more than 180 days past due. If accounts are less than 120 days past due, it will most likely result in significant cost savings over contingency collections.

If you want less hassle-based recovery, go for Contingency Only collections.

Filed Under: Debt Recovery

What to Do When Your Collection Agency Closes: How to Transfer Accounts?

You had submitted accounts to a collection agency, but they have ceased their operations now.

This is a fairly serious situation.

What happens to the accounts they were working on, and what about those debtors in the middle of a payment plan?

Are there any legal aspects involved?

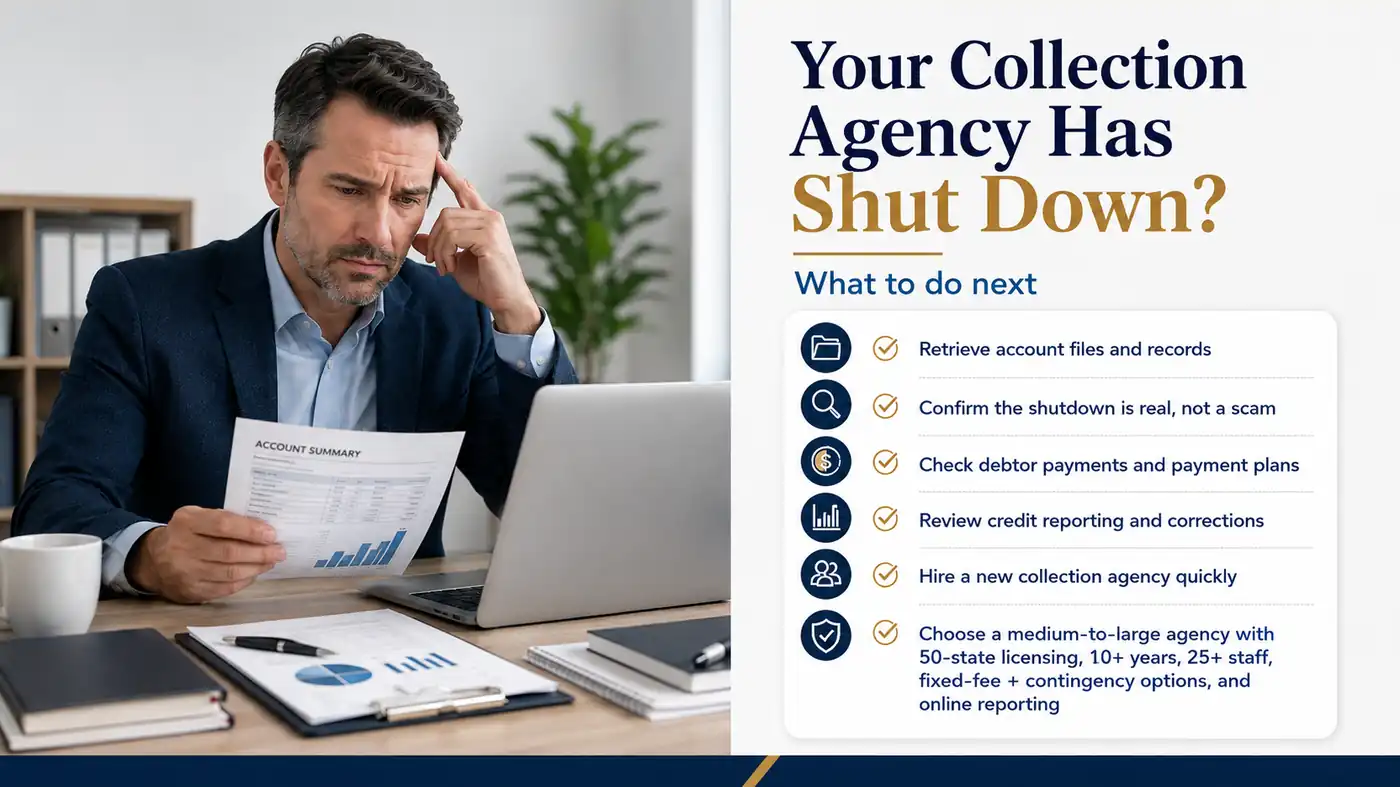
Concerned business owner reviewing account records after a collection agency shuts down, with steps to protect payments and transfer accounts.

What about the charges that were credit reported? If there is a need to undo the credit reporting for a debtor (say due to some error), how will that be handled?

  • Try to retrieve any files, account data, or documentation they have regarding your accounts. Keep records of all communications with the collection agency. If your debtors have made payments to the agency or have arranged a payment plan.
  • Explore any potential claims you may have against the agency.
  • Are they notifying your debtors about the shutdown and any instructions on how their debt will be handled in the future?
  • If the agency was responsible for reporting to credit bureaus, ensure this information is accurately reflected as needed. Make sure that any payments your debtors have made are reported. After evaluation, it may just be better to withdraw all credit reporting submitted by that collection agency for your debtors.
  • Double-check that the agency has shut down and that this isn’t a mistake or a scam.

There is a possibility that your old collection agency is not cooperating or is simply unreachable. Their phones don’t work and they have abandoned the office.


Next, Hire a new Collection Agency. Your priority this time is to look out for a mid-to-large-sized collection agency, regardless of their location. Smaller agencies always carry the risk of shutting down.

Your new collection agency should be able to guide you through the transition process, minimizing the risk. Share all updates that have been received from your old collection agency.

There is a systematic procedure to hand over accounts from one collection agency to another that is legally compliant and convenient. Not all collection agencies are experts in handling this transition.

Need a new collection agency: Contact us today
Please mention that your existing agency has closed, and we’ll make the transition easy.

Why Collection Agency Closures Are Happening More Often?

Many collection agencies have shut down recently, and the pressure hasn’t let up. The reasons compound on each other:

  • Regulation F: The CFPB’s Regulation F took effect November 30, 2021 and remains the most significant update to debt collection law since the FDCPA itself. It set a hard “7-in-7” call frequency limit, more than seven calls in seven consecutive days about a particular debt, or calling again within seven days of a prior conversation about it, creates a presumption of harassment. It also formalized rules for email, text, and social media contact, each requiring a working opt-out mechanism, and introduced a model validation notice format. Many smaller agencies found it cheaper to close than to rebuild call scripts, dialer logic, and notice templates around these requirements. And the tightening hasn’t stopped: New York City’s own local rule, taking effect in September 2026, cuts the limit to just three contact attempts in seven days and extends it to original creditors, not just third-party collectors, a preview of where local and state rules may be headed elsewhere.
  • Debtors aren’t picking up the phone the way they used to. Carrier-level spam filtering and caller ID apps now flag collection-agency numbers as “Spam Likely” or “Scam Likely” at scale. Branded, authenticated calls answer around 62% of the time; unbranded numbers sit closer to 20%, and a number tagged “Spam Likely” is mostly ignored outright. One bad labeling event can drop a number’s answer rate 20-50% overnight, and industry surveys show a majority of businesses have lost real revenue to incorrect spam flagging, some losing well over $100,000. An agency still relying on a pure cold-call playbook is fighting a connection problem that didn’t exist a decade ago.
  • Credit Bureau Reporting changes, and they’ve only gotten more restrictive. Starting July 2022, the top three credit bureaus made it harder to report medical debt. Since then, several states, including California, Colorado, North Carolina, and Maryland, have gone further and banned medical debt credit reporting outright. The CFPB’s own broader federal rule on this was vacated in July 2025, an unresolved legal question that leaves some of these state bans in a genuinely uncertain position, but the direction of travel is clear. Medical debt makes up nearly half of consumer debt collections, and “credit damage” as a collection lever has been steadily losing its force for several years now.
  • Compliance infrastructure costs keep stacking up. The Gramm-Leach-Bliley Act, effective for collection agencies since June 2023, requires securing consumer data nearly the same way a bank does. That’s on top of state-by-state licensing, many states require a surety bond, some license third-party agencies but exempt original creditors, and the specific requirements rarely match from state to state, plus SOC 2 audits and HIPAA obligations for any agency touching medical accounts. For a small agency, this isn’t one cost, it’s a compounding stack of them, and it’s a genuine reason the math on staying in business stops working.

What to Look in your new collection agency

  • Most collection agencies that shut down were small collection agencies. Hiring medium-sized collection agencies with the license to collect consumer and commercial debt across the USA is always advisable.
  • They should have a staff of more than 25 people and in business for more than 10 years.
  • Immediately hire a collection agency (without delay) because there may have been quite a few of your debtors who were about to pay or were paying their debt in installments.
  • Hire a collection agency that offers both fixed fee and contingency fee collections. Accounts less than 90 days past due should ideally be submitted for fixed fee collections.
  • You should also be able to download a collection performance report for all your accounts online.
  • They should have the license to collect money in all 50 states, which takes care of issues in case your debtor crosses state lines.
  • Ask whether bankruptcy and litigious-debtor screening happens on every account before contact, not just when something goes wrong. A smaller, under-resourced agency may skip this step entirely, and that exposure ultimately lands on the creditor whose name is on the account, not just the agency.

How Nexa Handles Your Portfolio Transition

Moving accounts from a shut-down or struggling agency to a new one is not a flip of a switch, and any agency that promises it will be shouldn’t be trusted on that promise. The prior agency often doesn’t cooperate. Phones may go unanswered, records may be incomplete or missing entirely, and the timeline depends as much on what the old agency will or won’t provide as it does on how fast the new one moves. This is a careful, deliberate process, not a fast one.

What Nexa actually does with an incoming portfolio:

  • Verify chain of title on each account, confirming what documentation exists and what’s missing before anything else happens.
  • Run a fresh address and bankruptcy scrub on the full portfolio, since accounts sitting idle during a shutdown or transition often have outdated contact information or new bankruptcy filings that need to be caught before any further contact is made.
  • For transferred accounts with existing disputes, active legal representation, or prior cease-and-desist notices, files must be reviewed on a case-by-case basis. Seamless transition requires basic cooperation from your prior agency to provide account histories, dispute notes, and attorney contact details to maintain full FDCPA compliance
  • Validate remaining statute of limitations on every account individually, since accounts that sat idle during a shutdown may be closer to their legal deadline than the paperwork suggests.
  • Re-engage aged balances cleanly, with a compliant first-contact sequence rather than picking up wherever the prior agency left off, since the debtor’s own history with that agency (including its shutdown) is now part of the account’s context.

This takes real time to do properly, and Nexa would rather tell a prospective client that upfront than promise a seamless handoff that doesn’t reflect how this actually works.


Frequently Asked Questions

What should I do if my collection agency suddenly shuts down?

This requires your immediate attention. Start by securing your account files, debtor contact information, payment histories, dispute records, payment-plan details, and credit-reporting status. Confirm which accounts are still active and whether the agency is holding any debtor payments. Make this process quick as your accounts data may become unavailable after they completely shut operations. Then identify a replacement collection agency that can review the portfolio and manage the transition without unnecessary interruption. The longer accounts sit untouched, the harder they may become to recover.

Can I transfer uncollected accounts from my old collection agency to Nexa?

Yes. Accounts can generally be reassigned after they have been properly closed or withdrawn from the previous agency and the account status has been documented. Nexa should be informed of any existing disputes, attorney representation, cease-communication requests, bankruptcies, settlements, or payment arrangements before collection activity begins. Federal rules place specific restrictions on communications involving disputed accounts, cease requests, and consumers represented by attorneys.

What happens to debtors who were already making payments when the collection agency closed?

These accounts need special attention. Obtain a complete payment ledger showing amounts already paid, remaining balances, payment-plan terms, and any funds still held by the former agency. Debtors should receive clear instructions about where future payments should be made so they are not confused or contacted for amounts they have already paid. Accounts should be reconciled before a new agency resumes collection activity.

What happens to credit reporting if my old collection agency goes out of business?

First determine which accounts the previous agency reported and whether balances, payments, settlements, or disputes are accurately reflected. A replacement agency should not simply assume that the former agency’s credit-reporting information can be transferred unchanged. Credit-reported accounts should be reviewed individually so reporting remains accurate and any necessary updates or corrections can be addressed.

Should transferred accounts use fixed-fee or contingency collections?

It depends largely on the age and condition of the account. Newer accounts that have not undergone extensive collection activity may be suitable for Nexa’s fixed-fee service, starting around $15 per account, where you keep 100% of payments received. Older, difficult, disputed, or heavily worked accounts may be better suited to contingency collections, where the collection agency is paid only when it successfully recovers money.

How do I avoid hiring another collection agency that could shut down?

Look beyond the contingency rate. Evaluate the agency’s years in business, nationwide licensing capabilities, data security, compliance program, staffing, client portal, online reputation, industry experience, and ability to handle both consumer and commercial accounts. Data security is particularly important: the FTC specifically includes collection agencies among the financial institutions covered by its Safeguards Rule, which requires covered businesses to maintain appropriate protections for customer information.

Filed Under: Debt Recovery

  • « Go to Previous Page
  • Page 1
  • Interim pages omitted …
  • Page 19
  • Page 20
  • Page 21
  • Page 22
  • Page 23
  • Interim pages omitted …
  • Page 55
  • Go to Next Page »

Primary Sidebar


accounts receivable

Need a Collection Agency?
Kindly fill this form.
We’ll get in touch with you

    Please prove you are human by selecting the key.

    Compliance & Security

    • SOC 2 Type II Certified: Third-party audited data security and strict privacy controls.

    • HIPAA Compliant: Secure, legal processing of medical and municipal EMS accounts.

    • PCI-DSS Level 1: Highest tier of data encryption for secure payment processing.

    • FDCPA & FCRA Aligned: Full legal adherence to federal consumer protection laws.

    Recent Posts

    • Why Dental Patients Dispute Bills: The Nexa Collections Dental Account Dispute Index
    • 2027 Commercial Collections Benchmark: U.S. Late Payments, AR Risk and B2B Collection Trends
    • Bulk Account Placement: What a Collection Agency Actually Needs From You
    • Nationwide Debt Collection Agency Serving U.S. Cities
    • Chula Vista Collection Agency for Medical, B2B, Schools & Business Debt
    • Corpus Christi Collection Agency: Itemized Bill Rules for Practices
    • Riverside Collection Agency | For Logistics, Medical, Schools & Business Recovery
    • Collection Agency for Large Balances: High-Value B2B Debt Recovery

    Featured Posts

    • Collection Agency Near Me: Licensed Recovery for Local Businesses
    • Navigating Canada’s Debt Collection Landscape: Laws, Ethics and Regulations
    • How are Dental Digital Impression Created: Benefits & Types

    Copyright © 2026 NEXACOLLECT.COM | This content is provided for general informational purposes only and should not be considered legal advice. Collection laws and requirements may vary by state, account type, documentation, debtor status, and specific facts. Please consult qualified legal counsel for guidance regarding your particular situation. Nexa and its authorized collection partners service accounts in accordance with applicable federal and state collection requirements. Visit our home page to know more about us.

    X
    Need a Collection Agency?
    Contact Us