• Skip to main content
  • Skip to primary sidebar

Nexa Collections

  • Home
  • Serving
    • Medical
    • Dental
    • Small Business
    • Large Business
    • Commercial Collections
    • Government
    • Utilities
    • Fitness Clubs
    • Schools
    • Senior Care Facility
  • Contact Us
    • About us
    • Cost

Debt Recovery

The Collection Agency School Districts Trust With Their Reputation

A collection agency’s worst outcome for a school district isn’t a low recovery rate. It’s a parent posting a screenshot of an aggressive collection call on the district Facebook group the week before a bond referendum.

Every dollar recovered the wrong way costs more in trust than it returns in cash. That’s the entire premise behind how Nexa works with school districts, and it’s why districts nationwide, several of whom are current clients seeing genuinely strong recovery results, have moved their unpaid balances to a partner built specifically for public education rather than a generic commercial collector wearing a school-friendly logo.
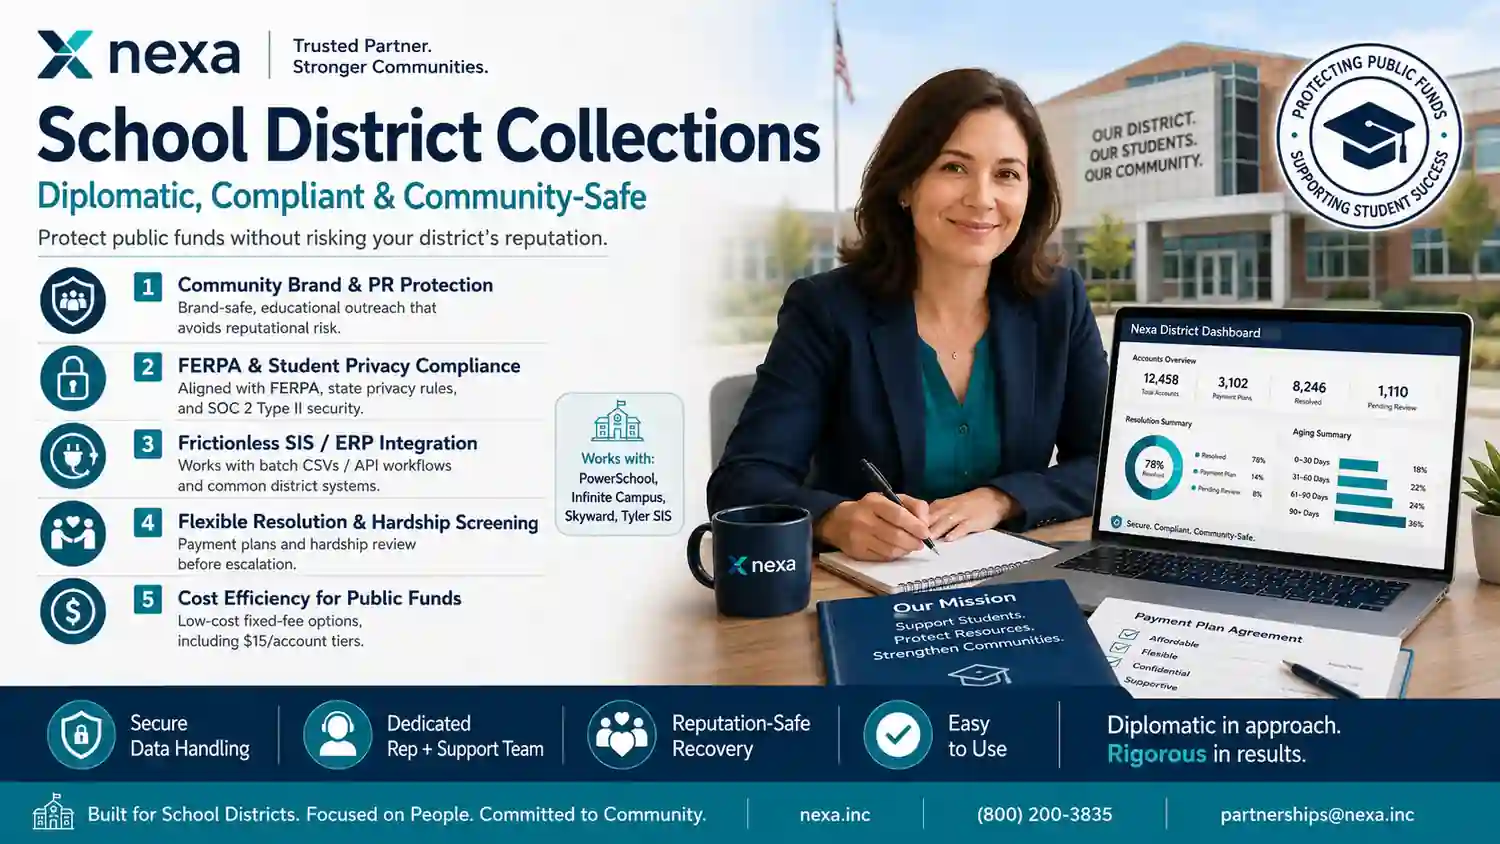
School district collections service with FERPA-aware privacy, reputation-safe recovery, secure data handling, flexible payment options, SIS integration, and cost-effective account recovery.


Quick answer: School districts recover unpaid meal, device, and activity balances most effectively through diplomatic third-party mediation, not aggressive collection tactics. Because a child’s school standing is involved, families respond quickly to an official, credible notice once they realize a balance is genuinely overdue, often faster than to another portal reminder buried in daily school communications. Nexa works with public districts, charter networks, and private schools under FERPA’s school-official exception, offering a $15 fixed-fee option (districts keep 100% of recovered funds) alongside contingency recovery for aged accounts, with SIS-compatible batch uploads and strict anti-lunch-shaming-aware communication standards.


Nexa provides reputation-safe,  parent friendly, 50-state collections license with free skip tracing, litigious debtor check and bankruptcy scrubs, and zero hidden or onboarding fees on both fixed-fee and contingency models. Secure – SOC 2 Type II & FEPRA compliant. Easy to use, and references available upon request.

Need a Collection Partner for Your District? Contact us


Why Recovery Rates Run Higher Than Districts Expect

A parent portal notice competes with dozens of other messages in a given week. An official third-party notice doesn’t. It signals, correctly, that a balance has moved past the point of routine reminders, and because it involves a child’s account standing, families tend to act on it promptly rather than letting it sit in an inbox. This isn’t aggressive pressure, it’s simply cutting through genuine notification fatigue with something that reads as serious without reading as hostile.

Third-party mediation also does something a district’s own staff structurally can’t: it creates distance. A front-office employee who has to see a family at pickup every day is in a difficult position pursuing a balance directly. A neutral third party absorbs that friction, letting the district maintain the same warm, welcoming relationship with the family it had before the balance became a problem.


What Districts Actually Look For in a Collection Partner

Public reputation and PR safety come first, not last. 

Zero heavy-handed tactics, full brand protection, and a tone that could be read aloud at a school board meeting without anyone flinching. This isn’t a nice-to-have for a public institution, it’s the primary selection criterion.

Real FERPA compliance, not a badge. 

Student financial data is shared under FERPA’s school-official exception, which requires a formal written agreement, use limited strictly to the collection purpose, and the district retaining control over how that data is used. SOC 2 Type II certified security and encryption back this up operationally.

Administration that doesn’t create work for already-stretched staff. 

A dedicated account manager, simple batch Excel uploads, and direct compatibility with the SIS platforms districts already run, PowerSchool, Infinite Campus, Skyward, and similar systems, so placing accounts doesn’t mean building a new workflow from scratch.

Transparent, genuinely taxpayer-friendly pricing. 

A $15 flat fixed fee for earlier-stage accounts, with the district keeping 100% of what’s recovered, and contingency pricing reserved for older, harder-to-recover balances. Public funds deserve a pricing model a board member can explain in one sentence.

Licensing that doesn’t create a gap. 

Active licensing across all 50 states means a family that relocates mid-collection doesn’t cause the account to simply stall.


The Balances Districts Actually Place

  • Unpaid meal and cafeteria balances, handled in a way that’s aware of, and consistent with, state anti-lunch-shaming requirements from the first contact.
  • 1:1 device and technology fees, damaged, lost, or unreturned Chromebooks, tablets, laptops, and mobile hotspots, an increasingly large category as 1:1 programs have become standard.
  • Extracurricular, athletic, and activity fees, sports participation, instrument rental, club dues, and field trip balances.
  • Textbook, library, and course material replacement costs.
  • Early childhood, Pre-K, and extended-day/after-school program balances.
  • Dual-enrollment, AP, and exam or lab fee balances, an account type that’s often overlooked until it accumulates across a graduating class.

Why Gentle, Respectful Outreach Actually Works Better Here

Heavy-handed tactics don’t just risk one family’s goodwill in a school district context, they risk becoming a story. A Pennsylvania district drew national attention after sending letters implying unpaid lunch debt could lead to a child’s removal from the home. Minnesota districts drew similar attention after considering barring students with meal debt from their own graduation ceremony, a plan state officials stepped in to stop. Neither of these recovered more money than a calm, well-documented process would have; both cost the districts involved real public trust.

The alternative that actually works: clear, empathetic communication explaining the balance, flexible installment plans, an accessible online parent payment portal, and a genuine, fast path to dispute resolution when a family believes a charge is wrong. Families experiencing documented financial hardship are routed toward the district’s own assistance programs rather than pursued as a standard account, since collecting from a family that genuinely cannot pay isn’t a collections problem, it’s a policy question the district should be handling directly.


Worth Knowing: Pending Federal Legislation on Meal Debt Specifically

A federal bill, the No Shame at School Act, has been reintroduced in Congress and would specifically prohibit districts from hiring debt collectors to pursue school meal balances. It has not passed. This doesn’t change what’s legally available to districts today, but it’s a genuine signal of where policy attention on meal debt specifically is heading, and it’s part of why Nexa’s approach to meal balances in particular leans toward the gentlest end of the outreach spectrum: clear communication and payment plans first, with collection escalation used sparingly and only after every softer option has been offered.


What This Costs

Nexa Collections fixed-fee and contingency pricing structure

Early-Stage Fixed Fee ($15/account). A structured sequence of respectful, official-sounding notices for accounts still fresh. The district keeps 100% of what’s recovered. See the full pricing breakdown.

Contingency Recovery. For older, harder-to-reach accounts, no recovery, no fee, with free bankruptcy scrubs and skip-tracing/address verification included before any account is actively worked.


Why Districts Choose Nexa Specifically

  • 100% reputation-safe communication, reviewed against the same standard a school board would apply.
  • Two flexible recovery tiers, so a district isn’t paying contingency rates on accounts that would resolve with a simple, low-cost notice.
  • SIS-compatible batch processing, no manual re-entry for PowerSchool, Infinite Campus, Skyward, or similar platforms.
  • SOC 2 Type II data security, FERPA-aware handling, FDCPA and CFPB Regulation F compliance, and a dedicated account manager who understands public education specifically, not commercial collections dressed up for schools.

Frequently Asked Questions

Is it legal and FERPA-compliant for a school district to use a collection agency?

Yes, when it’s structured correctly. FERPA’s “school official” exception allows a district to share necessary financial data with a collection agency without separate parental consent, provided the agency performs a service the district would otherwise handle itself, is formally designated under the district’s FERPA notice, and remains under the district’s control over how the data is used. This requires a written agreement between the district and the agency, it isn’t automatic simply because the agency claims compliance.

How does Nexa handle unpaid school meal balances without violating state anti-lunch-shaming statutes?

By treating meal debt as the most sensitive account category by default, not an edge case. At least 15 states have specific anti-lunch-shaming laws, and common requirements, meals aren’t withheld regardless of balance, and communication goes confidentially to parents rather than identifying a student publicly, are built into how meal accounts are handled from the first contact, not added after a complaint.

What happens if a family experiences documented financial hardship?

Hardship accounts are routed toward resolution and the district’s own assistance programs rather than pursued as a standard collection. The goal is matching the response to the actual situation, a family that genuinely cannot pay needs a different conversation than one that’s simply overlooked a bill, and treating both identically is where reputational damage tends to start.

How do parents typically respond when an outside collection agency contacts them about school fees?

Generally faster and more directly than they respond to internal reminders, since an official third-party notice reads as a clear signal that a balance needs real attention, cutting through the volume of routine school communications most parents receive weekly. This isn’t about pressure, it’s about a message that’s distinguishable from the noise.

Does COPPA apply to school debt collection?

No, and this is worth being precise about rather than repeating a common assumption. COPPA governs commercial websites and online services that collect personal data directly from children under 13, and it explicitly does not apply to schools or districts as “operators.” School debt collection involves contacting parents about a financial balance, not collecting data from a child through an online service, so COPPA simply isn’t the relevant framework here; FERPA is.

How does Nexa’s $15 fixed-fee model actually save money for taxpayer-funded districts?

By pricing per account rather than as a percentage of the balance recovered, so the district keeps the full amount collected instead of losing a third or more to a traditional contingency fee on every account. For the large volume of smaller-balance accounts, meal debt, activity fees, minor device charges, that a district typically carries, this difference compounds significantly across a full aging report compared to a contingency-only model.
Talk to Us About Your District’s Receivables

Filed Under: Debt Recovery

How Dental Insurance Denials Turn Into Patient Debt (And How to Stop It)

Quick answer: A dental insurance denial becomes patient debt when the shifted balance reaches the patient without a clear explanation, and the practice has no structured process for appeal, communication, and follow-up before the account ages past the point of easy recovery. Most claims can still be appealed within 30 to 180 days of denial, most patient statements go unpaid simply because they’re confusing, and most practices should refer an account to collections between 90 and 180 days of unsuccessful internal follow-up, since collectability drops sharply after that window.

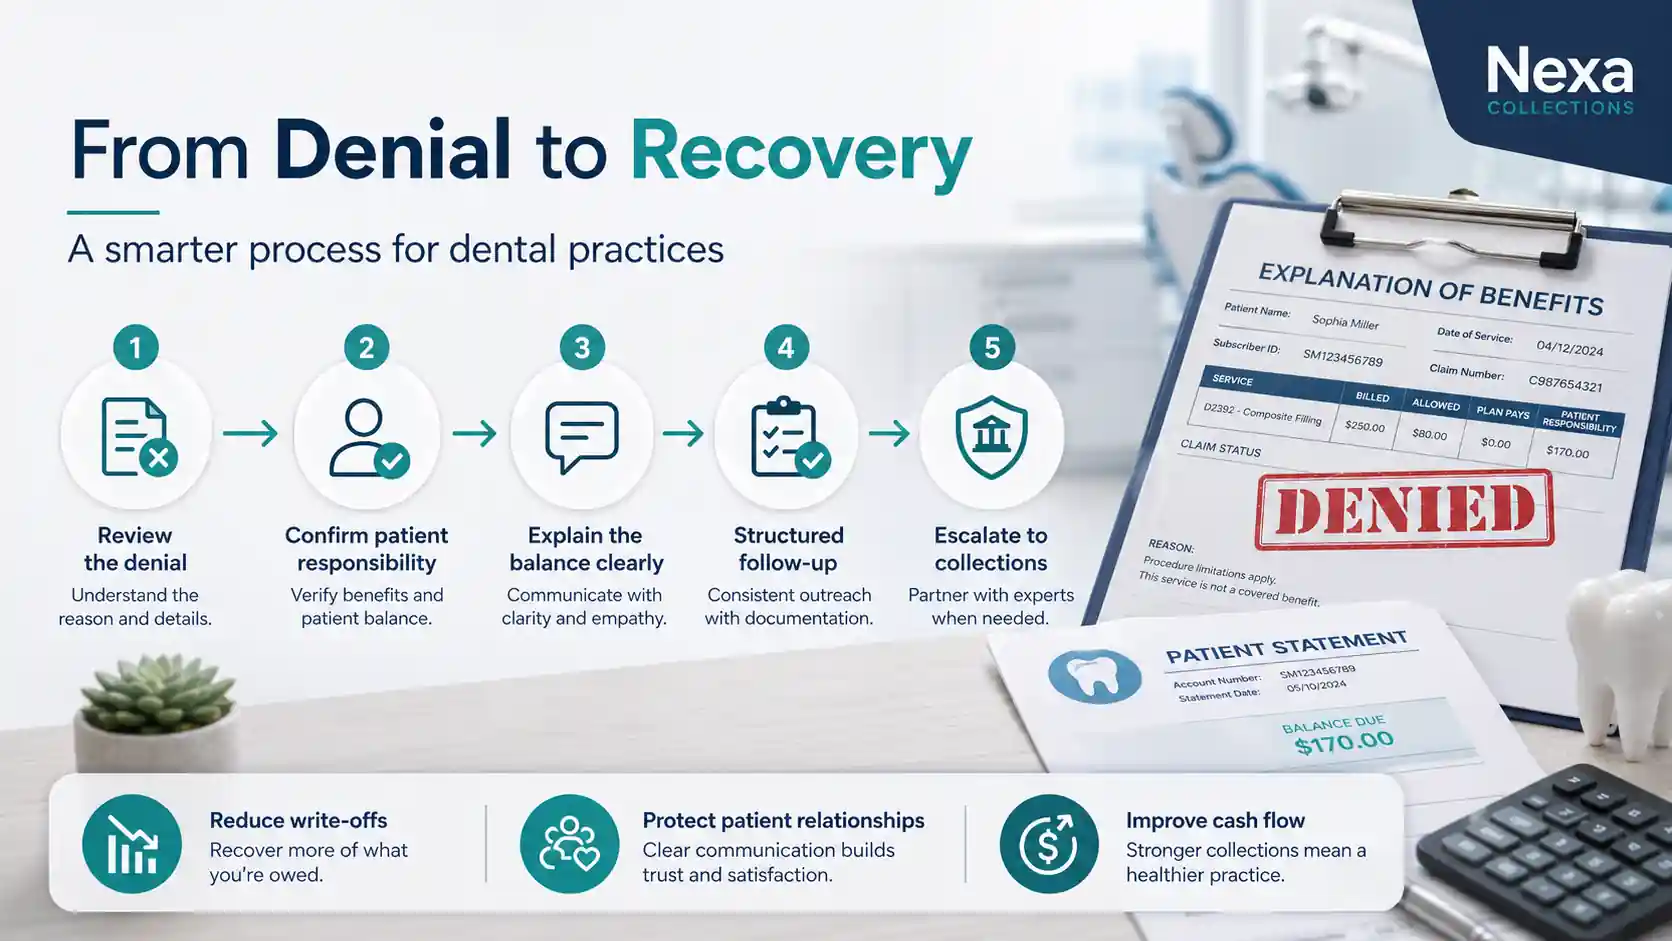
Dental insurance denial recovery process helping practices reduce write-offs and recover patient balance

Need help with unpaid dental balances? Contact us


Why a Denial Turns Into a Debt Problem, Not Just a Billing Problem

The claim gets denied. Weeks pass. The practice, trying to keep the ledger current, sends a statement. The patient, who assumed insurance was handling it, has no idea why they suddenly owe $340. That gap, between the denial and an explanation the patient can actually understand, is where a solvable billing issue turns into an unpaid balance.

This isn’t a small or occasional problem. More than half of dentists cite denied or delayed insurance reimbursement as a top practice challenge, and initial denial rates typically run 5–15% of submitted claims depending on payer mix and documentation quality. Across a full patient panel, that’s a meaningful share of production sitting in limbo at any given time, and most of it is genuinely recoverable if the process behind it is right.

What Actually Causes Dental Claims to Get Denied

Treating every denial as a single category leads to the same generic response every time, appeal and hope. The reality is more specific, and knowing the category changes both the appeal strategy and the odds of success.

  • Missing or incomplete documentation. Narratives, radiographs, or periodontal charting that didn’t accompany the original submission. Often the fastest and highest-odds appeal, since the fix is simply attaching what should have been there.
  • Frequency limitations exceeded. The plan covers the procedure, but not this often, this year. Appeals here rarely succeed unless there’s a documented medical necessity for the exception.
  • Non-covered service. The plan simply doesn’t include the procedure. These are usually not appealable in the traditional sense; the conversation shifts to patient financial responsibility from the start, which is exactly why clear, upfront communication before treatment matters.
  • Bundling or down-coding. The payer reclassified the procedure as part of a broader code, or paid at a lower-complexity rate than billed. These require a specific, documented rebuttal tied to the actual clinical findings, not a generic appeal letter.

Knowing which category a denial falls into before drafting an appeal is the difference between a productive fifteen minutes and a wasted one.

Before You Bill the Patient: Confirm You’re Actually Allowed To

Appeal first. Billing a patient before the insurance process is exhausted, before the final EOB actually confirms patient responsibility, is one of the more damaging mistakes in dental billing, and it isn’t only a relationship problem.

In-network providers have signed an agreement with the payer, and that agreement can restrict balance-billing for certain denial categories, particularly when the denial traces back to a practice-side error like a missed timely-filing deadline or a documentation gap. Billing the patient for a balance the practice isn’t contractually entitled to collect isn’t just bad optics; it can be a breach of the provider agreement itself. Out-of-network providers generally have more flexibility, but “more flexibility” isn’t “no rules,” and a denial tied to exhausted benefits behaves differently than one tied to a coding dispute.

The practical rule: don’t bill until the final EOB has actually established what the patient owes. Most carriers allow 30 to 180 days for an appeal from the denial date.

Does the No Surprises Act Protect Patients From These Bills?

Almost certainly not, and this is worth stating clearly because the assumption runs the other way. The No Surprises Act’s balance-billing protections, the part most people mean when they invoke it, apply to emergency care and certain out-of-network care at in-network facilities. Dental insurance is virtually always classified as an “excepted benefit” plan under federal regulation, which places routine dental care outside those protections entirely.

What the NSA does require, and this genuinely applies to dental practices: a Good Faith Estimate must be given to uninsured or self-pay patients before treatment, generally within three business days of scheduling or request, under 45 CFR 149.610. If the actual bill comes in $400 or more above that estimate, the patient can formally dispute it through the federal Patient-Provider Dispute Resolution process. A denied-claim patient who was insured at the time of treatment generally falls outside this specific protection, but a practice that failed to provide a required estimate to an uninsured patient has real exposure regardless of how the claim itself was handled.

How to Communicate a Denial So the Patient Actually Pays

The single highest-leverage sentence in dental billing may be this one, placed directly on the statement: “Your insurance claim was denied. That is why you are receiving this bill.” Patients who understand why they owe money pay faster, respond to follow-up more readily, and, when they’re frustrated, direct that frustration at the insurer rather than the practice that treated them. A statement with a dollar amount and no context gets set aside, not paid.

We leverage state prompt-pay statutes (e.g., Texas Insurance Code § 843.338, California Insurance Code § 10123.13) to enforce 30-day interest penalties on clean EDI 837D claims.

The Internal Follow-Up Window Before Escalation

A structured sequence, generally running 90 days, gives a practice its best shot at resolving the balance without outside help:

  • Day 30: Initial statement with the denial explanation attached, plus a first follow-up contact.
  • Day 60: Second notice, ideally offering a payment plan, since a debtor who understands the balance but is under financial strain will often commit to a schedule they can actually keep.
  • Day 90: Final notice with clear next steps, including that continued non-payment moves the account toward professional collection.

Document every contact: date, method, outcome. That record protects the practice twice over, it keeps the billing team aligned on where each account stands, and it demonstrates the practice made a genuine effort if the account does eventually move to a collection agency.

When to Hand the Account to a Collection Agency

Most dental practices refer accounts to collections after 90 to 180 days of unsuccessful internal follow-up, and earlier tends to outperform later. Collectability drops to roughly the mid-70s percent range once an account passes 90 days past due, and falls below half by around nine months. Waiting longer doesn’t protect the patient relationship; it just lowers the odds of ever collecting the balance at all.

The clearer signals that an account is ready: no response across multiple documented contacts, a dispute the practice genuinely cannot resolve internally, or a patient who can no longer be located. Any one of those, following a real internal effort, is a reasonable trigger.

Nexa’s dental debt collection services are built specifically for this handoff, HIPAA-compliant, dental-specific, and diplomatic by design, since most of these balances trace back to insurance confusion rather than an unwillingness to pay. See the full pricing structure for how fixed-fee and contingency options compare for accounts at this stage.

Frequently Asked Questions

Who is actually responsible for a dental bill after an insurance denial?

Generally the patient, once the final Explanation of Benefits confirms the balance as patient responsibility, but whether the practice is allowed to bill for it depends on the provider’s network status and the denial reason. In-network providers can be contractually restricted from balance-billing patients for certain denial categories, particularly ones caused by a practice-side error like a missed filing deadline, so the final EOB should be treated as the trigger for billing, not the initial denial notice itself.

Does the No Surprises Act protect patients from a denied dental claim balance?

Generally no. The NSA’s balance-billing protections apply mainly to emergency care and certain out-of-network hospital-facility scenarios, and dental insurance is almost always classified as an excepted benefit plan that falls outside those specific protections. The part of the NSA that does apply to dental practices is the Good Faith Estimate requirement for uninsured or self-pay patients, which carries its own separate dispute right if the final bill exceeds the estimate by $400 or more.

What’s the fastest way to know if a denial is worth appealing?

Identify which category it falls into before drafting anything. A denial for missing documentation is usually a fast, high-odds fix, attach what should have been submitted originally. A denial for a non-covered service or an exceeded frequency limit is rarely worth a generic appeal and is better handled as a direct, upfront conversation with the patient about financial responsibility.

What should a patient statement actually say after a denial?

It needs one clear sentence explaining why the balance exists, something as simple as noting the claim was denied and that’s the reason for the bill. Statements that show only a dollar amount with no context are the single biggest reason denied-claim balances go unpaid, since patients who don’t understand a bill tend to set it aside rather than call to ask about it.

How long should a dental practice wait before sending a denied-claim balance to collections?

Most practices refer accounts after 90 to 180 days of documented, unsuccessful internal follow-up, and earlier referral generally produces a better outcome than waiting. Collectability declines significantly once an account passes 90 days past due, so the trigger is worth setting as a firm policy rather than a case-by-case judgment call that tends to drift later than it should.

What should a practice look for in a collection agency for denied dental claims?

HIPAA compliance is non-negotiable given the health information involved, and dental-specific experience matters because most of these accounts stem from insurance confusion or financial hardship rather than deliberate non-payment, which calls for a different tone than standard commercial collections. A contingency-based fee structure, or a low fixed fee for earlier-stage accounts, also means the practice isn’t paying anything upfront on a balance that may not be fully recoverable.


Need help with denied-claim dental balances? Contact us

Filed Under: Debt Recovery

College Station Collection Agency: Recovering What Aggieland Is Owed

Nearly 80,000 students move through Texas A&M each fall, and the businesses, clinics, and schools that keep Brazos Valley running don’t get the luxury of waiting for payment the way a university endowment can. Highway 6 carries the daily traffic between College Station and Bryan; the region’s hospitals, contractors, and CPA firms carry the receivables that don’t collect themselves. That’s where a properly handled account, not a shouting match, tends to win.

College Station Texas skyline near Texas A&M representing local business and medical debt recovery

Nexa provides reputation-safe, equipped with all 50-state collections license, offering free credit reporting, free litigation/bankruptcy scrubs, and zero onboarding fees. Secure – SOC 2 Type II & HIPAA compliant.

Need a Collection Agency? Contact us


What It Costs to Get Paid

Two ways to work an account, and you choose based on how fresh it is. Fixed-fee recovery runs $15 per account — ideal for early-stage balances, and you keep 100% of whatever comes in, no commission taken. Contingency service is 40%, performance-based: no recovery, no fee. Earlier assignment consistently produces better results than waiting, since a debtor’s willingness to pay tends to fade with distance from the original bill. Outreach can include email or text when appropriate and permitted, which often gets a faster response than a letter sitting in a mailbox. And your staff — hired to run a clinic, a jobsite, or a classroom, not to chase invoices — get that time back. Spanish-speaking collectors are available for households and businesses across the Brazos Valley where that’s the more effective way to communicate. One practical note worth passing to your CPA: many clients find the fixed-fee service qualifies as a deductible business expense, which can make the service effectively free after taxes — confirm the specifics with your accountant.

Nexa Collections fixed-fee and contingency pricing for College Station and Bryan business and medical debt collection

Why Cooperative Mediation Wins

In farm country, nobody waits until after the harvest to check on a crop, and receivables work the same way — the earlier the attention, the better the outcome. Our approach, which we call the velvet hammer, stays firm enough to secure payment while staying respectful enough to protect your five-star reputation online. Arguing with a debtor gives them a reason to dig in. Working with them — understanding what they can actually pay and when — gives them a reason to want to settle with you before anyone else on their list. Every account also goes through a litigious scrub before outreach begins, screening out the small share of debtors with a documented history of suing over collection contact, so you’re not exposed to that risk. Recovery rates under this approach consistently run above industry norms, without needing aggressive tactics to get there.

A note from the reconciliation team: we’ve found that a College Station debtor who feels heard settles faster than one who feels cornered — it’s not a slogan, it’s just what the data from this market keeps showing us.

Who We Work With Around Brazos Valley

Healthcare and medical practices, including specialty clinics near the Baylor Scott & White and CHI St. Joseph corridors, get fully HIPAA-aligned recovery built for patient balances. Texas A&M’s orbit means tuition, housing, and bursar accounts for colleges and universities are a natural fit, handled to preserve the student relationship, not just the balance. Dental and orthodontic practices, K-12 private and charter schools navigating a growing school-choice landscape, and accountants and CPA firms working net-30 cycles all get the same mediation-first approach. Banks and credit unions get experienced handling of delinquent consumer loans and deficiency balances. Construction, HVAC, and electrical trades, restoration and pool contractors, waste management, and broader B2B commercial accounts round out the portfolio — the common thread is protecting the relationship while still getting paid.

Recent Recovery Results

A College Station outpatient physical therapy clinic had a stack of small patient balances left over after a wave of deductible resets. A bilingual reminder sequence went out first, followed by a litigious scrub on the handful of non-responders before any next step. Most of the balance cleared within a few weeks, with no account needing to escalate further.

A mechanical contractor based in Bryan was owed a final payment on a multi-unit job near the Highway 6 corridor after the client withheld funds over a punch-list dispute. A documented demand laid out the completed scope, followed by a mediated conversation focused on what could be resolved immediately versus what needed more documentation. The balance was paid in full without litigation, and the contractor’s standing in a tight local trade network stayed intact.

What the Rules Actually Say

Texas gives most creditors four years to sue on a contract debt, regardless of whether it was written or oral. Wage garnishment for private debt is nearly impossible here — Texas is one of only four states with that protection — so a judgment against an individual doesn’t automatically translate into collectible income. The state’s homestead exemption also protects a primary residence’s full value, regardless of price. None of this is legal advice, just the practical landscape: before any account is worked, we run an address check through USPS, a skip trace if the debtor has moved, and a bankruptcy screen — and only pursue credit reporting where the account qualifies and it’s the right tool for that specific balance.

A Few Questions Worth Asking

Does a Texas A&M football weekend actually change how a College Station account should be handled?

Somewhat. Game weekends and semester billing cycles create predictable spikes in both spending and payment delays, and timing outreach around them tends to work better than ignoring the calendar entirely.

Does bilingual outreach really change outcomes in the Brazos Valley?

Yes, measurably. A debtor who receives a message in their preferred language responds faster and with less friction than one navigating a language barrier on top of a payment request.

What happens if a debtor has already filed for bankruptcy?

Collection activity stops. A bankruptcy screen runs before any account is worked specifically to catch this, since continuing to collect after a filing creates real legal exposure for everyone involved.

All calls are recorded and randomly reviewed — a safeguard against rogue collectors and the kind of review-bomb risk one bad call can create for a business’s reputation.

Trust, Security & Compliance

HIPAA & BAA Coverage for Medical and Dental Accounts

Patient billing records carry protected health information regardless of practice size. HIPAA-aligned handling procedures apply to every medical and dental account, with a Business Associate Agreement executed where the engagement requires one.

FDCPA Alignment

Every account is worked in alignment with the federal Fair Debt Collection Practices Act, layered with the practical Texas landscape described above rather than a generic national script.

Licensed Nationwide, Secure Data Handling

Collection activity is carried out under nationwide 50-state licensing, with SOC 2 Type II-certified data security and PCI-DSS Level 1 payment processing behind every account.

Secure Client Portal for Documentation & Account Tracking

Patient ledgers, invoices, and correspondence move through a secure portal rather than email, with account status visible without needing to call or email for an update.

Filed Under: Debt Recovery

Recovering Cash in Clovis Without Losing Your Community Respect

The balance of doing business in Clovis relies on trust. Whether you are operating near the bustling Herndon Avenue commercial corridor or managing a family-owned trade near Old Town, an unpaid invoice can disrupt your cash flow. You cannot afford to let hard-earned revenue slip away, but you also cannot risk aggressive, old-school collection tactics that trigger public backlash on digital review platforms.

Nexa provides a reputation-safe approach, equipped with all 50-state collections license, offering free credit reporting, free litigious debtor check, free bankruptcy scrub, and zero onboarding fees. Secure – SOC 2 Type II & HIPAA compliant. Over 2,000 online reviews rate us 4.85 out of 5. 

Need a Collection Agency? Contact us

Our Account Reconciliation Team steps in right here. We deliver firm, professional results while protecting your local brand. By deploying bilingual Spanish-speaking collectors, we ensure clear, respectful communication across our diverse Central Valley community. Assigning past-due accounts early dramatically elevates recovery rates before inflation eats into your margins. Let your team focus on core growth, rather than wasting hours on uncomfortable collection calls they dislike.

blank

Money-Saver Tip: Most local business owners effectively eliminate the cost of our fixed-fee service by claiming it as a legitimate Business Expense during tax season, after verifying with their CPA.

The Velvet Hammer: Why Cooperative Mediation Outperforms Conflict

Heavy-handed demands usually make people defensive, causing them to shut down communication entirely. Our approach uses a strategic “Velvet Hammer” methodology: we maintain unwavering firmness regarding the obligation to pay, combined with an empathetic, diplomatic tone that motivates people to resolve the matter. We position your past-due invoice as the priority bill to settle.

Before we make initial contact, your accounts undergo a comprehensive litigation scrub. This step identifies litigious individuals and protects your company from regulatory traps. Furthermore, we speed up resolutions by utilizing secure SMS and email channels when appropriate, accelerating turnaround times well beyond old-fashioned mailing methods.

Clovis Business Alert: Three Common Local Collection Pitfalls

  • Ignoring the Regional Commuter Dynamic: Assuming a debtor is ignoring you when they actually commute via Highway 168 or to Fresno daily, limiting their availability during standard banking hours.

  • Allowing Accounts to Age Past 90 Days: Waiting too long in a fast-moving Central Valley economy, where local operational costs can shift rapidly.

  • Drafting Aggressive Public Responses: Reacting emotionally to non-payment, which can cause local viral blowback and damage your reputation across the Fresno County market.

Recent Recovery Results

Enterprise Business Resolution

A regional commercial supply firm near the Clovis Industrial Park was owed a significant balance by a subcontracting partner. Our Account Reconciliation Team initiated a formal data verification process via USPS address checks, combined with deep skip tracing to locate the principal owners. Instead of threatening legal action, we presented an structured, objective payment schedule. The debtor agreed to an accelerated multi-week payout, recovering the full balance without fracturing a critical Central Valley B2B relationship.

Medical Specialty Settlement

A specialized healthcare clinic near the medical complexes off Herndon Avenue faced thousands in outstanding patient deductibles. We ran a bankruptcy scrub to confirm financial status and utilized our specialized bilingual team to reach out to the individuals. Through empathetic mediation, we set up manageable, automated settlement clearing options. The clinic recovered its vital operational revenue while maintaining absolute HIPAA compliance and protecting its local neighborhood reputation.

Dynamic Protection and Legal Safeguards

Every outbound and inbound call is recorded and systematically reviewed by management. This oversight ensures our staff never exposes your business to rogue collector behavior or retaliatory online review-bombing.

Our workflow integrates thorough identity verification, including USPS address validation, advanced skip tracing, and proactive bankruptcy database checks. If authorized and permitted by regional regulations, we can also initiate formal credit bureau reporting to provide additional motivation for resolution. Our processes comply strictly with the Fair Debt Collection Practices Act (FDCPA) and California’s Rosenthal Act, keeping your business fully insulated from compliance liabilities.

Tailored Solutions for Local Sectors

  • Healthcare & Medical: Compliant revenue recovery optimized for regional medical centers, physical therapy offices, and neighborhood specialty clinics.

  • Colleges & Universities: Resolving student accounts, campus housing balances, and bursar fees with a diplomatic touch that respects institutional prestige and student relations.

  • Dental: Specialized recovery for orthodontic practices and family dental clinics, ensuring gentle but effective past-due patient communication.

  • Construction & Trades: Professional collection solutions built for local HVAC, plumbing, electrical, and general contracting businesses navigating complex project billing cycles.

  • K-12 Private & Charter Schools: Managing tuition arrears and registration fees respectfully, keeping the local family dynamic in mind.

  • Accountants & CPA Firms: Direct mediation for outstanding professional service fees, protecting your professional rapport and net-30 billing integrity.

  • Banks & Credit Unions: Managing deficient consumer portfolios, overdrawn balances, and auto loans using compliant, structured recovery workflows.

  • B2B Commercial & Waste Management: High-impact business-to-business debt recovery tailored for industrial suppliers, transport operations, and regional waste management services.

Common Questions

How does cooperative mediation protect my business from negative web reviews?

By eliminating aggressive, confrontational language, we prevent the emotional escalation that drives individuals to leave angry public reviews. We treat people with professional dignity, turning a dispute into a structured financial resolution.

Are there extra charges for using your Spanish-speaking staff?

No. Our bilingual capabilities are completely integrated into both our $15 fixed-fee and 40% contingency service models at no additional cost to your business.

What happens if a debtor has moved away from the Fresno County area?

Our advanced skip tracing tools track address updates, workplace changes, and asset movements nationwide, allowing us to maintain contact even if they leave Clovis.

Filed Under: Debt Recovery

When Pearland Businesses Stop Getting Paid, the Clock Starts Ticking

Shadow Creek Ranch is booming. Lower Kirby is filling up with life sciences firms and engineering campuses. The SH 288 corridor keeps drawing new clinics, specialty practices, and professional offices. Pearland isn’t slowing down — and neither are the unpaid balances quietly piling up on the back end of all that growth.

If your business is sitting on receivables that calls, emails, and polite follow-ups haven’t moved — this was written for you.

Nexa provides reputation-safe, equipped with all 50-state collections license, offering free credit reporting, free litigious debtor check, free bankruptcy scrub, and zero onboarding fees. Secure – SOC 2 Type II & HIPAA compliant. Over 2,000 online reviews rate us 4.85 out of 5. 

Need a Collection Agency? Contact us


Straightforward Pricing. No Surprises.

Fixed-fee: $15 per account. You keep every dollar recovered.

Contingency: 40%. If we don’t collect, you owe nothing.

blank

Most of our clients recoup the fixed-fee cost entirely by writing it off as a business expense — ask your CPA how to apply it on your return.


What the Numbers Actually Show

Our Account Reconciliation Team’s recovery rates run well above industry averages. One reason: we don’t treat your debtor like an adversary. We treat them like someone who needs a reason to pay you before anyone else.

Most people juggling multiple debts aren’t choosing who to ignore — they’re choosing who to avoid. Aggressive collectors get avoided. Our approach — firm enough to produce results, respectful enough to protect your reputation — makes us the call they actually pick up.

We call this the Velvet Hammer. No threats. No pressure tactics that backfire. Just structured, professional mediation that gives debtors a clear path forward while keeping your five-star reputation exactly where it belongs.

Before contact, we run a litigation scrub — identifying accounts that carry elevated legal risk so we don’t expose you unnecessarily. We verify mailing addresses through the USPS, perform skip tracing on moved accounts, and conduct bankruptcy checks so your team isn’t chasing accounts that are legally off-limits. Credit bureau reporting is available where permitted and appropriate.

Calls are recorded and randomly reviewed internally — which is how we prevent rogue behavior and protect you from the review-bomb risk that aggressive collectors bring.

We also reach debtors via email and text where appropriate, which meaningfully speeds up response times. And yes — our team includes Spanish-speaking collectors, which matters in Brazoria County’s increasingly diverse business landscape.

The earlier you assign an account, the better the result. That’s not a sales line — it’s what the data consistently shows.


Recent Recovery Results

Specialty clinic, Pearland (SH 288 corridor): A multi-physician practice near Shadow Creek Parkway had accumulated $38,400 in unpaid patient balances across 61 accounts — mostly older bills that the front-desk team had already followed up on without results. Our Account Reconciliation Team verified current addresses through USPS, confirmed no active bankruptcies, and initiated outreach using a HIPAA-compliant, non-threatening protocol. Spanish-language outreach was used on approximately a third of the accounts. Within 47 days, $26,900 had been recovered. The practice received zero complaints and zero negative online mentions.

Commercial contractor, Manvel (Brazoria County): A restoration and general contracting firm south of Pearland held $19,200 in unpaid invoices from three separate commercial clients — all relationships they wanted to preserve. We assigned a dedicated mediator, reached decision-makers directly at each company, and structured payment arrangements that fit each client’s cash flow situation. Two accounts settled in full; one was resolved through a negotiated partial payment. Total recovery: $15,750. The contractor kept all three clients.


Pearland’s Business Reality — and What It Means for Collections

Pearland isn’t a suburb anymore. It’s an economic engine in its own right. The Lower Kirby District hosts global firms like Endress+Hauser and Lonza alongside biotech startups. The University of Houston – Clear Lake Pearland campus feeds a growing professional workforce. Memorial Hermann and HCA Houston Healthcare anchor a healthcare corridor along SH 288 that’s expanding every year. The Port of Houston is a short drive north; Bush Intercontinental and Hobby are accessible without a second thought.

All of that growth brings opportunity — and it brings receivables complexity. B2B transactions in construction and manufacturing. Patient balances across specialty medicine. Tuition and fee disputes. Professional service invoices caught in net-30 limbo. Our team understands the texture of Brazoria County business relationships, and we collect accordingly.


Red Flag Box: 3 Collection Mistakes Pearland Businesses Make

— Waiting 90+ days to assign. By that point, debtors have reorganized their financial priorities and you’re at the back of the line.

— Using the same employee who manages the relationship to make collection calls. It creates awkward leverage and rarely works along the SH 288 professional corridor where word travels fast.

— Assuming the debtor simply won’t pay. In most cases, there’s a reason — financial hardship, a dispute, an overlooked invoice. Our mediators uncover it. That’s how accounts get resolved.


The Rules That Govern This Space

Texas collections operate under a dual framework. Federally, the Fair Debt Collection Practices Act (FDCPA) sets baseline rules: no contact before 8 a.m. or after 9 p.m., no harassment, no misrepresentation. Texas Finance Code Chapter 392 applies those same standards to original creditors — not just third-party collectors — which makes Texas one of the more debtor-protective states in the country.

Texas also enforces a four-year statute of limitations on most debts. There is no wage garnishment available for consumer debt in Texas. For B2B commercial debt, FDCPA protections don’t apply, but ethical collection standards still govern how our team operates.

None of this is legal advice — consult an attorney for your specific situation. What matters practically: we know the lines, and we don’t cross them.


FAQs

We already sent invoices twice. Why would a third-party contact work when we didn’t? Familiarity breeds avoidance. A message from an Account Reconciliation Team signals consequence in a way that a reminder from someone they’ve worked with does not. It reframes the situation — and that shift in framing is often all it takes.

We serve a lot of Spanish-speaking clients in Brazoria County. Can your team communicate with them directly? Yes. We have Spanish-speaking collectors on staff specifically because the demographics along the 288 corridor demand it. Comfortable communication shortens collection timelines considerably.

What if the debtor claims they never received the invoice? We address that directly. USPS address verification, documented digital outreach, and skip tracing confirm current contact information before any engagement. Disputes about receipt are handled professionally, not escalated into conflict.


Who We Serve

Healthcare & Medical — HIPAA-compliant recovery for the specialty clinics, urgent care centers, and physician groups expanding throughout Pearland’s SH 288 healthcare zone.

Dental & Orthodontics — Patient balance recovery handled with the sensitivity that protects referral-dependent practices.

Restoration & Contractors — Payment recovery for the HVAC, electrical, general contracting, and restoration firms doing significant work across Brazoria County’s fast-growing residential and commercial markets.

Pool & Home Services — End-of-season and project-balance recovery for service businesses where customer relationships matter beyond the single job.

K-12 Private & Charter Schools — Enrollment fee and tuition balance recovery managed with the diplomacy that Pearland’s growing school-choice community expects from institutions it trusts.

Banks & Credit Unions — Delinquent loan recovery, overdrawn account balances, and deficiency collections handled with an understanding of regulatory sensitivity.

Accountants & CPA Firms — Professional fee recovery calibrated for the net-30 billing world, where preserving the client relationship has real dollar value.

Construction & Trades — Revenue recovery for subcontractors and general contractors operating across the Lower Kirby and SH 35 development corridors.

B2B Commercial — Accounts receivable mediation for manufacturers, distributors, and professional service firms operating in the Houston metro supply chain.

Waste Management — Recurring service balance recovery for providers serving Pearland’s residential and commercial growth zones.

Colleges & Universities — Bursar balance, housing fee, and enrollment debt recovery that respects institutional reputation — relevant for the UH Clear Lake Pearland campus community and beyond.

Contact Nexa Today

Filed Under: Debt Recovery

In Columbia, Unpaid Invoices Don’t Age Gracefully – Neither Should Your Recovery Strategy

Columbia moves at a different pace than most mid-sized Missouri cities. The research activity on Mizzou’s campus, the foot traffic through The District, the steady rhythm of Boone Health and MU Health Care — this is a city built on relationships and credibility. Which is exactly why how you collect matters just as much as whether you collect.

Nexa provides a reputation-safe approach, equipped with all 50-state collections license, offering free credit reporting, free litigious debtor check, free bankruptcy scrub, and zero onboarding fees. Secure – SOC 2 Type II & HIPAA compliant. Over 2,000 online reviews rate us 4.85 out of 5. 

Need a Collection Agency? Contact us


Two Ways to Work With Us — You Choose

  • Fixed Fee: $15 per account — you keep every dollar recovered. Most clients expense this as a business deduction — check with your CPA, and many walk away paying nothing net.
  • Contingency: 40% — no collection, no charge. Zero risk, zero upfront.

Both options come backed by the same bilingual team, the same standards, and an approach designed to protect your reputation in a city where reputation travels fast. Spanish-speaking collectors are on staff — Columbia’s growing Hispanic community means that’s not optional, it’s essential.

blank


A Note From Our Account Reconciliation Team

We’ve worked enough B2B and patient-facing accounts to know that the fastest way to lose a Columbia client is to embarrass them. So we don’t. We open a conversation the debtor actually wants to finish — one where paying you first feels like the obvious move. That’s the Velvet Hammer in practice: structured enough to create urgency, measured enough that your Google rating stays intact. When a debtor feels treated with dignity, they prioritize your invoice over everyone else’s stack.

Before the first call goes out, we run a bankruptcy check, verify addresses through USPS, and conduct a litigation scrub to protect you from accounts that carry more legal risk than dollar value. Skip tracing handles the ones that have quietly moved on. And when appropriate, we use email and text — because that’s where people actually respond.

All calls are recorded and randomly reviewed internally. That’s not fine print — it’s our quality control. It’s also what keeps rogue behavior and review-bomb risk off your radar.


Three Collection Pitfalls Columbia Businesses Hit Regularly

  • Assigning accounts only after internal staff has tried and failed for 90+ days — every week past day 60 meaningfully lowers recovery odds
  • Assuming a long-term client relationship makes the conversation less awkward — it usually makes it harder, not easier, which is exactly why a neutral third party works
  • Treating student-adjacent debt (renters, service clients near campus) the same as commercial accounts — different tone, different timing, different outcome

Recent Recovery Results

Columbia Specialty Clinic — Behavioral Health Practice, Near Stadium Boulevard Corridor

A behavioral health provider carried 31 accounts past 90 days, mostly patients who had self-pay balances after insurance adjudication. Internal staff had attempted calls with limited success. Our team verified active addresses through USPS, reached out via multiple channels including text, and structured flexible arrangements that fit each patient’s situation. The practice recovered 68% of total outstanding — without a single complaint, review flag, or HIPAA issue.

Jefferson City Commercial Contractor — B2B Flooring & Interior Finish

A commercial flooring company servicing properties throughout mid-Missouri had a disputed $19,400 invoice from a commercial property developer who had gone quiet after project completion. We made direct contact with the decision-maker, referenced the signed scope of work, and framed resolution as the cleaner path versus an escalating dispute. Settled in full within 23 days. No attorney. No court.


What Missouri Law Actually Means for You as a Creditor

Missouri doesn’t have a standalone state debt collection act — the federal FDCPA is the primary framework, with two state layers worth knowing:

  • Statute of limitations: 10 years for written contracts (signed agreements, medical billing, personal loans). 5 years for open accounts and oral agreements. 4 years for sale-of-goods debt. Missouri’s windows are longer than most states — but accounts still weaken with age. Assign earlier.
  • Missouri Merchandising Practices Act (MMPA): Adds state-level protection against deceptive collection practices — relevant for any debt connected to the sale of goods or services.
  • FDCPA contact rules: No contact before 8 a.m. or after 9 p.m. Calls capped at 7 within any 7-day period per account. Texts and email are permitted channels.
  • Wage garnishment: Missouri allows garnishment of up to 25% of disposable wages — reduced to 10% for heads of household. A judgment is required first.
  • Credit reporting: Available as a recovery tool where permitted — discussed with each client by account type.
  • Missouri requires debt collection agencies to be licensed with the state — a baseline protection you should confirm with any agency you engage.

We address all accounts with USPS verification, bankruptcy screening, and skip tracing. Educational context only — not legal advice.


FAQs

Columbia has a lot of transient residents — students, residents, staff who leave town. Can you find people after they’ve moved? Yes. Skip tracing is a standard part of our process, not an add-on. Between USPS address verification and investigative data sources, most accounts that appear unreachable are reachable — they’ve just moved without updating you.

We serve patients at MU Health Care-affiliated clinics. Is this process HIPAA-compliant? Fully. Patient accounts are handled under strict HIPAA-compliant protocols. No protected health information is used or shared outside of what’s legally permitted in the collection process.

What happens if my debtor disputes the debt? We pause outreach and follow the FDCPA verification process — providing written validation before resuming. This protects you legally and keeps the process clean.


Who We Serve in Columbia

Healthcare & Medical — HIPAA-compliant recovery for clinics, specialty practices, and providers across the MU Health Care and Boone Health ecosystems serving Boone County.

Dental & Orthodontics — Patient balance recovery handled with the discretion a care-based practice depends on.

Colleges & Universities — Tuition balances, housing fees, bursar accounts, and lab-fee recovery for institutions in and around Columbia’s three-campus corridor — Mizzou, Columbia College, and Stephens College.

K-12 Private & Charter Schools — Unpaid enrollment and materials fees managed with the diplomatic sensitivity Columbia’s school-choice families expect.

Accountants & CPA Firms — Professional fee recovery that respects your billing cycle and preserves the long-term client relationships you’ve built.

Banks & Credit Unions — Delinquent consumer loans, overdrawn accounts, and deficiency balances, with full knowledge of Missouri’s garnishment framework.

Construction & Trades — Revenue recovery for HVAC, electrical, roofing, and general contractors active in Columbia’s ongoing commercial and residential growth along US-63 and I-70 corridors.

Restoration & Waste Management — B2B commercial accounts where documentation and chain-of-custody matter as much as the balance itself.

Pool & Exterior Contractors — Seasonal businesses that often face end-of-project disputes — we know how to close those without burning the relationship.

B2B Commercial — Any business-to-business receivable where a professional intermediary creates faster resolution than internal follow-up.


Your team was hired to move Columbia’s economy forward — not to chase invoices. Let the Account Reconciliation Team handle what we do best, so your people can focus on what they do best.

Contact Nexa Today

Filed Under: Debt Recovery

  • « Go to Previous Page
  • Page 1
  • Page 2
  • Page 3
  • Page 4
  • Page 5
  • Interim pages omitted …
  • Page 55
  • Go to Next Page »

Primary Sidebar


accounts receivable

Need a Collection Agency?
Kindly fill this form.
We’ll get in touch with you

    Please prove you are human by selecting the star.

    Compliance & Security

    • SOC 2 Type II Certified: Third-party audited data security and strict privacy controls.

    • HIPAA Compliant: Secure, legal processing of medical and municipal EMS accounts.

    • PCI-DSS Level 1: Highest tier of data encryption for secure payment processing.

    • FDCPA & FCRA Aligned: Full legal adherence to federal consumer protection laws.

    Recent Posts

    • Why Dental Patients Dispute Bills: The Nexa Collections Dental Account Dispute Index
    • 2027 Commercial Collections Benchmark: U.S. Late Payments, AR Risk and B2B Collection Trends
    • Bulk Account Placement: What a Collection Agency Actually Needs From You
    • Nationwide Debt Collection Agency Serving U.S. Cities
    • Chula Vista Collection Agency for Medical, B2B, Schools & Business Debt
    • Corpus Christi Collection Agency: Itemized Bill Rules for Practices
    • Riverside Collection Agency | For Logistics, Medical, Schools & Business Recovery
    • Collection Agency for Large Balances: High-Value B2B Debt Recovery

    Featured Posts

    • Process to Send Someone to Collections
    • Speed Up Medical Insurance Claims with a Collection Agency
    • Early Commercial Debt Collection: Why Waiting 90 Days Costs You 20% of Your Revenue

    Copyright © 2026 NEXACOLLECT.COM | This content is provided for general informational purposes only and should not be considered legal advice. Collection laws and requirements may vary by state, account type, documentation, debtor status, and specific facts. Please consult qualified legal counsel for guidance regarding your particular situation. Nexa and its authorized collection partners service accounts in accordance with applicable federal and state collection requirements. Visit our home page to know more about us.

    X
    Need a Collection Agency?
    Contact Us