• Skip to main content
  • Skip to primary sidebar

Nexa Collections

  • Home
  • Serving
    • Medical
    • Dental
    • Small Business
    • Large Business
    • Commercial Collections
    • Government
    • Utilities
    • Fitness Clubs
    • Schools
    • Senior Care Facility
  • Contact Us
    • About us
    • Cost

Debt Recovery

Collection Agency for Large Balances: High-Value B2B Debt Recovery

Contract-aware. UCC-aware. Relationship-conscious. Litigation Ready, but as the Last Resort.

A $100,000 unpaid invoice should not cost you 40% to collect. Large commercial debts require experienced negotiation and stronger account review, but their size can also justify substantially lower contingency rates. Nexa uses tiered commercial pricing based on both the amount owed and the age of the debt, with qualifying fresh balances of $100,000+ carrying contingency rates as low as 10%. That means B2B negotiation, documentation review, debtor research, structured payment arrangements, dispute resolution, and legal escalation when financially justified, without a flat rate that eats disproportionately into a large recovery.

No Recovery-No Fee.
NexaCollect large balance B2B debt recovery for commercial accounts over $10,000, with lower contingency rates, professional negotiation, and relationship-focused collections.

Nexa provides a reputation-safe approach to commercial debt recovery, with nationwide collection capabilities and specialized experience in B2B accounts. Our team handles disputed invoices, contracts, purchase orders, personal guarantees, and UCC-related commercial accounts where applicable. 15+ years experience. Clients receive free bankruptcy screening, litigation checks, business-location research, and appropriate credit reporting, with zero onboarding fees. 

Our SOC 2 Type II environment helps protect sensitive business data, while experienced negotiators work to recover payment without unnecessarily damaging valuable commercial relationships. With more than 2,000 online reviews and a 4.85/5 rating, Nexa combines strong recovery capabilities with responsive client support.

Need a Collection Agency for Large Balance Recovery? Contact us

Collection → Negotiation → Payment Plan/Settlement → Attorney Review → Litigation When Justified


Large Debts Need a Different Collection Strategy

A $100,000 unpaid invoice is rarely solved by simply making more calls. Large commercial accounts commonly involve disputed invoices, contract disagreements, purchase-order issues, delayed internal approvals, cash-flow problems on the debtor’s side, partial payments, personal guarantees, and multiple decision-makers who all need to sign off before money actually moves.

High-value commercial collections are often negotiations, not just collection calls. Getting a large balance resolved usually means understanding exactly why payment stopped, not just repeating the amount owed.


Bigger Balance, Lower Contingency Percentage

Nexa can charge lower percentages on larger accounts because the work of collecting a big invoice doesn’t scale one-to-one with its size, and a lower rate on a large recovery still returns more absolute value to both sides than a high rate on a small one.

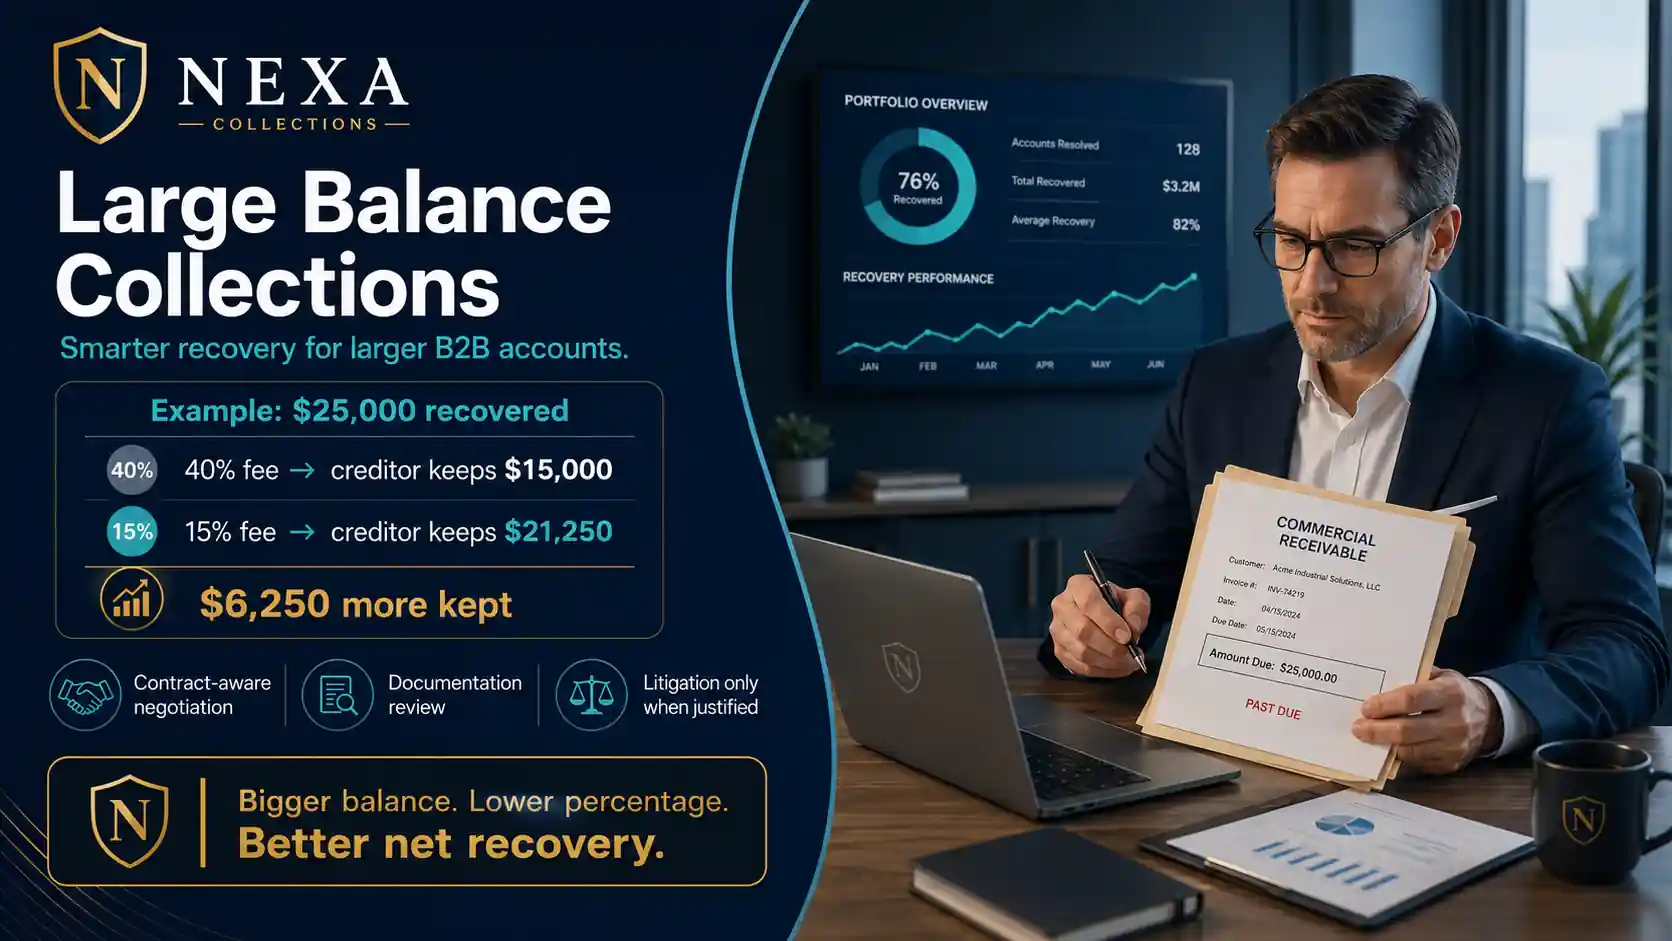
Here’s what that actually looks like: if $100,000 is recovered at a 10% contingency rate, the creditor keeps $90,000. Compare that to a flat 40% rate on the same recovery:

  • $100,000 recovered
  • 40% fee = creditor keeps $60,000
  • 10% fee = creditor keeps $90,000
  • Difference = $30,000

That 10% rate applies specifically to qualifying $100,000+ accounts under 90 days old, not to every large balance regardless of age. The amount recovered matters. The amount you keep matters too.

Nexa’s Commercial Contingency Rates

Age of Account $5,000–$19,999.99 $20,000–$99,999.99 $100,000+
Under 90 days 20% 15% 10%
90–180 days 25% 20% 15%
180 days–1 year 30% 25% 20%
Over 1 year 35% 30% 25%

The rate always depends on both the balance and how long it’s been outstanding, not on size alone.


Age of Debt Matters Almost as Much as the Balance

A fresh account generally means better contact information, easier access to supporting documentation, current employees who were actually involved in the transaction still being reachable, fewer ownership or business-status changes, and simply more negotiating leverage while the relationship is still recent.

A $100,000 debt placed at 60 days is not the same collection problem as a $100,000 debt placed after two years. The table above reflects that directly, the same balance can carry a 10% rate or a 25% rate depending entirely on how long it’s been sitting.


Why Large B2B Accounts Need Experienced Negotiation

Large commercial balances often require finding out why payment actually stopped before anything else can happen. That can mean identifying the true underlying dispute, reaching the right controller, CFO, owner, or accounts-payable decision-maker (not just whoever answers the phone), reconciling invoices against purchase orders and delivery records, reviewing the supporting documentation in detail, negotiating realistic payment terms, arranging structured payments, or negotiating an appropriate settlement when the creditor has authorized one.

Professionalism matters here specifically because large B2B relationships are often ongoing ones. Preserving the business relationship, where that’s still valuable to the creditor, is part of doing this well, not a separate consideration from collecting the money.
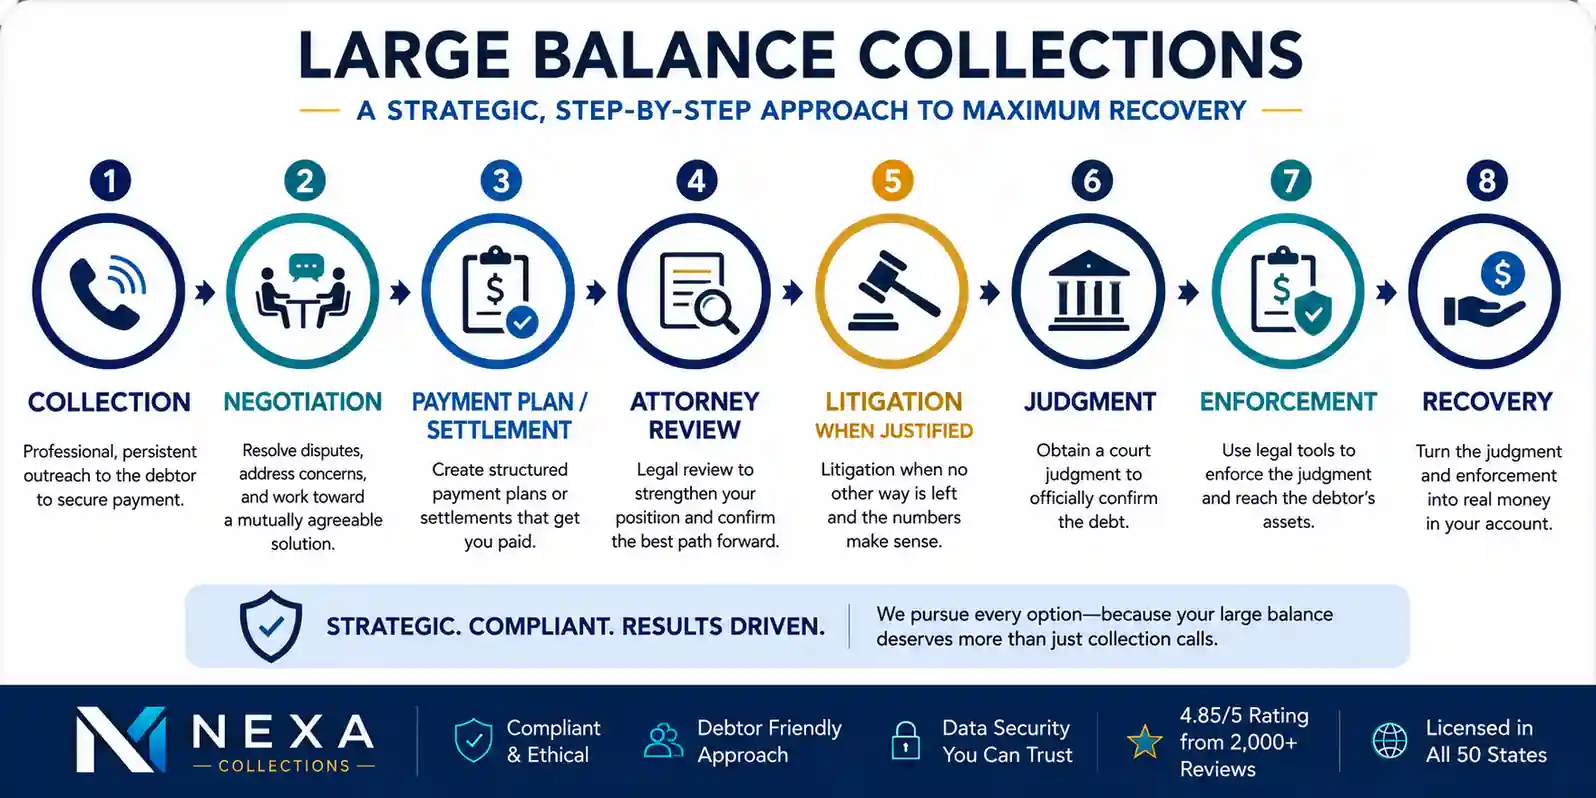
Large balance collection process showing collection, negotiation, payment plan or settlement, attorney review, litigation when justified, judgment, enforcement, and recovery.


If Your Transaction Included a Security Interest, You May Have More Options

Large equipment, inventory, or accounts-receivable-financed transactions are more likely than smaller ones to include a properly documented security interest, formalized through a security agreement and typically perfected with a UCC-1 financing statement. If that documentation exists, the creditor generally has real advantages an unsecured creditor doesn’t: the right to repossess collateral without going to court first (provided it can be done without breaching the peace), and, where the collateral is accounts receivable, the right to notify the debtor’s own customers to pay the creditor directly. This can be significantly faster than litigation, and it generally holds a stronger position even if the debtor later files for bankruptcy. Not every large balance has this in place, but for the ones that do, it’s worth confirming before assuming a standard collection or litigation path is the only option.


When Legal Escalation Makes Sense

Large balances can make litigation more economically practical than it would be for a small account, but that doesn’t mean litigation should be treated as automatic. The goal is not to sue because the balance is large. The goal is to escalate when the documentation, collectability, and economics genuinely support it, factoring in bankruptcy screening, the debtor’s current business status, documentation quality, likely collectability of any resulting judgment, expected legal costs, and expected net recovery after those costs.

Collection → Negotiation → Payment Plan/Settlement → Attorney Review → Litigation When Justified

For more on how that legal review process actually works, see our full guide to how debt collection lawyers work.


Types of Large Commercial Debts Nexa Handles

Manufacturing: Large unpaid supply, equipment, component, and purchase-order invoices.

Construction & Trades: Contractor, subcontractor, materials, and project balances.

Staffing Companies: Unpaid invoices where payroll has already been funded.

Transportation & Logistics: Freight, warehousing, shipping, and transportation receivables.

Wholesale & Distribution: Inventory, trade-credit, and distributor balances.

Professional Services: Consulting, engineering, IT, accounting, and other high-value service invoices.

Commercial Property: Commercial lease, vendor, and contractual balances.

See our full commercial collections overview for the broader B2B recovery process this large-balance pricing sits within.


Why Pay 40% on a Fresh $100,000 Account?

A flat contingency percentage may make sense for smaller or genuinely difficult accounts, but applying that same high rate to every balance can dramatically reduce what the creditor actually keeps. Nexa’s tiered pricing recognizes that a $2,000 account and a $200,000 account should not necessarily carry the same collection percentage. See the full fee structure for how this fits alongside standard and legal-referral pricing.

Need a Collection Agency? Contact us


Frequently Asked Questions

Do collection agencies charge lower rates for large debts?

Often, yes, when the agency’s pricing is genuinely tiered rather than flat. Nexa’s contingency rate depends on both the size of the balance and how long it’s been outstanding, with larger, fresher accounts qualifying for meaningfully lower rates than smaller or older ones carry.

What percentage does a collection agency charge on a $100,000 debt?

With Nexa, a qualifying $100,000+ account under 90 days old can carry a contingency rate as low as 10%. That rate rises with age, 15% at 90-180 days, 20% at 180 days to a year, and 25% beyond a year, so the exact rate depends on both size and how long the account has been outstanding.

Can a collection agency recover a $50,000 or $100,000 B2B invoice?

Yes, this is squarely the kind of account experienced commercial collection handles well, provided the underlying debt is documented and the debtor is genuinely collectible. Large B2B balances often benefit from negotiation and documentation review more than repeated calls alone.

Should I use a collection agency or a lawyer for a large commercial debt?

Generally, agency-first, with attorney escalation reserved for accounts where litigation is financially justified. A large balance can make legal costs easier to absorb, but escalation should still depend on documentation strength, debtor collectability, and expected net recovery, not size alone.

When should a large unpaid B2B invoice be sent to collections?

Earlier than most businesses assume. Waiting generally makes recovery harder, contact information ages, documentation gets harder to assemble, and the pricing table above reflects this directly: the same balance carries a meaningfully lower rate when it’s fresh than when it’s aged past a year.

What documents help collect a large disputed commercial debt?

The signed contract or purchase order, invoices, delivery or acceptance records, account statements, relevant email correspondence, any personal guarantee, and the full payment history. A well-documented large account is significantly easier to resolve through negotiation than one relying on the invoice alone.

How does a personal guarantee protect my business if a corporate debtor shuts down?

When an insolvent LLC or corporation closes its doors, standard commercial claims against the company often become uncollectible “paper debts” against an empty shell entity. A signed, enforceable personal guarantee changes the legal landscape. It waives the business principal’s corporate limited-liability shield, creating joint and several liability. This allows you to bypass the lengthy, expensive legal battle of “piercing the corporate veil” and pursue recovery directly against the owner’s personal bank accounts, real estate, and private assets.

How should large debt settlement plans be structured to prevent future defaults?

Large-balance payment plans should never rely on verbal promises or basic promissory notes. If a debtor defaults midway through a plan, an informal agreement forces you to file a lawsuit and spend months proving the original underlying claim. Instead, anchor substantial settlements with an Agreed Judgment, Consent Order, or Confession of Judgment Note (where permitted by state law). Under this structure, the judgment is held in escrow while payments remain current; if the debtor misses a payment, the creditor can immediately enter judgment with the court and proceed directly to post-judgment enforcement—such as bank levies and property liens—without relitigating the case.


Nexa understands that high-value commercial accounts require a different approach than a routine consumer balance. Larger balances may qualify for significantly lower contingency rates, while professional negotiation, documentation review, debtor research, and selective legal escalation help maximize what actually comes back to the creditor. If your business is carrying a large commercial balance, especially $10,000 or above, talk to Nexa about the right recovery strategy and which contingency tier your account qualifies for.
 

Filed Under: Debt Recovery

Baltimore Collection Agency | Medical, Commercial, Schools & More

One Baltimore name sits at the center of two completely different revenue cycles: Johns Hopkins. On one side are hospital and medical patient balances; on the other are university tuition, research, and education-related receivables. They may share the Hopkins name, but they do not share the same collection playbook. That is Baltimore in a nutshell—a city where healthcare, higher education, logistics, government, contractors, and small businesses all create very different kinds of overdue accounts. Johns Hopkins Hospital remains one of the nation’s top-ranked hospitals, while Johns Hopkins University is America’s first research university.

Quick answer: Baltimore creditors generally have a three-year window for many civil claims, and for consumer debt, once the applicable limitation period expires, a later payment does not restart it. Meanwhile, the Port of Baltimore remains a national leader in roll-on/roll-off cargo, reinforcing the city’s major logistics and commercial base. Nexa helps Baltimore healthcare providers, schools, universities, contractors, logistics companies, and businesses recover overdue accounts starting at $15 per account, with contingency options for tougher balances.

Baltimore collection agency

Nexa provides a reputation-safe approach, equipped with all 50-state collections license, offering free credit reporting, free litigious debtor check, free bankruptcy scrub, and zero onboarding fees. Secure – SOC 2 Type II & HIPAA compliant. Over 2,000 online reviews rate us 4.85 out of 5. 

Need a Collection Agency? Contact us


Why Baltimore’s Economy Doesn’t Fit One Category

Johns Hopkins is genuinely two account types in one institution. 
Johns Hopkins Hospital consistently ranks among the top hospitals nationally, generating patient medical balances requiring HIPAA-compliant, sensitivity-aware handling. Johns Hopkins University, the same name, a distinct institution, generates tuition, program fee, and housing balances that follow an entirely different pattern, more like a standard educational receivable than a medical one. Treating every Hopkins-adjacent account the same way misses which set of rules and sensitivities actually applies.

The Port of Baltimore has recovered and is genuinely strong, distinct from the ongoing bridge rebuild. 
The Port of Baltimore is the country’s leading port for automobile and farm equipment imports, and its shipping channel fully reopened within months of the 2024 Francis Scott Key Bridge collapse. The bridge itself is a separate, longer story: Maryland changed contractors in 2026 and is still procuring construction for a project now estimated at over $4 billion, with completion not expected until 2030. For a commercial creditor, this distinction matters, port-dependent businesses have been operating normally for some time, while construction, engineering, and supply firms tied to the bridge rebuild itself are engaging with a large, active, multi-year project.

Maryland’s non-revival rule is worth knowing precisely. 
Under CJP § 5-101, once a consumer debt’s statute of limitations expires, a later payment or written acknowledgment does not restart the clock, the same non-revival pattern already confirmed for Maine, Minnesota, and D.C. This makes early placement more valuable in Maryland than in states where a partial payment can buy back time.


The Maryland Legal Landscape

Statute of Limitations (general contracts) 4 years (12 years for sealed instruments)
SOL Revival (consumer debt) Non-revivable once expired — CJP § 5-101
Medical Debt Credit Reporting Generally barred (HB 1020), subject to an unresolved federal FCRA preemption question

What This Costs

Step 1 & 2: Fixed-Fee Recovery (~$15/account). Professional demand sequences for accounts under roughly 60-90 days. Payments go directly to you. See the full pricing breakdown.

Step 3: Contingency Collection (20%~40%). For older or unresponsive accounts, no recovery, no fee.

Step 4: Legal Referral (client-approved, ~50%). Filing fees reimbursed from the first recovery.

Nexa Collections fixed-fee and contingency pricing structure


Who We Collect For Across Baltimore

  • Medical & Hospital Systems: HIPAA-compliant patient balance recovery for practices and hospital systems across the metro, including the Johns Hopkins Hospital network and independent providers.
  • Universities & Higher Education: Tuition and program fee recovery for the metro’s universities, including Johns Hopkins’ academic side specifically, a genuinely distinct account type from its hospital’s patient balances.
  • Commercial & Port-Adjacent Logistics: B2B and commercial receivables for the freight, warehousing, and auto-import logistics companies supporting the Port of Baltimore.
  • Construction & Infrastructure: Commercial recovery for the contractors, engineering firms, and suppliers engaging with the region’s large-scale infrastructure projects, including the ongoing Key Bridge rebuild.
  • Dental: Patient-first dental debt recovery for practices across the metro.
  • Schools & Districts: Meal and activity fee recovery for Baltimore-area public school districts.

Recent Recovery Results

1. Port & Intermodal Logistics Supplier (Port of Baltimore Corridor)

  • Balance: $12,600 (Overdue 90-Day Freight, Drayage & Storage Invoices)

  • Outcome: Commercial B2B mediation resolved an accessorial billing dispute with corporate accounts payable, securing full wire payment in two scheduled installments.

2. Outpatient Surgical & Physical Therapy Clinic (Downtown / Mid-Town Baltimore)

  • Balance: $4,150 (Past-Due Patient Co-pays & High Deductibles)

  • Outcome: HIPAA-compliant digital reminders and a simplified payment portal recovered 78% of outstanding balances within 40 days without negative patient feedback.

3. Commercial HVAC & Mechanical Contractor (Baltimore County / Towson)

  • Balance: $9,800 (Delinquent Progress Billing & Equipment Service Charges)

  • Outcome: Direct pre-litigation outreach to the property management group verified completed work orders and secured full settlement before mechanics lien deadlines expired.


Frequently Asked Questions

Does Johns Hopkins generate one type of account, or two genuinely different ones?

Two. Johns Hopkins Hospital generates patient medical balances requiring HIPAA-compliant, sensitivity-aware collection, while Johns Hopkins University, a distinct institution under the same name, generates tuition, program fee, and housing balances that follow standard educational receivable handling instead. Confirming which side of Hopkins an account actually comes from changes which compliance framework and tone applies.

Is the Port of Baltimore still disrupted from the 2024 bridge collapse?

No, the port itself recovered relatively quickly, the shipping channel fully reopened within months, and the port has continued operating as the country’s leading destination for automobile and farm equipment imports, with new business commitments announced as recently as 2026. The Key Bridge rebuild is a separate, ongoing, multi-year infrastructure project, distinct from day-to-day port operations, which have not been disrupted for some time now.

Does the ongoing Key Bridge rebuild create commercial collections opportunities specific to Baltimore right now?

Potentially, yes. As of 2026, Maryland is actively procuring a new construction contractor for a project now estimated at over $4 billion, with completion not expected until 2030. This means engineering, construction, and supply firms are actively engaging with a large, multi-year regional project, a genuine, current source of commercial account activity distinct from the port’s own, already-recovered operations.

Does a partial payment restart Maryland’s statute of limitations on an old debt?

No. Under CJP § 5-101, once the limitations period on a consumer debt expires, a later payment or written acknowledgment does not revive it, the same non-revival rule already confirmed for Maine, Minnesota, and D.C. This makes early placement more valuable in Maryland than in states that do allow revival.

Can medical debt still appear on a Maryland resident’s credit report?

Generally no under Maryland’s HB 1020, though this is worth stating with appropriate precision: the CFPB raised a federal preemption question in October 2025 about whether federal law allows states to ban medical debt reporting at all, an unresolved question affecting Maryland’s law along with similar bans in roughly a dozen other states.

How long does a Baltimore business have to collect on a written contract?

Generally four years for most contracts, extending to 12 years for contracts executed as sealed instruments, a distinction worth confirming on higher-value or older agreements before assuming the shorter period applies.


Talk to Us About Your Baltimore Receivables

Filed Under: Debt Recovery

Commercial and B2B Collection Agency in Detroit

A Detroit supplier ships an order on net-60 terms. Three weeks later, it learns the customer filed bankruptcy the same week the goods were delivered. Most businesses assume the unpaid invoice is now just another bankruptcy claim. Not necessarily. A seller may have a narrow legal window to demand the goods back — but timing matters.

In short: Michigan gives qualifying sellers powerful tools that ordinary collections advice often overlooks. Under Fisher v. Sweebe, qualifying open-account and account-stated claims can carry a six-year limitations period rather than the UCC’s four-year sales-contract period. And when goods were delivered to an insolvent buyer, Michigan UCC § 2-702 and federal bankruptcy law may provide reclamation rights with very short notice deadlines.

For Detroit manufacturers, distributors, suppliers, commercial service providers — and even healthcare businesses dealing with business accounts — the takeaway is simple: the age of the invoice and what happened immediately before a bankruptcy can materially change the recovery strategy.

blank

Nexa provides 100% reputation-safe, equipped with all 50-state collections license, offering free credit reporting, free litigation/bankruptcy scrubs, and zero onboarding fees. Secure – SOC 2 Type II, FDCPA, UCC & HIPAA compliant.

Need a Collection Agency in Detroit? Contact us


Two Tools Most Detroit Suppliers Don’t Know They Have

Aged trade accounts may not be as time-barred as they look.
Michigan’s Supreme Court held in Fisher Sand & Gravel Co. v. Neal A Sweebe, Inc. that open-account and account-stated claims fall under the state’s 6-year contract limitations period under MCL § 600.5807, not the UCC’s 4-year window, even when the underlying transaction was a sale of goods. A distributor or supplier that’s been writing off 4-to-6-year-old Michigan trade accounts under a generic UCC assumption may be leaving genuinely collectable receivables on the table.

A 10-day clock most businesses never learn about until it’s already run. 
If a buyer turns out to have been insolvent when it received goods on credit, UCC § 2-702 gives the seller the right to demand those goods back, but the demand generally has to be made within 10 days of the buyer’s receipt. Standard purchase terms that treat acceptance of goods as an implicit representation of solvency can help preserve this right if that 10-day window is missed for a reason tied to misrepresentation, but absent that, the clock is simply the clock. If the buyer has already filed bankruptcy by the time the seller finds out, Bankruptcy Code § 546(c) provides a parallel right, goods received within 45 days before the filing, with a written demand made within that same 45-day period. Even when reclamation itself doesn’t succeed, § 503(b)(9) can still elevate a seller’s claim to administrative priority status for goods delivered in the 20 days before filing.

Why this matters more here than almost anywhere else. 
Detroit’s economy runs on a deep, multi-tier automotive supply chain, Tier 1, 2, and 3 suppliers feeding the Big Three and their broader ecosystem, an industry with a well-documented history of supplier restructurings and OEM-adjacent bankruptcies. A parts supplier that doesn’t know the reclamation window exists has no way to use it, and a business that finds out about it after the ten days have passed has lost a real, legally available remedy for reasons that had nothing to do with the merits of the claim.


The Michigan Legal Landscape

Statute of Limitations (contracts generally) 6 years — MCL § 600.5807
Statute of Limitations (open account/goods, per Fisher v. Sweebe) 6 years, not the UCC’s 4-year default
Seller’s Reclamation Right (pre-bankruptcy) 10-day written demand from buyer’s receipt — UCC § 2-702
Seller’s Reclamation Right (post-filing) 45-day written demand from buyer’s receipt — Bankruptcy Code § 546(c)
Administrative Priority Fallback Goods delivered within 20 days pre-filing — Bankruptcy Code § 503(b)(9)
Governing Consumer Law Michigan Regulation of Collection Practices Act, reaches original creditors (for consumer-adjacent accounts)

What This Costs

Step 1 & 2: Fixed-Fee Recovery (~$15/account). Professional demand sequences for accounts under roughly 60-90 days. Payments go directly to you. See the full pricing breakdown.

Step 3: Contingency Collection (20%~40%). For older or unresponsive accounts, no recovery, no fee.

Step 4: Legal Referral (client-approved, ~50%). For accounts genuinely warranting litigation, or coordination with counsel on time-sensitive reclamation and bankruptcy-priority claims.

Nexa Collections fixed-fee and contingency pricing structure


Who We Collect For Across Metro Detroit

  • Automotive Suppliers & Manufacturers: B2B and commercial receivables for Tier 1, 2, and 3 parts suppliers, tooling companies, and industrial vendors across the metro, with reclamation-eligibility screening built into intake for accounts tied to a buyer’s insolvency.
  • Distributors & Wholesalers: Trade credit recovery for companies extending net terms across the manufacturing and industrial supply base.
  • Logistics & Freight: Recovery for the transportation and warehousing companies supporting the region’s manufacturing corridor.
  • Professional Services: Commercial receivables for the engineering, staffing, and consulting firms serving the automotive sector.
  • Medical & Dental: HIPAA-compliant patient balance recovery for practices across the metro.
  • Property Management: Commercial and residential lease-end balance recovery across the region.

Recent Recoveries in Detroit

1. Tier-2 Automotive Tooling Supplier (Metro Detroit / Auburn Hills)

  • Balance: $13,800 (Delinquent 90-Day Custom Fabrication Invoices)

  • Outcome: Commercial B2B mediation resolved an invoice-matching discrepancy with corporate accounts payable, securing full wire settlement in two scheduled payments without disrupting ongoing purchase orders.

2. Industrial Freight & Warehousing Provider (Southwest Detroit)

  • Balance: $8,650 (Overdue Commercial Transport & Storage Fees)

  • Outcome: Direct outreach to the client’s corporate finance team clarified bill-of-lading documentation and secured 100% payment within 30 days.

3. Family & Cosmetic Dental Practice (Midtown Detroit)

  • Balance: $3,400 (Aged Patient Co-pays & Out-of-Pocket Balances)

  • Outcome: HIPAA-compliant digital notifications and structured 3-month payment arrangements recovered over 75% of past-due balances while preserving patient goodwill and clinic reviews.


Frequently Asked Questions

A customer we shipped goods to just declared bankruptcy. Can we get the goods back?

Possibly, but only if you act quickly. Under Bankruptcy Code § 546(c), a seller can generally reclaim goods the debtor received within 45 days before the bankruptcy filing, provided a written demand is made within that same 45-day window. Even where the goods themselves can’t be recovered, § 503(b)(9) can elevate the seller’s claim to administrative priority status for goods delivered in the 20 days before filing, ranking ahead of most unsecured claims even if it doesn’t return the goods directly.

What if we find out a buyer was insolvent before they’ve filed for bankruptcy?

UCC § 2-702 gives sellers a separate right in this situation: if a buyer received goods on credit while insolvent, the seller can demand their return, but generally only within 10 days of the buyer’s receipt of the goods. That deadline doesn’t apply if the buyer made a written misrepresentation of its solvency within the three months before delivery, but absent that, the ten-day window is strict, and missing it generally forfeits the reclamation right even though the underlying debt is still owed.

Is a Michigan trade account really time-barred after four years, or does it depend on the type of claim?

It depends. Michigan’s Supreme Court held in Fisher Sand & Gravel Co. v. Neal A Sweebe, Inc. that open-account and account-stated claims get the state’s 6-year contract limitations period under MCL § 600.5807, not the UCC’s 4-year default, even when the underlying transaction was a sale of goods. An account written off at four years under a generic assumption may still be legally actionable.

How does Nexa determine whether an account is eligible for goods reclamation versus standard collection?

We review the account’s timeline against both windows, the 10-day pre-bankruptcy demand period under UCC § 2-702 and the 45-day post-filing period under Bankruptcy Code § 546(c), as soon as an account is placed, since these deadlines run from the buyer’s receipt of the goods, not from when the seller learns about the situation. Accounts outside both windows move to standard commercial collection or, where appropriate, an administrative priority claim in the bankruptcy proceeding itself.

Does Detroit’s automotive supply chain create different collections risk than a typical manufacturing account elsewhere?

Meaningfully, yes. The multi-tier supplier structure common in automotive manufacturing means a single OEM or Tier 1 disruption can cascade through several layers of smaller suppliers at once, and the industry’s history of supplier restructurings makes insolvency-related risk a more routine consideration here than in a less concentrated manufacturing market. Building reclamation and bankruptcy-priority awareness into standard account handling matters more in this specific market than in most.

What documentation should we have ready if we need to act on a reclamation right quickly?

Proof of the delivery date (to calculate the 10 or 45-day window accurately), the original purchase order or contract terms, any correspondence suggesting the buyer’s financial condition at the time of the order, and, if applicable, standard terms and conditions language addressing acceptance as a representation of solvency. Having this ready before a crisis hits is what actually makes a ten-day deadline achievable.


Talk to Us About Your Detroit Commercial Receivables

Filed Under: Debt Recovery

Boston Medical Collection Agency | Serving Hospitals, Physicians & Dentists

A hospital billing office in most states can send an account to collections and, eventually, to court on a fairly standard timeline. Boston’s teaching hospitals operate under a materially different clock. Massachusetts requires roughly six months to pass from the first bill before a lawsuit can even be filed, layers state-specific financial assistance requirements on top of the federal minimum, and runs its own state-funded safety net most states simply don’t have. Getting the sequencing right here isn’t optional, it’s the difference between a collectible account and a compliance problem.

In short: Boston collections run on Massachusetts’ unusually protective hospital billing framework: a 180-day minimum from first bill before a lawsuit can be filed, free care mandated at 200% of the federal poverty level, a state Health Safety Net covering care up to 300% FPL, and a $1 million homestead exemption that matters directly for judgment enforcement. General consumer debt follows Massachusetts’ standard garnishment rules (15% of gross wages or the amount above 50x minimum wage, whichever is less), while the state’s newer 3%-interest, enhanced-garnishment-protection rules apply specifically to medical debt judgments, not debt generally. Nexa is HIPAA compliant and  recovers Boston accounts starting at a $15 fixed fee per account, with contingency options for older balances, built around this specific sequencing.

Boston Medical Debt Collection Agency for Hospitals & Healthcare Providers

Nexa provides reputation-safe, equipped with all 50-state collections license, offering free credit reporting, free litigation/bankruptcy scrubs, and zero onboarding fees. Secure – SOC 2 Type II & HIPAA compliant. Backed by a very helpful customer support team.

Need a Medical Collection Agency in Boston? Contact us


Why Boston’s Hospital Billing Rules Are Genuinely Different

The 180-day rule changes when an account is actually placeable. 
A hospital, or a collector acting for one, generally cannot initiate a lawsuit until at least 180 days have passed from the date of the first post-discharge bill. Placing an account for collection isn’t the same as suing on it, but the sequencing matters: financial assistance screening and payment plan negotiation are supposed to happen within this window, before any legal escalation, not as an afterthought once the clock has already run.

Financial assistance here goes beyond the federal floor. 
Every nonprofit hospital must publish a financial assistance policy under federal 501(r) rules, but Massachusetts’ Attorney General layers on additional requirements: free care at or below 200% of the federal poverty level, and hospitals cannot deny assistance for copays, coinsurance, or deductibles even when a patient has insurance. A meaningful share of Boston hospital accounts that look like straightforward non-payment are actually accounts that were never properly screened for a benefit the patient qualified for.

The Health Safety Net is a real, distinctly Massachusetts program. 
Beyond hospital-level financial assistance, the state itself funds a Health Safety Net covering care up to 300% of the federal poverty level, a legacy of Massachusetts’ 2006 healthcare reform, the model the ACA was later built on. This is a state-level backstop most other states don’t have, and it’s worth checking before assuming a patient balance is a dead end.

A $1 million homestead exemption changes what judgment enforcement actually looks like. 
Massachusetts protects up to $1 million in home equity from most creditor claims, a notably high figure. For a creditor evaluating whether pursuing a residential asset makes sense after judgment, this is a real number to know before spending on that path.

Worth flagging as pending, not current law: 
Governor Healey announced in January 2026 an intention to file regulations banning medical debt from credit reporting statewide. As of this writing, that’s an announced intention, not a finalized, currently-effective rule, worth watching rather than assuming is already in force.


The Massachusetts Legal Landscape

Pre-Suit Waiting Period (hospital debt) 180 days from first bill
Hospital Free Care Threshold 200% FPL (Attorney General Community Benefits Guidelines)
State Health Safety Net Coverage Up to 300% FPL
Homestead Exemption $1,000,000
General Wage Garnishment 15% of gross wages or amount above 50x minimum wage, whichever is less
Medical Debt Judgment Garnishment Enhanced protections: 3% interest cap, 65x minimum wage exemption (Debt Collection Fairness Act)
Call Frequency (940 CMR 7.00) 2 calls/7 days to residence, separate 2 calls/30 days to workplace numbers

What This Costs

Step 1 & 2: Fixed-Fee Recovery (~$15/account). Professional demand sequences timed appropriately around any applicable waiting periods. Payments go directly to you. See the full pricing breakdown.

Step 3: Contingency Collection (~40%). For older or unresponsive accounts, no recovery, no fee.

Step 4: Legal Referral (client-approved, ~50%). Timed to comply with any applicable pre-suit waiting period, filing fees reimbursed from the first recovery.

Nexa Collections fixed-fee and contingency pricing structure


Who We Collect For Across Boston

  • Academic Medical Centers & Hospitals: HIPAA-compliant patient balance recovery built around Massachusetts’ specific financial assistance sequencing, for the teaching hospitals and specialty practices concentrated in the Longwood Medical Area and beyond.
  • Universities & Higher Education: Tuition and program fee recovery for the region’s dense concentration of colleges and universities.
  • Biotech & Professional Services: B2B and commercial receivables for the life sciences, consulting, and financial services firms clustered around Kendall Square and the Financial District.
  • Property Management: Move-out and lease-end balance recovery for a rental market with unusually high annual turnover given the region’s student population.
  • Fitness & Membership Businesses: Recurring billing recovery for studios and gyms across the city.
  • Dental: Patient-first dental debt recovery for practices across the metro.

Frequently Asked Questions

How long does a Boston hospital have to wait before suing over an unpaid bill?

At least 180 days from the date of the first post-discharge bill. This waiting period exists specifically to give patients time to apply for financial assistance or negotiate a payment plan before legal escalation becomes an option, so an account placed for collection during this window should focus on resolution and screening, not litigation.

What income level qualifies a patient for free care at a Massachusetts hospital?

Generally 200% of the federal poverty level or below, under the Massachusetts Attorney General’s Community Benefits Guidelines, a higher threshold than federal law alone requires. Hospitals also cannot deny financial assistance for copays, coinsurance, or deductibles, even for patients who have insurance.

What is the Massachusetts Health Safety Net, and how is it different from hospital financial assistance?

It’s a state-funded program, separate from any individual hospital’s own financial assistance policy, that covers care for patients with income up to 300% of the federal poverty level. It’s a legacy of Massachusetts’ 2006 healthcare reform and represents a state-level backstop that most other states don’t have, worth checking on a patient account before assuming a balance is uncollectable from every angle.

How much home equity is protected from creditors in Massachusetts?

Up to $1,000,000 under the state’s homestead exemption, a notably high figure compared to most states. This matters directly for judgment enforcement: pursuing a debtor’s primary residence as an asset is generally not realistic in Massachusetts the way it might be in a state with a smaller or no homestead protection.

Does Massachusetts’ 3% interest cap on medical debt apply to all consumer debt, or just medical judgments?

Just medical debt judgments specifically, under the state’s Debt Collection Fairness Act. General consumer and commercial debt in Massachusetts follows the standard garnishment rule instead, 15% of gross wages or the amount exceeding 50 times minimum wage, whichever is less, a materially different and less protective framework than the medical-specific rules.

Is medical debt currently banned from credit reports in Massachusetts?

Not yet as a finalized rule, though it may be soon. Governor Healey announced in January 2026 that her administration intends to file regulations banning medical debt from credit reporting statewide. As of now, this is an announced intention rather than a currently effective regulation, worth watching rather than treating as settled.


Talk to Us About Your Boston Receivables

Filed Under: Debt Recovery

Collection Agency in El Paso, TX | Compliant, Cost Effective & Reputation Safe

A collections account in El Paso has a different shape than one in most Texas cities. The region combines healthcare, construction, logistics, professional services, schools, small businesses, commercial B2B companies, contractors, restoration firms, and utilities —all with very different types of overdue accounts.

Nexa helps El Paso organizations recover unpaid invoices and patient or customer balances through Texas-aware, reputation-safe collection strategies, secure data handling, nationwide coverage, and flexible fixed-fee or contingency options. Because El Paso is a major cross-border market, some accounts may involve debtors who have moved to Mexico, where a U.S. collection laws and judgments are not automatically enforceable and may require a separate recognition process through the Mexican courts. This situation is clearly outside the domain of US collection agencies.

Nexa starts fresher accounts with low-cost fixed-fee recovery from about $15 per account, escalates harder balances to contingency collections when appropriate, and supports clients with dedicated representatives, clear reporting, bankruptcy and address checks, credit reporting where permitted, and a professional approach designed to protect valuable relationships.

el paso collection agency

Need a Collection Agency in El Paso? Contact us


What the Border Actually Changes

A US judgment doesn’t just work in Mexico. If a debtor relocates across the border, enforcing a US judgment against them requires a formal Mexican legal process called homologation (or exequatur), and it’s genuinely demanding: service of process has to go through a Mexican court rather than a private process server, documents require apostille authentication, and everything needs certified translation into Spanish. Cross-border attorneys who specialize in exactly this describe the outcome as uncertain even when the underlying claim is sound. This is a materially different problem than domesticating a Texas judgment in another US state, which is comparatively routine, and it’s worth knowing early in an account’s life whether this is even a realistic path before spending on litigation.

Binational commercial relationships create their own version of this problem. El Paso’s economy runs heavily on cross-border trade, logistics, and manufacturing tied to Ciudad Juárez’s maquiladora sector. A commercial account involving a Mexican counterparty isn’t governed by the same straightforward domestic contract framework as a typical Texas B2B relationship, and assuming it is can lead to spending on collection or litigation efforts that don’t actually translate into enforceable recovery.

Fort Bliss adds a real, if secondary, layer. One of the largest Army installations by land area in the country sits just outside the city, meaning a meaningful share of consumer accounts involve active-duty servicemembers or veterans, bringing the federal Servicemembers Civil Relief Act into play, interest caps on pre-service debt, and military-status verification requirements before a default judgment.


The Texas Legal Landscape

Statute of Limitations (most consumer debt) 4 years — Tex. Civ. Prac. & Rem. Code § 16.004
Wage Garnishment Not allowed for most consumer debts (exceptions: child support, taxes, certain federal student loans)
Governing Consumer Law Texas Finance Code Chapter 392, reaches original creditors, not just agencies
Third-Party Collector Bonding $10,000 surety bond with the Texas Secretary of State
Cross-Border Enforcement (Mexico) Requires Mexican court homologation/exequatur; not automatic
Judgments Generally enforceable for 10 years, renewable

What This Costs

Step 1 & 2: Fixed-Fee Recovery (~$15/account). Professional demand sequences for accounts under roughly 90 days, while the debtor’s location and reachability are still clear. Payments go directly to you. See the full pricing breakdown.

Step 3: Contingency Collection (~40%). For older or unresponsive accounts, no recovery, no fee.

Step 4: Legal Referral (client-approved, ~50%). For accounts where litigation is genuinely warranted domestically, with an honest assessment given if cross-border enforcement would be required.

Nexa Collections fixed-fee and contingency pricing structure


Who We Collect For Across El Paso

  • Medical & Dental: HIPAA-compliant patient balance recovery for practices across the metro’s hospital and outpatient network.
  • Trade, Logistics & Manufacturing: B2B and commercial receivables for the freight, customs brokerage, and manufacturing-adjacent companies operating along the border corridor.
  • Property Management: Move-out and lease-end balance recovery for the metro’s rental market.
  • Fitness & Membership Businesses: Recurring billing recovery for studios and gyms across the city.
  • Schools & Education: Tuition and program fee recovery for the region’s private schools and training programs.
  • Utilities: Utility account recovery across the El Paso service territory.

Recent Recovery Results

1. Private Preparatory School (West El Paso)

  • Balance: $5,800 (Overdue Tuition & Auxiliary Program Fees)

  • Outcome: Resolved through a diplomatic, bi-lingual outreach process that established a manageable 4-month installment plan, preserving the family’s relationship with the school.

2. Outpatient Specialist Clinic (Central El Paso / MCA District)

  • Balance: $4,200 (Past-Due Patient Co-pays & Deductibles)

  • Outcome: HIPAA-compliant balance reminders and a simplified digital payment link recovered 75% of the outstanding self-pay balances within 40 days.

3. Cross-Border Logistics & Warehousing Supplier (East El Paso)

  • Balance: $12,400 (Delinquent 90-Day Freight & Storage Invoices)

  • Outcome: Professional commercial mediation cleared up an accessorial billing dispute, securing full wire payment from the client’s corporate office in two scheduled payments.


Frequently Asked Questions

Can we actually collect from a debtor who has moved to Mexico?

It’s genuinely harder than domestic collection, not impossible, but it requires realistic expectations. A US judgment isn’t automatically enforceable in Mexico, it requires a separate Mexican court process called homologation, involving formal service through a Mexican court, document authentication, and certified translation. Attorneys who specialize in this describe outcomes as uncertain even on sound claims, so this route generally makes sense only for larger balances where the cost is justified, and it requires coordination with Mexican legal counsel rather than a standard domestic collection step.

Does the Texas Debt Collection Act apply the same way to accounts involving a Mexican business counterparty?

Texas Finance Code Chapter 392 governs collection conduct within Texas and reaches original creditors as well as agencies, but a commercial dispute involving a Mexican counterparty may also implicate Mexican contract and enforcement law depending on where the agreement was formed and where assets are located. Assuming a purely domestic Texas framework applies to every cross-border commercial account can lead to pursuing a path that doesn’t actually produce enforceable recovery.

Can wages be garnished for unpaid debt in El Paso?

Generally no. Texas broadly prohibits wage garnishment for most consumer debts, with narrow exceptions for child support, taxes, and certain federal student loans, which shifts practical focus toward voluntary payment plans and, once a judgment is obtained domestically, remedies like bank levies rather than garnishment.

How long does an El Paso business have to collect on an unpaid account?

Generally four years for most consumer debt under Tex. Civ. Prac. & Rem. Code § 16.004. In a border market where a debtor may relocate across an international line rather than just across town, placing an account early matters even more than usual, since a debtor who has crossed the border becomes significantly harder to reach the longer an account sits.

Does Fort Bliss’s presence change how consumer accounts should be handled in El Paso?

Yes, for a meaningful share of accounts. Given the installation’s scale, a real portion of the local consumer debtor population is active-duty military or recently separated, which brings the Servicemembers Civil Relief Act into play: interest on pre-service debt can generally be capped at 6% upon request, and courts must verify military status before entering a default judgment against a non-responsive debtor.

If homologation isn’t realistic for a given account, what’s actually left?

Often a negotiated resolution reached before the debtor relocates, or focusing collection effort on any assets or income the debtor still has within US jurisdiction rather than pursuing enforcement in Mexico at all. Assessing this early, ideally before an account is placed for months, gives a more realistic picture of what’s actually recoverable than discovering the debtor has moved after litigation has already been pursued.


Talk to Us About Your El Paso Receivables

Filed Under: Debt Recovery

Collection Agency in Washington DC | Medical, Schools, Businesses & Contractors

Washington, D.C. is not a place for one-size-fits-all debt collection. Consumer accounts face unusually detailed procedural requirements—including strict documentation and service-of-process rules—while medical, commercial B2B, professional-service and other debts each require a different recovery strategy. Nexa combines D.C.-aware compliance, reputation-safe communication, secure handling and account-specific recovery to help organizations collect what they are owed without creating unnecessary legal or reputational risk.

In short: Washington, D.C. runs one of the strictest, most procedurally detailed debt collection codes reviewed anywhere in this project (D.C. Code § 28-3814): a permanent ban on visiting a debtor’s home or workplace, a call cap of 4 per account per week, a 3-year statute of limitations that explicitly cannot be revived by a later payment, and a GPS-and-timestamp photo requirement for proof of service in any lawsuit. Nexa recovers D.C. accounts starting at a $15 fixed fee per account, with contingency options for older balances, run against this specific procedural framework from the first contact.

Washington, DC collection agency offering compliant, reputation-safe debt recovery, secure data handling, nationwide coverage, dedicated support, and flexible fixed-fee or contingency options.

Need a Collection Agency in Washington, D.C.? Contact us


The Procedural Rules That Make D.C. Different

Proof of service has to be photographic and GPS-verified. 
Under § 28-3814(p), before filing suit a collector must reasonably investigate the debtor’s current address, and when proof of service is filed with the court, it must include a photograph with a readable timestamp and readable GPS coordinates showing where service occurred. This exists specifically to prevent “sewer service”, falsely claiming service happened to obtain a default judgment, and it means any lawsuit filed here needs genuinely rigorous documentation from the process server, not just a signed affidavit.

Home and workplace visits are permanently off the table. 
Separate from D.C.’s (currently inactive) pandemic-era provisions, § 28-3814(d) permanently bars a collector from visiting a consumer’s household or place of employment at any time for collection purposes, the only exception is serving legal process. Contact has to happen by phone, mail, or approved electronic channels.

Contact frequency is capped tighter than the federal norm. 
D.C. limits calls to 4 per account in any 7-day period (versus the more commonly cited federal benchmark of 7), and after a completed call, no callback for 7 days unless the consumer asks for one. Text messages, emails, and social media messages are capped at 5 per account per week, and none of those channels can be used at all before the required written validation notice has been mailed.

The statute of limitations doesn’t bend for a later payment. 
Under § 28-3814(o), consumer debt actions must generally be filed within 3 years of accrual, “notwithstanding the provisions of any other statute of limitations.” Section (l) goes further than most states’ case law by saying so directly: once that period expires, a later payment or written or oral acknowledgment does not revive it. D.C. joins Maine, Maryland, and Minnesota as a non-revival jurisdiction, stated with more statutory clarity than most.


The Washington, D.C. Legal Landscape

Statute of Limitations (consumer debt) 3 years, non-revivable — D.C. Code § 28-3814(o), (l)
Home/Workplace Visits Permanently prohibited for collection purposes — § 28-3814(d)(5)-(6)
Call Frequency Max 4 per account per 7-day period — § 28-3814(d)(4)(A)
Text/Email Frequency Max 5 per account per 7-day period, after written notice — § 28-3814(d)(4)(B)
Proof of Service GPS-tagged, timestamped photograph required — § 28-3814(p)
Attorney’s Fees Generally capped at 15% of the debt absent detailed justification — § 28-3814(v)
Imprisonment for Debt Prohibited outright — § 28-3814(y)
Statutory Damages $500–$4,000 per violation, plus actual and punitive damages — § 28-3814(u)

What This Costs

Step 1 & 2: Fixed-Fee Recovery (~$15/account). Five professional demand touches for accounts under roughly 60 days. Payments go directly to you. See the full pricing breakdown.

Step 3: Contingency Collection (20%~40%). For older or unresponsive accounts, no recovery, no fee.

Step 4: Legal Referral (client-approved, ~50%). Handled with the documentation rigor D.C.’s courts specifically require, filing fees reimbursed from the first recovery.

Nexa Collections fixed-fee and contingency pricing structure


Who We Collect For Across the District

  • Medical & Dental: HIPAA-compliant patient balance recovery for practices across the district’s hospital and outpatient network.
  • Government Contractors, Law Firms & Associations: B2B and commercial receivables for the professional services, consulting, and trade-association sector that defines much of D.C.’s private-sector economy.
  • Nonprofits & Membership Organizations: Recurring dues and program-fee recovery for the district’s dense concentration of associations and advocacy organizations.
  • Schools & Education: Tuition and program fee recovery for the district’s private schools and universities.
  • Property Management: Move-out and lease-end balance recovery for the district’s rental market.
  • Fitness & Membership Businesses: Recurring billing recovery for studios and gyms across the city.

Recent Recovery Results

1. Private Day School (NW Washington, DC)

  • Balance: $6,400 (Past-Due Tuition & Program Fees)

  • Outcome: Resolved via a diplomatic 3-month payment plan after skip tracing located the relocated parent, recovering the balance without damaging school-community relations.

2. Outpatient Medical Clinic (Downtown DC)

  • Balance: $3,850 (Aging Patient Co-pays & Deductibles)

  • Outcome: HIPAA-compliant outreach and online payment portal setup resulted in over 70% direct payment settlement within 45 days.

3. Commercial IT & Professional Services (K Street Corridor)

  • Balance: $11,500 (Delinquent 90-Day Vendor Invoices)

  • Outcome: Professional B2B mediation with corporate accounts payable resolved a billing dispute and secured full wire settlement in two installments.


Frequently Asked Questions

Why does a debt collection lawsuit in D.C. require a photo with GPS coordinates?

Because D.C. Code § 28-3814(p) requires it specifically to prevent “sewer service,” a process server falsely claiming a defendant was served in order to obtain a default judgment. When proof of service is filed with the court, it must include a photograph with a readable timestamp and readable GPS coordinates showing the location of service, a documentation standard well beyond what most jurisdictions require.

Can a collection agency visit a debtor’s home or workplace in D.C.?

No, not for the purpose of collecting a debt. § 28-3814(d) permanently prohibits visiting a consumer’s household or place of employment at any time for collection purposes, with the only exception being to serve legal process. This is a standing rule, separate from D.C.’s pandemic-era provisions, which suspended other collection activity but are not currently in effect.

How many times can a collector call a D.C. resident in a week?

Generally no more than 4 times per account in any 7-day period, stricter than the 7-per-week benchmark commonly cited under federal rules. After a completed call, the collector generally cannot call back for 7 days unless the consumer requests it.

If a debtor makes a payment on an old D.C. debt, does that restart the clock?

No. Under § 28-3814(l), once the 3-year statute of limitations on a consumer debt has expired, a later payment or a written or oral acknowledgment does not revive it. D.C. states this directly in statute, more explicitly than most states leave to case law.

Are attorney’s fees capped if a collection lawsuit goes to judgment in D.C.?

Generally yes. Under § 28-3814(v), a contractual attorney’s fee provision is enforceable up to 15% of the debt, excluding fees and collection costs, unless the prevailing party applies to the court with a detailed, itemized justification for a higher amount and the court finds the additional fees were reasonably necessary.

Does D.C.’s law treat debt buyers differently from original creditors pursuing their own accounts?

Yes, significantly. Before a debt buyer can obtain a default or summary judgment, § 28-3814(s) requires account-specific affidavits establishing the debt from the original creditor and from every subsequent party in the chain of ownership, a real evidentiary burden that doesn’t apply to original creditors collecting their own debt.


Talk to Us About Your Washington, D.C. Receivables

Filed Under: Debt Recovery

  • « Go to Previous Page
  • Page 1
  • Page 2
  • Page 3
  • Page 4
  • Interim pages omitted …
  • Page 55
  • Go to Next Page »

Primary Sidebar


accounts receivable

Need a Collection Agency?
Kindly fill this form.
We’ll get in touch with you

    Please prove you are human by selecting the cup.

    Compliance & Security

    • SOC 2 Type II Certified: Third-party audited data security and strict privacy controls.

    • HIPAA Compliant: Secure, legal processing of medical and municipal EMS accounts.

    • PCI-DSS Level 1: Highest tier of data encryption for secure payment processing.

    • FDCPA & FCRA Aligned: Full legal adherence to federal consumer protection laws.

    Recent Posts

    • Why Dental Patients Dispute Bills: The Nexa Collections Dental Account Dispute Index
    • 2027 Commercial Collections Benchmark: U.S. Late Payments, AR Risk and B2B Collection Trends
    • Bulk Account Placement: What a Collection Agency Actually Needs From You
    • Nationwide Debt Collection Agency Serving U.S. Cities
    • Chula Vista Collection Agency for Medical, B2B, Schools & Business Debt
    • Corpus Christi Collection Agency: Itemized Bill Rules for Practices
    • Riverside Collection Agency | For Logistics, Medical, Schools & Business Recovery
    • Collection Agency for Large Balances: High-Value B2B Debt Recovery

    Featured Posts

    • How to Find New Clients for a Medical Accounting Firm
    • How to Prevent your Business from Losing Customers
    • Collection Agency for Semen Distributors & Breeders

    Copyright © 2026 NEXACOLLECT.COM | This content is provided for general informational purposes only and should not be considered legal advice. Collection laws and requirements may vary by state, account type, documentation, debtor status, and specific facts. Please consult qualified legal counsel for guidance regarding your particular situation. Nexa and its authorized collection partners service accounts in accordance with applicable federal and state collection requirements. Visit our home page to know more about us.

    X
    Need a Collection Agency?
    Contact Us