The United States is approaching a remarkable financial milestone: $40 trillion in national debt.
That number is so large that it naturally raises a frightening question:
🔥 How will America ever pay it back?
The surprising answer is that the United States probably will not pay off the entire national debt in the way an individual pays off a mortgage or car loan.
Instead, the real objective is to manage the debt, refinance it as it matures, keep interest payments affordable, and grow the economy fast enough that the debt becomes more manageable relative to the size of the economy.
That distinction is important.
A $40 trillion national debt does not automatically mean the United States is about to go bankrupt. But the speed at which the debt and interest costs are growing has become a serious long-term economic challenge.
What Does $40 Trillion of U.S. Debt Actually Mean?
The national debt represents the accumulated amount the federal government has borrowed over many years when government spending exceeded government revenue.
To finance those deficits, the U.S. Treasury issues securities including Treasury bills, notes and bonds. Investors, banks, pension funds, governments, financial institutions and other buyers purchase those securities and receive interest in return.
The headline national-debt number includes two major categories: debt held by the public and intragovernmental debt, which is money owed by one part of the federal government to another.
This distinction matters when comparing the debt with GDP.
The Congressional Budget Office projects federal debt held by the public at about 101% of GDP in 2026, rather than the roughly 140% figure sometimes quoted when different definitions of government debt are mixed together.
The problem is not simply that the debt is large. The bigger concern is that, under current policy, debt is projected to keep growing faster than the U.S. economy.
America Does Not Have to Repay $40 Trillion at Once
One of the biggest misconceptions about the national debt is that the government will eventually receive a giant $40 trillion bill that it has to pay.
That is not how sovereign debt works.
Treasury securities mature at different times. When a Treasury bond matures, the government can repay the investor and issue new Treasury securities to raise the money needed to finance existing obligations.
This process is known as refinancing or rolling over the debt.
Governments around the world routinely do this.
As long as investors remain willing to purchase U.S. Treasury securities at sustainable interest rates, the United States can continue refinancing a significant portion of its debt rather than eliminating the entire balance.
The U.S. Treasury market has an enormous advantage here. It remains one of the world’s deepest and most liquid financial markets, and Treasury securities are widely used as safe assets, collateral and benchmarks for interest rates throughout the global financial system.
But refinancing becomes much more expensive when interest rates rise.
The Real Problem: Interest on the Debt
The size of the national debt attracts headlines, but the more immediate concern is the cost of servicing it.
When interest rates were extremely low, the federal government could carry large amounts of debt relatively cheaply.
That environment has changed.
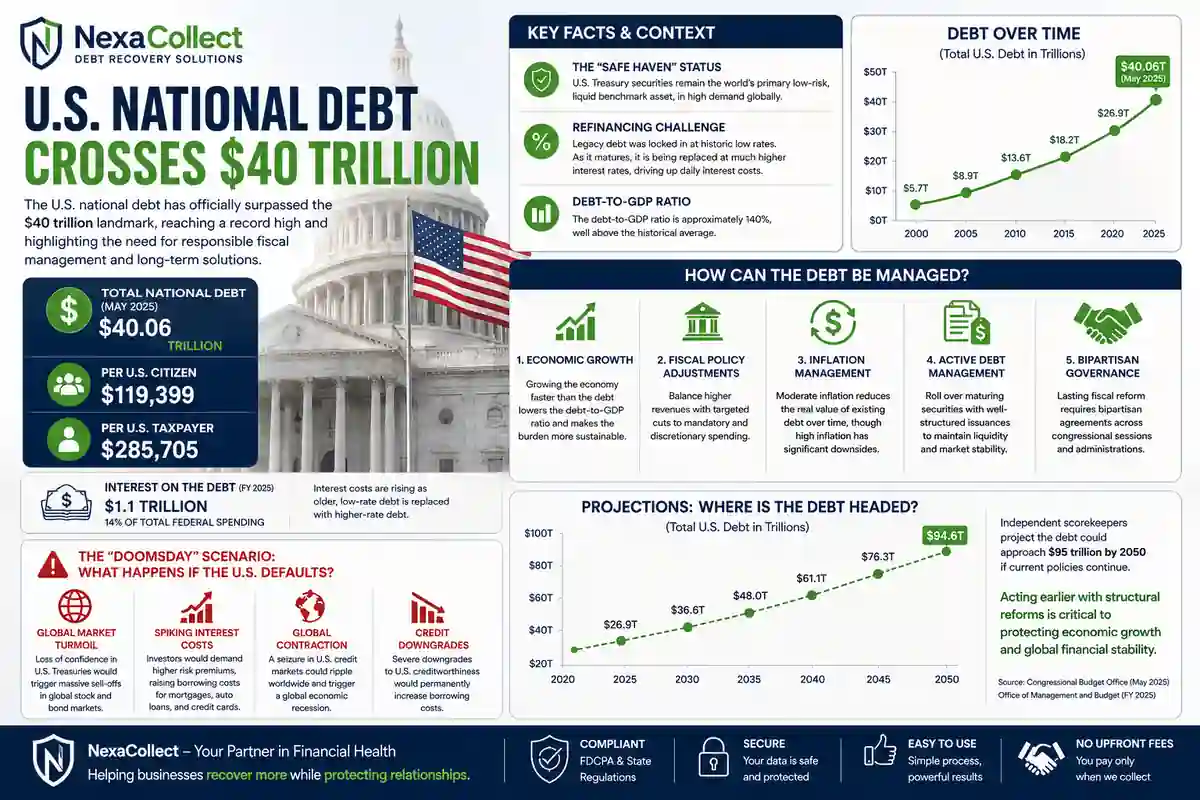
As older Treasury securities mature, some must be replaced with newly issued securities carrying higher interest rates. That means the government’s interest bill can rise even without an equally dramatic increase in the amount borrowed.
The Government Accountability Office reported that federal interest costs reached roughly $1.2 trillion in fiscal 2025, while net interest spending exceeded federal defense spending.
And the pressure may increase.
CBO projects that net federal interest outlays could rise to approximately $2.1 trillion annually by 2036 under its baseline assumptions.
Every additional dollar spent servicing past debt is a dollar that cannot easily be used for infrastructure, defense, healthcare, research, education or other government priorities without increasing taxes or borrowing even more.
That is why controlling the growth of the debt matters.
So How Can the United States Manage $40 Trillion of Debt?
There is no single solution.
The most realistic outcome would involve several strategies working together over many years.
1. Grow the Economy Faster
Economic growth is arguably the least painful way to make a large debt burden more manageable.
Suppose national debt continues rising, but the U.S. economy grows even faster.
In that situation, debt becomes smaller relative to GDP, even if the actual dollar amount of debt remains very large.
A growing economy also usually produces more tax revenue because companies earn more, workers earn more and consumers spend more.
This is why productivity improvements from areas such as artificial intelligence, automation, advanced manufacturing, energy innovation and new technologies could ultimately matter for America’s fiscal position.
The objective does not necessarily have to be reducing the debt to zero.
It can instead be to stop debt from growing faster than the country’s ability to support it.
2. Reduce Persistent Federal Deficits
Debt grows primarily because the federal government repeatedly spends more than it collects.
CBO projects a federal budget deficit of roughly $1.9 trillion in fiscal 2026, rising to approximately $3.1 trillion annually by 2036 under current-law assumptions.
If Washington wants to stabilize the debt, eventually it has to reduce the gap between revenue and spending.
That could involve some combination of higher tax revenue, slower spending growth, changes to federal programs, reforms to entitlement programs or reductions in other expenditures.
None of those choices are politically easy.
That is precisely why America’s debt problem has persisted.
The mathematics may be relatively straightforward. The political decisions are considerably harder.
3. Keep Interest Rates and Inflation Under Control
Moderate inflation can reduce the real value of previously issued fixed-rate debt.
For example, $1 trillion owed 20 years from now does not have the same purchasing power as $1 trillion today.
But inflation is not a free solution.
High inflation can hurt consumers, reduce purchasing power and cause investors to demand higher interest rates on new Treasury debt.
That would increase the government’s borrowing costs and potentially offset some of the benefits of reducing the inflation-adjusted value of existing debt.
Therefore, deliberately creating very high inflation would be an extremely risky way to address the debt.
4. Continue Refinancing Treasury Debt
The Treasury will continue replacing maturing securities with new securities.
That is normal debt management.
The challenge is maintaining sufficient investor confidence that the United States can refinance at reasonable interest rates.
Demand for Treasury securities remains extraordinarily important because Treasury yields affect borrowing costs across much of the economy, including corporate debt and mortgages.
The stronger the confidence in America’s economy, institutions and fiscal management, the easier it is for Treasury to finance government borrowing.
5. Make Gradual Fiscal Reforms Instead of Waiting for a Crisis
Perhaps the most realistic long-term solution is not one dramatic tax increase or spending cut.
It is a series of smaller changes implemented over many years.
Gradual reforms give businesses, households and financial markets time to adjust.
Waiting until debt markets force the government to take action could require much more painful decisions.
The Government Accountability Office describes the current federal fiscal path as unsustainable and has urged Congress to develop a comprehensive strategy for addressing it.
Why Can’t America Just Print $40 Trillion?
This is another common question.
The United States has a major advantage because its debt is denominated primarily in its own currency: the U.S. dollar.
But that does not mean it can simply create unlimited dollars without consequences.
Creating enormous quantities of money to finance government obligations could undermine confidence in the currency and create severe inflation.
Investors could then demand substantially higher yields to hold Treasury securities, making future government borrowing more expensive.
In other words, printing money might appear to solve the debt problem mathematically while creating an entirely different economic problem.
Could the U.S. Simply Raise Taxes?
Higher tax revenue could reduce deficits, but solving the entire problem through taxes alone would be difficult economically and politically.
Higher taxes can raise government revenue, but depending on how they are structured, they can also affect investment, consumption, business formation and economic growth.
The same problem exists on the spending side.
Large reductions in government spending could improve the fiscal balance but might affect retirees, healthcare programs, defense, infrastructure or other services.
That is why most realistic long-term fiscal solutions involve a combination of economic growth, revenue changes and spending restraint rather than relying entirely on one policy.
What Happens If Nothing Changes?
This is where the projections become concerning.
CBO estimates that federal debt held by the public could increase from about 101% of GDP in 2026 to 120% by 2036.
Looking even further ahead, CBO projects the ratio could reach approximately 175% of GDP by 2056 under its baseline assumptions.
These are projections, not guarantees.
Economic growth could be stronger. Government policies could change. Interest rates could decline. Technology could increase productivity and tax revenue.
But the numbers demonstrate why economists focus less on today’s $40 trillion headline and more on the trajectory.
A country can sustain a large debt for a long time.
What becomes increasingly difficult to sustain is debt that consistently grows faster than the economy supporting it.
Could the United States Actually Default?
A U.S. default would mean the federal government failed to make required payments on its debt obligations on time.
That would be fundamentally different from simply having a very large national debt.
Treasury securities occupy a central position in global finance. They are widely treated as highly liquid, high-quality assets and are extensively used as financial collateral and pricing benchmarks.
A genuine U.S. default could therefore affect far more than Washington.
Credit markets could experience severe disruption, Treasury borrowing costs could rise sharply and financial stress could spread throughout the U.S. and global economies. Both the Treasury Department and CBO have warned that a default could have extremely serious economic consequences.
Higher Treasury yields could also filter through to interest rates paid by businesses and households.
Mortgages, corporate loans and other forms of credit are ultimately influenced by conditions in the Treasury market.
This is one reason policymakers generally view an intentional default as an unacceptable solution to the national debt.
Default does not solve the debt problem. It could make borrowing much more expensive.
Could the Dollar Lose Its Global Importance?
Another long-term concern is whether excessive U.S. borrowing could eventually weaken confidence in the dollar and Treasury securities.
The dollar and U.S. Treasury market currently enjoy enormous structural advantages. Treasury securities remain deeply embedded in global financial markets as safe, liquid assets, collateral and benchmarks.
Those advantages are difficult to replace quickly.
However, reserve-currency status should not be interpreted as permission for unlimited borrowing.
If investors eventually demanded significantly higher compensation for holding U.S. government debt, America’s interest expense could rise substantially.
Maintaining global confidence is therefore one of the country’s most valuable financial assets.
Is $40 Trillion a Financial Doomsday?
Not by itself.
The United States remains one of the world’s largest economies and operates the world’s most important sovereign bond market.
The government does not need to suddenly produce $40 trillion in cash.
The more important questions are:
Can the U.S. economy continue growing?
Can Washington prevent annual deficits from expanding indefinitely?
Can interest costs remain manageable?
And will global investors continue trusting Treasury securities?
If the answers remain positive, the United States can carry a very large national debt for many years.
If debt and interest payments continually grow faster than the economy, however, policymakers will eventually face increasingly difficult choices.
The Bottom Line
So, how will the United States pay off its $40 trillion national debt?
Most likely, it won’t completely pay it off.
And it does not necessarily need to.
Instead, America will continue refinancing maturing debt, growing the economy, collecting taxes and issuing new Treasury securities.
The real objective should be to stabilize the debt relative to the economy and prevent interest costs from consuming an ever-larger share of the federal budget.
That requires stronger economic growth, responsible fiscal policy, sustainable government spending and continued global confidence in the U.S. financial system.
The $40 trillion number is undoubtedly enormous.
But the most important number to watch over the coming decades may not be the absolute size of the national debt.
It may be how fast the debt grows compared with the American economy’s ability to support it.
That will ultimately determine whether America’s debt remains manageable—or becomes one of the country’s biggest economic challenges.