A debt collection lawyer does much more than file lawsuits. The real job is to determine whether legal action makes financial sense, prove the debt, obtain a judgment when necessary, and then turn that judgment into actual money. Winning a judgment and getting paid are two different things, and a good attorney evaluates collectability before spending the creditor’s money on litigation, not after. This matters for business owners, medical practices, schools, landlords, and contractors alike: the value of a collection attorney isn’t just legal firepower, it’s judgment about when that firepower is actually worth using.
Lawyer Fee: Debt collection lawyers commonly charge about 25%–50% of the amount recovered on a “no win, no fee” contingency basis, meaning the lawyer earns a fee only if money is collected; however, court costs, filing fees, service-of-process fees, and similar litigation expenses are generally paid separately by the client, not the lawyer. This means anywhere between $100 to $500 in upfront cost (often recoverable if added to the judgment).
The Process, Start to Finish
Debt Review → Collectability Check → Attorney Demand → Negotiation → Lawsuit → Service → Judgment → Asset Discovery → Garnishment / Levy / Lien → Payment
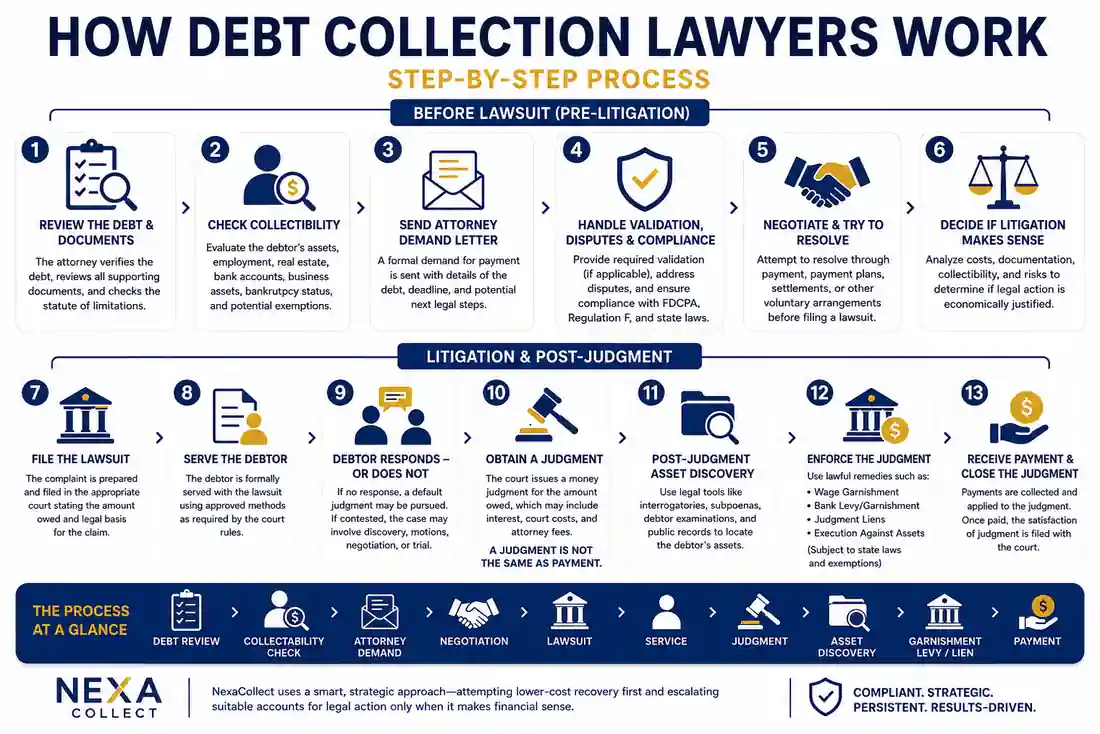
Step 1: Review the Debt and Supporting Documents
Before anything else, the attorney verifies whether the debt can legally and practically be pursued. This starts with documentation.
Stronger documentation makes litigation faster, cheaper, and more likely to succeed. Useful records include the signed contract, credit application, personal guarantee, invoices, account statements, purchase orders, work orders, delivery receipts, emails or text correspondence, payment history, and any previous collection notes. A file with a signed agreement and a clear paper trail of what was delivered and when is a fundamentally different case than an unsigned invoice with no supporting correspondence.
The attorney also checks whether the debt is still within the applicable statute of limitations. This period varies by state and by the type of obligation (written contract, oral agreement, open account), so this is confirmed for the specific account, not assumed from a general rule of thumb.
Step 2: Check Whether the Debtor Is Actually Collectible
This step is arguably the most important one in the entire process, and it’s also the one most often skipped.
A good attorney should not automatically recommend litigation just because a debt is valid and provable. Before filing suit, the attorney or collection team typically evaluates whether the business is still operating, the debtor’s current address, employment status, real estate ownership, business assets, bankruptcy status, and any existing judgments or liens against the debtor. Some of this information is available through lawful public records and skip-tracing tools even before a lawsuit is filed; other information, like detailed bank account data, generally requires post-judgment legal tools discussed later.
A lawyer should always run a pre-litigation asset and bankruptcy scrub before advancing court filing fees to avoid wasting money on an uncollectible “paper judgment” against a judgment-proof debtor.
A $50,000 judgment against someone with no collectible assets may be worth less than a $10,000 judgment against a financially healthy debtor. Pre-litigation screening exists precisely to avoid the first scenario: spending real money on a lawsuit that produces a piece of paper rather than a payment.
Step 3: Send an Attorney Demand Letter
Before filing anything in court, many attorneys send a formal demand letter. This typically states the creditor’s name, the amount owed, the basis for the debt, a payment deadline, instructions for resolving the account, and, where appropriate, the potential next legal steps if the account isn’t resolved.
An attorney letter often creates more urgency than an ordinary invoice or a standard collection reminder, simply because it signals that legal escalation is a real possibility, not just a phrase in a form letter. That said, not every debtor pays after receiving one. For some accounts, this letter resolves the matter; for others, it’s simply the next documented step before deciding whether litigation is worth pursuing.
Step 4: Handle Validation, Disputes, and Legal Compliance
Consumer debts are generally subject to the federal Fair Debt Collection Practices Act (FDCPA) and its implementing rule, Regulation F. This matters for attorneys specifically: under Heintz v. Jenkins, 514 U.S. 291 (1995), attorneys who regularly collect consumer debts, including through litigation, may themselves be considered “debt collectors” under federal law, with the same compliance obligations that apply to any other collector.
If a debtor disputes the account, supporting documentation generally needs to be reviewed before further collection activity continues. This is also where consumer debt and commercial (B2B) debt genuinely diverge: the FDCPA’s specific protections apply to personal, family, or household debts, not to a business-to-business invoice dispute, though state-level commercial collection laws and general contract principles still apply to those accounts.
Step 5: Try to Resolve the Account Before Filing Suit
Litigation is often not the first objective, and a well-run collection process treats it as a last resort rather than a default move.
Possible resolutions at this stage include full payment, a short-term payment arrangement, a structured payment plan, a negotiated settlement, or, in some commercial contexts, a voluntary business resolution. An attorney may use the credible possibility of litigation, the fact that a lawsuit genuinely could be filed, to encourage resolution without ever actually filing a case. This is often the fastest and cheapest outcome for everyone involved.
Step 6: Decide Whether Litigation Makes Financial Sense
This is where the earlier collectibility screening pays off. A practical decision to litigate weighs the balance owed, the age of the debt, the strength of the documentation, whether the debt is disputed, filing fees, attorney costs, the debtor’s location, the likelihood of successfully serving the debtor, available assets, bankruptcy risk, possible legal exemptions, and the expected net recovery after all of that.
The goal is not to win a lawsuit for the sake of winning. The goal is to recover more money than the legal process costs. A technically winnable case against a judgment-proof debtor is still, in practical terms, a losing proposition.
Step 7: File the Lawsuit
Once litigation is the right call, the process itself is fairly straightforward. A complaint is prepared, stating the amount owed and the legal basis for the claim, and filed in the appropriate court. Court filing fees are paid at this stage. The defendant then has to be formally served, which is a separate step from filing.
Venue and jurisdiction, meaning which court has the authority to hear the case, can depend on the type of debt and where the parties are located. This varies enough by state and case type that it’s worth confirming for the specific situation rather than assuming a single rule applies everywhere.
Step 8: Serve the Debtor
Filing a lawsuit does not automatically notify the debtor that it exists. The defendant generally must be formally served according to the specific court’s rules, commonly through a process server, a sheriff’s office, certified mail where permitted, or another court-approved method.
If the debtor can’t be located, service can be delayed, which in turn delays the entire case. This is one of several reasons accurate address information, ideally confirmed before litigation even begins, matters as much as it does.
Step 9: Debtor Responds — or Does Not Respond
From here, the case follows one of two paths.
If the debtor does not respond, the attorney may seek a default judgment, subject to the specific court’s requirements for proving proper service and the amount owed.
If the debtor contests the case, the matter can involve a formal answer, legal defenses, discovery, document production, depositions in some cases, pre-trial motions, negotiation, and, if none of that resolves things, trial. Many lawsuits settle before ever reaching trial, often once both sides have a clearer picture of the evidence and the likely outcome.
Step 10: Obtain a Judgment
A money judgment formally establishes that the debtor owes a specific, court-recognized amount. Depending on the underlying contract and applicable law, that amount may include the principal balance, accrued interest, court costs, and attorney’s fees where those are legally recoverable.
A judgment is not the same thing as payment. It’s a legal determination, not a transfer of money. Everything from this point forward is about converting that legal determination into an actual recovery.
Step 11: Post-Judgment Asset Discovery
Once a judgment exists, an attorney generally has stronger legal tools available to locate a debtor’s assets than were available before. Depending on state law, these can include written interrogatories, formal requests for financial information, subpoenas, in-person debtor examinations, public-record searches, employer identification, and bank discovery.
This is often where a skilled collection attorney adds the most real value, not in winning the case itself, which is frequently uncontested, but in actually finding something worth collecting against once the judgment is in hand.
Step 12: Enforce the Judgment
Enforcement methods vary meaningfully by state, and exemptions can protect a real share of a debtor’s income or property from being reached at all. None of the following is automatically available in every state or every case.
Wage Garnishment
Part of a debtor’s eligible wages may be withheld, subject to state and federal limits and exemptions, some states protect a much larger share of income than others, and several states restrict or prohibit wage garnishment for most ordinary consumer debts entirely.
Bank Levy or Garnishment
Non-exempt funds in a qualifying bank account may potentially be seized to satisfy the judgment, though exempt funds (certain benefits, for example) generally cannot be reached.
Judgment Liens
A judgment may, depending on the state, attach to real property the debtor owns, creating a claim that generally has to be resolved before that property can be sold or refinanced.
Execution Against Assets
Certain non-exempt personal property may potentially be seized or sold under court procedures, though many states protect a meaningful amount of personal property from this kind of execution.
State exemptions vary significantly, and it should never be assumed that a judgment automatically means a debtor’s wages or bank account can be garnished. In many cases, some or all of a debtor’s income and assets are legally protected, which is exactly why the collectibility screening in Step 2 matters so much before money is spent getting to this point.
Step 13: Receive Payment and Close the Judgment
Once enforcement produces payment, whether through garnishment, a levy, a lien resolution, or a negotiated settlement, payments are tracked and the judgment balance is reduced accordingly. Interest may continue to accrue on any unpaid portion where legally permitted. Once the judgment is fully paid, the appropriate satisfaction or release of judgment generally needs to be filed with the court.
Failing to properly record that satisfaction can create real problems later, for the debtor, whose credit and property records may continue to show an unpaid judgment, and for the creditor, who may face questions about the account’s status well after it was actually resolved.
When Should a Collection Agency Send an Account to an Attorney?
Legal escalation generally makes more sense when the balance is significant, the documentation is strong, the debtor appears genuinely collectible, earlier collection attempts have failed, the debt remains within the statute of limitations, and the expected recovery clearly justifies the legal costs involved.
Litigation is often not worthwhile when the balance is very small, the debtor is bankrupt or otherwise judgment-proof, documentation is weak or missing, the statute of limitations has already expired, or the likely legal expenses would exceed what’s realistically recoverable. Recognizing these situations early avoids spending money chasing an outcome that was never realistically available.
Collection Agency vs. Debt Collection Lawyer
These two roles are complementary, not interchangeable, and understanding the difference helps in deciding when to use which one.
A collection agency is generally best suited for high-volume collections, phone, email, and letter outreach, negotiated payment arrangements, skip tracing, credit reporting where permitted, and lower-cost recovery efforts before litigation becomes necessary.
A debt collection lawyer is generally best suited for formal legal demand letters, filing and litigating lawsuits, court appearances, obtaining judgments, and the post-judgment tools, garnishments, bank levies, and judgment liens, along with genuinely complex or heavily disputed accounts.
The strongest recovery model for most creditors uses both, in sequence: agency-based collection first, with attorney escalation reserved for the specific accounts where it’s actually economically justified, rather than treating litigation as an automatic next step for every unresolved balance. See our full guide to the legal collection process and small claims judgment enforcement for more detail on each stage.
What Does a Debt Collection Lawyer Cost?
Debt collection lawyers commonly charge about 25%–50% of the amount recovered on a “no win, no fee” contingency basis, meaning the lawyer earns a fee only if money is collected; however, court costs, filing fees, service-of-process fees, and similar litigation expenses are generally paid separately by the client, not the lawyer. This means anywhere between $100 to $500 in upfront cost (often recoverable if added to the judgment).
Attorney pricing structures vary, and no single number applies universally. Common structures include hourly billing, a flat fee for a defined scope of work, contingency (a percentage of what’s actually recovered), or hybrid arrangements combining elements of these, with court costs typically paid separately from the attorney’s own fee.
What an attorney actually charges tends to depend on the balance involved, the complexity of the case, the state and court where it’s filed, whether the debtor contests the claim, and whether post-judgment enforcement work becomes necessary on top of simply obtaining the judgment. See the full breakdown of collection agency and legal referral fee structures for how this typically fits alongside standard collection pricing.
The lowest attorney fee does not necessarily produce the highest net recovery. A cheaper flat fee that doesn’t include serious post-judgment asset discovery may produce a judgment that’s never actually collected, which is a worse outcome than a somewhat higher fee that includes the work needed to get paid.
Frequently Asked Questions
Can a debt collection lawyer guarantee payment?
No. An attorney can improve legal leverage and enforcement options, but recovery still depends on the validity of the debt and the debtor’s available, non-exempt assets. No legitimate attorney can guarantee a specific recovery outcome.
Is a judgment the same as getting paid?
No, and this is one of the most commonly misunderstood parts of the process. A judgment establishes legal liability, that the debtor genuinely owes the amount stated. Actually collecting that amount may still require garnishment, a bank levy, a judgment lien, a negotiated settlement, or simply voluntary payment once the debtor understands the judgment exists.
Can a debt collection lawyer find a debtor’s bank account?
Sometimes, through lawful post-judgment discovery tools. Depending on state law, this can include subpoenas, formal debtor examinations, public-record searches, and other legally permissible methods for locating financial accounts. This isn’t guaranteed to succeed, and what’s available varies by state.
What happens if the debtor has no assets?
This is generally called being “judgment-proof,” a debtor with no meaningful non-exempt income or property to collect against. In this situation, obtaining a judgment may establish the legal right to payment without producing any actual recovery in the near term, and pursuing litigation in the first place may not have been economically sensible.
How long does a debt collection lawsuit take?
There’s no universal timeline. A default case, where the debtor never responds, can move relatively quickly. A contested case can take months or considerably longer, depending on the specific court’s schedule, how quickly the debtor is served, how much discovery is involved, and whether the parties settle along the way.
Does a collection agency have to sue every debtor who refuses to pay?
No. Litigation should be selective and economically justified, not an automatic response to every unresolved account. Many accounts are better resolved through continued negotiation, a structured payment plan, or, where the numbers don’t support the cost of a lawsuit, a business decision to write the balance off rather than spend more pursuing it.
Whatever stage an account is at, the same principle applies throughout: strong documentation, honest collectibility screening, and nationwide recovery capability matter more than moving to litigation quickly. Nexa’s process is built to resolve accounts at the lowest reasonable cost first, with legal escalation reserved for the accounts where the numbers genuinely support it, and handled with the same reputation-safe approach throughout.